
 Optoelectronic Transducers Market | 2026-2036
Optoelectronic Transducers Market Size, Share, and Industry Trends Forecast 2026-2036
Optoelectronic Transducers Market Outlook
Market Context
Multi-source procurement for III-V semiconductor wafers is broadening as OEMs reduce dependency on single foundries. Hamamatsu Photonics leverages captive crystal-growth facilities to secure gallium arsenide supply chains. Vishay Intertechnology anchors its position through backward integration into epitaxy operations. ON Semiconductor competes by operating dual-source agreements with European and Asian substrate vendors.
Technical Definition and Segments
Optoelectronic transducers convert electromagnetic radiation into electrical signals through photovoltaic, photoconductive, or photoemissive mechanisms, typically operating across ultraviolet to near-infrared wavelengths with responsivity values measured in amperes per watt. These devices serve as the detection layer in lidar modules, pulse oximeters, and fiber-optic communication receivers. Photodiodes command the largest revenue pool due to their ubiquity in consumer camera modules and automotive sensing, while opto-isolators carry superior margins in medical-grade and aerospace applications where isolation voltage ratings exceed five kilovolts. The analog technology segment remains mature in industrial process control, though hybrid architectures are displacing pure analog designs in telecommunications transceivers.
Regulatory Outlook
The FDA's 21 CFR Part 820 quality-system regulation shapes design-control requirements for photodiodes embedded in Class II medical devices, while the EU MDR imposes stricter clinical-evidence thresholds on optoelectronic diagnostic equipment sold in Europe. REACH compliance adds material-selection constraints for manufacturers using lead-based solders in opto-isolator packages. Stakeholders must monitor how the EU AI Act's risk-classification framework will treat optoelectronic sensor arrays deployed in autonomous vehicle perception stacks.
Market Dynamics
The EU Green Deal's energy-efficiency mandates are compressing design cycles for industrial light sensors, forcing OEMs to requalify lower-power photodiode architectures ahead of traditional automotive refresh timelines.
Growth Catalysts
- EU Green Deal mandates:Binding energy-efficiency targets for industrial automation are accelerating replacement of legacy analog sensors with low-power photodiode arrays in German and French manufacturing plants.
- Medical imaging densification:Diagnostic equipment manufacturers are scaling photodiode array purchases for CT and PET scanner upgrades to meet rising hospital throughput requirements.
- III-V wafer supply diversification:Multi-source procurement agreements for gallium arsenide substrates are reducing foundry dependency and stabilizing input costs for high-responsivity detector production.
Market Restraints
- Gallium arsenide price volatility:III-V semiconductor wafer costs fluctuate with rare earth export quotas, squeezing margins for photodiode manufacturers without captive crystal-growth capabilities.
- REACH material constraints:Lead-based solder restrictions in opto-isolator packages are forcing costly redesigns of hermetic sealing architectures for medical-grade devices.
- Silicon photonics substitution:Integrated silicon photodetector arrays in telecom transceivers are capturing share from discrete III-V photodiodes in datacenter interconnect applications.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting photodiode packaging investments to serve domestic medical device and automotive sensor demand.
- EU AI Act risk classification:Optoelectronic sensor arrays in autonomous vehicle perception stacks face emerging compliance frameworks that favor suppliers with pre-certified quality systems.
- Hybrid analog-digital architectures:Convergence of CMOS readout circuits with III-V detection layers is opening design wins in lidar modules for industrial metrology.
Industry Challenges
- Epitaxy engineering talent scarcity:Foundries struggle to hire III-V thin-film deposition specialists capable of maintaining responsivity uniformity across 6-inch wafer formats.
- MDR clinical evidence timelines:EU Medical Device Regulation requirements for optoelectronic diagnostic equipment are extending certification cycles by 18-24 months versus previous directives.
- Dual-source qualification overhead:Maintaining parallel substrate vendor relationships demands redundant epitaxy process validation, consuming engineering bandwidth.
Report Scope
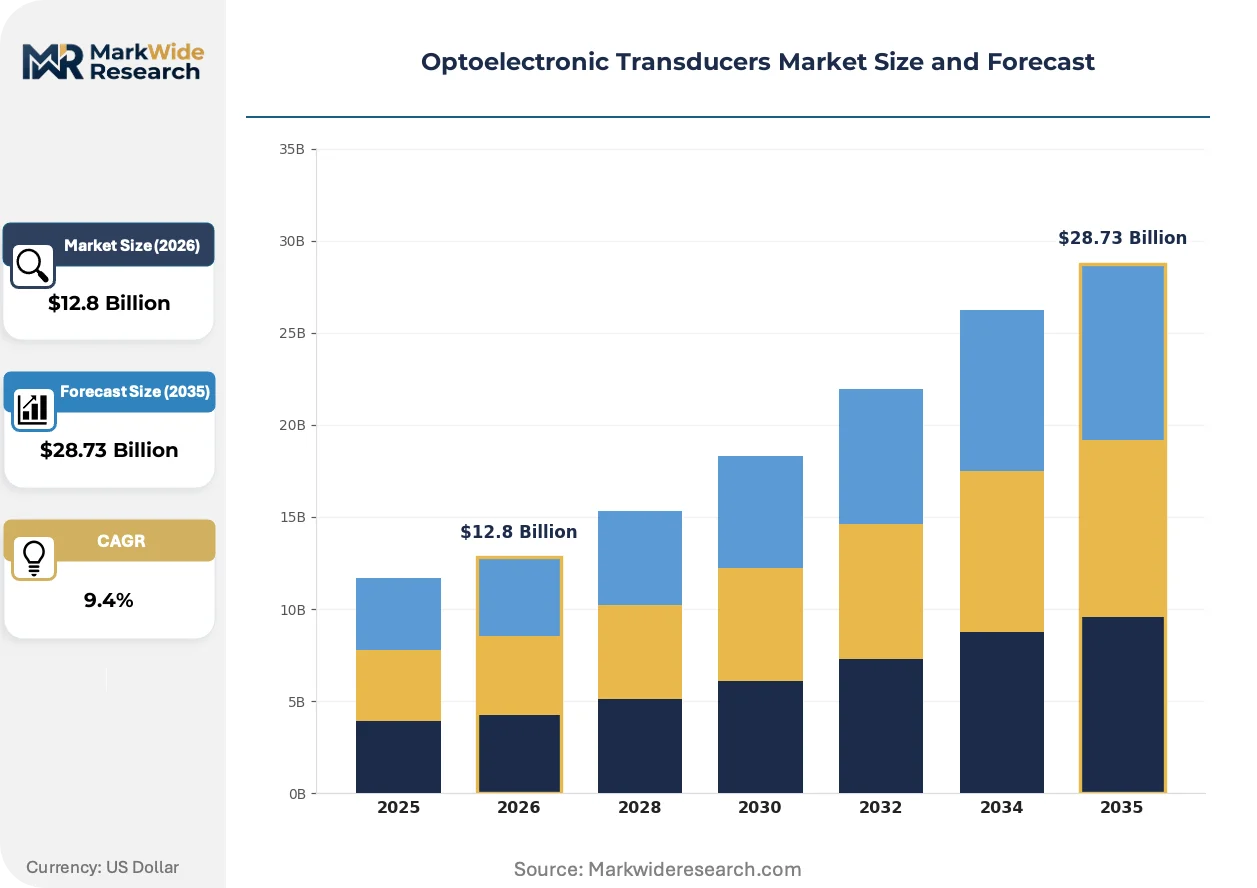
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optoelectronic Transducers Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodiodes, Phototransistors, Light Sensors, Opto-Isolators Application: Industrial Automation, Consumer Electronics, Medical Devices, Communication Systems Technology: Analog, Digital, Hybrid, Wireless End User: Automotive, Aerospace, Telecommunications, Security |
| Companies Covered | Hamamatsu Photonics, Vishay Intertechnology, ON Semiconductor, Sony Corporation, Rohm Semiconductor, Excelitas Technologies, TT Electronics, AMS-OSRAM, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optoelectronic Transducers Market Strategic Shifts
Silicon photonics integration and heterogeneous packaging are collapsing the boundary between detection and signal processing, enabling new form factors that bypass traditional module assembly constraints.
Hybrid CMOS-III-V photodetector arrays are overtaking pure III-V discrete photodiodes in automotive lidar receivers. Tier-1 automotive suppliers are adopting these architectures for 1550-nanometer wavelength systems. The shift is overtaking established supply relationships with discrete component distributors and compressing bill-of-materials complexity.
REACH substance restrictions are tightening material-selection criteria for opto-isolator packages across European industrial markets. Manufacturers are qualifying gold-tin eutectic solders as lead-free alternatives for hermetic sealing. Medical-grade and aerospace applications face the steepest requalification burdens due to isolation voltage ratings exceeding five kilovolts.
Hospital procurement consortia are consolidating photodiode array purchasing for diagnostic imaging equipment through multi-year sole-source agreements. Original equipment manufacturers are responding with dedicated account teams and co-development programs. This concentration is most visible in Germany's university hospital networks and diagnostic imaging clusters around Jena and Munich.
Optoelectronic Transducers Market Segmentation
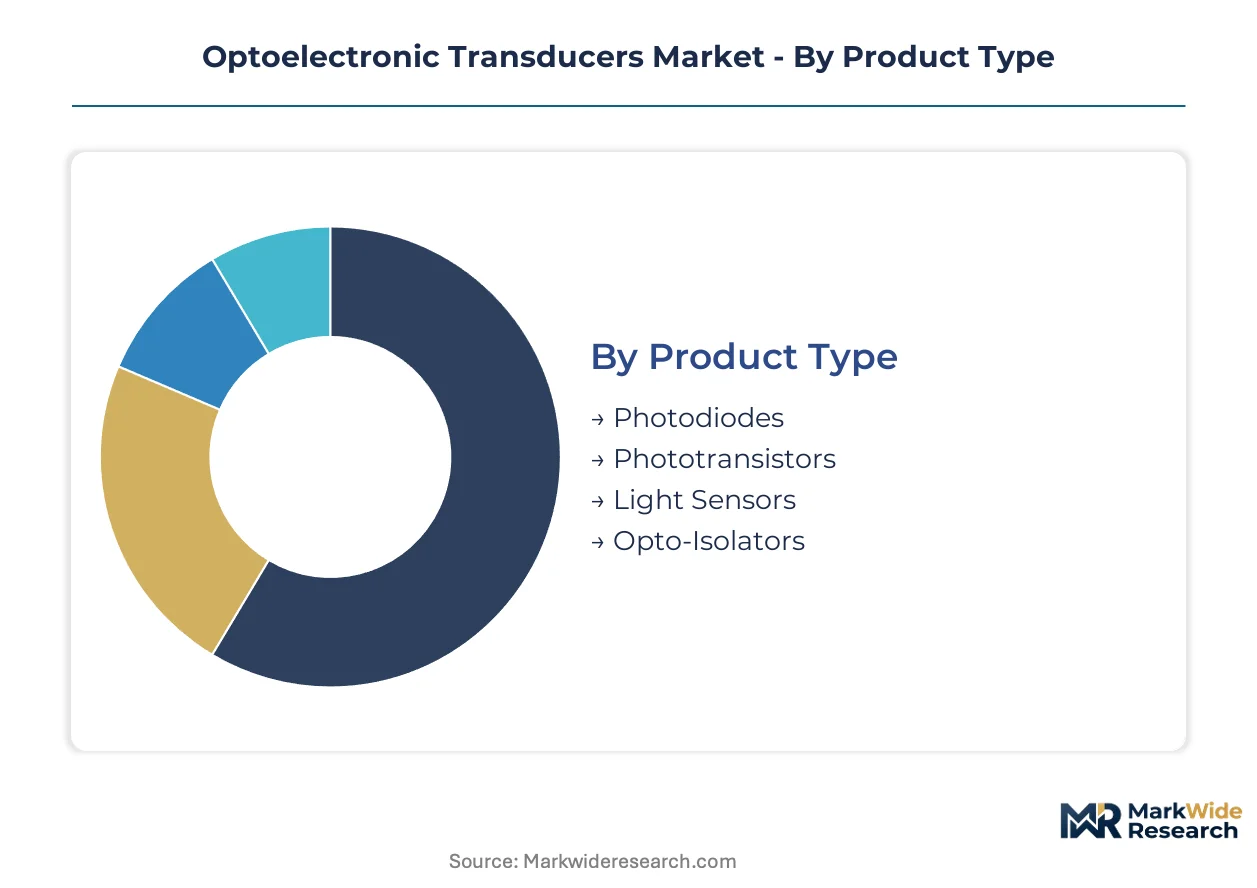
Optoelectronic transducers serve divergent performance requirements across medical imaging, automotive lidar, and industrial automation, making segment-level technology choices critical for procurement strategy. Component selection varies sharply between high-volume consumer applications demanding cost minimization and safety-critical systems where isolation voltage ratings dominate supplier qualification.
Product Type:
Photodiodes command the largest revenue pool through sheer deployment volume, while opto-isolators extract premium margins from aerospace and medical-grade applications where hermetic sealing and isolation specifications exceed five kilovolts.
- Photodiodes:These devices convert incident photons to electrical current through photovoltaic or photoconductive mechanisms, with responsivity calibrated in amperes per watt across ultraviolet to near-infrared wavelengths. Demand concentrates in Germany's precision optics cluster around Jena and Munich, where diagnostic imaging OEMs are scaling array purchases for CT and PET scanner upgrades to meet hospital throughput requirements.
- Opto-Isolators:These components transfer electrical signals between isolated circuits using light as the intermediary medium, achieving galvanic isolation critical for patient safety in Class II medical devices. REACH compliance mandates are forcing costly redesigns of lead-free hermetic sealing architectures, particularly for devices rated above five kilovolts in medical-grade and aerospace applications.
- Phototransistors:These bipolar junction devices amplify photocurrent internally, offering higher sensitivity than standard photodiodes in low-light industrial sensing applications.
- Light Sensors:These integrated modules combine detection elements with signal conditioning circuitry for ambient light measurement in consumer electronics and building automation systems.
Today's leader: Photodiodes. Tomorrow's challenger: Opto-Isolators.
Application:
Medical devices and industrial automation anchor current procurement volumes, while communication systems represent the steepest expansion trajectory as datacenter interconnect demands accelerate.
- Medical Devices:Diagnostic equipment manufacturers embed photodiode arrays in pulse oximeters, CT scanners, and PET imaging systems where signal-to-noise ratio directly impacts diagnostic accuracy. The FDA's 21 CFR Part 820 quality-system regulation and EU MDR clinical-evidence thresholds are extending certification cycles by 18-24 months, favoring suppliers with pre-certified quality systems.
- Industrial Automation:Factory floor deployments leverage photoelectric sensors for position detection, object counting, and safety interlocks under the EU Green Deal's binding energy-efficiency mandates. German and French manufacturing plants are accelerating replacement of legacy analog sensors with low-power photodiode architectures ahead of traditional automotive refresh timelines.
- Consumer Electronics:Smartphone camera modules and wearable health monitors drive high-volume, cost-optimized photodiode consumption with rapid product cycle turnover.
- Communication Systems:Fiber-optic receivers and telecom transceivers deploy high-speed photodetectors, though silicon photonics integration is capturing share from discrete III-V photodiodes in datacenter interconnect applications.
Medical devices retain the margin premium. Industrial automation offers the volume scale.
Technology:
Analog architectures maintain entrenched positions in mature industrial process control, while hybrid designs are displacing pure analog implementations in next-generation telecommunications transceivers.
- Hybrid:Convergence of CMOS readout circuits with III-V detection layers enables new form factors that collapse the boundary between detection and signal processing. Tier-1 automotive suppliers are adopting these architectures for 1550-nanometer lidar receivers, overtaking established supply relationships with discrete component distributors.
- Analog:Pure analog photodetector circuits persist in cost-sensitive industrial applications where signal processing occurs downstream, though design cycles are compressing under energy-efficiency regulatory pressure.
- Digital:Integrated analog-to-digital conversion within sensor packages reduces system complexity for consumer electronics and IoT endpoint devices.
- Wireless:Optical wireless communication links deploy specialized photodetector arrays for free-space data transmission in environments where RF interference or security concerns preclude conventional wireless.
Hybrid architectures are climbing the fastest. Analog retains the installed base.
End User:
Automotive and telecommunications sectors are driving technology roadmaps, while aerospace maintains the most stringent qualification barriers.
- Automotive:Lidar perception stacks for advanced driver-assistance systems deploy photodiode arrays at 905-nanometer and 1550-nanometer wavelengths, with the EU AI Act's emerging risk-classification framework favoring suppliers with pre-certified quality systems for autonomous vehicle deployments.
- Telecommunications:Datacenter interconnect and 5G fronthaul infrastructure consume high-bandwidth photodetectors, though silicon photonics substitution threatens discrete III-V component demand.
- Aerospace:Satellite optical communication terminals and avionics systems demand radiation-hardened photodetectors with extended temperature operating ranges and hermetic packaging.
- Security:Biometric authentication systems and perimeter intrusion detection deploy specialized photodetector configurations for fingerprint imaging and infrared motion sensing.
Automotive commands the technology investment. Aerospace sets the reliability standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting optoelectronic transducer production toward jurisdictions with lower cost-of-compliance gaps, particularly as REACH and EU MDR requirements intensify material-selection and certification burdens in Europe. Manufacturers are qualifying alternative packaging sites while maintaining design and epitaxy operations in established precision-optics clusters.
Germany
Diagnostic imaging OEMs in Jena and Munich are scaling photodiode array purchases for CT and PET scanner upgrades to meet hospital throughput requirements. The EU MDR imposes stricter clinical-evidence thresholds on optoelectronic diagnostic equipment, extending certification cycles. Bavaria's precision optics cluster anchors high-responsivity detector production for medical-grade applications.
United States
FDA's 21 CFR Part 820 quality-system regulation shapes design-control requirements for photodiodes embedded in Class II medical devices, favoring suppliers with pre-certified quality systems. The IRA's domestic manufacturing incentives are attracting photodiode packaging investments. Greater Boston's medical device corridor concentrates pulse oximeter and diagnostic equipment production.
China
MIIT's dual carbon goals are accelerating demand for low-power light sensors in industrial automation, compressing design cycles for photodiode architectures. NMPA regulatory harmonization efforts are streamlining import pathways for high-responsivity detectors. The Yangtze River Delta hosts expanding packaging capacity serving domestic automotive lidar demand.
India
The PLI scheme for electronics manufacturing is attracting photodiode packaging investments to serve domestic medical device and automotive sensor demand. BIS certification requirements are tightening for optoelectronic components in safety-critical applications. Karnataka's electronics manufacturing cluster around Bengaluru is scaling assembly operations for consumer camera modules.
Japan
METI's semiconductor supply-chain resilience initiatives are reinforcing domestic III-V wafer production capabilities for high-responsivity photodetectors. PMDA quality-system requirements align with FDA harmonization frameworks for medical-grade optoelectronics. The Kanto region around Tokyo maintains captive crystal-growth facilities securing gallium arsenide supply chains.
Optoelectronic Transducers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid CMOS-III-V integration architectures. The vendor base stratifies across three maturity levels: integrated device manufacturers with captive epitaxy, fabless designers relying on multi-source foundry agreements, and specialized packaging houses serving medical-grade hermetic sealing requirements. Dominant competitive moves include backward integration into substrate supply and strategic partnerships for lidar module co-development.
Among Japan-based integrated producers, Hamamatsu Photonics exemplifies the captive supply archetype through in-house crystal-growth capabilities. Vishay Intertechnology anchors the precision-component tier with upstream control over epitaxy operations. ON Semiconductor occupies a position within the fabless-designer segment, relying on dual-source substrate agreements to stabilize input costs.
| Leading Market Players |
|---|
| Hamamatsu Photonics |
| Vishay Intertechnology |
| ON Semiconductor |
| Sony Corporation |
| Rohm Semiconductor |
| Excelitas Technologies |
| TT Electronics |
| AMS-OSRAM |
| Teledyne Technologies |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement consortia in Germany are consolidating photodiode array purchasing through multi-year sole-source agreements, forcing suppliers to absorb certification and requalification costs while maintaining price stability across medical-grade and industrial tiers.
Pricing Analysis
III-V semiconductor wafer cost pass-through dominates photodiode pricing structures, with gallium arsenide substrate volatility compressing margins for non-integrated manufacturers. Three-tier pricing structure across medical-grade, automotive-qualified, and industrial-standard levels reflects certification investment and responsivity uniformity requirements. Pricing pressure stems from silicon photonics substitution in datacenter interconnects, eroding discrete component premiums. Consumer electronics buyers exhibit highest price sensitivity, while aerospace and medical device OEMs prioritize isolation voltage ratings and hermetic sealing over unit cost.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific substrate vendors is accelerating regionalization of photodiode packaging operations. Supply concentrates in Japan, Germany, and China, with crystal-growth capabilities anchoring in the Kanto region and epitaxy operations clustering around Jena. Raw material dependencies include gallium arsenide wafers, gold-tin eutectic solders for lead-free hermetic sealing, and specialized ceramic substrates for high-voltage opto-isolators. Single-source vulnerability in 6-inch III-V wafer supply creates exposure to rare earth export quota disruptions. Distribution runs through authorized distributors for industrial automation, direct account teams for medical OEMs, and module integrators for automotive lidar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optoelectronic transducers market functions as a stable compounder, with regulatory mandates for energy efficiency and medical device safety creating durable replacement demand across industrial and healthcare end uses.
For Market Incumbents: Extend captive crystal-growth capabilities to secure gallium arsenide supply chains against rare earth quota volatility. Deepen co-development partnerships with Tier-1 automotive suppliers for hybrid CMOS-III-V lidar receivers, locking out discrete component distributors. Invest in pre-certified quality systems to capture EU AI Act compliance premiums for autonomous vehicle perception stacks.
For New Entrants and Emerging Players: Hybrid analog-digital architectures for industrial metrology offer a technology-first wedge, bypassing entrenched relationships in pure analog process control. Target India's PLI-supported packaging corridor for cost-competitive entry into medical device and automotive sensor supply chains. Pursue qualification partnerships with German university hospital networks to establish reference installations before scaling.
For Investors and Strategic Acquirers: Asymmetric upside sits with fabless designers holding dual-source substrate agreements and proven CMOS-III-V integration roadmaps. The five-to-ten-year viability window favors acquisition targets with existing FDA 21 CFR Part 820 or EU MDR quality system certifications. Monitor REACH substance restriction timelines as an inflection indicator for lead-free hermetic sealing technology premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxy Operations | Vishay Intertechnology's upstream control over III-V thin-film deposition stabilizes input costs against gallium arsenide price volatility. |
| Dual-Source Substrate Agreements | ON Semiconductor's parallel vendor relationships reduce foundry dependency for high-responsivity detector production. |
| Hybrid CMOS-III-V Architecture Development | Tier-1 automotive suppliers adopting converged detection-signal processing for 1550-nanometer lidar receivers collapse bill-of-materials complexity. |
| Lead-Free Hermetic Sealing Qualification | Gold-tin eutectic solder adoption addresses REACH compliance for medical-grade opto-isolators rated above five kilovolts. |
| PLI Scheme Packaging Investment | India's production-linked incentives attract photodiode assembly capacity to serve domestic medical device and automotive demand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with epitaxy engineering directors, medical device procurement managers, automotive Tier-1 supplier quality leads, and industrial automation OEM technical buyers with secondary validation through SEC filings, EU MDR submission databases, and customs trade records for III-V semiconductor wafer flows. Bottom-up segment sizing triangulated against top-down market envelope checks.
Comparable historical periods anchored the projection horizon, with CAGRs derived from segment-level demand elasticity modeling across photodiode, opto-isolator, and hybrid architecture product categories, end-use applications spanning medical imaging and industrial automation, and technology tiers distinguishing analog from hybrid implementations. Forecast inputs included hospital capital expenditure cycles for diagnostic equipment, automotive lidar content-per-vehicle trajectories, and EU Green Deal implementation timelines for energy-efficiency mandates.
The model holds under stable rare earth export policies and sustained REACH enforcement; deviation in III-V wafer supply disruptions or accelerated silicon photonics substitution would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
Laser Projection Market
Optoelectronics
3D Projector Market
Optoelectronics
Laser Projector Market