
 Global Chip on Board (COB) Light Emitting Diode Market | 2026-2036
Global Chip on Board (COB) Light Emitting Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chip on Board (COB) Light Emitting Diode Market Analysis
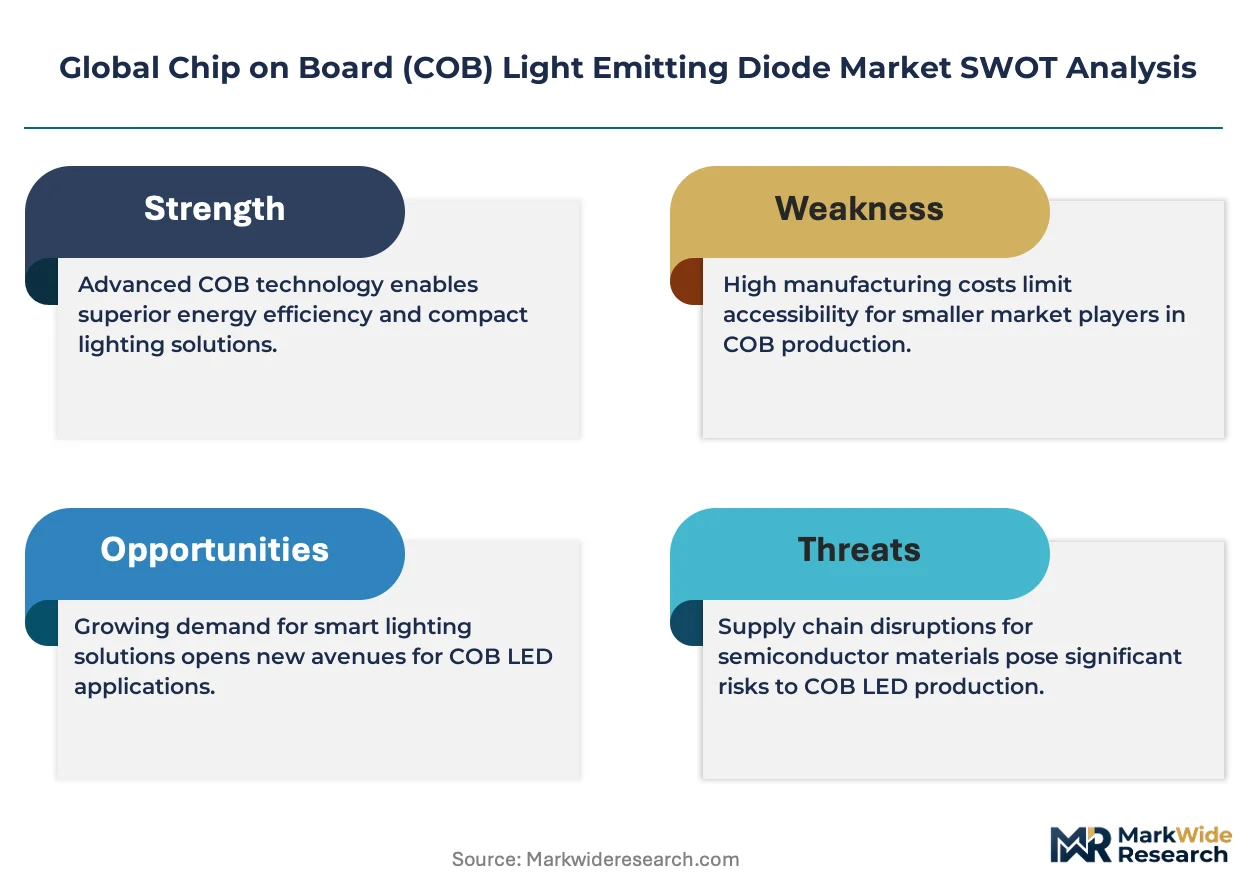
A capital-intensity divergence between bare-die bonding capability and phosphor deposition scale is bifurcating the competitive landscape. ams OSRAM AG leverages its integrated sapphire substrate and LED die operations to control cost structures across high-power segments. CITIZEN ELECTRONICS CO., LTD anchors its position through precision ceramic substrate expertise that sustains thermal performance in automotive qualification cycles. Seoul Semiconductor Co., Ltd. differentiates via proprietary WICOP technology that eliminates wire bonds, reducing failure modes in mid-power general lighting deployments.
Chip on Board (COB) Light Emitting Diode refers to a packaging architecture where unpackaged LED dies are mounted directly onto a substrate—typically ceramic or metal-core PCB—and encapsulated with a phosphor-doped silicone layer, achieving luminous efficacies exceeding 150 lm/W in premium configurations. This construction eliminates individual LED packages, enabling higher lumen density per unit area and simplified thermal paths for directional luminaires. High-Power LEDs command the dominant revenue share due to penetration in commercial downlighting and track applications where thermal management constraints favor COB form factors. Mid-Power LEDs represent the fastest-expanding category as cost-optimized designs penetrate residential retrofit markets, while Multi-Color LEDs concentrate margin pools in entertainment and architectural tunable-white systems. Display Lighting applications lag in COB adoption because edge-lit and mini-LED alternatives dominate thin-form backlighting, constraining addressable volume in that segment.
EU Ecodesign regulations and REACH phosphor substance restrictions are tightening material compliance requirements for silicone encapsulants and rare-earth dopants, elevating formulation costs for non-compliant suppliers. China's GB standards for solid-state lighting efficiency and the US DOE Lighting Facts program create divergent certification burdens that fragment go-to-market strategies across major demand centers. Stakeholders must monitor regulatory harmonization pressures between efficiency mandates and circular-economy material rules that could reshape substrate material choices and phosphor recovery economics.
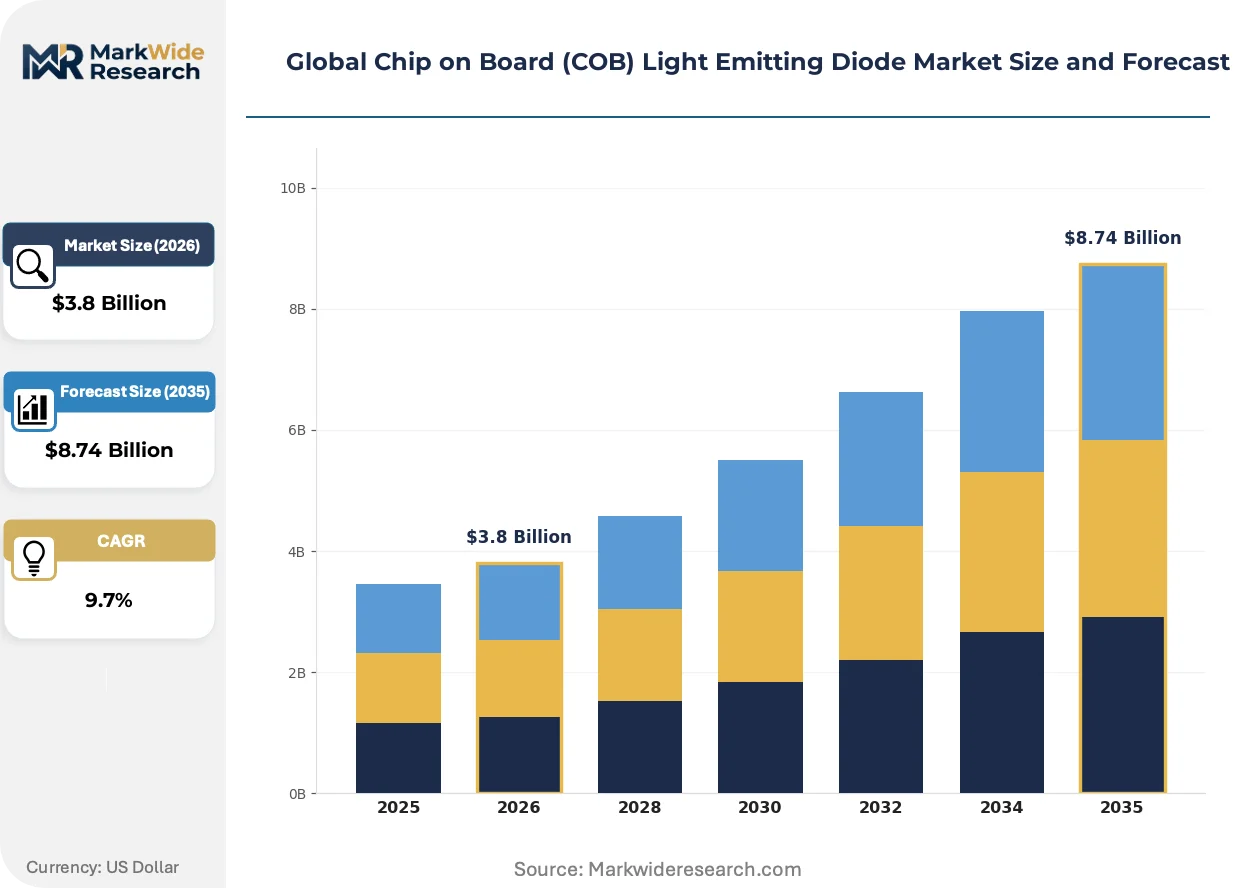
Market Dynamics
Capital-intensity divergence between bare-die bonding capability and phosphor deposition scale is bifurcating the competitive landscape, forcing mid-tier suppliers to specialize or exit as integrated players capture margin pools.
Growth Catalysts
- EU Ecodesign efficiency mandates:Tightening lumen-per-watt thresholds for commercial luminaires accelerate retrofit demand for high-density COB modules in office and retail installations.
- China's dual carbon goals:National efficiency targets under MIIT direction drive municipal procurement toward solid-state lighting with verified thermal performance metrics.
- Phosphor-on-chip deposition advances:Improved silicone encapsulant uniformity reduces color-binning waste, lowering effective cost per kilolumen for mid-power general lighting deployments.
Market Restraints
- Rare-earth phosphor supply concentration:Dysprosium and europium sourcing dependence on Chinese refining operations creates input cost volatility and qualification timeline risk.
- REACH substance restrictions:ECHA regulatory friction limits cadmium-based quantum dot alternatives, constraining premium multi-color LED formulation pathways.
- Mini-LED edge-lit substitution:Thin-form display backlighting applications favor distributed die architectures over COB thermal profiles, capping addressable volume in that segment.
Strategic Opportunities
- India BIS efficiency certification:Mandatory star-rating expansion for commercial lighting creates first-mover advantage for suppliers with pre-tested thermal management documentation.
- Human-centric circadian lighting:Tunable-white COB systems penetrate healthcare and education verticals where melanopic lux specifications drive specification premiums.
- Automotive qualification pipelines:AEC-Q102-compliant ceramic substrate expertise transfers from headlamp modules to interior ambient lighting as OEMs consolidate vendor bases.
Industry Challenges
- Phosphor deposition technician scarcity:Precision silicone dispensing and curing optimization require specialized process engineering talent concentrated in East Asian manufacturing clusters.
- Divergent certification timelines:GB standards, EU Ecodesign, and US DOE Lighting Facts create fragmented test-and-approval burdens that delay product launches across major demand centers.
- Wire-bond elimination IP complexity:Proprietary interconnect architectures trigger licensing disputes that complicate technology sourcing decisions for second-tier assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chip on Board (COB) Light Emitting Diode Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power LEDs, Mid-Power LEDs, Low-Power LEDs, Multi-Color LEDs Application: General Lighting, Automotive Lighting, Backlighting, Display Lighting End User: Residential, Commercial, Industrial, Entertainment Technology: Thermal Management, Color Mixing, Dimming, Integration |
| Companies Covered | ams OSRAM AG, CITIZEN ELECTRONICS CO., LTD, Wolfspeed, Inc., EVERLIGHT ELECTRONICS CO., LTD., Philips Lumileds, Nichia Corporation, Seoul Semiconductor Co., Ltd., Samsung Electronics Co., Ltd., Lumileds Holding B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chip on Board (COB) Light Emitting Diode Market Emerging Trajectories
Thermal management architectures and deposition precision are converging to redefine performance benchmarks across power classes. Three developments dominate strategic planning.
Wafer-level phosphor conversion is miniaturizing emission surface areas while maintaining lumen output, enabling tighter beam control in directional luminaires. High-end retail and museum lighting specifiers adopt these compact emitters for accent applications. The technology is miniaturizing optical system footprints, reducing fixture depth requirements and expanding retrofit compatibility in ceiling-restricted installations.
REACH phosphor substance restrictions are tightening silicone encapsulant formulation requirements across European supply chains. ECHA compliance timelines force reformulation investments that elevate non-compliant supplier exit costs. Multi-color entertainment lighting segments absorb disproportionate impact as rare-earth dopant alternatives face extended qualification cycles.
Facilities managers now specify lumen-maintenance guarantees over operational lifespan rather than upfront efficacy metrics. Commercial retrofit procurement contracts increasingly bundle installation with performance-based maintenance obligations. This contracting evolution concentrates most visibly in German and Dutch municipal lighting tenders where total-cost-of-ownership documentation determines award outcomes.
Global Chip on Board (COB) Light Emitting Diode Market Segmentation
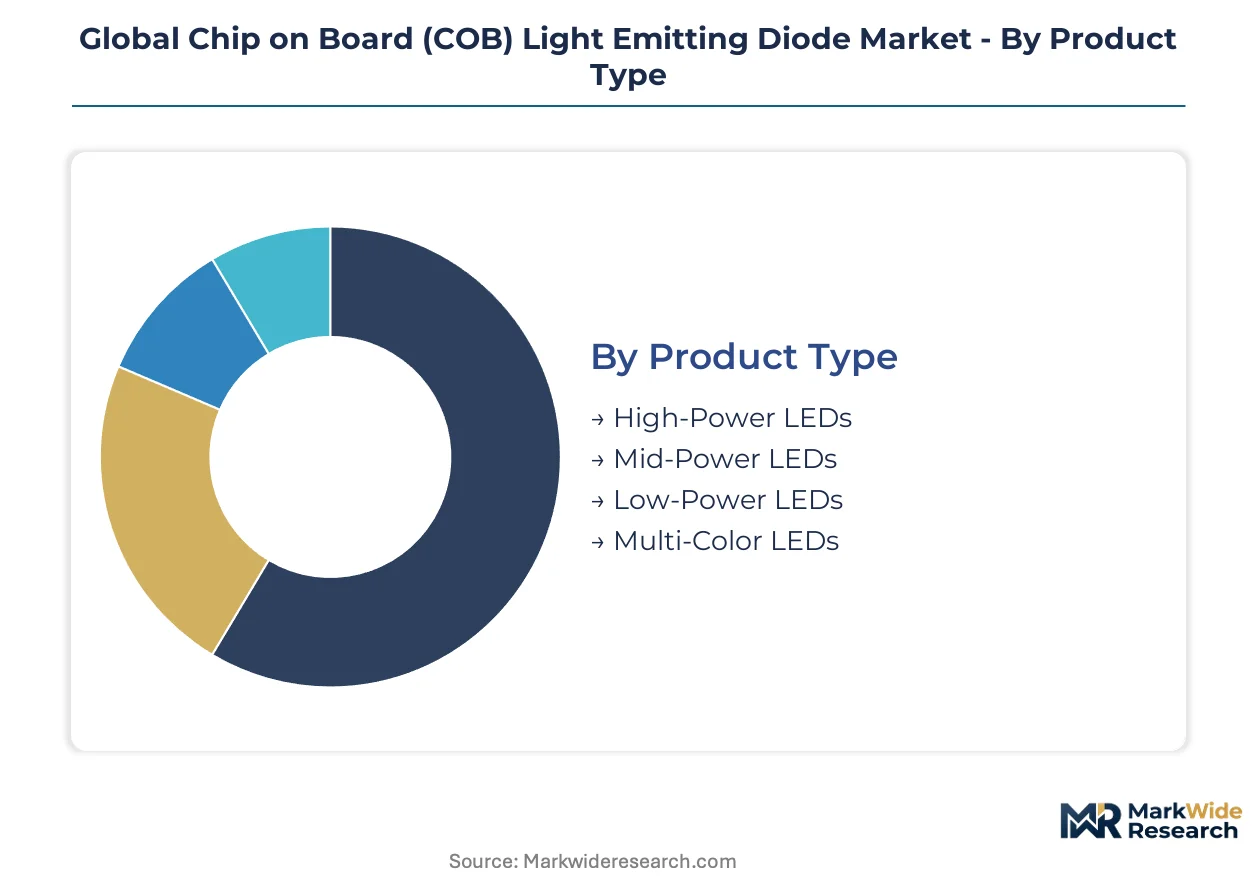
COB LED segmentation reveals how power-class specialization and application-specific thermal requirements create distinct procurement channels. Each dimension exposes different margin structures and certification burdens that suppliers must navigate across fragmented demand centers.
Product Type:
High-Power and Mid-Power variants dominate export flows to retrofit-heavy markets, while Multi-Color concentrates in domestic entertainment clusters with shorter qualification cycles.
- High-Power LEDs:Unpackaged dies bonded directly to ceramic or metal-core substrates achieve luminous efficacies exceeding 150 lm/W with simplified thermal paths. Demand concentrates in German and Dutch municipal tenders where total-cost-of-ownership documentation determines award outcomes for commercial downlighting and track applications.
- Mid-Power LEDs:Cost-optimized designs eliminate wire bonds through proprietary interconnect architectures, reducing failure modes in volume deployments. Residential retrofit markets across India and Southeast Asia absorb the steepest volume expansion as BIS efficiency certification mandates accelerate replacement cycles.
- Low-Power LEDs:Compact form factors serve indicator and accent applications with minimal thermal overhead requirements.
- Multi-Color LEDs:Tunable-white systems penetrate healthcare and education verticals where melanopic lux specifications command specification premiums.
High-Power LEDs command the established base. The steepest expansion runs through Mid-Power LEDs.
Application:
Margin concentration varies sharply by thermal complexity, with automotive and general lighting rewarding qualification depth while display applications face substitution pressure.
- General Lighting:Commercial and residential retrofit demand drives volume, with facilities managers prioritizing lumen density and thermal efficiency in ceiling-restricted installations. EU Ecodesign tightening lumen-per-watt thresholds accelerates module replacement in office and retail environments.
- Automotive Lighting:AEC-Q102-compliant ceramic substrate expertise transfers from headlamp modules to interior ambient lighting as OEMs consolidate vendor bases. Seoul and Stuttgart manufacturing clusters anchor qualification pipelines for thermal-cycling endurance.
- Backlighting:Edge-lit alternatives constrain COB penetration in thin-form television and monitor applications.
- Display Lighting:Mini-LED distributed die architectures displace COB thermal profiles in premium screen backlighting, capping addressable volume.
General Lighting generates the revenue foundation. Automotive Lighting delivers the margin expansion.
End User:
Procurement sophistication divides segments, with commercial and industrial buyers demanding performance guarantees while residential and entertainment prioritize upfront cost.
- Commercial:Facilities managers specify lumen-maintenance guarantees over operational lifespan rather than upfront efficacy metrics. German municipal lighting tenders bundle installation with performance-based maintenance obligations.
- Industrial:High-bay and hazardous-location applications require explosion-rated enclosures that elevate thermal management complexity.
- Residential:Cost-optimized mid-power designs penetrate retrofit markets through distributor channels with minimal specification friction.
- Entertainment:Tunable-white and multi-color systems serve stage and architectural applications where color-binning precision commands premium pricing.
Commercial end users anchor contract value. Residential channels scale volume fastest.
Technology:
Process capability differentiation separates integrated players from assemblers, with thermal and color-mixing expertise commanding the widest moats.
- Thermal Management:Substrate material choices and phosphor deposition precision determine lumen maintenance over operational lifespan. Guangdong Province manufacturing clusters concentrate technician expertise for silicone encapsulant curing optimization.
- Color Mixing:Phosphor-on-chip deposition advances reduce color-binning waste, lowering effective cost per kilolumen for multi-color entertainment deployments.
- Dimming:Driver compatibility and flicker-free performance specifications differentiate premium from standard tiers in healthcare and education verticals.
- Integration:Wafer-level phosphor conversion miniaturizes emission surface areas while maintaining lumen output, enabling tighter beam control in directional luminaires.
Thermal Management underpins competitive position. Color Mixing unlocks premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows reveal divergent regional specialization patterns. East Asian manufacturing clusters dominate module assembly and bare-die sourcing, while European and North American markets absorb premium high-power configurations for commercial retrofit applications.
China
Guangdong Province anchors substrate fabrication and phosphor deposition capacity serving global luminaire assemblers. MIIT-directed dual carbon goals accelerate municipal procurement of solid-state lighting with verified thermal performance metrics. Shenzhen and Dongguan manufacturing clusters concentrate technician expertise for silicone encapsulant curing optimization.
Germany
Commercial facilities managers specify lumen-maintenance guarantees over operational lifespan in retrofit tenders. EU Ecodesign tightening lumen-per-watt thresholds drives module replacement in office and retail environments. Stuttgart manufacturing clusters anchor AEC-Q102 qualification pipelines for automotive interior ambient lighting.
United States
Healthcare and education verticals adopt tunable-white COB systems where melanopic lux specifications command specification premiums. US DOE Lighting Facts program creates certification documentation burdens that delay product launches. Pacific Northwest distributor channels scale residential retrofit volume for cost-optimized mid-power designs.
South Korea
Seoul metropolitan area co-locates substrate sourcing and phosphor deposition expertise for directional luminaire manufacturers. Proprietary wire-bond elimination architectures reduce failure modes in mid-power general lighting deployments. Busan-Ulsan manufacturing corridors transfer ceramic substrate expertise from headlamp modules to interior automotive applications.
India
BIS efficiency certification mandates accelerate replacement cycles across residential retrofit markets. Mandatory star-rating expansion for commercial lighting creates first-mover advantage for suppliers with pre-tested thermal management documentation. Maharashtra and Gujarat distribution channels absorb steepest volume expansion for cost-optimized designs.
Global Chip on Board (COB) Light Emitting Diode Market Vendor Landscape
Concentration sits with integrated sapphire substrate operators and precision ceramic substrate specialists. The vendor base separates into three strategic tiers: bare-die bonding capability holders, phosphor deposition scale players, and regional assemblers without upstream control. Dominant competitive moves include backward integration into substrate sourcing and technology licensing arrangements for wire-bond elimination architectures.
Within the integrated substrate tier, ams OSRAM AG and CITIZEN ELECTRONICS CO., LTD exemplify divergent specialization paths. Seoul Semiconductor Co., Ltd. occupies a distinctive position through proprietary interconnect technology. These three anchors represent how thermal management expertise and phosphor deposition precision separate margin capture from commodity assembly.
| Leading Market Players |
|---|
| ams OSRAM AG |
| CITIZEN ELECTRONICS CO., LTD |
| Wolfspeed, Inc. |
| EVERLIGHT ELECTRONICS CO., LTD. |
| Philips Lumileds |
| Nichia Corporation |
| Seoul Semiconductor Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Lumileds Holding B.V. |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign efficiency mandates and REACH phosphor substance restrictions simultaneously gate supplier qualification and stratify price tiers, forcing non-compliant assemblers toward economy positioning while certified operators capture premium-mid-economy pricing differentiation through verified thermal performance documentation.
Pricing Analysis
Configured-to-order pricing for AEC-Q102-compliant automotive modules commands spreads exceeding standard commercial lighting SKUs by margins tied to ceramic substrate qualification depth. Pricing stratifies across premium certified tiers, standard BIS-verified residential retrofit lines, and economy unbranded export batches. Cost compression in mid-power residential channels intensifies as Guangdong assemblers compete on phosphor deposition scale. Facilities managers in German municipal tenders exhibit lowest price sensitivity due to total-cost-of-contracting procurement models.
Supply Chain Analysis
Rare-earth phosphor refining concentration in Chinese Jiangxi and Inner Mongolia operations creates single-source vulnerability for europium and dysprosium dopants essential to high-CRI formulations. Bare-die sourcing draws from Taiwan and South Korea foundries, while ceramic substrate fabrication anchors in Japan and Germany. Distribution runs through Shenzhen and Dongguan export corridors toward European luminaire OEMs and Indian distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based maintenance contracting bundles now expand faster than hardware unit sales, creating recurring revenue layers that outpace lumen-per-watt specification premiums in German and Dutch commercial retrofit markets.
For Market Incumbents: Shield margin pools by deepening backward integration into sapphire substrate operations and phosphor deposition capacity in Guangdong manufacturing clusters. Wire-bond elimination IP licensing disputes threaten technology sourcing flexibility for second-tier assemblers. Certification investment in India's BIS star-rating fast-tracks defends position against emerging domestic competitors. For New Entrants and Emerging Players: India's BIS efficiency certification fast-track offers lowest barrier to volume deployment for cost-optimized mid-power designs. Residential retrofit channels in Maharashtra and Gujarat absorb steepest expansion with minimal specification friction. Circadian lighting specification in US healthcare and education verticals provides white-space entry with melanopic lux performance guarantees as the go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision ceramic substrate specialists holding AEC-Q102 qualification pipelines. Long-term viability hinges on thermal management expertise transferability from automotive to general lighting applications. Watch for phosphor deposition technician scarcity inflections in Seoul and Guangdong clusters as supply-constraint signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sapphire Substrate Operations | Captures cost control across high-power segments where ams OSRAM and CITIZEN ELECTRONICS anchor competitive position. |
| Phosphor Deposition Scale Expansion | Reduces color-binning waste and lowers effective cost per kilolumen for mid-power general lighting deployments. |
| AEC-Q102 Certification Pipeline Investment | Transfers ceramic substrate expertise from headlamp modules to interior automotive ambient lighting consolidation. |
| Performance-Based Maintenance Contracting | Bundles installation with lumen-maintenance guarantees that determine award outcomes in German municipal tenders. |
| Wire-Bond Elimination Technology Licensing | Proprietary interconnect architectures reduce failure modes but trigger IP disputes complicating second-tier assembler sourcing. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, MIIT efficiency standard filings, EU Ecodesign regulatory documentation, and SEC 10-K disclosures from listed LED component suppliers. Interviews with facilities managers at German commercial retrofit contractors, phosphor deposition technicians in Guangdong manufacturing clusters, and procurement leads at Indian BIS certification laboratories informed demand-side validation. Bottom-up module shipment analysis triangulates against top-down luminaire production estimates.
Segmentation dimensions modeled span power class, application vertical, end-user procurement sophistication, and thermal management technology across the projection horizon. CAGRs derive from fitted growth curves applied to verified installation base data and replacement cycle assumptions. Phosphor deposition yield improvements and REACH reformulation cost impacts feed directly into cost-per-kilolumen trajectory modeling.
Underlying assumptions cover EU Ecodesign enforcement continuity and rare-earth phosphor supply stability, with deviation risk concentrated in REACH substance restriction timeline acceleration and China dual carbon policy implementation intensity. Practitioners should keep alternative scenarios live as regulatory harmonization pressures between efficiency mandates and circular-economy material rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Downlight Market
LED
Global Chip Scale Package (CSP) LED Market
LED
Europe Outdoor LED Lighting Market
LED
Gan Micro LED Market
LED
East Africa LED Lighting Market
LED
Philippines LED Market
LED
Infrared (IR) LED Market
LED
France LED Lighting Market
LED
Bi-Color LED Ring Light Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
LED Encapsulation Market
LED
Global Waterproof LED Module Market
LED
Chip on Board LED Market
LED
LED and OLED Display Market
LED
France Outdoor LED Lighting Market
LED
US and Europe LED Lighting Market