
 Semiconductor Target Market | 2026-2036
Semiconductor Target Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Target Market Insights
Tungsten is rebalancing cost structures across semiconductor target supply chains as fabs substitute it for gold in certain interconnect layers. TSMC leverages captive refining partnerships to secure five-nines purity tungsten for its Arizona and Kaohsiung fabs. Samsung Electronics anchors gallium nitride target procurement through long-term offtake agreements with Korean smelters. Intel differentiates via vertical integration into target recycling, reclaiming spent materials at its Rio Rancho facility.
Semiconductor targets are high-purity metal or compound discs—typically 99.99% to 99.9999% pure—bombarded by ions in physical vapor deposition chambers to create atomic-thin films on wafer surfaces. These sputtering targets range from 2 to 18 inches in diameter and operate at chamber pressures below 10 millitorr, serving as the foundational step in building transistor gates, interconnects, and barrier layers. Power Semiconductors command the dominant share of target consumption due to thicker deposition requirements in high-voltage devices, while Gallium Nitride targets represent the fastest-expanding technology segment as RF and power applications multiply. Integrated Circuits remain the most mature application, with margin pools shifting toward Silicon Carbide targets where supply scarcity sustains premium pricing.
EPA hazardous waste rules govern spent target disposal in the United States, pushing fabs toward closed-loop reclamation. REACH registration requirements in Europe restrict certain alloying elements, redirecting formulation R&D toward compliant alternatives. China's GB standards and MEE emissions rules tighten domestic target manufacturing permits, favoring scale players with environmental compliance infrastructure. Stakeholders must monitor how export licensing for high-purity tantalum and cobalt evolves, as these materials face escalating supply security reviews across multiple jurisdictions.
Market Dynamics
The migration from silicon to silicon carbide power modules is restructuring raw material demand across the semiconductor target supply chain. This substrate transition concentrates procurement power among automotive power module manufacturers while stretching the five-nines purity refining capacity that advanced node foundries require.
Growth Catalysts
- Electric vehicle power modules:Automakers expanding silicon carbide inverter production are consuming thicker sputtering targets than conventional integrated circuits. Deposition chambers for 800V architectures run longer cycles, accelerating target replacement rates.
- REACH material traceability:The European framework mandates documented supply chain provenance for tantalum and cobalt inputs. Compliant suppliers capture preferential placement in automotive qualification programs.
- China's dual carbon goals:Domestic refining capacity expansion for high-purity tungsten and molybdenum targets reduces import dependency. State-backed smelters achieve six-nines purity for domestic foundry supply.
Market Restraints
- Tantalum ore concentration:Over 60% of tantalum feedstock originates from central African artisanal mining operations. Conflict mineral certification delays extend raw material qualification timelines by 8-14 months.
- Five-nines purity bottleneck:Electron beam melting capacity for ultra-high-purity tungsten concentrates in three Japanese and German metallurgical facilities. New entrant qualification requires 18-24 months of foundry validation.
- Platinum group metal substitution:Ruthenium capping layers in copper interconnects face displacement by cobalt-based alternatives. Memory manufacturers accelerate cobalt target trials to reduce noble metal exposure.
Strategic Opportunities
- Spent target reclamation:Closed-loop refining services capture 85-92% of residual metal value from consumed sputtering targets. Arizona and New Mexico facilities position for US-based circular supply chains serving domestic fabs.
- Gallium nitride RF expansion:5G base station deployments and military radar programs multiply GaN-on-SiC epitaxy demand. Target suppliers with ceramic bonding expertise access premium thermal management specifications.
- India's semiconductor PLI scheme:Domestic display and logic fab construction creates captive target manufacturing incentives. Joint ventures between Korean metallurgists and Indian industrial groups secure local supply commitments.
Industry Challenges
- Plasma spray coating expertise:Rotatable target manufacturing requires thermal spray technicians with ceramic-metal interface optimization skills. Workforce development lags behind gallium nitride target capacity expansion.
- Multi-jurisdictional export licensing:High-purity cobalt and tantalum shipments face divergent national security review protocols. Compliance teams must navigate simultaneous US, EU, and Chinese licensing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Target Market |
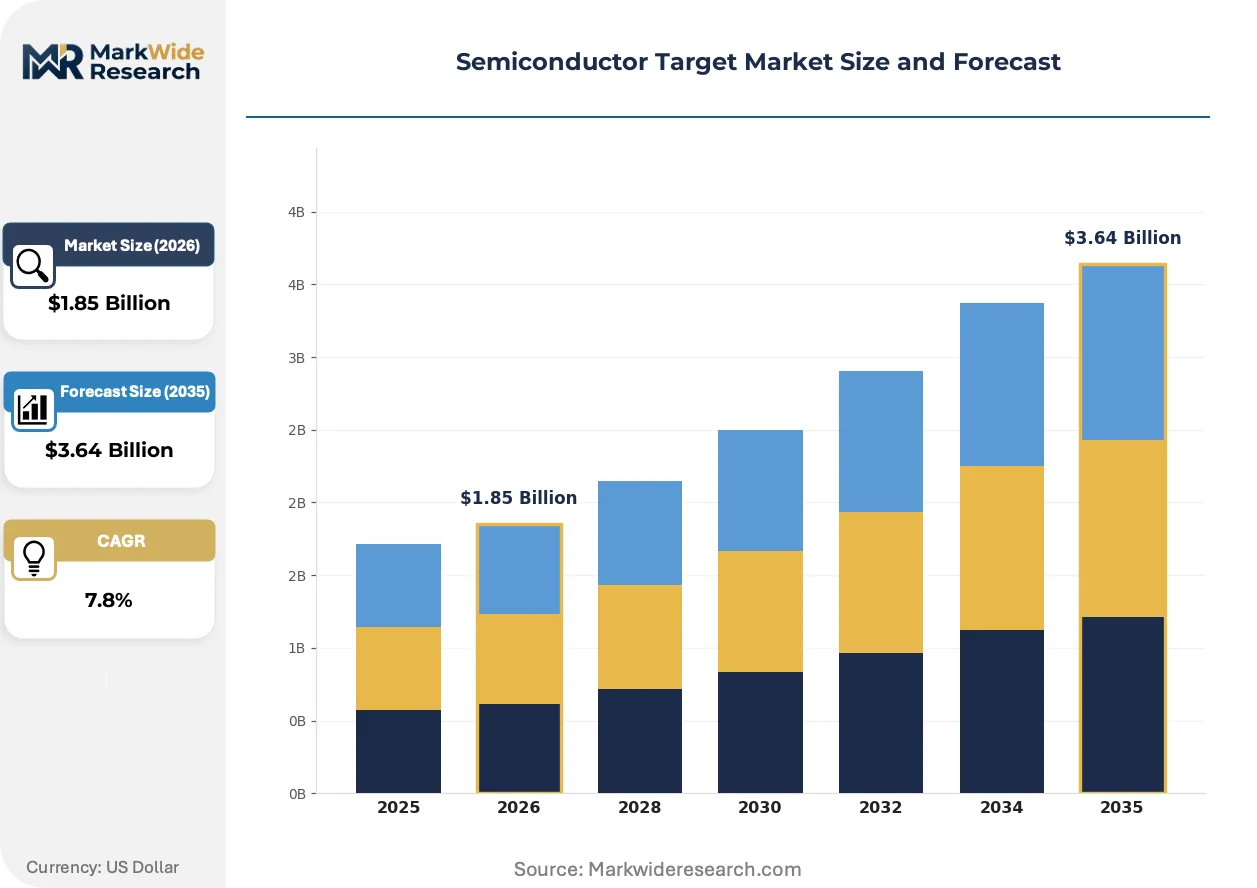
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Semiconductors, Discrete Devices, Integrated Circuits, Optoelectronics Technology: Silicon, Gallium Nitride, Silicon Carbide, CMOS End User: Consumer Electronics, Telecommunications, Automotive Industry, Industrial Applications Application: Data Processing, Signal Processing, Power Management, RF Communication |
| Companies Covered | TSMC, Samsung Electronics, Intel, Nvidia, Broadcom, SK Hynix, Micron, Qualcomm, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Target Market Trends and Innovations
Atomic layer deposition compatibility requirements are forcing target manufacturers to tighten grain structure control beyond traditional physical vapor deposition specifications. This precision shift favors metallurgical houses with in-house forging and heat treatment capabilities.
Machine learning-driven grain orientation mapping is automating quality assurance workflows for large-diameter tungsten targets. Foundries in Taiwan and Arizona deploy real-time crystallographic analysis to predict sputtering uniformity across 300mm wafer batches. This predictive capability compresses target qualification cycles from six months to ten weeks while reducing chamber downtime from misaligned grain structures.
EPA hazardous waste classification updates are tightening spent target handling requirements for US-based fabs. The revised rules mandate manifest tracking for nickel-vanadium and titanium-tungsten residues previously exempt from cradle-to-grave documentation. Intel and Texas Instruments are expanding on-site reclamation capacity to avoid third-party disposal liabilities and recover gallium and indium values.
Long-term offtake contracting is displacing spot procurement for silicon carbide and gallium nitride target materials. Power semiconductor manufacturers lock in five-year supply agreements with Korean and Japanese smelters to secure capacity ahead of automotive qualification ramps. This contractual shift concentrates volume commitments among top-tier foundries while squeezing mid-tier buyers into secondary supply channels.
Semiconductor Target Market Segmentation
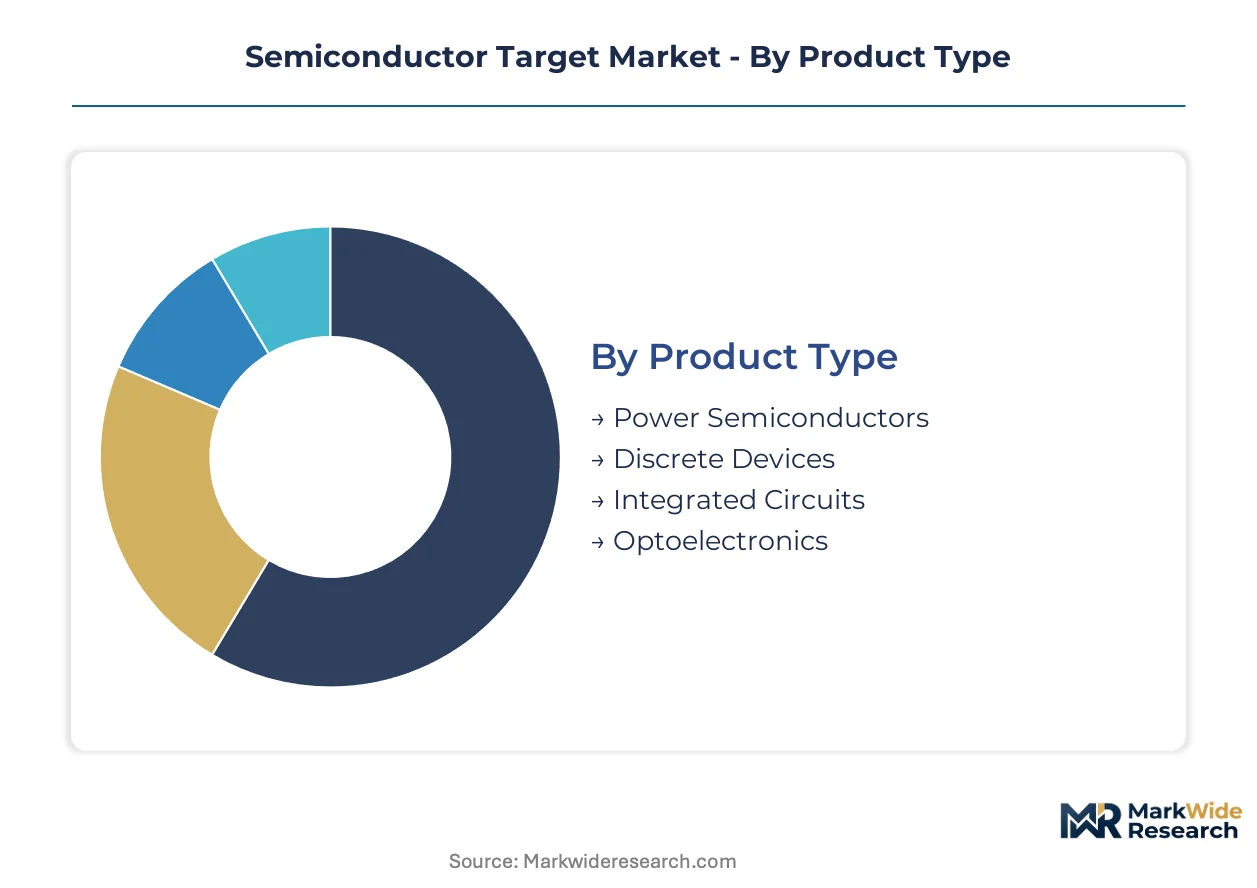
Semiconductor target procurement patterns diverge sharply across device architectures and purity requirements. Sputtering material specifications cascade differently through power modules versus logic chips, creating distinct metallurgical demand clusters.
Product Type:
Deposition thickness requirements separate buyers into divergent material consumption profiles.
- Power Semiconductors:Thick-film sputtering for high-voltage substrates consumes targets at 3-4x the rate of logic devices. Automotive inverter production in Germany and Japan drives tungsten and molybdenum procurement volumes.
- Integrated Circuits:Atomic-layer precision demands six-nines purity copper and ruthenium for sub-3nm interconnects. Taiwan foundries anchor qualification timelines for advanced node target suppliers.
- Discrete Devices:Diode and transistor manufacturing favors cost-optimized aluminum and titanium compositions.
- Optoelectronics:LED and laser fabrication requires indium-tin-oxide and gallium arsenide targets with strict compositional uniformity.
Power Semiconductors lead volumes today; Integrated Circuits command the steepest purity premiums.
Technology:
Substrate material transitions are restructuring elemental demand across the supply chain.
- Silicon Carbide:800V EV architectures require thicker tantalum and niobium barrier layers during epitaxy. Wolfspeed and STMicroelectronics expansion in Italy and Singapore concentrates target procurement power.
- Gallium Nitride:RF power amplifiers and fast chargers drive indium-gallium-zinc-oxide target adoption. Military radar programs in the United States and South Korea lock in multi-year gallium supply agreements.
- Silicon:Mature node production sustains baseline demand for aluminum-silicon and titanium-tungsten compositions.
- CMOS:Image sensor manufacturing consumes specialized cobalt and nickel-platinum targets for pixel isolation layers.
Silicon retains the largest installed base; Silicon Carbide is climbing the fastest amid automotive electrification.
End User:
Industry-specific reliability standards dictate target purity tiers and qualification protocols.
- Automotive Industry:AEC-Q100 stress testing mandates documented supply chain provenance for tantalum and cobalt inputs. Tier-1 module suppliers in Germany enforce 18-month qualification cycles.
- Telecommunications:5G base station deployments multiply gallium nitride target consumption for macro-cell power amplifiers. Ericsson and Nokia procurement in Finland and Sweden favors European-sourced refining.
- Consumer Electronics:Smartphone and wearable manufacturing prioritizes cost-optimized aluminum and copper targets with four-nines purity.
- Industrial Applications:Motor drive and renewable energy inverters sustain steady demand for silicon-based power device targets.
Consumer Electronics anchors current volumes; Automotive Industry is expanding most quickly on EV penetration.
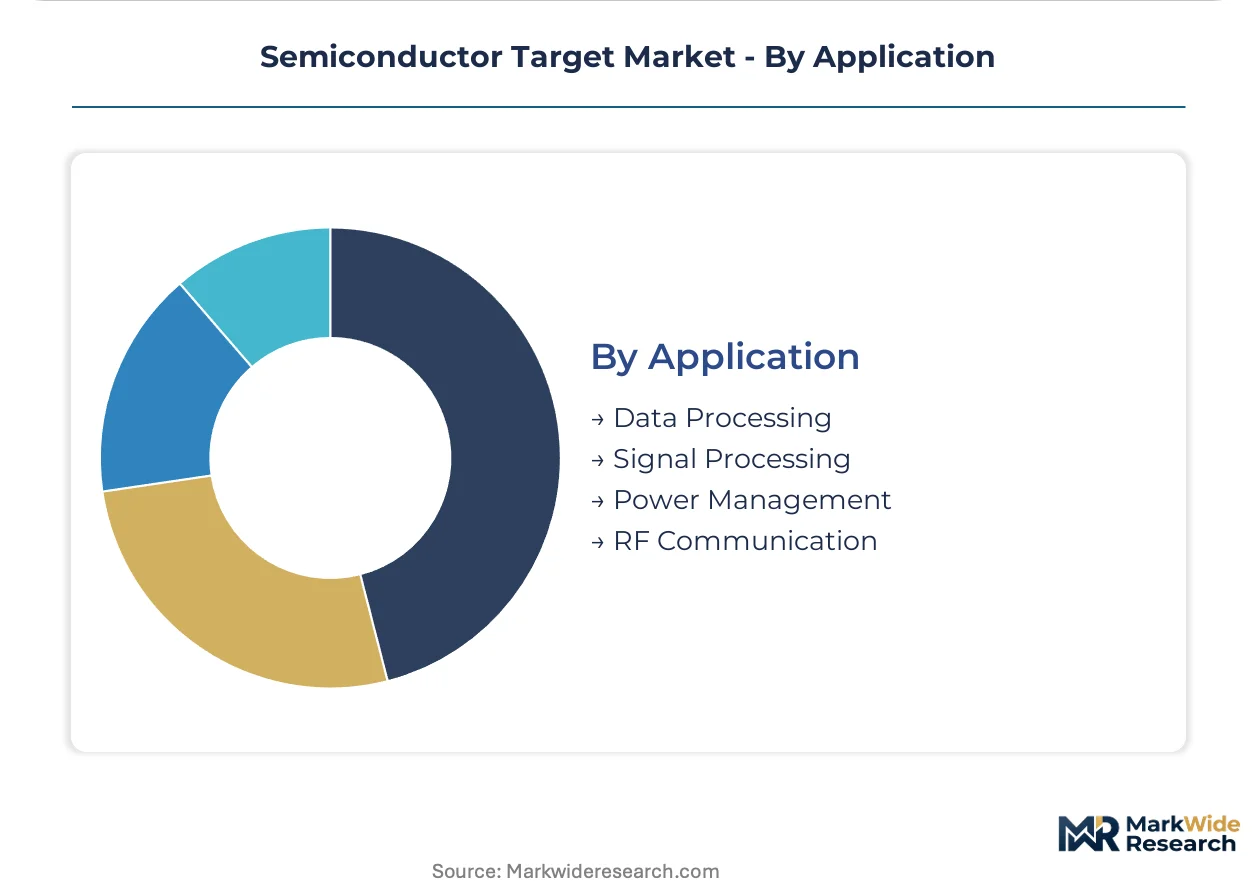
Application:
Functional performance requirements determine target composition complexity and thermal management specifications.
- Power Management:Voltage regulator and battery management ICs require thick copper and nickel-vanadium deposition layers. Data center buildouts in Virginia and Oregon drive high-volume procurement.
- RF Communication:Millimeter-wave front-ends demand precisely engineered aluminum-scandium and tantalum nitride targets. Satellite constellation operators in California specify radiation-hardened material certifications.
- Data Processing:CPU and GPU logic layers consume ultra-high-purity cobalt and ruthenium for copper interconnect capping.
- Signal Processing:Analog-to-digital converters rely on specialized platinum-group metal targets for precision resistor networks.
Data Processing dominates current target consumption; RF Communication shows the steepest expansion trajectory on 5G and satellite demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's foundry cluster anchors semiconductor target procurement volumes as TSMC and Samsung Electronics expand advanced node capacity in Hsinchu and Tainan Science Parks.
Taiwan
TSMC's Arizona and Kaohsiung fab expansions drive five-nines purity tungsten demand through captive refining partnerships. The National Development Council coordinates domestic smelter subsidies under the Chip 4 alliance framework. Hsinchu Science Park concentrates electron beam melting capacity serving 3nm node production.
United States
Intel's Rio Rancho reclamation facility and Texas Instruments' Dallas manufacturing anchor spent target recovery investments. EPA hazardous waste rules mandate manifest tracking for nickel-vanadium residues. Arizona's Phoenix metro attracts metallurgical joint ventures serving domestic fab construction.
China
State-backed smelters achieve six-nines purity for tungsten and molybdenum targets under dual carbon goals. GB standards and MEE emissions rules tighten manufacturing permits. Yangtze River Delta foundries reduce import dependency through domestic refining expansion.
Germany
Automotive power module manufacturers in Stuttgart and Munich enforce AEC-Q100 qualification cycles for tantalum supply chains. REACH registration requirements restrict certain alloying elements. Bavaria's semiconductor equipment cluster drives ceramic bonding expertise for rotatable targets.
South Korea
Samsung Electronics anchors gallium nitride target procurement through long-term offtake agreements with domestic smelters. METI-aligned export protocols govern high-purity cobalt shipments. Busan-Ulsan metallurgical facilities supply RF power amplifier manufacturers.
Semiconductor Target Market Competitive Landscape
Global majors compete with regional champions across refining capacity and foundry integration depth. The vendor base stratifies between captive suppliers serving single foundry networks and independent metallurgical houses qualifying across multiple fabs. Three archetypes dominate: integrated semiconductor manufacturers with in-house reclamation, Japanese and German electron beam melting specialists, and Chinese state-backed smelters expanding six-nines capacity. Competitive moves concentrate on long-term offtake contracting and geographic co-location with fab construction.
Among integrated device manufacturers, TSMC, Samsung Electronics, and Intel exemplify distinct supply security strategies. TSMC leverages captive refining partnerships to secure five-nines purity tungsten. Samsung Electronics anchors gallium nitride procurement through Korean smelter offtake agreements. Intel differentiates via spent target reclamation capacity at its New Mexico facility.
| Leading Market Players |
|---|
| TSMC |
| Samsung Electronics |
| Intel |
| Nvidia |
| Broadcom |
| SK Hynix |
| Micron |
| Qualcomm |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
Electron beam melting energy costs cascade through semiconductor target pricing tiers as five-nines purity tungsten moves from Japanese and German metallurgical facilities to Taiwan foundries and Arizona fabs. High-purity refining capacity scarcity concentrates pricing power among electron beam specialists while automotive power module buyers absorb premium markups for AEC-Q100 qualified tantalum supply.
Pricing Analysis
Input-cost pass-through from tantalum ore and cobalt concentrate volatility shapes contract structures across the supply chain. Pricing stratifies across six-nines purity premium tiers for advanced node foundries, five-nines standard grades for power semiconductor manufacturers, and four-nines economy compositions for discrete device makers. Price differentiation hinges on electron beam melting certification and REACH-compliant supply chain documentation. Cost compression in standard-grade tungsten targets is intensifying because Chinese state-backed smelters are expanding six-nines domestic capacity. Automotive power module manufacturers show the least price sensitivity due to AEC-Q100 qualification lock-in effects, while consumer electronics buyers prioritize cost-optimized aluminum and copper targets.
Supply Chain Analysis
High-purity tantalum feedstock rests on central African artisanal mining operations and Brazilian hard rock deposits, creating raw material dependencies that stretch qualification timelines. Electron beam melting capacity concentrates in Japan and Germany, while Taiwan and South Korea anchor downstream target fabrication for foundry customers. Raw material dependencies span tantalum ore, cobalt concentrate, and high-purity tungsten powder. Single-source vulnerability persists in electron beam melting equipment supply, where three facilities globally control ultra-high-purity refining. Distribution runs through long-term offtake agreements directly from metallurgical houses to captive foundry partnerships, displacing spot procurement for silicon carbide and gallium nitride materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor target procurement has shifted toward a late-cycle quality story as automotive electrification mandates AEC-Q100 qualified supply chains with documented provenance. Five-nines purity specifications now separate qualified suppliers from commodity competitors.
For Market Incumbents: To counter Chinese state-backed smelter expansion in six-nines tungsten refining, Japanese and German electron beam specialists should deepen captive partnerships with Taiwan and Arizona foundries while accelerating spent target reclamation capacity in New Mexico and Arizona. Certification investment in REACH-compliant tantalum supply chains represents the critical defensive lever against conflict mineral disclosure delays.
For New Entrants and Emerging Players: Indian display and logic fab construction under the PLI scheme offers the most penetrable geographic entry point for metallurgical joint ventures with Korean technology partners. RF power amplifier manufacturers in South Korea present a white-space application target for gallium nitride target suppliers with ceramic bonding expertise. A qualification-fast go-to-market angle centers on offering ten-week target qualification cycles through machine learning-driven grain orientation mapping.
For Investors and Strategic Acquirers: Consolidation pressure builds where electron beam melting capacity scarcity meets automotive qualification timeline extension. Long-term viability over the next decade favors vertically integrated metallurgical houses with captive refining and reclamation capabilities. The acquisition target archetype combines electron beam melting expertise with established foundry qualification relationships. Export licensing divergence for high-purity cobalt and tantalum across US, EU, and Chinese jurisdictions warrants ongoing watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Power semiconductor manufacturers lock in Korean and Japanese smelter capacity ahead of automotive ramps. |
| Backward Integration | Intel's Rio Rancho reclamation facility recovers gallium and indium values from spent targets. |
| Joint Venture | Korean metallurgists partner with Indian industrial groups to secure local supply under PLI incentives. |
| Capacity Expansion | Chinese state-backed smelters build six-nines tungsten refining capacity under dual carbon goals. |
| Green Manufacturing Transition | Closed-loop refining services capture residual metal value while avoiding EPA hazardous waste liabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foundry procurement managers, electron beam melting specialists, automotive power module qualification engineers, and semiconductor equipment OEMs with secondary validation. Secondary sources encompassed EPA hazardous waste filings, REACH registration databases, SEC 10-K disclosures from integrated device manufacturers, and customs trade data on high-purity metal imports. Bottom-up target consumption models triangulated against top-down foundry capacity expansion announcements.
Comparable-period anchoring linked forward projections to historical qualification timeline patterns and purity grade adoption curves across the analysis window. The analytical framework segmented by device architecture, substrate material technology, end-user industry reliability standards, and functional application requirements. CAGRs derived from installed base replacement rates and automotive electrification penetration assumptions. Forecast inputs incorporated electron beam melting capacity expansion schedules and automotive inverter production ramp timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export licensing divergence for tantalum and cobalt, electron beam melting equipment lead times, and automotive qualification cycle extensions. Forecasts reflect documented assumptions about foundry capacity migration patterns and purity grade specification trajectories. A small set of triggers—conflict mineral certification delays, REACH registration scope expansion, and dual carbon goal enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
North America Semiconductor Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Semiconductor IP Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Gaas Wafer Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
India Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Analog Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market