
 Asia Pacific Flash Memory Market | 2026-2036
Asia Pacific Flash Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Flash Memory Market Insights
The performance gap between enterprise-grade 3D NAND and consumer-level 2D NAND is broadening into a genuine market bifurcation. Samsung Electronics leverages its Pyeongtaek fabrication complex to sustain leadership in high-layer-count vertical flash. SK Hynix anchors its competitive position through advanced packaging integration for AI server modules. Yangtze Memory Technologies differentiates via domestic channel control across China's telecom and industrial automation sectors.
Asia Pacific flash memory encompasses non-volatile solid-state storage devices fabricated through floating-gate or charge-trap NAND architectures, with bit densities now exceeding 200 layers in leading 3D configurations. These devices retain data without power and serve as primary storage across consumer mobile devices, enterprise servers, and automotive control systems. SSDs command the largest value pool as datacenter operators displace mechanical drives, while embedded flash grows fastest from automotive ECU and IoT module integration. 3D NAND leads form factor evolution as manufacturers stack cells vertically to reduce cost-per-bit, whereas eMMC maintains volume relevance in cost-constrained education and retail endpoints.
Japan's METI semiconductor revitalization framework and South Korea's K-Semiconductor Belt Act shape capital allocation and facility expansion timelines across the region. China's MIIT and SAMR enforce domestic content thresholds that redirect OEM procurement toward local suppliers like Yangtze Memory Technologies. Stakeholders must monitor how export control classifications from multiple jurisdictions constrain equipment access for advanced node development.
Market Dynamics
Enterprise AI training clusters across Singapore and Australia are compressing storage refresh cycles, forcing NAND procurement to migrate from capacity-driven to performance-driven specifications. This demand recalibration is electrifying investment in high-layer 3D architectures and advanced packaging integration.
Growth Catalysts
- AI Server Density Requirements:Hyperscale datacenter operators in Singapore and Australia now specify NAND modules with enhanced thermal tolerance and sustained throughput for GPU-accelerated training workloads.
- K-Semiconductor Belt Act:South Korea's capital allocation framework accelerates facility expansion timelines across the Pyeongtaek-Yongin corridor, concentrating captive ecosystem development.
- Automotive ECU Integration:ADAS controller architectures in Japan and South Korea mandate embedded flash with extended temperature ratings and deterministic latency profiles.
Market Restraints
- Extreme Ultraviolet Lithography Access Constraints:Export control classifications from multiple jurisdictions restrict equipment procurement for advanced node development beyond 200-layer configurations.
- Fluorinated Gas Supply Concentration:Etching chemistry inputs concentrate among Japanese and South Korean suppliers, exposing fabrication timelines to input cost volatility and allocation disputes.
- Charge-Trap Architecture Limitations:Current 3D NAND cell designs face electron retention degradation at elevated operating temperatures, constraining automotive and industrial deployment.
Strategic Opportunities
- Underpenetrated Industrial Automation:China's domestic channel control via MIIT guidelines creates procurement pathways for local suppliers into telecom base station and factory controller applications.
- Automotive Zonal Architecture Convergence:Integration of domain controllers with centralized storage pools in electric vehicle platforms creates specification openings for high-reliability NAND modules.
- PLI Scheme Tailwinds:India's production-linked incentive framework for electronics manufacturing attracts module assembly investment, establishing regional supply presence for education and retail endpoints.
Industry Challenges
- Packaging Engineering Talent Scarcity:Advanced 3D stacking and hybrid bonding processes require specialized process integration expertise concentrated among incumbent South Korean and Japanese engineering pools.
- Cross-Border Certification Timelines:Divergent electromagnetic compatibility and safety standards across China's GB system, Japan's JIS framework, and Australia's ACMA requirements extend product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Flash Memory Market |
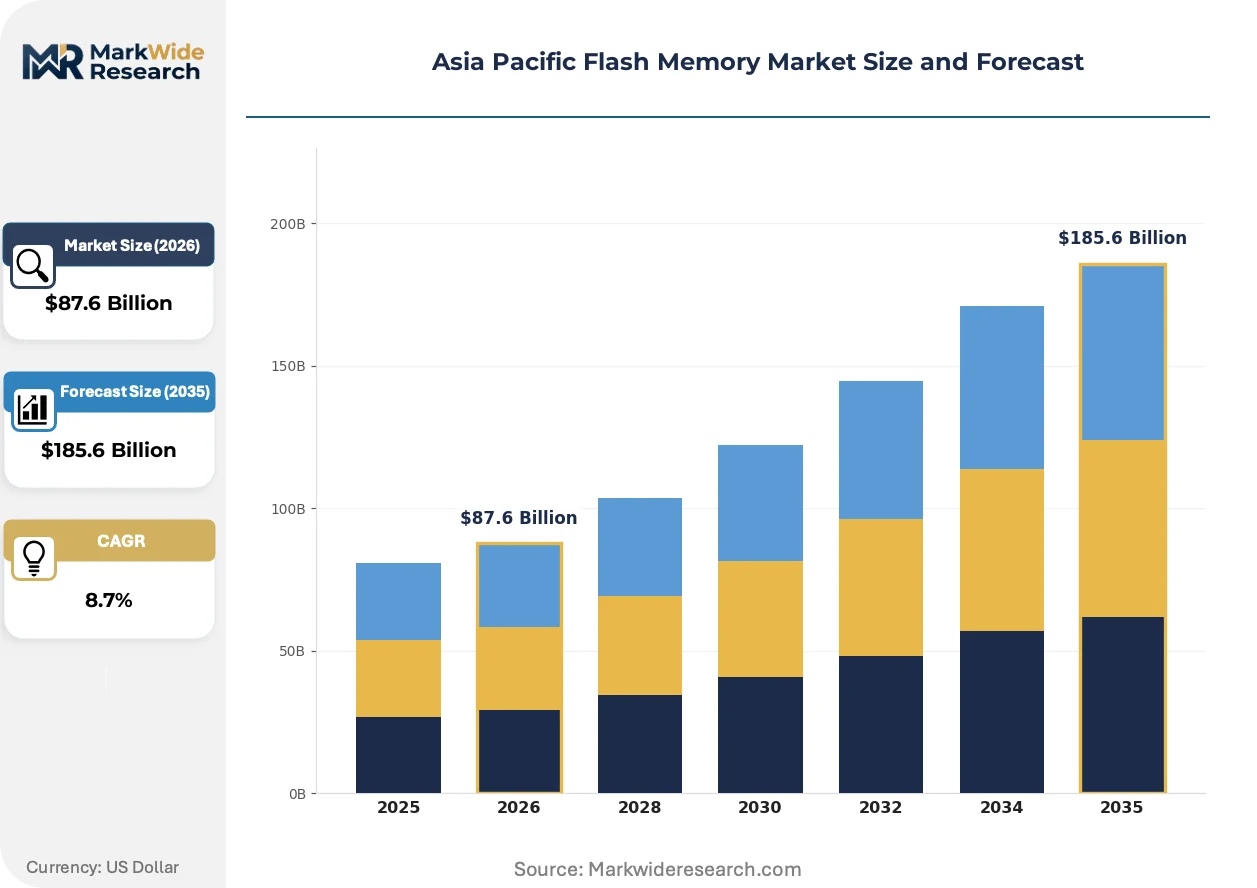
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SD Cards, USB Flash Drives, SSDs, Embedded Flash Application: Consumer Electronics, Automotive, Industrial Automation, Telecom Equipment Form Factor: 2D NAND, 3D NAND, UFS, eMMC End User: Retail, OEMs, Healthcare, Education |
| Companies Covered | Kioxia, Yangtze Memory Technologies, Samsung Electronics, ATP Electronics, Winbond Electronics, SK Hynix, Western Digital, Macronix International, Micron Technology, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Flash Memory Market Trends and Innovations
Process-node compression and architectural stacking are converging to redefine cost-per-bit trajectories across the Asia Pacific flash memory landscape. These technical currents are forcing equipment strategies and procurement specifications to synchronize more tightly than in prior technology generations.
Charge-trap 3D NAND with 200-plus layer vertical stacking is electrifying density scaling roadmaps for enterprise SSD applications. Datacenter operators in Singapore and Australia now specify these configurations for AI training storage tiers. The technology is compressing floor space requirements per petabyte while elevating thermal design power thresholds.
China's MIIT domestic content thresholds are redirecting OEM procurement flows toward local NAND fabrication. Industrial automation and telecom equipment manufacturers face sourcing mandates that reshape supplier qualification processes. Yangtze Memory Technologies captures channel position through compliance-aligned module supply to state-affiliated end-users.
Buyer concentration among hyperscale cloud operators is compressing negotiation leverage for component suppliers. Direct procurement contracts with Samsung Electronics and SK Hynix now displace distributor-mediated volume arrangements across South Korea and Japan. This channel consolidation is most visible in enterprise SSD categories where annual volume commitments exceed legacy procurement thresholds by substantial margins.
Asia Pacific Flash Memory Market Segmentation
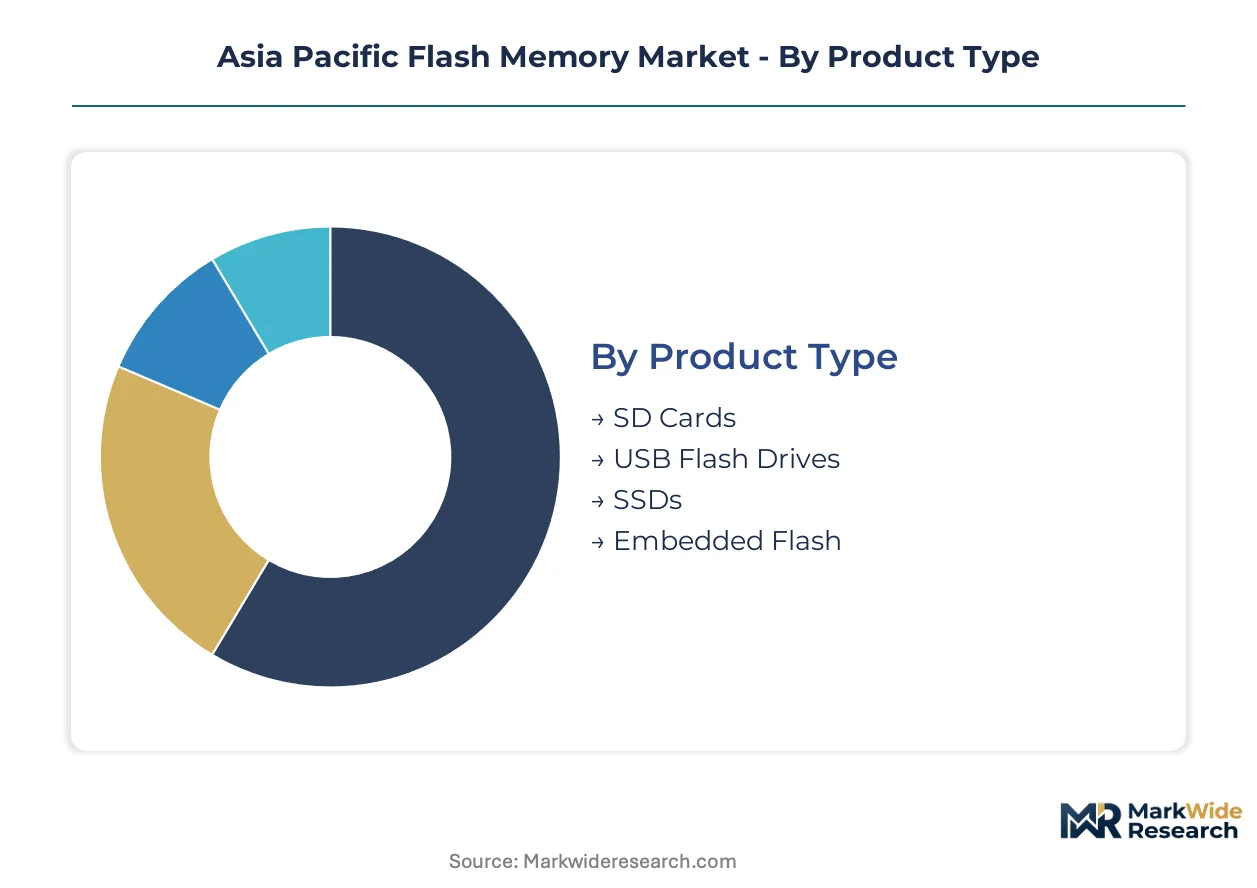
Flash memory segmentation in the Asia Pacific region reflects divergent technical requirements across AI datacenters, automotive ECUs, and cost-constrained consumer devices. Procurement specifications now split sharply between performance-optimized enterprise tiers and price-driven volume categories.
Product Type:
Customization intensity varies from commodity removable media to application-specific embedded modules with firmware-locked configurations.
- SSDs:Enterprise NVMe and SATA configurations now dominate procurement from Singapore and Australian hyperscale operators refreshing storage for GPU-accelerated training clusters. Thermal tolerance specifications above 70°C operating temperatures are displacing mechanical drives in these facilities.
- Embedded Flash:Automotive-grade modules with deterministic latency profiles and extended temperature ratings are capturing specification slots in South Korean and Japanese ADAS controller architectures. Integration into zonal domain controllers elevates reliability requirements beyond consumer tiers.
- SD Cards:Removable storage maintains volume relevance in surveillance and retail POS terminals across Southeast Asian markets.
- USB Flash Drives:Education sector procurement in India and Indonesia sustains demand for cost-optimized portable storage with basic shock resistance.
Leading the category by volume: SSDs. Expanding most quickly: Embedded Flash.
Application:
End-use concentration shifts toward infrastructure-heavy segments as industrial automation and telecom base station deployments accelerate.
- Industrial Automation:Factory controller applications across China's Yangtze River Delta specify NAND with vibration tolerance and deterministic write endurance. MIIT domestic content thresholds redirect procurement toward Yangtze Memory Technologies for state-affiliated manufacturing facilities.
- Automotive:Electric vehicle platforms in Japan and South Korea integrate centralized storage pools with zonal architecture convergence, mandating AEC-Q100 qualified modules with 15-year data retention guarantees.
- Telecom Equipment:Base station controllers in China and India specify industrial-temperature flash for outdoor deployment reliability.
- Consumer Electronics:Smartphone and tablet manufacturers concentrate procurement in South Korean and Chinese assembly hubs with tiered performance specifications.
Dominant by procurement value: Industrial Automation. Steepest expansion trajectory: Automotive.
Form Factor:
Vertical stacking density now separates premium enterprise supply from legacy planar configurations serving price-sensitive endpoints.
- 3D NAND:Charge-trap architectures exceeding 200 layers compress floor space per petabyte in Singapore and Australian datacenter deployments. Samsung Electronics and SK Hynix anchor captive production ecosystems in South Korea's Pyeongtaek-Yongin corridor for these high-layer configurations.
- 2D NAND:Legacy planar cells maintain cost-positioned supply for education and retail endpoints where density requirements remain modest.
- UFS:Universal Flash Storage commands smartphone flagship tier specifications with command queue optimization.
- eMMC:Embedded MultiMediaCard persists in cost-constrained education tablets and industrial gateways with simplified controller requirements.
Technology leadership sits with: 3D NAND. Volume anchor remains: 2D NAND.
End User:
Channel structure bifurcates between direct hyperscale contracts and distributor-mediated SME procurement.
- OEMs:Direct annual volume commitments with Samsung Electronics and SK Hynix now displace legacy distributor arrangements for enterprise SSD categories across South Korea and Japan. Contract thresholds exceed prior procurement baselines by substantial margins.
- Healthcare:Medical device manufacturers in Japan and Australia specify NAND with extended retention for imaging equipment and patient monitoring systems.
- Education:India's PLI scheme attracts module assembly investment for cost-optimized storage in government tablet distribution programs.
- Retail:Consumer electronics chains across Southeast Asia stock branded removable media with regional packaging localization.
Procurement concentration centers on: OEMs. Channel development focus targets: Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyeongtaek-Yongin corridor anchors Asia Pacific flash memory production through Samsung Electronics and SK Hynix captive ecosystems. Singapore and Australian hyperscale operators compress storage refresh cycles for AI training clusters. China's MIIT domestic content thresholds redirect procurement flows toward local NAND fabrication.
China
Industrial automation and telecom base station deployments concentrate NAND demand in the Yangtze River Delta. MIIT guidelines enforce domestic semiconductor sourcing thresholds that reshape supplier qualification processes. Yangtze Memory Technologies captures channel position through compliance-aligned module supply to state-affiliated manufacturing facilities.
South Korea
AI server density requirements and automotive ADAS controller integration drive specification upgrades for high-layer 3D NAND. The K-Semiconductor Belt Act accelerates capital allocation timelines across fabrication facility expansion. Samsung Electronics and SK Hynix anchor captive production ecosystems in the Pyeongtaek-Yongin corridor.
Japan
Automotive ECU architectures and medical imaging equipment mandate extended retention guarantees for embedded flash modules. METI's semiconductor revitalization framework shapes facility investment timelines and R&D tax incentive structures. Industrial clusters in the Chubu and Kansai regions concentrate etching chemistry supplier networks.
Singapore
Hyperscale datacenter operators specify NAND modules with enhanced thermal tolerance for GPU-accelerated training workloads. The country's national electronics regulator enforces electromagnetic compatibility standards that compress product qualification cycles. Enterprise storage procurement concentrates in purpose-built facilities across the island's western industrial zones.
Australia
Cloud infrastructure expansion and healthcare imaging system upgrades sustain enterprise SSD procurement growth. ACMA electromagnetic compatibility requirements extend certification timelines for imported storage modules. Datacenter development clusters in Sydney and Melbourne drive specification shifts toward performance-driven NAND configurations.
Asia Pacific Flash Memory Market Competitive Landscape
Premium-margin players sit above commodity-margin players across layer-count and packaging integration capabilities. The vendor base stratifies between captive fabrication specialists and fabless module integrators. Three archetypes dominate: vertically integrated memory fabricators, advanced packaging specialists, and regional channel controllers. Capacity expansion and strategic technology licensing represent the dominant competitive moves across the analysis window.
Among Asia Pacific-based fabricators, Samsung Electronics, SK Hynix, and Yangtze Memory Technologies occupy distinct tier positions. Samsung Electronics exemplifies the vertically integrated archetype through captive ecosystem control. SK Hynix represents advanced packaging integration specialization for AI server module applications. Yangtze Memory Technologies sits within the regional channel controller archetype, leveraging domestic compliance alignment for state-affiliated procurement pathways.
| Leading Market Players |
|---|
| Kioxia |
| Yangtze Memory Technologies |
| Samsung Electronics |
| ATP Electronics |
| Winbond Electronics |
| SK Hynix |
| Western Digital |
| Macronix International |
| Micron Technology |
| Others |
Pricing and Supply Chain Analysis
The performance gap between enterprise-grade 3D NAND and consumer-level 2D NAND manifests in both pricing power and supply chain configuration. Enterprise modules command value-based premiums through thermal tolerance guarantees and sustained throughput specifications, while commodity tiers compete on wafer cost and assembly efficiency. This bifurcation concentrates margin capture among South Korean fabricators with captive high-layer production, leaving module integrators to absorb price volatility in planar cell supply.
Pricing Analysis
Value-based pricing anchored to petabyte-scale datacenter throughput specifications dominates enterprise SSD procurement. Three-tier pricing structure across premium, standard, and economy levels separates AI training modules with enhanced thermal ratings from education-sector eMMC bundles. Cost compression in consumer planar NAND is intensifying because China's MIIT domestic content mandates redirect volume toward local suppliers. Hyperscale operators in Singapore and Australia exhibit lowest price sensitivity, while India's education tablet programs drive acute cost optimization in removable storage tiers.
Supply Chain Analysis
Freight costs for etching chemistry inputs from Japan and South Korean suppliers elevate working capital requirements across the Pyeongtaek-Yongin corridor. Fabrication concentrates in South Korea, Japan, and China, with equipment dependencies drawing from Dutch lithography specialists and American deposition tool vendors. Single-source vulnerability in fluorinated gas supply exposes 200-plus layer production timelines to allocation disputes. Distribution runs through direct annual volume contracts with hyperscale operators, displacing legacy distributor arrangements in enterprise categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
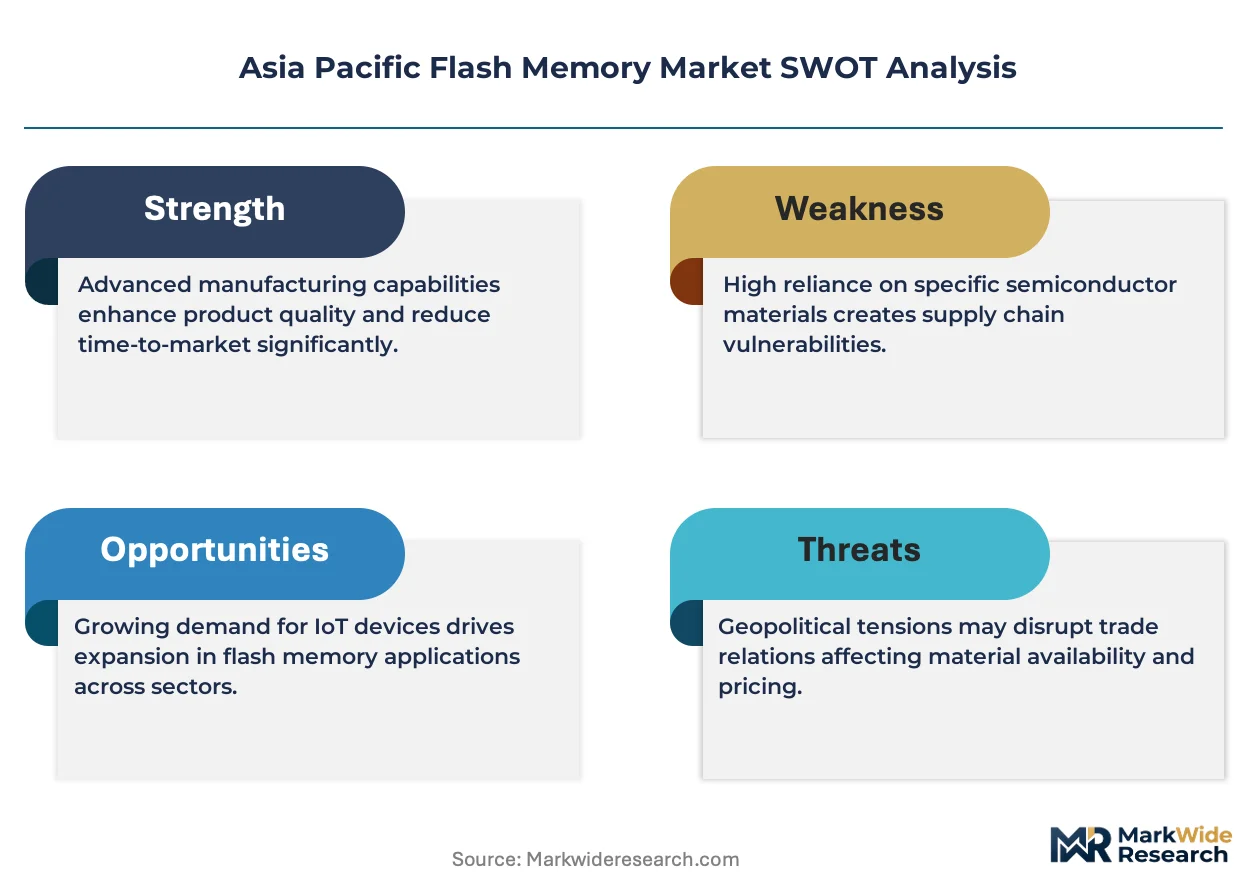
This market functions as a vertical-integration race where upstream control over high-layer charge-trap architectures and advanced packaging capabilities determines margin sustainability. Players are pursuing backward integration into etching chemistry supply and captive packaging capacity to defend specification premiums.
For Market Incumbents: Deploy advanced packaging integration as the primary defensive lever. Samsung Electronics and SK Hynix should expand hybrid bonding capacity in the Pyeongtaek-Yongin corridor to lock in AI server module specifications. Certification investment in AEC-Q100 automotive qualifications creates switching costs against emerging Chinese suppliers. Threat from Yangtze Memory Technologies' domestic channel control in China's industrial automation sector necessitates accelerated compliance alignment with MIIT guidelines.
For New Entrants and Emerging Players: Direct procurement platform partnerships offer the most penetrable route for module integrators without captive fabrication. White-space targets include India's PLI-attracted assembly facilities for education and retail endpoints, and Australia's ACMA-compliant healthcare imaging storage upgrades. Target industrial automation controllers in Southeast Asian markets where specification requirements remain below enterprise datacenter thresholds. Go-to-market angle should emphasize firmware customization for deterministic latency profiles in factory controller applications.
For Investors and Strategic Acquirers: Re-rating potential sits with advanced packaging specialists given AI server density requirements compressing procurement cycles toward integrated module suppliers. Long-term viability over a multi-year horizon favors players with demonstrated high-layer stacking roadmaps and established hyperscale operator relationships. Acquisition target archetype: fabless module integrators with automotive certification pipelines and existing MIIT compliance frameworks. Signal to watch is export control classification expansion restricting equipment access beyond current 200-layer configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Layer 3D NAND Capacity Expansion | Samsung Electronics and SK Hynix anchor captive ecosystems in South Korea's Pyeongtaek-Yongin corridor. |
| Advanced Packaging Integration | Hybrid bonding processes for AI server modules elevate thermal tolerance specifications above 70°C operating thresholds. |
| Domestic Content Compliance Alignment | Yangtze Memory Technologies captures channel position through MIIT-guided procurement in China's state-affiliated manufacturing facilities. |
| Automotive Certification Investment | AEC-Q100 qualification opens specification slots in Japanese and South Korean electric vehicle zonal architectures. |
| Regional Module Assembly Footprint | India's PLI scheme attracts investment for cost-optimized education and retail endpoint supply. |
Research Methodology
SEC filings from memory fabricators, hyperscaler capex disclosures, and customs trade data formed the secondary backbone for volume and value estimation. Primary interviews with datacenter procurement officers, automotive Tier 1 supplier engineers, and industrial automation system integrators validated specification trends and pricing benchmarks. Bottom-up triangulation across product type, application, and form factor segments reconciled with top-down regional demand aggregation.
Historical trendline analysis of layer-count roadmaps and packaging technology adoption curves informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, form factor, and end user, with additional granularity on domestic content compliance status for China-bound supply. CAGRs derived from elasticity-adjusted demand curves incorporating AI server density requirements and automotive ECU integration trajectories. Forecast inputs encompassed equipment access constraints from multi-jurisdictional export controls and fluorinated gas supply allocation patterns.
Inputs from equipment vendors and etching chemistry suppliers were available through the study window; gaps in real-time hyperscale operator inventory positions introduce uncertainty bands around near-term demand inflection points. Forecasts reflect documented assumptions on layer-count migration timelines and packaging yield improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Semiconductor Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Semiconductor Clock Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
High Reliability Semiconductor Market
Semiconductors
Gaas Wafer Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
India Semiconductor Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Organic Electronics Market
Semiconductors
Organic Polymer Electronics Market