
 Aluminum Gallium Indium Phosphide Semiconductor Market | 2026-2036
Aluminum Gallium Indium Phosphide Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Gallium Indium Phosphide Semiconductor Market Analysis
Japanese epitaxial wafer producers is repositioning capacity toward 6-inch AlGaInP platforms to serve the automotive lighting tier. OSRAM Opto Semiconductors leverages its vertical integration from epitaxy to packaged LED to dominate premium automotive forward-lighting programs. WIN Semiconductors anchors the pure-play foundry layer with GaAs and AlGaInP process nodes optimized for high-volume RF and optoelectronic customers. Infineon Technologies differentiates through its automotive-qualified portfolio, supplying AlGaInP-based emitter components to Tier 1 headlamp module suppliers.
Aluminum Gallium Indium Phosphide is a III-V compound semiconductor with tunable direct bandgap spanning 1.9 to 2.3 electron volts, typically grown via metal-organic chemical vapor deposition on GaAs substrates to produce red, orange, and yellow emission spectra for visible-light applications. LEDs occupy the largest value share within the product-type dimension, though laser diodes for LiDAR and structured-light sensing are pulling the fastest growth as automotive OEMs adopt solid-state scanning architectures. MOCVD technology leads the process hierarchy due to its precision in controlling aluminum and indium mole fractions across quantum well structures, while hydride vapor phase epitaxy remains confined to research-scale production and specialty photodetector batches.
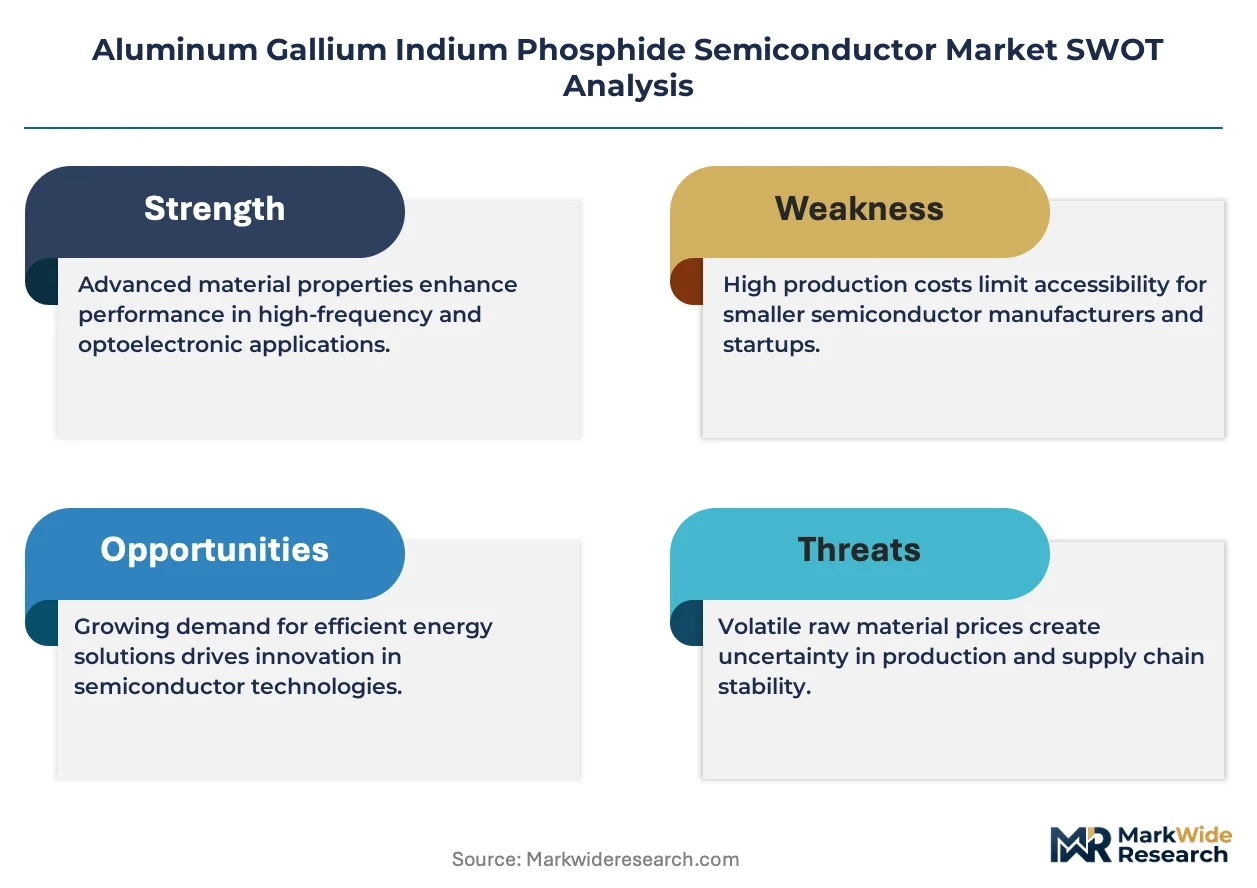
The US EPA and NHTSA jointly shape demand through vehicle lighting efficiency mandates and safety-performance testing protocols that specify minimum luminous efficacy and color-rendering thresholds. REACH and RoHS frameworks in Europe restrict cadmium and mercury content in competing technologies, indirectly advantaging AlGaInP-based red emitters in display and signage applications. China's GB standards and MIIT industrial policies establish domestic content benchmarks for LED procurement in municipal infrastructure projects. Stakeholders must monitor how tightening rare-earth export controls and gallium processing capacity constraints in China reshape substrate pricing and epitaxial supply security.
Market Dynamics
Automotive OEMs are consolidating LED headlamp sourcing around vertically integrated suppliers capable of delivering automotive-qualified AlGaInP emitters with full traceability from epitaxy to module assembly.
Growth Catalysts
- EPA energy-efficiency mandates:Tightened solid-state lighting standards in the United States are forcing fixture manufacturers to specify high-efficacy red and amber emitters, directly expanding AlGaInP die procurement.
- LiDAR sensor proliferation:Automotive solid-state scanning architectures are incorporating AlGaInP laser diodes for structured-light applications, creating incremental demand beyond traditional LED illumination.
- China's MOCVD capacity expansion:Domestic tool installation rates and MIIT-backed LED chip subsidies are pulling epitaxial wafer production eastward, lowering regional supply costs.
Market Restraints
- Gallium supply concentration:Processing capacity constraints and export control tightening in China create substrate pricing volatility and supply security exposure for non-domestic purchasers.
- GaAs substrate cost structure:High-purity 6-inch gallium arsenide wafers command premium pricing, compressing margins for mid-tier LED chip producers unable to absorb input fluctuations.
- Blue LED substitution:InGaN-based phosphor-converted alternatives are displacing AlGaInP in general illumination applications where color purity requirements permit spectral compromise.
Strategic Opportunities
- Micro-LED display manufacturing:Emerging transfer and bonding technologies are enabling AlGaInP red micro-LEDs for augmented-reality headsets, opening premium display segments.
- India's PLI scheme for LEDs:Domestic manufacturing incentives and BIS certification requirements are attracting compound semiconductor packaging investments to serve South Asian infrastructure projects.
- Automotive interior ambient lighting:Tier 1 module suppliers are expanding RGB LED content per vehicle, pulling additional AlGaInP die volume for customizable cabin illumination systems.
Industry Challenges
- MOCVD reactor operator scarcity:Precision control of aluminum and indium mole fractions across quantum well structures requires specialized technicians, creating hiring bottlenecks for capacity expansion.
- AEC-Q102 certification timelines:Extended qualification cycles for automotive-grade optoelectronics delay revenue recognition from new epitaxial designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Gallium Indium Phosphide Semiconductor Market |
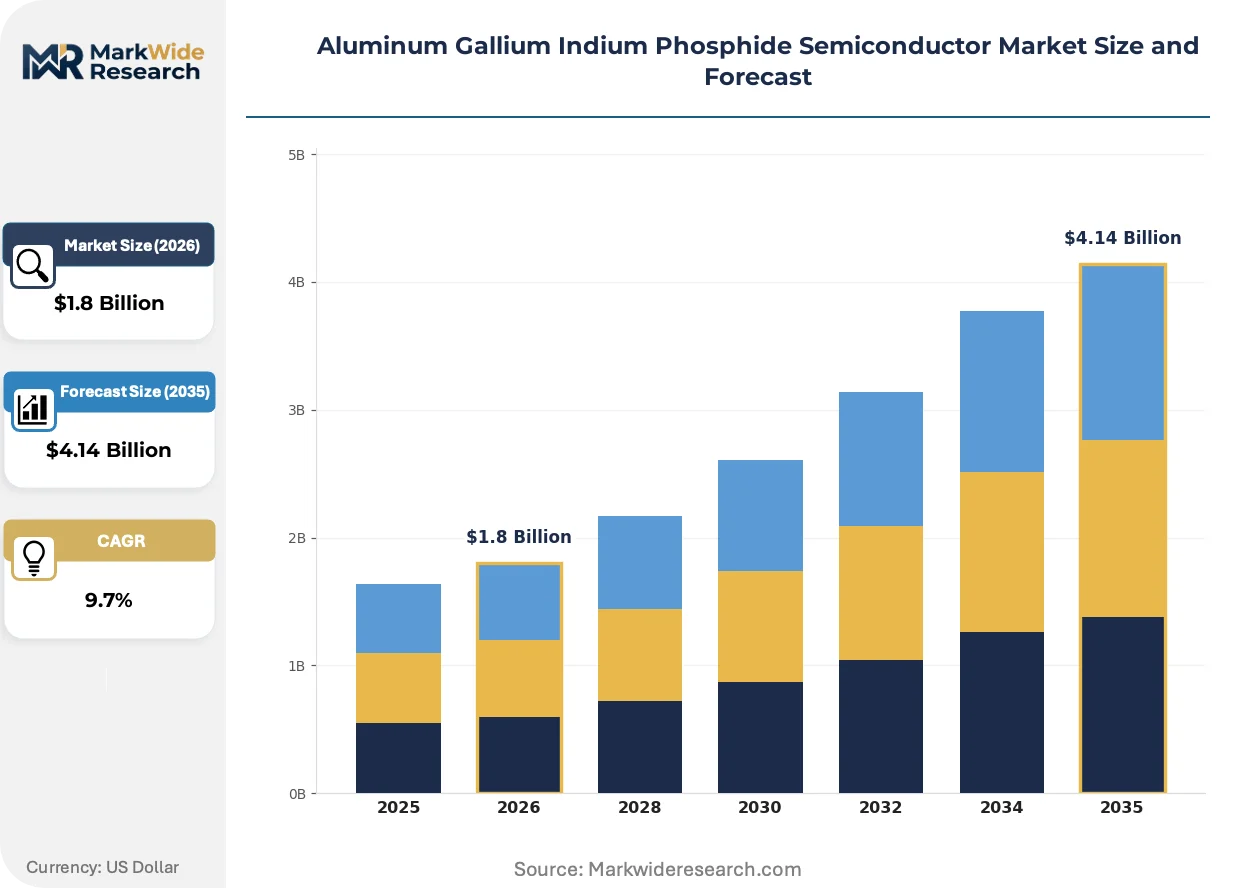
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LEDs, Laser Diodes, Photodetectors, RF Devices Technology: MOCVD, LPE, Hydride Vapor Phase Epitaxy, Liquid Phase Epitaxy Application: Telecommunications, Consumer Electronics, Automotive, Lighting End User: Manufacturers, Research Institutions, Electronics Companies, Aerospace |
| Companies Covered | OSRAM Opto Semiconductors, WIN Semiconductors, NXP Semiconductors, GaN Systems, STMicroelectronics, Analog Devices, Infineon Technologies, Advanced Wireless Semiconductor, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Gallium Indium Phosphide Semiconductor Market Emerging Trajectories
Process automation and wafer-size transitions are compressing manufacturing economics while regulatory pressure on lighting efficiency accelerates specification upgrades across automotive and infrastructure end-uses.
6-inch AlGaInP epitaxial platforms are rewriting cost structures for high-brightness LED production. Japanese wafer producers are repositioning capacity to serve automotive lighting tiers demanding larger die formats. This transition is enabling single-wafer output gains that compress per-lumen manufacturing costs for headlamp-grade emitters.
REACH and RoHS frameworks in Europe are restricting cadmium and mercury content in competing display technologies. These substance bans are indirectly advantaging AlGaInP-based red emitters for signage and professional display applications. Manufacturers serving EU markets are reformulating product portfolios to emphasize phosphide-based alternatives over restricted quantum dot formulations.
Automotive OEMs are consolidating supplier relationships around vertically integrated partners capable of delivering full optical engine solutions. Tier 1 headlamp module suppliers are reducing vendor counts and awarding multi-year contracts to qualified compound semiconductor houses. This concentration is most visible in Germany and Japan, where premium vehicle programs demand simultaneous cost reduction and performance verification.
Aluminum Gallium Indium Phosphide Semiconductor Market Segmentation
AlGaInP semiconductor procurement splits across four distinct dimensions, each reflecting different technical requirements, qualification standards, and margin structures. Buyers navigate trade-offs between performance specifications and supply security across these categories.
Product Type:
Customization intensity varies sharply across this spectrum, from standardized commodity dies to application-specific laser architectures.
- LEDs:High-brightness red, orange, and amber emitters grown on GaAs substrates dominate automotive forward-lighting and traffic signal applications. OEMs in Germany and Japan are consolidating sourcing around vertically integrated suppliers capable of AEC-Q102 qualification.
- Laser Diodes:Edge-emitting and VCSEL structures for LiDAR and structured-light sensing require precise aluminum mole fraction control across quantum wells. Automotive solid-state scanning programs in the United States and South Korea are pulling demand fastest.
- Photodetectors:PIN and avalanche structures for optical communication receivers.
- RF Devices:Heterojunction bipolar transistors and power amplifiers leveraging AlGaInP bandgap engineering.
Leading the category by volume: LEDs. Growing fastest: Laser Diodes.
Technology:
Process maturity creates a cost-precision hierarchy, with established methods competing against emerging alternatives for specific layer structures.
- MOCVD:Metal-organic chemical vapor deposition enables atomic-scale control of aluminum and indium incorporation across multi-quantum-well active regions. China's MIIT-subsidized MOCVD tool installations are compressing regional production costs for high-volume LED manufacturing.
- Hydride Vapor Phase Epitaxy:HVPE achieves faster growth rates for thick cladding layers but lacks the compositional precision required for quantum well structures. Research-scale photodetector production and specialty military applications sustain limited commercial presence.
- LPE:Liquid phase epitaxy serves legacy optoelectronic devices with simpler layer requirements.
- Liquid Phase Epitaxy:Alternative nomenclature for LPE processes in certain regional patent filings.
Dominating production scale: MOCVD. Expanding most quickly: Hydride Vapor Phase Epitaxy for power electronics research.
Application:
End-use concentration determines pricing power, with automotive qualification requirements filtering supplier participation.
- Automotive:Headlamp forward-lighting, interior ambient systems, and emerging LiDAR integration demand AEC-Q102 qualified emitters with full epitaxy-to-module traceability. NHTSA safety-performance testing protocols specify minimum luminous efficacy thresholds that favor high-performance AlGaInP dies.
- Lighting:Municipal infrastructure and commercial solid-state installations pull high-volume demand for standardized red and amber emitters.
- Telecommunications:Optical fiber transmission systems.
- Consumer Electronics:Indicator lamps and display backlighting facing InGaN phosphor-converted substitution pressure.
Highest value concentration: Automotive. Climbing the fastest: Lighting efficiency retrofits driven by EPA mandates.
End User:
Customer sophistication and volume scale segment procurement patterns across the value chain.
- Electronics Companies:Tier 1 module suppliers and consumer device OEMs drive specification-setting for packaged emitters and integrated optical engines. These buyers demand automotive qualification, full material traceability, and multi-year supply agreements.
- Manufacturers:LED chip foundries and epitaxial wafer producers purchasing substrates and precursor chemicals.
- Research Institutions:University and national laboratory programs exploring novel AlGaInP heterostructures.
- Aerospace:Satellite and avionics applications requiring radiation-hardened device performance.
Controlling procurement volume: Electronics Companies. Gaining share fastest: Manufacturers consolidating around 6-inch platform transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium processing capacity concentrates in China, pulling epitaxial wafer production eastward while automotive OEMs in Germany and Japan consolidate sourcing around qualified suppliers. The United States and South Korea are accelerating LiDAR integration programs that reshape demand patterns for compound semiconductor emitters.
China
Domestic MOCVD tool installations and MIIT-backed LED chip subsidies are compressing regional production costs for high-brightness emitters. GB standards establish domestic content benchmarks for municipal infrastructure procurement. The Yangtze River Delta hosts the densest concentration of epitaxial foundries serving automotive lighting tiers.
United States
EPA energy-efficiency mandates for solid-state lighting force fixture manufacturers to specify high-efficacy red and amber AlGaInP dies. NHTSA safety-performance testing protocols set minimum luminous efficacy thresholds that favor premium emitters. Michigan and Texas anchor automotive headlamp module assembly clusters where Tier 1 suppliers consolidate vendor relationships.
Germany
REACH and RoHS frameworks restrict cadmium and mercury in competing display technologies, indirectly advantaging AlGaInP-based red emitters for professional signage. Premium vehicle programs in Bavaria and Baden-Württemberg demand simultaneous cost reduction and full epitaxy-to-module traceability. KBA vehicle-type approval processes filter supplier participation toward AEC-Q102 qualified houses.
Japan
METI industrial policies support 6-inch AlGaInP platform transitions to serve automotive lighting tiers demanding larger die formats. Japanese epitaxial wafer producers are repositioning capacity toward these advanced substrates. The Kanto and Kansai regions concentrate precision optoelectronics manufacturing for export-oriented automotive programs.
South Korea
Automotive solid-state LiDAR programs are incorporating AlGaInP laser diodes for structured-light sensing applications. The country's national semiconductor regulator coordinates domestic content requirements for compound semiconductor devices. Seoul Capital Area and Busan-Ulsan clusters host integrated optoelectronics houses serving Hyundai-Kia supply chains.
Aluminum Gallium Indium Phosphide Semiconductor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue micro-LED display and automotive LiDAR adjacencies. The vendor base stratifies across three tiers: vertically integrated compound semiconductor houses with captive epitaxy, pure-play foundries offering GaAs and AlGaInP process nodes, and fabless design houses outsourcing manufacturing. Dominant competitive moves include backward integration into substrate supply and multi-year qualification contracts with Tier 1 automotive module suppliers.
Among Germany-based semiconductor specialists, OSRAM Opto Semiconductors and Infineon Technologies exemplify the vertically integrated archetype with automotive-qualified portfolios. Taiwan-based WIN Semiconductors anchors the pure-play foundry tier with process nodes optimized for high-volume optoelectronic customers. These three companies represent distinct strategic positions: full optical engine solutions, epitaxial manufacturing services, and automotive emitter components respectively.
| Leading Market Players |
|---|
| OSRAM Opto Semiconductors |
| WIN Semiconductors |
| NXP Semiconductors |
| GaN Systems |
| STMicroelectronics |
| Analog Devices |
| Infineon Technologies |
| Advanced Wireless Semiconductor |
| Texas Instruments |
| Others |
Supply Flow & Price Mechanics
AEC-Q102 certification tiers create a bifurcation between automotive-qualified premium emitters and commodity-grade dies, with this divergence manifesting in both pricing power and supply chain configurations. MIIT-subsidized Chinese foundries compress pricing at the standard tier while German and Japanese vertically integrated houses command premiums through full traceability from epitaxy to module assembly.
Pricing Analysis
Warranty-bundled qualification packages separate automotive-grade pricing from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks AEC-Q102 certification status and luminous efficacy thresholds. Cost compression in the standard tier intensifies because Chinese MOCVD capacity expansion floods municipal lighting procurement. Tier 1 automotive module suppliers exhibit lowest price sensitivity due to liability exposure from headlamp failures.
Supply Chain Analysis
Single-source vulnerability sits with Chinese gallium processing capacity and high-purity 6-inch GaAs substrate supply from Japan and Germany. The AlGaInP supply chain draws from metal-organic precursor chemicals sourced from the United States, South Korea, and Taiwan, plus MOCVD reactor components anchored in Japan and the Netherlands. Export control tightening on gallium compounds creates regulatory restriction risk. Distribution runs through vertically integrated compound semiconductor houses and pure-play foundry intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aluminum Gallium Indium Phosphide Semiconductor Market is becoming a vertical-integration race as players pursue captive control over gallium substrate supply to secure margin and qualification continuity.
For Market Incumbents: Deploy multi-year qualification contracts as the primary defensive lever. Lock Tier 1 automotive module suppliers into exclusive AEC-Q102 supply agreements before Chinese competitors achieve certification parity. Deepen upstream control over gallium arsenide substrate supply to buffer against Chinese export restriction volatility. InGaN phosphor-converted substitution in general illumination threatens volume at the commodity tier.
For New Entrants and Emerging Players: Direct-to-foundry digital procurement platforms offer the lowest-friction entry path. Target India's PLI-subsidized LED packaging clusters where BIS certification requirements filter out established Chinese suppliers. Micro-LED transfer and bonding equipment for augmented-reality headsets represents the most penetrable white-space segment. Lead with application-specific laser diode architectures for solid-state LiDAR rather than competing in saturated LED illumination.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play foundries possessing automotive-qualified process nodes given accelerating OEM consolidation around qualified suppliers. The 5-to-10-year viability window favors compound semiconductor houses with demonstrated AEC-Q102 track records over commodity LED chip producers facing InGaN displacement. Monitor MOCVD tool installation rates in China's Yangtze River Delta as the inflection signal for supply-cost compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive gallium arsenide wafer production insulates margin from Chinese export control volatility. |
| AEC-Q102 Certification Investment | Automotive qualification unlocks multi-year supply contracts with Tier 1 headlamp module suppliers. |
| Micro-LED Transfer Technology Development | Red micro-LED architectures for AR headsets open premium display segments beyond traditional illumination. |
| Geographic Manufacturing Footprint Expansion | India PLI scheme participation captures South Asian infrastructure procurement with BIS compliance. |
| Long-term Supply Agreement with MOCVD Equipment Vendors | Reactor allocation priority secures capacity expansion timing ahead of competitor tool installations. |
Methodological Framework
Multi-period observation of MOCVD tool installation rates, AEC-Q102 certification timelines, and gallium spot pricing anchored the trend analysis, supplemented by interviews with epitaxial wafer producers, Tier 1 automotive module procurement directors, compound semiconductor foundry operations managers, and LED chip packaging engineers. Secondary validation drew from MIIT industrial policy filings, EPA energy-efficiency standard updates, NHTSA safety-performance testing protocols, SEC 10-K disclosures from listed compound semiconductor houses, and customs trade data for gallium arsenide substrate flows. Bottom-up wafer consumption estimates and top-down automotive LED content-per-vehicle models were triangulated to cross-check volume assumptions.
Segment-weighting across product type, technology, application, and end-user dimensions structured the analytical framework across the analysis window. LED and laser diode splits were modeled separately with divergent growth trajectories reflecting LiDAR adoption curves versus headlamp penetration saturation. CAGRs were derived from slope-intercept fitting of annual volume estimates adjusted for substrate pricing volatility. Industry-specific forecast inputs included OEM platform standardization roadmaps and municipal infrastructure procurement pipelines under China's GB standards.
The model holds under stable gallium export control enforcement and continued MIIT subsidy continuity; deviation in rare-earth processing restrictions or automotive semiconductor demand cyclicality would shift trajectory bands. Forecasts reflect documented assumptions about MOCVD reactor throughput yields and 6-inch platform transition timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Discrete Semiconductor Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
India Semiconductor Market
Semiconductors
Semiconductor Target Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Semiconductor IP Market
Semiconductors
Chiplets Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
China Semiconductor Market