
 Semiconductor in Military and Aerospace Market | 2026-2036
Semiconductor in Military and Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor in Military and Aerospace Market Outlook
United States foundry expansion is narrowing the supply gap for trusted military-grade chips. Infineon Technologies leverages its power management portfolio to anchor European defense programs. Texas Instruments sustains broad analog leadership across radar and avionics platforms. BAE Systems differentiates through captive UK fabrication serving sovereign aerospace contracts.
Semiconductors in military and aerospace are electronic components engineered to withstand extreme temperatures, radiation exposure, and mechanical shock across operational lifetimes exceeding fifteen years, typically manufactured on specialized process nodes with enhanced reliability screening. These devices enable mission-critical functions including target acquisition, secure communications, and precision guidance in contested electromagnetic environments. Power management ICs and RF technologies command premium positioning due to their indispensability in electronic warfare and satellite payloads. Analog and digital segments split demand between mature platform upgrades and next-generation system architectures, with microprocessors gaining traction in autonomous weapon systems requiring edge computing capability.
Defense procurement regulations in the United States, including DFARS trusted foundry requirements and ITAR export controls, restrict component sourcing to qualified domestic and allied facilities, directly shaping supplier qualification timelines and capital allocation decisions. European REACH chemical restrictions and CE marking for dual-use goods add compliance layers for components crossing into civilian aviation applications. Stakeholders must monitor how evolving export control classifications and semiconductor sovereignty policies reshape eligible supplier pools and long-term contracting structures.
Market Dynamics
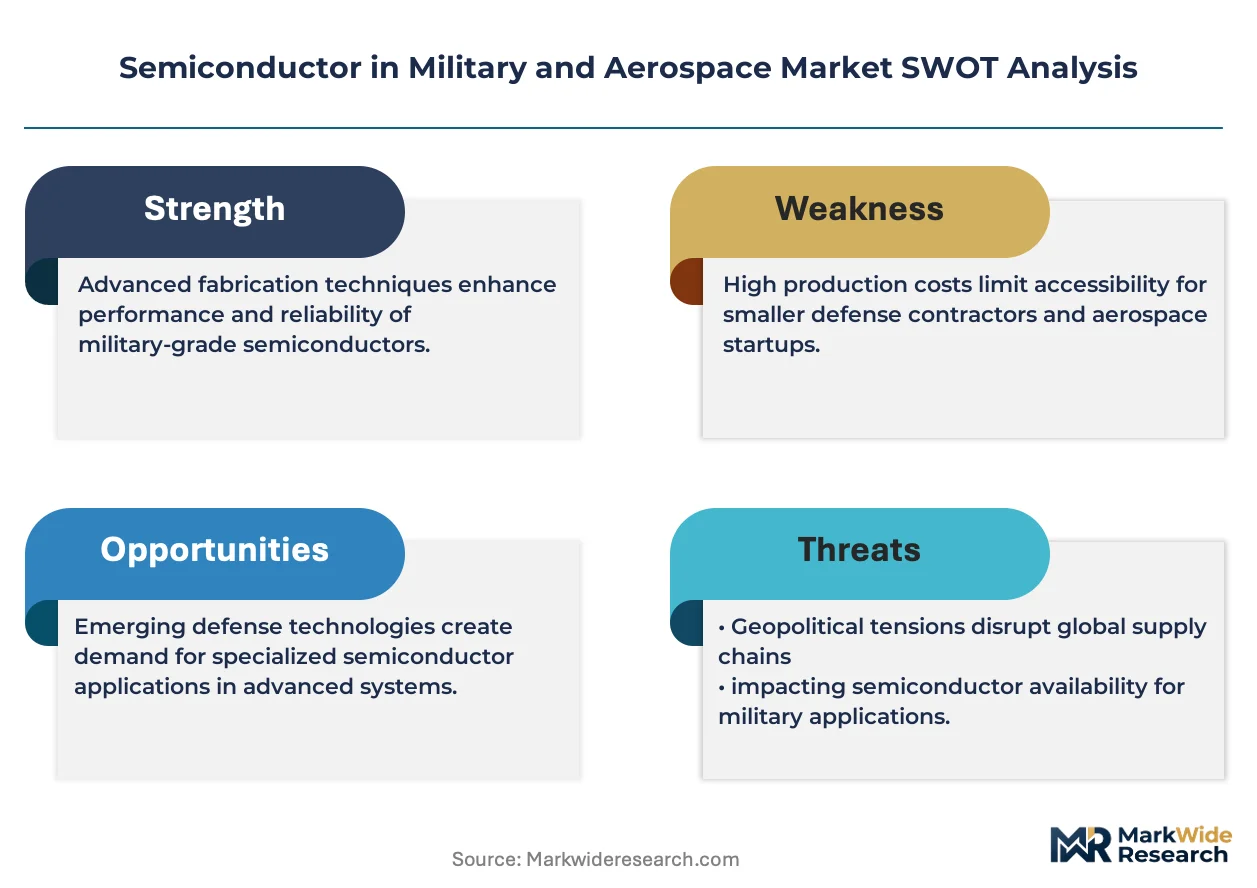
The Pentagon's DFARS trusted foundry mandate is compressing supplier qualification timelines while redirecting capital toward radiation-hardened process development at domestic facilities.
Growth Catalysts
- Satellite constellation deployment:Defense agencies are procuring radiation-tolerant components for proliferated low-Earth orbit architectures, expanding addressable demand for space-grade semiconductors.
- ITAR-controlled supply chains:Export classification restrictions are insulating qualified domestic foundries from price-based import competition, reinforcing margin structures for trusted suppliers.
- Electronic warfare modernization:RF gallium nitride devices are displacing legacy gallium arsenide in radar systems, creating specification upgrade cycles across tactical aircraft platforms.
Market Restraints
- Substrate supply concentration:Silicon carbide wafer production concentrates in Japanese and German facilities, exposing power semiconductor supply to single-source vulnerability.
- Qualification cost barriers:Military-grade screening protocols extend development cycles to 18-36 months, freezing out fabless entrants lacking balance sheet depth for pre-revenue investment.
- Legacy node dependency:Trusted foundry requirements lock production at mature geometries, constraining transistor density gains available to mission-critical processors.
Strategic Opportunities
- Hypersonic guidance systems:Thermal management semiconductors for Mach 5+ vehicles represent an unserved specification tier with limited qualified suppliers.
- CHIPS Act fabrication incentives:Domestic foundry construction subsidies are reducing capital recovery periods for radiation-hardened process lines.
- AI-enabled electronic warfare:Convergence of machine learning inference accelerators with software-defined radio architectures opens new payload categories for edge-deployed chips.
Industry Challenges
- Radiation effects engineering talent:Single-event upset modeling expertise concentrates at national laboratories and a handful of defense contractors, constraining design team scaling.
- Obsolescence management complexity:Fifteen-year platform lifecycles force semiconductor suppliers to maintain uneconomic production of discontinued geometries under lifetime buy contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor in Military and Aerospace Market |
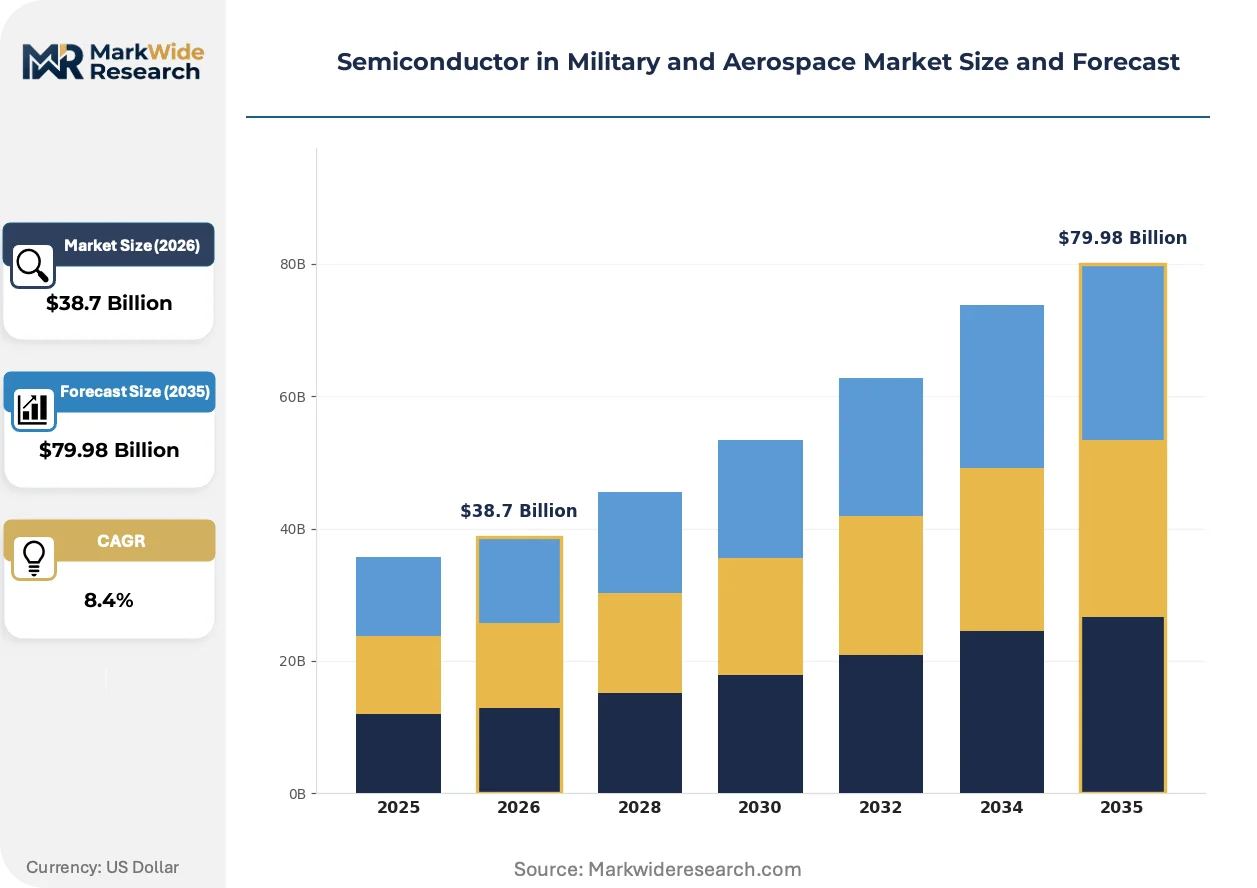
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Microprocessors, Power Management Application: Radar Systems, Communication Equipment, Navigation Systems, Weapon Systems End User: Defense Contractors, Government Agencies, Aerospace Manufacturers, Equipment Suppliers Technology: IC, Discrete, MEMS, RF |
| Companies Covered | Infineon Technologies, BAE Systems, Texas Instruments, Raytheon Technologies, Northrop Grumman, Analog Devices, NXP Semiconductors, Honeywell International, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor in Military and Aerospace Market Strategic Shifts
Digital engineering methodologies are compressing hardware validation cycles while chiplets and advanced packaging are fragmenting traditional monolithic integration strategies across defense platforms.
Software-defined radio architectures are virtualizing analog front-end functions previously implemented in discrete hardware. Navy surface vessels and Army tactical vehicles are fielding these reconfigurable systems at accelerated procurement tempos. This virtualization is collapsing the traditional RF component count per platform while elevating FPGA and ADC content in bill-of-materials structures.
REACH chemical restrictions from ECHA are forcing reformulation of substrate materials and die-attach compounds used in European aerospace programs. Suppliers serving dual-use markets must now maintain parallel material qualification tracks for defense and civilian aviation applications. Component manufacturers are responding by accelerating halogen-free packaging development to unify product lines across regulatory jurisdictions.
Defense primes are consolidating vendor pools through multi-year strategic sourcing agreements that bundle semiconductor procurement with subsystem integration responsibilities. This channel compression is displacing traditional distribution relationships in favor of direct foundry-to-prime contracting models. The shift is most pronounced in United States satellite programs where Space Force acquisition reform emphasizes supply chain traceability over cost competition.
Semiconductor in Military and Aerospace Market Segmentation
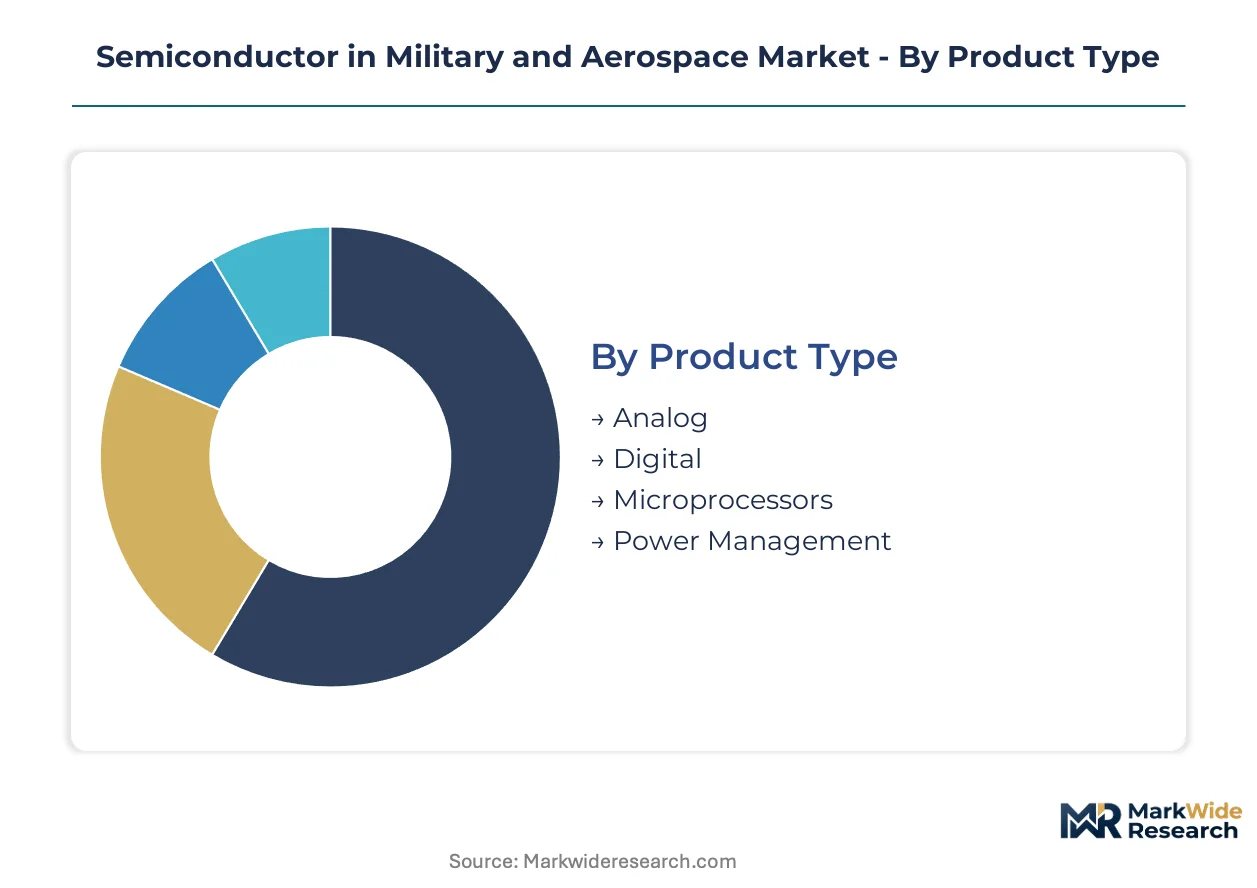
Segmentation in military and aerospace semiconductors reveals how procurement regulations, platform architectures, and qualification barriers reshape supplier economics across distinct technology tiers. Understanding these divisions exposes where capital concentrates and where new entrants face structural exclusion.
Product Type:
Cost tier stratification separates mature analog processes from premium radiation-hardened digital architectures, with foundry economics driving supplier positioning across each node.
- Power Management:Voltage regulators and DC-DC converters engineered for thermal extremes above 125°C. Demand concentrates in satellite payloads and hypersonic vehicles where thermal cycling resilience outweighs transistor density. Pentagon trusted foundry mandates favor domestic suppliers with captive packaging lines.
- Analog:Operational amplifiers, data converters, and interface circuits manufactured on mature nodes with extended temperature ranges. Radar modernization programs in the United States and United Kingdom sustain procurement volumes for precision signal conditioning components.
- Digital:Logic devices and memory components hardened against single-event upsets through redundant cell architectures. Space Force constellation deployments are expanding specification requirements for latch-up immune designs.
- Microprocessors:Edge computing engines for autonomous weapon systems requiring deterministic processing. Autonomous underwater vehicle programs represent emerging demand concentration.
Power Management holds installed capacity. Microprocessors is rotating up the share rankings.
Application:
Application segmentation tracks how electromagnetic spectrum dominance priorities redistribute semiconductor content across platform types, with electronic warfare absorbing disproportionate RF component volumes.
- Radar Systems:Phased array architectures demanding gallium nitride power amplifiers and high-speed ADCs. F-35 and NGAD programs in the United States are specifying active electronically scanned arrays with element-level digital beamforming, elevating FPGA and data converter content per aperture.
- Communication Equipment:Software-defined radios and satellite terminals requiring wideband transceivers with cryptographic acceleration. Army's unified network modernization is consolidating procurement around multi-band, multi-mode waveform processors.
- Navigation Systems:GPS receivers and inertial measurement units with anti-jam capabilities. M-code receiver upgrades are driving demand for radiation-tolerant correlator ASICs.
- Weapon Systems:Guidance processors and fuze electronics for precision munitions. JASSM and LRASM programs specify extended temperature range memory for flight computers.
Radar Systems holds installed capacity. Communication Equipment is rotating up the share rankings.
End User:
Customer type segmentation exposes how procurement authority concentration shapes contracting structures, with prime contractor consolidation compressing traditional distribution channels.
- Defense Contractors:System integrators including Lockheed Martin, Raytheon, and Northrop Grumman with direct foundry relationships. Multi-year strategic sourcing agreements are displacing spot market procurement for radiation-hardened components.
- Government Agencies:Defense Advanced Research Projects Agency and service laboratories funding advanced packaging research. Trusted foundry access programs administered by the Defense Microelectronics Activity gate supplier qualification.
- Aerospace Manufacturers:Boeing, Airbus Defence and Space, and BAE Systems with sovereign fabrication requirements. UK and French programs mandate domestic wafer processing for classified payloads.
- Equipment Suppliers:Tier-2 subsystem vendors supplying antennas, power supplies, and environmental controls. These firms face margin pressure from prime contractor vertical integration into semiconductor procurement.
Defense Contractors holds installed capacity. Government Agencies is rotating up the share rankings.
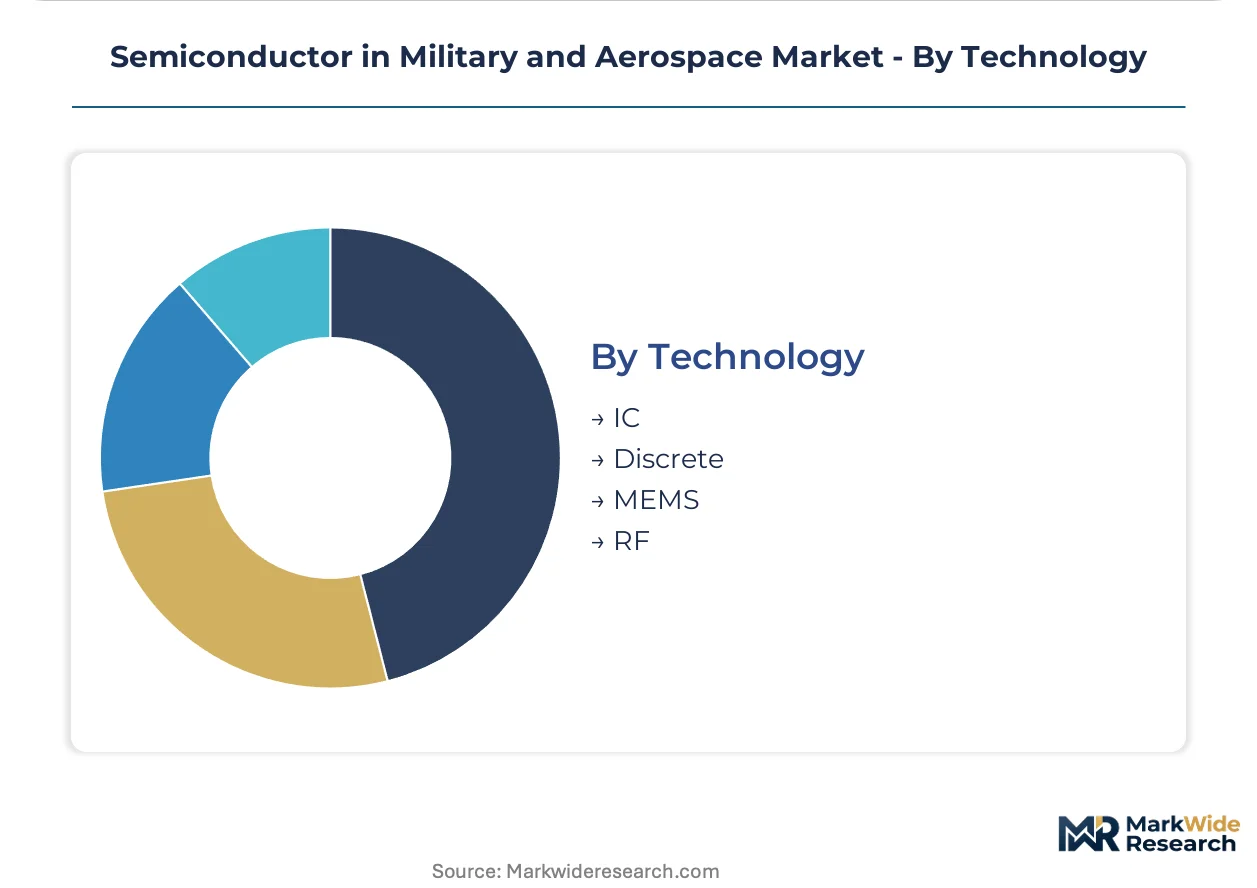
Technology:
Technology segmentation distinguishes between monolithic integration strategies and heterogeneous packaging approaches, with process node maturity determining qualification pathway economics.
- RF:Gallium nitride and gallium arsenide devices for transmit-receive modules and electronic warfare subsystems. Navy's Next Generation Jammer program is specifying GaN MMICs with >100W output power.
- IC:Integrated circuits encompassing both digital and analog functions on single die. Trusted foundry requirements lock production at 65nm and larger geometries for mission-critical processors.
- Discrete:Individual transistors, diodes, and passive components for high-reliability power conversion. Satellite bus power distribution relies on radiation-hardened MOSFETs with enhanced single-event burnout tolerance.
- MEMS:Microelectromechanical systems for inertial sensing and RF switching. Tactical grade accelerometers and gyroscopes enable gun-launched munitions guidance without GPS dependence.
IC holds installed capacity. RF is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across defense procurement systems. The United States prioritizes trusted domestic foundry output for classified payloads, while European programs emphasize sovereign fabrication mandates. Asia-Pacific demand concentrates in indigenous satellite programs and electronic warfare modernization.
United States
The Pentagon's DFARS trusted foundry mandate and CHIPS Act subsidies are accelerating domestic radiation-hardened capacity expansion. Defense Microelectronics Activity administers supplier qualification gates that restrict component sourcing to approved facilities. Arizona and Texas host emerging fabrication clusters where defense primes negotiate direct foundry relationships bypassing traditional distribution channels.
United Kingdom
BAE Systems anchors sovereign aerospace semiconductor demand through captive UK fabrication serving classified payloads. Ministry of Defence procurement regulations mandate domestic wafer processing for strategic systems. Bristol and London corridors concentrate design engineering talent for radiation-effects modeling and mission-critical processor architectures.
Germany
Infineon Technologies leverages its power management portfolio to anchor European defense programs requiring extended temperature range components. ECHA REACH chemical restrictions force reformulation of substrate materials for dual-use aerospace applications. Bavaria and Baden-Württemberg host industrial clusters where automotive semiconductor expertise migrates into defense-qualified packaging lines.
France
Thales and Safran drive procurement of RF gallium nitride devices for radar and electronic warfare subsystems. Direction Générale de l'Armement mandates domestic sourcing for sovereign satellite payloads. Toulouse and Paris-Saclay clusters concentrate aerospace semiconductor design capabilities with strong ties to European Space Agency programs.
Israel
Israel Aerospace Industries and Elbit Systems procure specialized components for autonomous weapon systems and electronic warfare platforms. Ministry of Defense procurement prioritizes indigenous design capabilities for sensitive applications. Haifa and Tel Aviv corridors host dense concentrations of fabless semiconductor firms serving classified defense programs.
Semiconductor in Military and Aerospace Market Competitive Environment
Capability concentration sits with radiation-hardened specialists possessing trusted foundry accreditation; scale advantage sits with diversified analog and power management houses serving dual-use markets. The vendor base stratifies across three tiers: defense primes with captive fabrication, qualified commercial suppliers with defense divisions, and niche radiation-effects engineering boutiques. Dominant competitive moves include strategic sourcing agreements that bundle semiconductor procurement with subsystem integration, and capacity reservation contracts that lock qualified foundry output years ahead of delivery.
Among defense prime contractors with semiconductor capabilities, Raytheon Technologies and Northrop Grumman exemplify the vertical integration archetype, maintaining direct foundry relationships and in-house packaging lines for classified programs. Texas Instruments and Analog Devices represent the qualified commercial supplier tier, leveraging broad analog portfolios to capture radar and avionics platform upgrades while navigating ITAR compliance frameworks. Infineon Technologies and NXP Semiconductors anchor European positioning, with Infineon particularly exemplifying power management specialization for thermal-extreme applications.
| Leading Market Players |
|---|
| Infineon Technologies |
| BAE Systems |
| Texas Instruments |
| Raytheon Technologies |
| Northrop Grumman |
| Analog Devices |
| NXP Semiconductors |
| Honeywell International |
| Microchip Technology |
| Others |
Value Chain & Pricing Dynamics
Long Beach-to-Shanghai freight corridors impose surcharge volatility that compounds with DFARS qualification backlogs to widen price spreads between ITAR-compliant domestic foundries and non-qualified offshore alternatives. Defense primes absorb these logistics premiums through multi-year capacity reservation contracts, while tier-2 equipment suppliers face margin compression from dual sourcing requirements.
Pricing Analysis
Geographic price spreads between Arizona trusted foundries and Asian commercial facilities exceed three-to-one for radiation-hardened microprocessors. Three-tier pricing structure across radiation-hardened, extended-temperature, and commercial-off-the-shelf levels reflects certification grade and lifetime buy guarantees. Cost compression in standard analog tiers is intensifying because automotive semiconductor fabs are repurposing mature nodes for defense orders. Equipment suppliers exhibit highest price sensitivity due to prime contractor vertical integration into component procurement.
Supply Chain Analysis
Silicon carbide substrate supply draws from Japanese and German wafer production, with gallium nitride epitaxy concentrated in United States and South Korean facilities. Raw material dependencies encompass high-purity silicon, specialty gases for ion implantation, and gold wire for die bonding. Single-source vulnerability in silicon carbide wafer supply exposes power semiconductor availability to geopolitical disruption. Distribution runs through defense prime direct foundry contracts that displace traditional component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiation-effects engineering services and obsolescence management contracts are expanding faster than discrete component sales as platform lifecycles stretch past fifteen years. Hardware procurement increasingly bundles with predictive maintenance analytics and lifetime supply guarantees.
For Market Incumbents: Entrench trusted foundry accreditation through captive packaging investments in Texas and Arizona corridors. Lockheed Martin and Raytheon procurement consolidation threatens margin structures for qualified commercial suppliers lacking direct prime relationships. Capacity reservation contracts with Defense Microelectronics Activity gate access provide defensive moats against fabless entrants. For New Entrants and Emerging Players: Build out thermal management semiconductor capabilities for hypersonic vehicle programs where qualified supplier pools remain thin. AI-enabled electronic warfare payload integration represents the most penetrable white space, with software-defined radio architectures collapsing traditional RF component counts. Partner with national laboratories for single-event upset modeling expertise to accelerate qualification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analog houses with underutilized defense divisions and dormant radiation-hardened process lines. Five-to-ten year viability hinges on CHIPS Act subsidy capture and trusted foundry accreditation maintenance. Watch for Defense Microelectronics Activity qualification backlog clearance as inflection signal for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardened Process Line Investment | Defense Microelectronics Activity accreditation unlocks Pentagon procurement for satellite constellation programs. |
| AI-Electronic Warfare Payload Integration | Machine learning inference accelerators converge with software-defined radio architectures at Space Force. |
| Multi-Year Strategic Sourcing Agreement | Direct foundry-to-prime contracting displaces distribution channels for radiation-tolerant components. |
| Obsolescence Management Service Launch | Lifetime buy contracts and predictive analytics extend revenue streams beyond hardware shipment. |
| CHIPS Act Fabrication Subsidy Capture | Arizona and Texas facility construction accelerates capital recovery for trusted process development. |
Study Parameters
Desk research of Defense Microelectronics Activity qualification databases, SEC 10-K filings from defense primes, and CHIPS Act award disclosures preceded structured interviews with radiation-effects engineers, procurement officers at tier-1 system integrators, foundry operations directors, and Defense Advanced Research Projects Agency program managers. Bottom-up triangulation across component-level bill-of-materials analysis and top-down validation against Pentagon budget justification documents anchored volume estimates.
Assumptions held CHIPS Act subsidy disbursement timelines and DFARS trusted foundry mandate enforcement intensity within observed patterns, while varying satellite constellation deployment rates and hypersonic vehicle program acceleration scenarios. Segmentation modeling incorporated product type, application platform, end-user procurement authority, and process node maturity dimensions. CAGRs derived from regression analysis of historical defense procurement cycles and foundry capacity expansion announcements. Single-event upset modeling talent availability and silicon carbide substrate supply elasticity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by commercial automotive semiconductor fabs or sudden relaxation of ITAR export controls would shift outcomes materially. Quarterly review of Defense Microelectronics Activity qualification queue depth and Space Force satellite launch manifests is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Germanium Semiconductor Market
Semiconductors
Smartphone Battery Market
Semiconductors
Resistive RAM Market
Semiconductors
Analog Semiconductor Market
Semiconductors
India Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Semiconductor Target Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Semiconductor IP Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Chiplets Market
Semiconductors
Gaas Wafer Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
Europe Discrete Semiconductor Market