
 Semiconductor IP Market | 2026-2036
Semiconductor IP Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor IP Market Intelligence
Automotive electronics is realigning the Semiconductor IP demand profile as vehicle architectures shift toward zonal computing and software-defined platforms. Synopsys Inc. leverages its broad digital design automation portfolio to anchor relationships with tier-one automotive suppliers. Arm Holdings Ltd. competes through processor core specialization for autonomous compute subsystems. Cadence Design Systems, Inc. differentiates via mixed-signal IP integration tailored to sensor fusion and power management circuits.
Semiconductor IP denotes licensable intellectual property blocks—specifications, circuit layouts, and verification environments—that chip designers integrate into system-on-chip designs rather than developing from scratch. These blocks typically target specific process nodes measured in nanometers and must meet foundry design rule checks for physical manufacturability. Processor cores command the largest revenue share within product type segments due to their ubiquity across computing platforms, while interface IPs expand fastest as data throughput requirements escalate in data centers and 5G infrastructure. Among technology categories, digital IP maintains mature margins, whereas mixed-signal IP captures premium pricing where analog-digital boundary precision determines system performance.
The EU AI Act and REACH framework constrain design choices for AI-accelerator IP sold into European automotive and industrial markets, mandating transparency and material traceability. The US FDA and NHTSA regulate semiconductor reliability in medical devices and safety-critical automotive systems, creating compliance barriers for IP vendors without automotive-grade verification methodologies. China MIIT and GB standards enforce local certification for chips deployed in telecommunications infrastructure, redirecting licensing flows toward domestically qualified IP providers. Stakeholders must monitor how export control expansions and subsidy qualification rules reshape customer eligibility and royalty structures across jurisdictions.
Market Dynamics
The Semiconductor IP market is restructuring around foundry-node concentration, where TSMC's process leadership is compressing design-tool ecosystems and licensing flows into Taiwan-centric supply webs.
Growth Catalysts
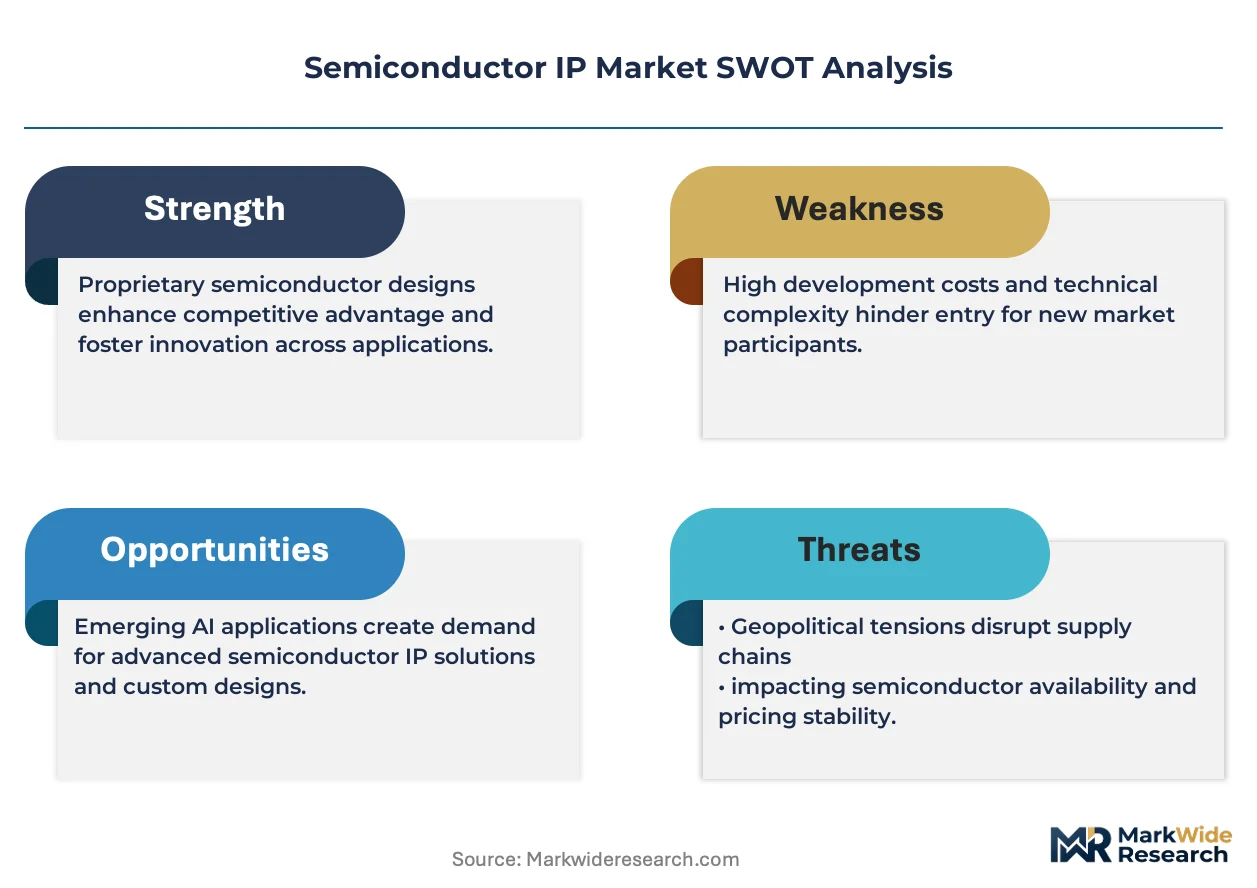
- EU AI Act compliance mandates:European automotive OEMs must source trustworthy AI hardware, creating certified-IP demand for safety-critical autonomous compute subsystems.
- Advanced driver-assistance systems integration:Vehicle architectures are shifting toward zonal computing platforms that require processor cores and sensor-fusion IP blocks.
- 5G infrastructure buildouts:Data throughput escalation in telecom networks is accelerating interface IP licensing for high-speed SerDes and memory controllers.
Market Restraints
- Foundry concentration risk:Advanced-node IP verification depends on TSMC design rule access, creating single-point vulnerability for sub-5nm blocks.
- REACH substance traceability:Material certification requirements for restricted substances add compliance overhead to analog-mixed signal IP development cycles.
- Legacy node cost pressure:Mature-process IP margins compress as foundry capacity allocation favors leading-edge wafers with higher revenue per square centimeter.
Strategic Opportunities
- India PLI scheme incentives:Domestic semiconductor manufacturing subsidies are attracting IP design centers to Bengaluru and Hyderabad ecosystems.
- Chiplets and 3D integration:Die-stacking architectures are creating demand for standardized interconnect IP and thermal-aware design verification environments.
- RISC-V open architecture:Royalty-free processor ecosystems are enabling new entrants to compete in embedded and edge-AI segments without Arm licensing overhead.
Industry Challenges
- Automotive-grade verification timelines:ISO 26262 functional safety certification extends IP development cycles by 18-24 months for ASIL-D rated blocks.
- Analog-digital co-design expertise scarcity:Mixed-signal IP development requires specialized talent pools that concentrate in Taiwan, Israel, and select US metro areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor IP Market |
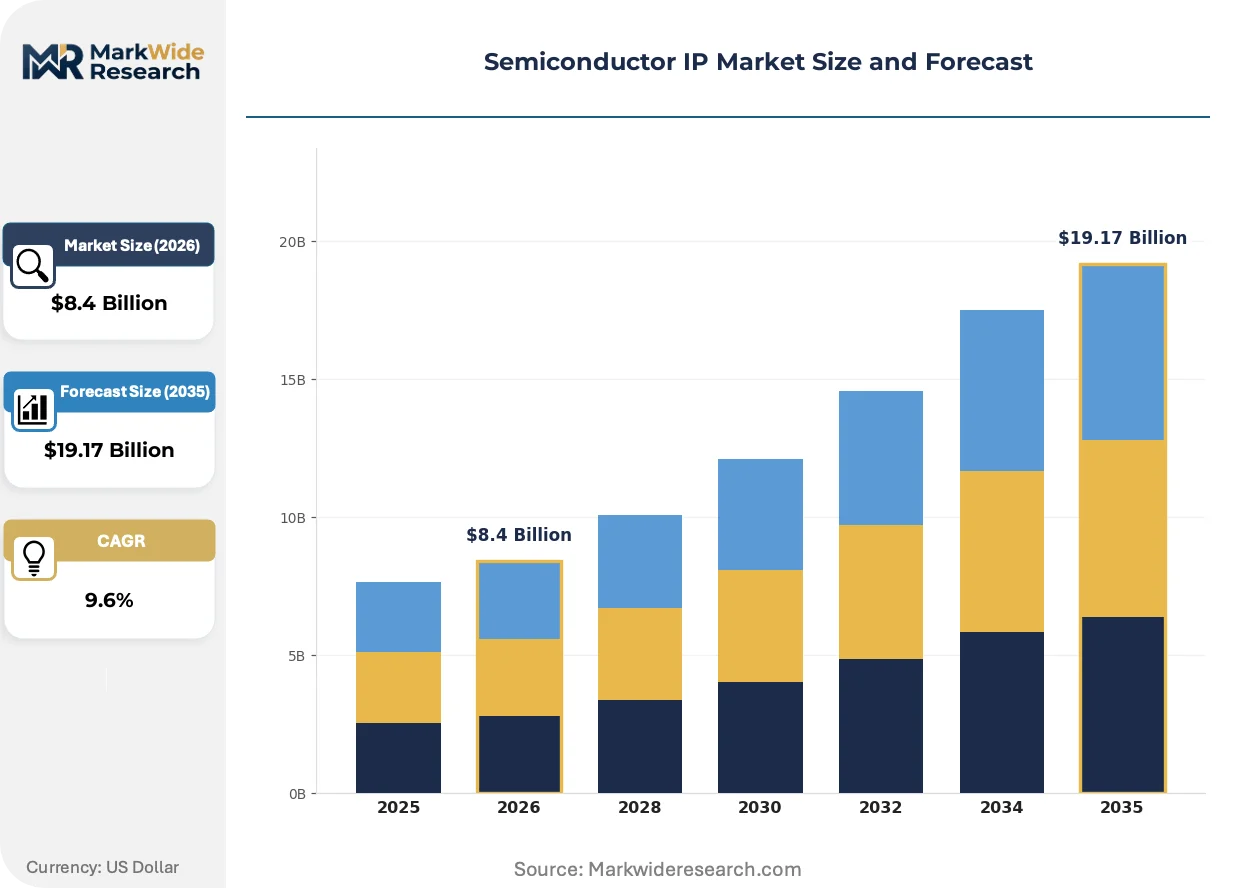
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processor Cores, Interface IPs, Memory Controllers, Analog IPs Technology: Digital IP, Mixed-Signal IP, RF IP, Embedded IP End User: OEMs, Fabless Companies, IDMs, Startups Application: Consumer Electronics, Automotive, Telecommunications, Industrial |
| Companies Covered | Cadence Design Systems, Inc., eMemory Technology Inc., Arm Holdings Ltd., Faraday Technology Corporation, Rambus Inc., Synopsys Inc., Fujitsu Limited, Arteris IP, Imagination Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor IP Market Strategic Shifts & Innovations
Design automation workflows are converging with cloud-native delivery models, compressing how IP vendors distribute verification environments and how foundries synchronize process-design kits.
Chiplets-based disaggregation is consolidating system-on-chip architectures into modular die assemblies. Automotive compute platforms are adopting this approach to mix process nodes within a single package. The structural consequence is that interface IP—die-to-die interconnects and memory PHYs—is consolidating as the critical integration layer between heterogeneous silicon tiles.
REACH and the EU AI Act are tightening substance traceability and algorithmic transparency requirements for IP sold into European automotive and industrial markets. Hardware vendors must document training data provenance and material composition through supply chains. Medical device and autonomous vehicle segments are responding by embedding compliance documentation into IP deliverables as standard contractual terms.
Buyer concentration among hyperscale data center operators and tier-one automotive suppliers is compressing procurement cycles and shifting contract structures toward multi-year platform licenses. Traditional per-use royalty models face displacement by subscription-based access to IP portfolios with foundry-specific optimization guarantees. This pattern is most visible in Taiwan and South Korea, where Samsung and TSMC direct customers are consolidating vendor relationships around integrated design-service partnerships.
Semiconductor IP Market Segmentation
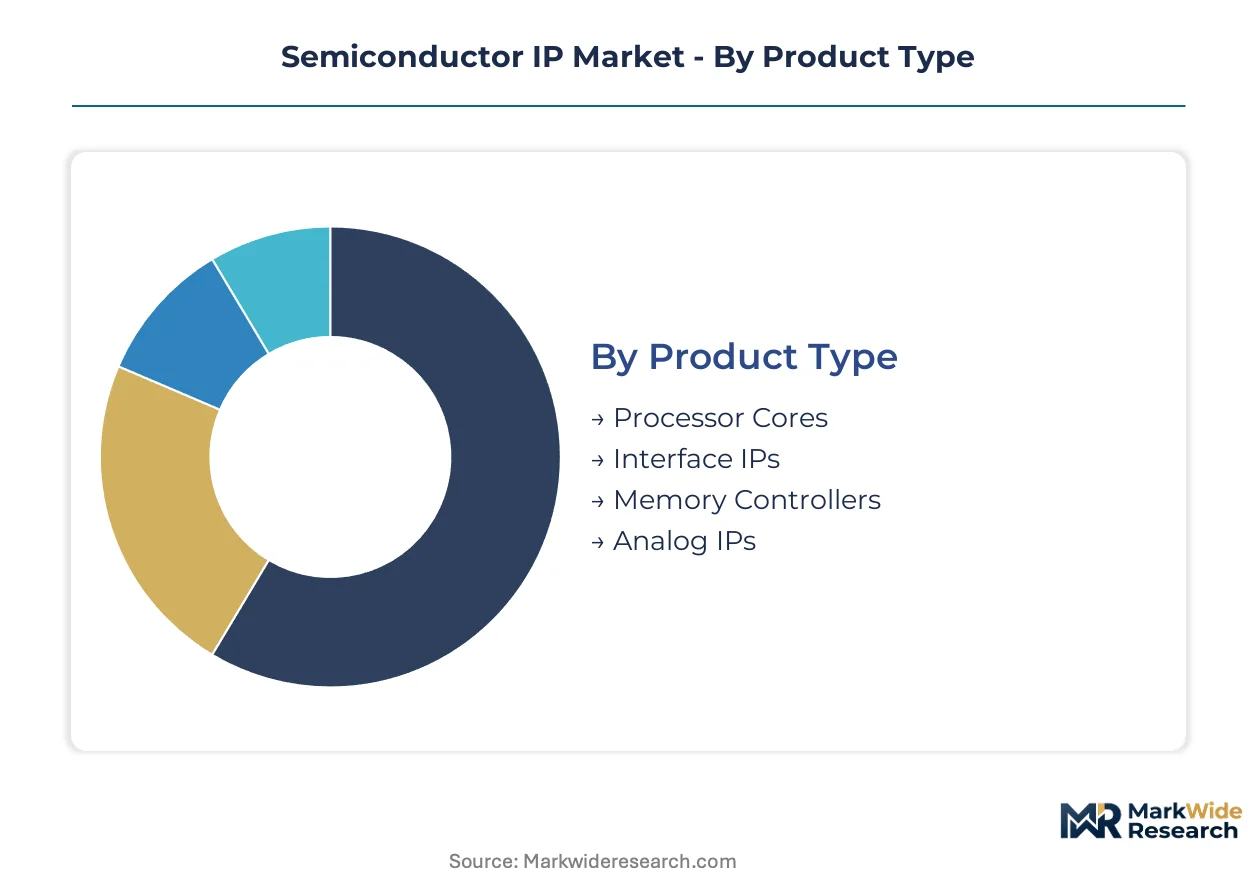
Semiconductor IP purchasing decisions pivot on process-node compatibility, functional safety certification, and foundry design rule alignment. Buyers evaluate IP blocks against specific integration timelines and target application performance thresholds.
Product Type:
Buyers prioritize functional integration density and verification completeness when selecting IP categories.
- Processor Cores:Central processing units and specialized accelerators execute computational workloads across heterogeneous system-on-chip designs. Automotive zonal controllers in Germany and autonomous compute subsystems in California concentrate demand for Arm and RISC-V ISA implementations with ASIL-B through ASIL-D safety ratings.
- Interface IPs:High-speed SerDes, PCIe, and memory PHY blocks manage data movement between dies and external systems. Data center buildouts in Virginia and Singapore drive licensing for 112G SerDes and DDR5 controllers as throughput requirements escalate.
- Memory Controllers:DDR, LPDDR, and HBM interface logic optimizes bandwidth and power for attached memory subsystems.
- Analog IPs:Data converters, PLLs, and power management circuits bridge physical signals to digital domains.
Volume sits with Processor Cores; growth tilts toward Interface IPs.
Technology:
Margin profiles diverge sharply based on analog-digital boundary complexity and foundry node maturity.
- Digital IP:Synthesizable logic blocks scale cleanly across process nodes with automated place-and-route flows. Mature margins prevail in standard cell libraries and datapath components licensed into high-volume consumer SoCs fabricated at TSMC facilities in Hsinchu.
- Mixed-Signal IP:Precision analog-digital interfaces command premium pricing where noise isolation and calibration determine system performance. Automotive radar and lidar front-ends in Stuttgart and Detroit require 16-bit ADCs with sub-LSB linearity guaranteed across temperature extremes.
- RF IP:Transceiver blocks for cellular and Wi-Fi connectivity integrate frequency synthesis and modulation functions.
- Embedded IP:Pre-verified subsystems combine processors, memories, and peripherals for rapid SoC assembly.
Revenue concentrates in Digital IP; premium expansion characterizes Mixed-Signal IP.
End User:
Procurement scale and technical sophistication shape vendor relationship structures.
- OEMs:Vertical integrators like Apple and Samsung source directly to control differentiation and secure supply allocation. Internal IP development teams in Cupertino and Seoul license selectively for foundry-specific optimizations unavailable through merchant vendors.
- Fabless Companies:Design houses without fabrication assets depend entirely on licensed IP to compress development cycles. Qualcomm and NVIDIA in San Diego and Santa Clara maintain broad portfolio agreements with Synopsys and Cadence covering multiple process generations.
- IDMs:Integrated device manufacturers balance captive IP development with external licensing for non-core functions.
- Startups:Capital-constrained entrants leverage RISC-V and open-source ecosystems to avoid upfront royalty burdens.
Transaction volume flows through Fabless Companies; platform consolidation targets OEMs.
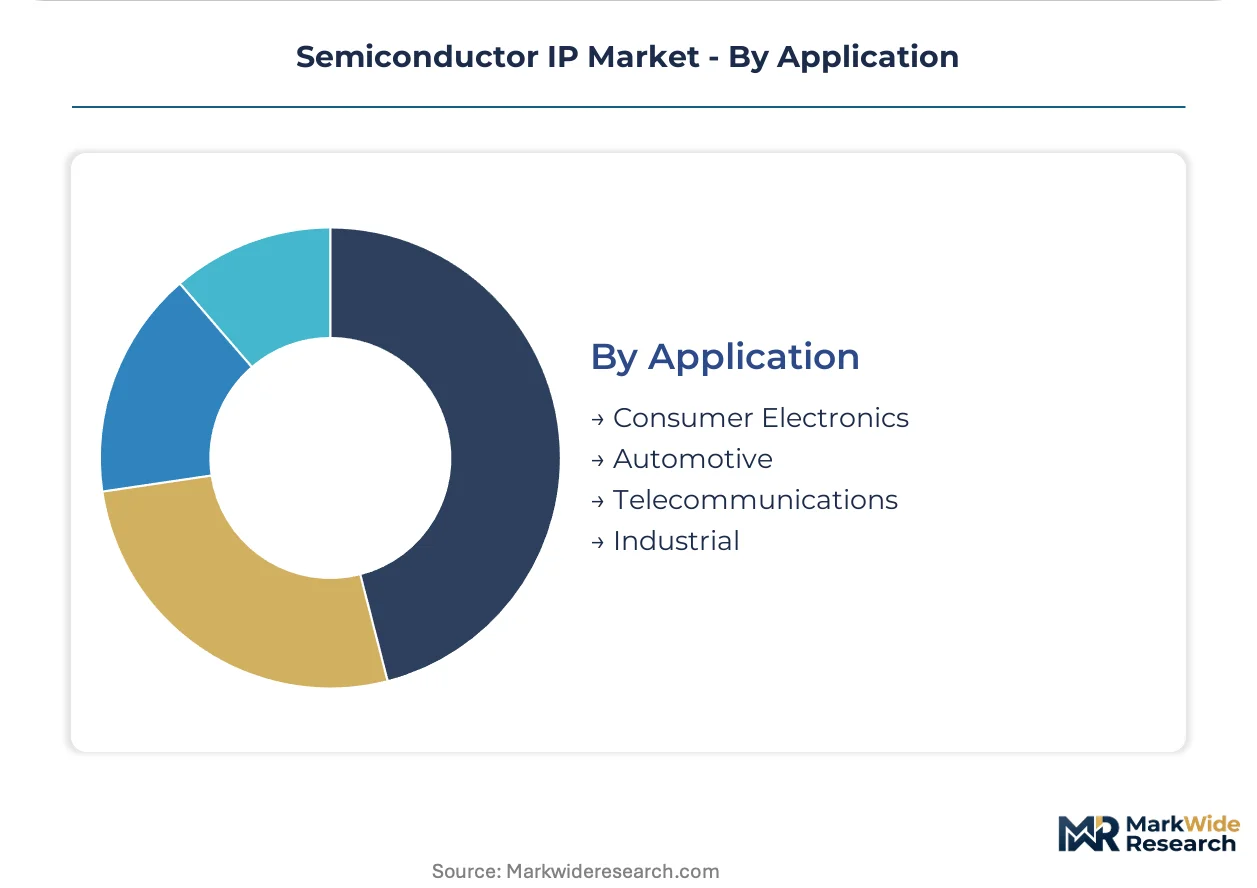
Application:
Certification requirements and reliability specifications segment demand by vertical.
- Automotive:Functional safety mandates under ISO 26262 and cybersecurity provisions in UN R155 reshape IP verification deliverables. Tier-one suppliers in Wolfsburg and Toyota City require fault-tolerant processor cores with documented failure modes and diagnostic coverage metrics.
- Telecommunications:5G baseband and infrastructure silicon demands low-latency datapaths and advanced error correction. Huawei and ZTE in Shenzhen license interface IP for massive MIMO arrays deployed under MIIT certification frameworks.
- Consumer Electronics:Mobile handsets and wearables prioritize power efficiency and area optimization.
- Industrial:Factory automation and energy systems require extended temperature operation and long-term supply guarantees.
Automotive commands the steepest expansion trajectory; Consumer Electronics maintains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Taiwan and South Korea where foundry ecosystems dominate advanced-node manufacturing, while design activity clusters in the United States, China, and Germany where automotive and data center demand pull IP licensing flows.
United States
Hyperscale data center operators in Virginia and autonomous vehicle developers in California drive demand for high-speed SerDes and safety-certified processor cores. NHTSA regulations mandate functional safety documentation for automotive IP deployed in ADAS platforms. The San Francisco Bay Area hosts design-service partnerships linking fabless companies to TSMC process nodes.
Taiwan
TSMC's foundry leadership compresses IP verification cycles and licensing negotiations into Hsinchu-centered supply webs. The country's national semiconductor regulator enforces local certification standards for chips in telecommunications infrastructure. Taipei-based design houses coordinate directly with foundry process development teams for sub-5nm optimization.
China
Domestic 5G baseband and AI accelerator development in Shenzhen accelerates interface IP licensing under MIIT certification frameworks. GB standards enforce traceability requirements for restricted substances in analog-mixed signal blocks. Shanghai design clusters cultivate RISC-V ecosystems to reduce Arm licensing dependencies.
Germany
Automotive OEMs in Stuttgart and Wolfsburg source ASIL-D rated processor cores for zonal computing architectures. The EU AI Act mandates trustworthy AI hardware documentation for autonomous subsystems sold into European markets. Bavarian semiconductor design centers specialize in radar and lidar front-end mixed-signal IP.
South Korea
Samsung's foundry operations and memory dominance in Suwon drive HBM controller and DDR5 PHY licensing for data center and mobile applications. The country's national technology regulator enforces local standards for chips in consumer electronics and telecommunications. Seoul-based design houses integrate IP portfolios across logic and memory process nodes.
Semiconductor IP Market Key Industry Players
Top-tier vendors anchor comprehensive design automation portfolios, while specialized core providers occupy niche positions in processor architectures and memory interfaces. The vendor base stratifies across three tiers: integrated design-platform providers, focused IP specialists, and open-source ecosystem enablers. Two strategic archetypes dominate competitive positioning: full-stack automation vendors bundling IP with EDA tools, and pure-play IP licensors betting on architectural specialization. M&A activity concentrates on acquiring functional safety certification capabilities and automotive-grade verification methodologies.
Within the integrated-platform tier, Synopsys Inc. and Cadence Design Systems, Inc. exemplify vendors bundling IP portfolios with design automation software. Arm Holdings Ltd. occupies a distinct position as an architecture licensor spanning processor cores through system-level IP. These three entities represent contrasting approaches to customer capture—tool-driven platform bundling versus royalty-based architectural licensing.
| Leading Market Players |
|---|
| Cadence Design Systems, Inc. |
| eMemory Technology Inc. |
| Arm Holdings Ltd. |
| Faraday Technology Corporation |
| Rambus Inc. |
| Synopsys Inc. |
| Fujitsu Limited |
| Arteris IP |
| Imagination Technologies |
| Others |
Cost & Logistics Intelligence
Captive integration into TSMC's advanced-node ecosystem anchors both supply security and pricing power for Semiconductor IP vendors, as foundry-specific verification access determines which blocks command premium positioning in automotive and data center procurement cycles.
Pricing Analysis
Short lead-time premiums dominate Semiconductor IP contracting, with automotive OEMs in Stuttgart and Wolfsburg paying substantial markups for ASIL-D certified blocks delivered under 18-month ISO 26262 verification timelines. The market operates on hybrid licensing combining per-use royalties with multi-year platform subscriptions, where pricing stratifies across automotive-grade, industrial-grade, and consumer-grade certification tiers. Cost compression in mature-node digital IP intensifies as foundry capacity allocation favors leading-edge wafers, squeezing margins for standard cell libraries. Fabless companies exhibit highest price sensitivity due to capital constraints, while tier-one automotive suppliers prioritize certification completeness over unit economics.
Supply Chain Analysis
Reverse-logistics flows for IP verification environments center on cloud-native redistribution models, with design kits and process-design kits cycling between foundry partners and customer engineering teams for iterative refinement. Supply concentrates in Taiwan, South Korea, and the United States, where TSMC's Hsinchu facilities, Samsung's Suwon operations, and EDA tool development in California form interdependent production nodes. Raw material dependencies span silicon wafer substrates, photomask fabrication services, and specialized EDA software licenses. Single-source vulnerability pervades sub-5nm IP verification, where TSMC design rule access creates irreplaceable bottlenecks. Distribution runs through direct foundry partnerships and design-service integrators, with procurement cycles compressing as hyperscale buyers consolidate vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor IP supply is tightening around TSMC's advanced-node allocation, with foundry capacity scarcity propping pricing power for verified blocks in automotive and data center segments.
For Market Incumbents: To counter RISC-V ecosystem encroachment in embedded and edge-AI segments, Arm Holdings and Synopsys should deepen automotive-grade verification capabilities through ISO 26262 ASIL-D certification investments, while securing exclusive foundry process-design kit access in Taiwan to lock out emerging competitors. Channel control through integrated design-service partnerships represents the priority defensive lever. For New Entrants and Emerging Players: Capture white-space in India PLI scheme subsidized design centers around Bengaluru and Hyderabad, where domestic semiconductor manufacturing incentives attract engineering talent without legacy royalty burdens. The most penetrable segment spans RISC-V processor implementations for industrial automation and medical devices, with go-to-market anchored through open-source community engagement and foundry-agnostic verification guarantees. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated EDA platform vendors seeking automotive functional safety capabilities. Long-term viability hinges on 5-10 year foundry-node roadmap alignment, with acquisition targets clustering around mixed-signal IP specialists possessing analog-digital co-design expertise. The signal to watch is MIIT certification acceleration in China, which would redirect licensing flows toward domestically qualified providers and strain Arm's market position.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Functional Safety Certification | ISO 26262 ASIL-D ratings unlock tier-one OEM procurement at BMW and Toyota. |
| Foundry-Specific Process Optimization | TSMC sub-5nm design rule access secures exclusive positioning in advanced-node IP. |
| RISC-V Architecture Investment | Royalty-free ecosystems enable cost-competitive entry into embedded compute segments. |
| Chiplet Interconnect Standardization | UCIe-compliant die-to-die IP captures modular disaggregation demand from AMD and Intel. |
| India Design Center Expansion | PLI scheme subsidies in Bengaluru reduce engineering costs for verification teams. |
Research Approach
Document review covered SEC 10-K filings from Synopsys and Cadence, EU AI Act regulatory texts, and MIIT certification frameworks, complemented by interviews with fabless company CTOs, tier-one automotive supplier procurement directors, TSMC foundry account managers, and EDA platform engineers. Secondary validation drew from foundry process roadmaps, ISO 26262 auditor disclosures, and hyperscaler data center capex announcements. Bottom-up segment sizing triangulated against top-down semiconductor industry production forecasts.
Cross-referencing historical licensing velocity against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology category, end-user archetype, and application vertical with foundry-node specificity. CAGRs derived from regression analysis of IP royalty disclosures and foundry wafer pricing trends, with automotive electronics adoption curves and 5G infrastructure deployment schedules as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export control expansions, REACH substance restriction amendments, and TSMC capacity allocation shifts. Forecasts reflect assumptions regarding foundry-node transition timelines and regulatory certification harmonization across jurisdictions. Material deviation in EU AI Act enforcement stringency or China MIIT localization mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Discrete Semiconductor Market
Semiconductors
Gaas Wafer Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Smartphone Battery Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Global Computer Microchip Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
India Semiconductor Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
China Semiconductor Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Global FD-SOI Wafers Market