
 Global Non Alcoholic Concentrated Syrup Market | 2026-2036
Global Non Alcoholic Concentrated Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non Alcoholic Concentrated Syrup Market Intelligence
Direct-to-foodservice channel sales, particularly to cafes and restaurant chains, is reconfiguring the margin landscape traditionally dominated by retail distribution. Monin specializes in the professional channel, supplying a vast portfolio of flavors for custom beverages. The Coca-Cola Company leverages its extensive distribution network to serve both retail and foodservice segments globally. In contrast, Rasna Private Limited anchors its strategy in the high-volume retail concentrate market in India.
Non-alcoholic concentrated syrup is a viscous liquid formulation of sugar, water, and flavorings, characterized by a high Brix value for shelf stability. Its primary commercial purpose is to serve as a base for dilution into finished beverages like sodas, juices, and flavored waters in foodservice and retail. Fruit-based syrups command the largest share, driven by their versatility in beverage manufacturing. The herbal and spicy flavor profiles represent a high-growth niche, aligning with consumer interest in novel and wellness-oriented drinks.
Product formulation and market access are shaped by food safety regulations from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). In India, standards from the Food Safety and Standards Authority of India (FSSAI) govern permissible additives and nutritional labeling. Future competitive advantage depends on navigating evolving health preferences and the patchwork of international sugar taxation policies.
Market Dynamics
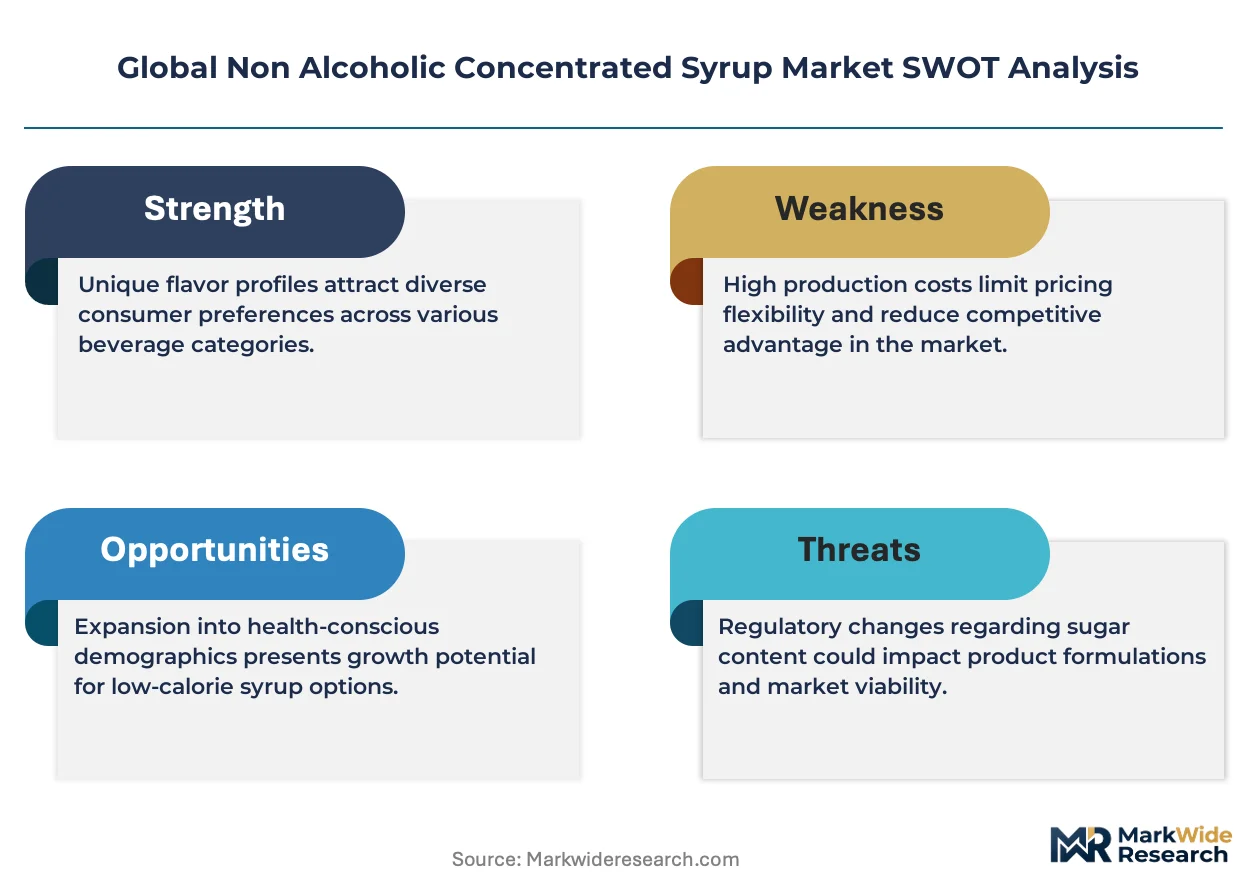
The non-alcoholic concentrated syrup market is shaped by the dual pressures of health-conscious consumerism and foodservice demand for operational efficiency. Regulatory frameworks like the US FDA's updated labeling are pushing for cleaner ingredients, while cafes and restaurants prioritize flavor diversity and ease of use.
Growth Catalysts
- Foodservice Channel Expansion:Demand from cafes, bars, and restaurant chains for a wide portfolio of flavors to create customized sodas, mocktails, and flavored coffees is a primary catalyst for market expansion.
- Convenience in Emerging Economies:In markets like India, strong consumer preference for affordable and easy-to-prepare beverage mixes for at-home consumption drives high-volume sales in the retail segment.
- Clean Label Formulations:Stricter nutritional labeling requirements from bodies like the FDA and EFSA encourage the use of natural sweeteners, fruit extracts, and plant-based ingredients, appealing to health-aware consumers.
Market Restraints
- Input Price Volatility:Fluctuations in the prices of key raw materials, especially sugar and natural fruit pulp, directly impact production costs and create margin pressure for manufacturers.
- Divergent Sugar Taxation:The lack of a harmonized global approach to sugar taxes forces producers to manage multiple product formulations and pricing strategies for different countries, increasing operational complexity.
- Substitution from RTD Beverages:The growing market for ready-to-drink (RTD) teas, coffees, and functional beverages presents a significant substitution threat, offering convenience that eliminates the need for dilution.
Strategic Opportunities
- Functional and Wellness Ingredients:Incorporating functional ingredients such as vitamins, botanicals, and adaptogens into syrup formulations can attract consumers seeking health benefits beyond simple flavoring.
- Herbal and Spice Flavor Innovation:Developing complex, sophisticated flavor profiles using herbs and spices like ginger, cardamom, and lavender caters to the growing consumer interest in novel and premium beverage experiences.
- Direct-to-Consumer (D2C) Channels:Establishing e-commerce platforms enables brands to sell artisanal and niche flavor syrups directly to home consumers, bypassing the competitive and crowded retail shelf space.
Industry Challenges
- Cold Chain Management:Maintaining the integrity of syrups made with natural fruit purees and no artificial preservatives requires robust and costly cold chain logistics to prevent spoilage and ensure shelf stability.
- Regulatory Compliance Burden:Navigating the intricate and varied food safety standards for additives, allergens, and labeling across jurisdictions, such as FSSAI in India and EFSA in Europe, poses a continuous compliance challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non Alcoholic Concentrated Syrup Market |
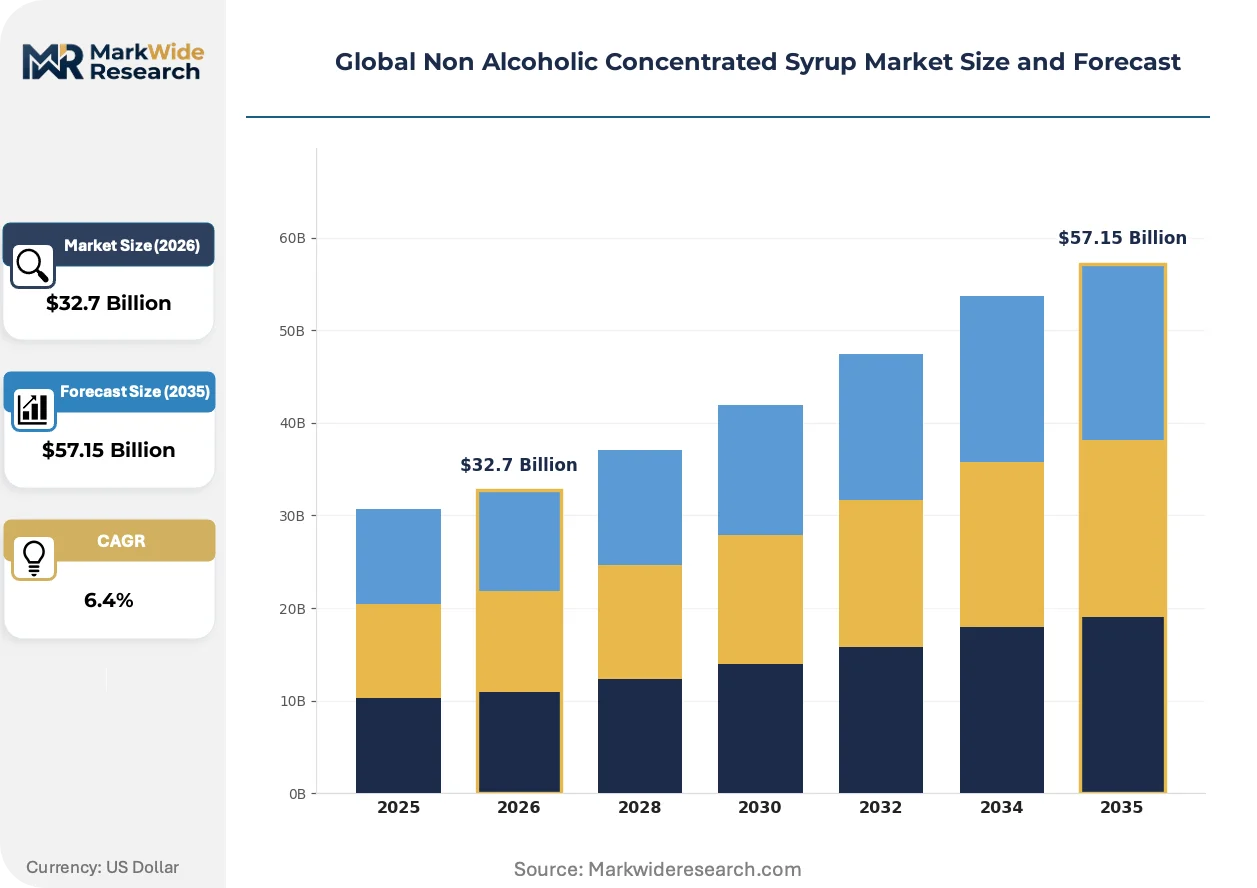
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $57.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit-Based, Herbal, Vanilla, Chocolate End User: Restaurants, Cafes, Beverage Manufacturers, Retail Outlets Distribution Channel: Online, Supermarkets, Wholesale, Convenience Stores Flavor Profile: Sweet, Tangy, Spicy, Savory |
| Companies Covered | Pioma Industries Pvt. Ltd, The Coca-Cola Company, Britvic Plc, Suntory Holdings Ltd., Unilever, Rasna Private Limited, Monin, Tru Blu Beverages, Golden Circle Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non Alcoholic Concentrated Syrup Market Strategic Shifts & Innovations
Product development is pivoting toward naturalness and functional benefits, moving beyond traditional sweet flavorings. This evolution is a direct response to both regulatory pressures on sugar and a consumer base that is increasingly sophisticated in its taste preferences and health expectations.
Advanced extraction methods are becoming central to creating authentic flavor profiles. Technologies like supercritical fluid extraction and cold-press techniques allow for the capture of delicate aromatic compounds from fruits, herbs, and spices. Premium syrup formulators targeting high-end foodservice clients and discerning consumers are the primary adopters of these processes. The market's value proposition is migrating from simple sweetening to delivering complex, natural, and authentic taste experiences in a concentrated format.
European Food Safety Authority (EFSA) regulations on food additives are influencing product composition. The agency's ongoing re-evaluation of certain artificial colorants and preservatives is compelling manufacturers to seek natural alternatives to maintain access to the European market. This shift particularly affects the fruit-flavored syrup segment, which has historically relied on synthetic colors for visual appeal, now turning to plant-based colorants derived from sources like beets and spirulina.
Consumer purchasing behavior is shifting toward curated, experience-driven buying through direct-to-consumer (D2C) models. The rise of subscription boxes and online flavor kits is disrupting the traditional retail channel, which often prioritizes high-volume, mainstream products. This trend is most pronounced in North American and European markets, where at-home mixology and personalized soda creation are gaining popularity among hobbyists and families.
Global Non Alcoholic Concentrated Syrup Market Segmentation
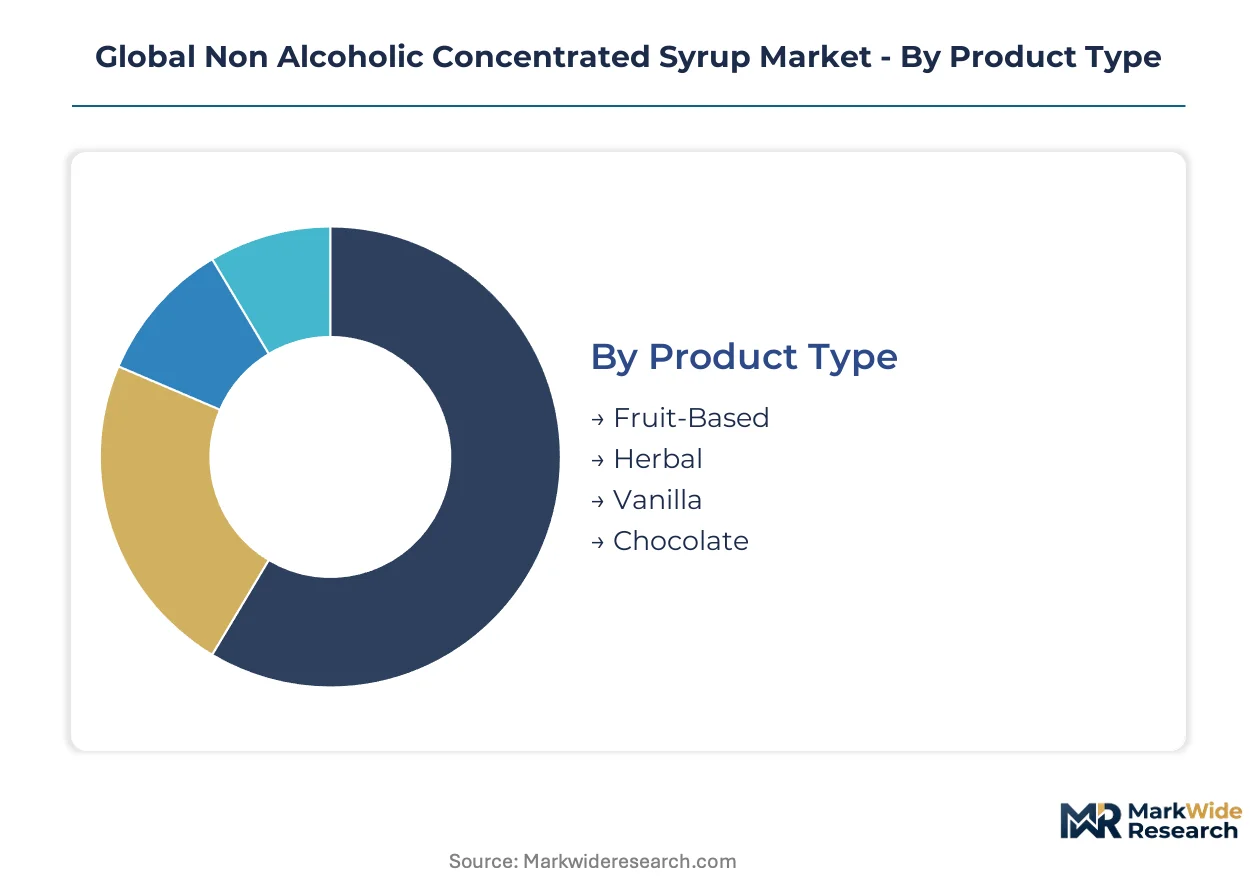
Market segmentation provides a critical framework for understanding the diverse demands and operational requirements within the non-alcoholic concentrated syrup industry. This granular analysis allows manufacturers to tailor product formulations, distribution strategies, and marketing efforts to specific customer needs and consumption patterns.
Product Type:
Product type segmentation highlights the varying levels of post-purchase support and formulation guidance required by customers, especially for complex or specialized flavor profiles.
- Fruit-Based:These syrups are typically made from fruit juices, purees, or extracts, often combined with sugar and water, and are highly versatile. Demand concentrates in both foodservice for customized beverages and in retail for at-home drink preparation across global markets.
- Herbal:Formulations incorporate botanical extracts and natural herbs, offering unique and often wellness-oriented flavor experiences with functional appeal. This segment sees significant demand from health-conscious consumers and high-end cafes seeking novel beverage ingredients in North America and Europe.
- Vanilla:This classic flavor profile is a staple, providing a sweet and aromatic base for coffees, desserts, and cocktails. Vanilla syrups maintain consistent demand across all end-user segments.
- Chocolate:Offering a rich and indulgent taste, chocolate syrups are popular for coffee drinks, milkshakes, and dessert applications. Cafes and restaurants widely use chocolate syrups for specialty beverages.
By volume, Fruit-Based syrups lead the market. By growth pace, Herbal formulations are expanding most quickly.
End User:
End user segmentation reflects the distinct operational demands and beverage preparation complexities across different commercial settings.
- Restaurants:These establishments require a broad range of flavors to create diverse beverage menus, from mocktails to flavored lemonades, often prioritizing ease of use and consistent quality. Demand is strong for versatile fruit and spice profiles to complement various cuisines.
- Cafes:Specializing in coffee, tea, and specialty drinks, cafes demand syrups that blend seamlessly with hot and cold beverages, focusing on authentic taste and premium ingredients. Customization options for patrons drive significant syrup usage in urban centers.
- Beverage Manufacturers:Large-scale producers utilize concentrated syrups as base ingredients for mass-produced sodas, juices, and flavored waters. These manufacturers prioritize cost-effectiveness and consistent ingredient specifications.
- Retail Outlets:This segment includes supermarkets and convenience stores selling syrups directly to consumers for home consumption. Retail outlets focus on popular flavors and convenient packaging for everyday use.
Foodservice establishments collectively drive significant volume, while beverage manufacturers seek consistency for large-scale production.
Distribution Channel:
Distribution channel analysis reveals how market access and consumer engagement strategies vary significantly across different sales platforms.
- Online:E-commerce platforms facilitate direct-to-consumer sales, enabling brands to reach niche markets and offer a wider selection of artisanal and specialty flavors. This channel is expanding rapidly in North America and Europe for at-home mixology enthusiasts.
- Supermarkets:These large retail chains provide broad consumer access to a variety of mainstream and premium syrup brands, catering to family consumption and everyday needs. Supermarkets are a primary channel for high-volume sales in India and other emerging economies.
- Wholesale:Wholesalers supply bulk quantities of syrups to foodservice distributors, restaurants, and cafes. This channel emphasizes competitive pricing and efficient logistics.
- Convenience Stores:These smaller retail formats offer quick access to popular syrup flavors, often catering to impulse purchases and immediate consumption needs. Convenience stores serve local communities effectively.
Online platforms are gaining share due to direct consumer engagement, while traditional retail channels maintain broad accessibility.
Flavor Profile:
Flavor profile segmentation illustrates the evolving consumer preferences for taste experiences, moving beyond traditional sweetness to more nuanced options.
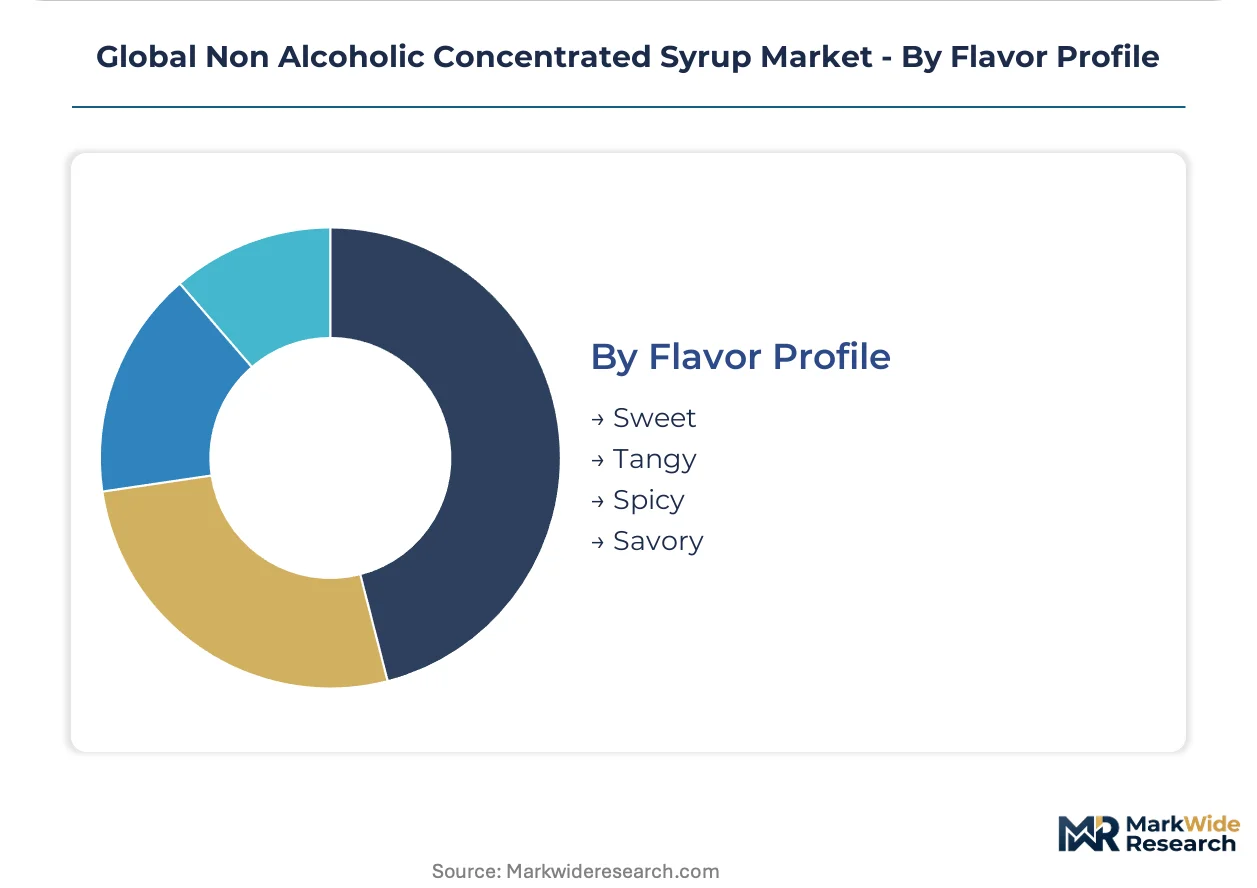
- Sweet:This profile encompasses traditional sugary flavors like fruit, vanilla, and caramel, forming the foundation of many popular beverages. Sweet syrups consistently appeal to a broad consumer base across all age groups.
- Spicy:Incorporating ingredients like ginger, chili, or cinnamon, spicy profiles offer a bold and adventurous taste experience, often used in mocktails and specialty drinks. This niche is gaining traction among adventurous consumers in urban markets.
- Tangy:Characterized by tart or sour notes, tangy syrups often feature citrus fruits or berries, providing a refreshing and zesty flavor. Tangy options are popular in summer beverages and functional drinks.
- Savory:Less common but emerging, savory profiles might include herbal or vegetable notes, offering unique culinary applications beyond traditional beverages. Savory syrups appeal to innovative chefs and mixologists.
Sweet profiles maintain foundational demand, but Spicy and Tangy options are capturing new consumer interest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The non-alcoholic concentrated syrup market exhibits varying demand elasticity across geographies. Consumers in emerging economies prioritize affordability and convenience, while developed markets show less price sensitivity for premium, health-oriented formulations. This divergence shapes regional product development and distribution strategies for manufacturers.
India
Demand for concentrated syrups in India is strong for affordable and easy-to-prepare beverage mixes. The Food Safety and Standards Authority of India (FSSAI) governs permissible additives and nutritional labeling for these products. Urban centers like Mumbai and Delhi see high-volume retail sales for at-home consumption.
United States
The United States market drives demand for clean label formulations and customized beverage options in foodservice. The US Food and Drug Administration (FDA) updated nutritional labeling requirements, pushing for natural ingredients. Major cities like New York and Los Angeles exhibit high demand for diverse flavor portfolios in cafes and restaurants.
Germany
Germany demonstrates a preference for natural ingredients and sophisticated flavor profiles in non-alcoholic syrups. European Food Safety Authority (EFSA) regulations influence product composition, compelling manufacturers to use natural colorants. Berlin's vibrant cafe scene and Munich's gourmet food sector foster innovation in herbal and spicy syrup offerings.
Canada
Canadian consumers seek health-conscious beverage options and increasingly engage in at-home mixology. Health Canada's food regulations guide ingredient approval and labeling for concentrated syrups. Toronto and Vancouver show a rising trend in direct-to-consumer sales for artisanal and niche flavor syrups.
Global Non Alcoholic Concentrated Syrup Market Key Industry Players
Global professional channel specialists and high-volume retail players split the non-alcoholic concentrated syrup market, creating a tiered competitive structure. This landscape features multinational beverage giants, specialized flavor houses, and regional concentrate manufacturers, each vying for distinct customer segments. Companies pursue portfolio diversification to meet evolving consumer preferences, particularly for natural and functional ingredients. Distribution network expansion remains a primary competitive move, alongside strategic partnerships to broaden market access and foster product innovation.
Within the market, Monin exemplifies a professional channel specialist, focusing on a vast portfolio of flavors for custom beverages in cafes and restaurants. This approach prioritizes product quality and variety for experienced mixologists and baristas. The Coca-Cola Company, a global entity, represents a market player leveraging an extensive distribution network to serve both retail and foodservice segments with established brands. Rasna Private Limited, an India-based company, anchors the high-volume retail concentrate market, catering to at-home consumption with affordable options and convenient packaging. These distinct strategies highlight the varied approaches for market penetration, with some prioritizing niche high-margin foodservice and others focusing on broad retail accessibility. This segmentation of strategies dictates product development and distribution investments, reflecting diverse customer needs.
| Leading Market Players |
|---|
| Pioma Industries Pvt. Ltd |
| The Coca-Cola Company |
| Britvic Plc |
| Suntory Holdings Ltd. |
| Unilever |
| Rasna Private Limited |
| Monin |
| Tru Blu Beverages |
| Golden Circle Ltd. |
| Others |
Cost & Logistics Intelligence
Global shipping routes face cost dynamics that directly influence both supply concentration and downstream price differentiation in the non-alcoholic concentrated syrup market. Freight expenses for bulk ingredients like sugar and fruit pulp impact manufacturing locations and subsequently, regional product pricing.
Pricing Analysis
Custom flavor development services drive significant lifetime value for syrup manufacturers in the foodservice segment. The dominant pricing model incorporates contract-based long-term offtake agreements for consistent supply to large chains. Price differentiation stems from ingredient quality grade and the level of customization offered to clients. Pricing pressure stems from input price volatility, particularly for sugar and natural fruit pulp. Retail consumers in emerging economies like India exhibit the highest price sensitivity, favoring affordable, high-volume concentrates.
Supply Chain Analysis
Input price volatility for key raw materials like sugar and natural fruit pulp represents a structural supply chain risk. Geographic supply concentration for these ingredients draws from major agricultural producers globally, with specific botanical extracts sourced from diverse regions. India serves as a significant hub for high-volume retail concentrate production, while Europe and North America focus on premium ingredient sourcing. Distribution runs through established wholesale networks for foodservice and broad retail channels for consumer products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a fragmentation opportunity, driven by evolving consumer demand for customized and wellness-oriented beverage experiences that create distinct niche segments.
For Market Incumbents:
Pre-empt the threat of substitution from ready-to-drink beverages by investing heavily in R&D for functional ingredients. Consolidate market share through strategic partnerships with specialized flavor houses to expand premium, natural flavor portfolios. Leverage existing extensive distribution networks to push innovative clean label formulations into new foodservice accounts and urban retail outlets.
For New Entrants and Emerging Players:
Build out direct-to-consumer (D2C) e-commerce platforms to bypass crowded traditional retail shelves. Target the underpenetrated market for artisanal, herbal, and spicy flavor profiles, particularly in North American and European urban centers. A strong go-to-market angle involves offering curated flavor kits and subscription boxes that cater to at-home mixology enthusiasts and health-conscious consumers.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors mid-cap specialists in advanced extraction methods and natural ingredient formulation. The long-term viability of the market (5-10 year window) supports investment in companies with strong intellectual property in flavor science. Acquisition targets should include firms with robust portfolios of plant-based colorants and functional botanical extracts. The signal to watch is an increase in M&A activity focused on companies excelling in wellness-oriented beverage components.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Natural Sweeteners R&D | This initiative mitigates regulatory risks from sugar taxation and aligns with health-conscious consumer preferences. |
| Expand Direct-to-Consumer Channels | This move allows brands to reach niche markets and offer specialized artisanal flavor syrups directly. |
| Form Strategic Partnerships with Cafes | These partnerships secure consistent demand for customized beverage options in the high-growth foodservice segment. |
| Develop Herbal and Spicy Flavor Lines | This innovation captures new consumer interest in novel and wellness-oriented beverage experiences. |
| Optimize Cold Chain Logistics | This optimization ensures the integrity and shelf stability of natural fruit puree-based syrups without artificial preservatives. |
Research Approach
Desk research of regulatory body publications, industry trade reports, and company annual filings preceded structured interviews with R&D directors, procurement managers, cafe owners, and regulatory officials. This approach combined primary insights with secondary validation to triangulate market dynamics from both bottom-up and top-down perspectives.
The forecast framework held macroeconomic conditions and established regulatory pathways fixed, while varying consumer preference shifts and raw material supply chain resilience across the analysis window. Segmentation dimensions modeled included product type, end-user, distribution channel, flavor profile, and regional regulatory compliance. Compound annual growth rates were derived from historical data extrapolation and expert consensus, incorporating raw material price indices and foodservice sector growth rates as key inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational beverage giants or specialized flavor houses would shift outcomes. These forecasts reflect assumptions regarding regulatory stability and consumer trends, but unforeseen regulatory changes or major supply chain disruptions could alter projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Coffee Substitute Market