
 Non-Alcoholic Wine and Beer Market | 2026-2036
Non-Alcoholic Wine and Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Wine and Beer Market Analysis
The EU's updated alcohol labeling requirements under EFSA guidance is hardening standards for what products qualify as non-alcoholic across European markets. Heineken N.V. leverages its global brewing infrastructure to distribute alcohol-free variants at scale. Athletic Brewing Company specializes in craft-oriented non-alcoholic beer, targeting performance-focused drinkers. Anheuser-Busch InBev anchors mass-market penetration through supermarket and convenience store placements.
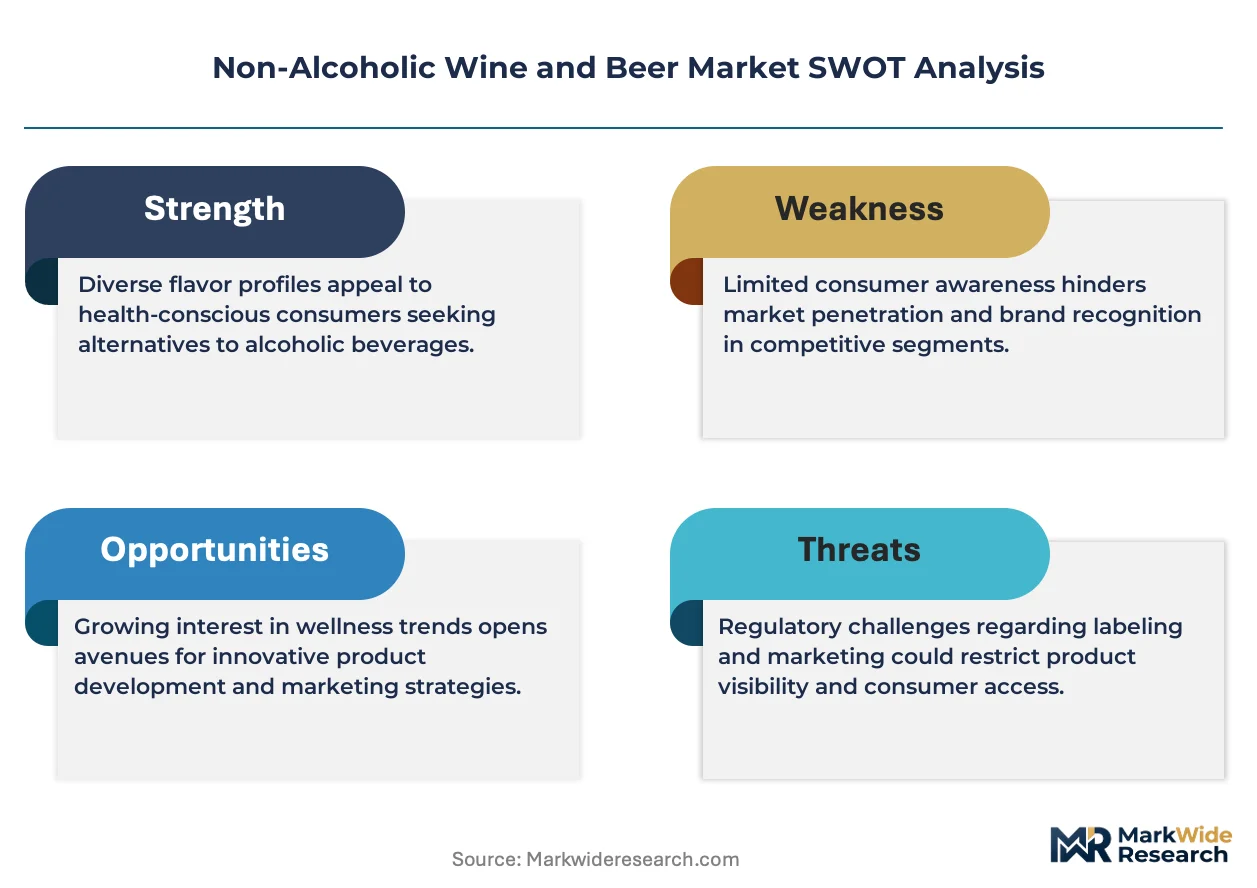
Non-alcoholic wine and beer comprises fermented beverages where alcohol content is reduced below 0.5% ABV through vacuum distillation, reverse osmosis, or arrested fermentation, preserving flavor compounds for consumers avoiding intoxication. Non-alcoholic beer dominates volume due to established brewing workflows and lower reformulation costs. Online retail represents the fastest-expanding distribution channel as direct-to-consumer subscriptions build repeat purchase behavior. Health-conscious consumers command premium pricing willingness, particularly for products with clean-label ingredient declarations and functional additions like electrolytes or adaptogens.
FDA guidelines in the United States govern permissible alcohol thresholds and labeling claims for non-alcoholic beverages, while REACH compliance in Europe affects packaging material specifications and additive approvals. BIS standards in India are beginning to address alcohol-free beverage categories as domestic production scales. Stakeholders should monitor evolving national definitions of zero-alcohol versus low-alcohol classifications, as regulatory divergence threatens cross-border formulation consistency and brand positioning.
Market Dynamics
EU labeling harmonization under EFSA guidance is compressing formulation latitude across member states, forcing producers to standardize at the strictest common denominator rather than optimizing for national variance.
Growth Catalysts
- EFSA Alcohol Threshold Guidance:Tightened definitions of non-alcoholic classification are eliminating consumer confusion and building trust in retail channels across Germany, France, and the Netherlands.
- Reverse Osmosis Advancement:Membrane filtration technology is reducing flavor degradation during alcohol removal, improving sensory parity with conventional beer and wine.
- Hospitality Channel Penetration:Restaurants and hotels in Berlin and Munich are expanding alcohol-free menu sections to capture health-conscious diners.
Market Restraints
- Hop and Barley Input Volatility:Agricultural commodity swings compress margin predictability for malt-based non-alcoholic beer production.
- German Brewing Concentration:Equipment and technical expertise cluster disproportionately in Bavaria, creating supply bottlenecks for new market entrants.
- Flavor Chemistry Limitations:Aroma compound loss during vacuum distillation remains unresolved for complex wine varietals.
Strategic Opportunities
- Spain and Italy Underpenetration:Mediterranean wine cultures present white space for alcohol-free red and sparkling variants with terroir positioning.
- Direct-to-Consumer Subscription Models:Online retail channels are bypassing traditional three-tier distribution economics in the United Kingdom and Scandinavia.
- Functional Ingredient Convergence:Adaptogen and electrolyte fortification is creating premium pricing tiers for fitness-oriented consumers.
Industry Challenges
- Brewing Microbiology Expertise Scarcity:Arrested fermentation protocols require specialized yeast strain management that outpaces current workforce training pipelines.
- Multi-Jurisdiction Labeling Compliance:Divergent national definitions of zero-alcohol versus low-alcohol classifications fragment packaging runs and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Wine and Beer Market |
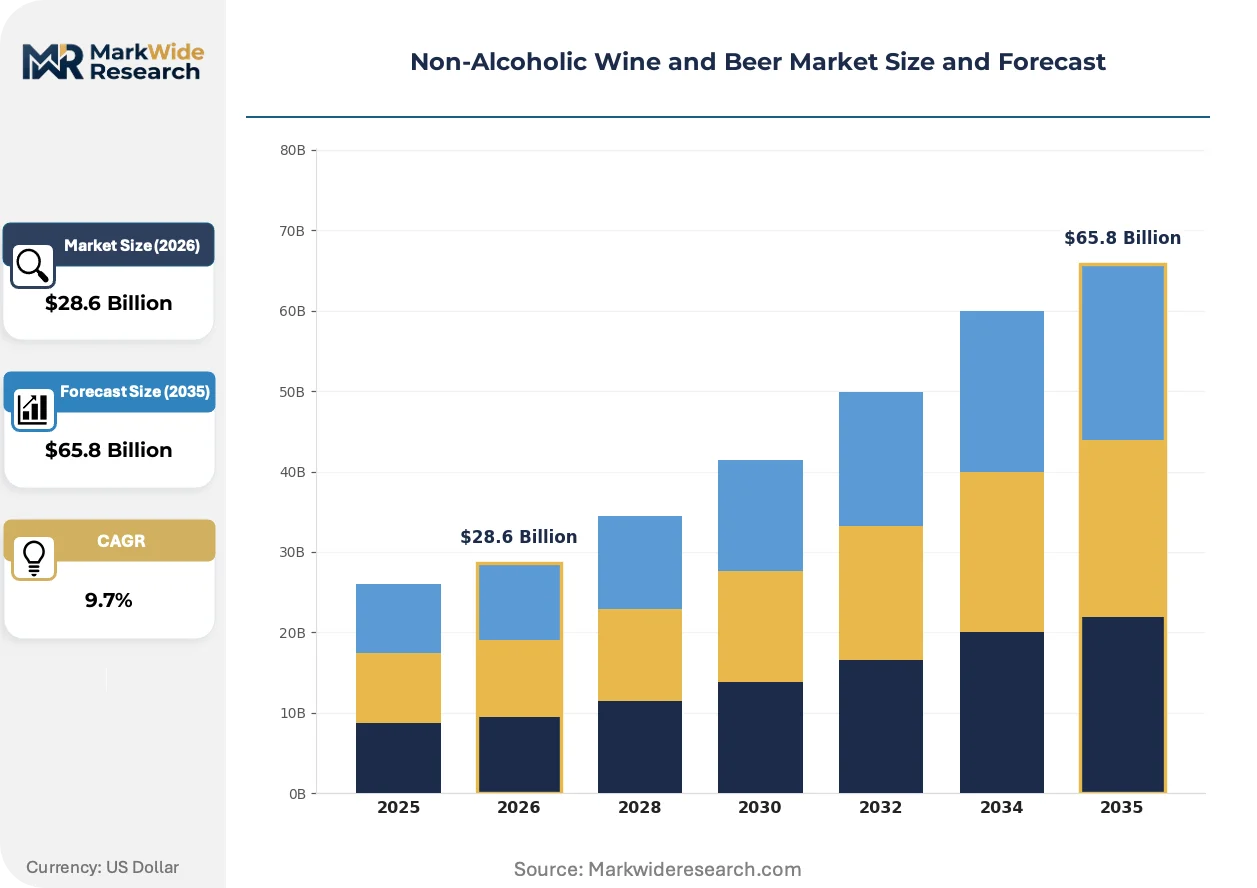
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Alcoholic Beer, Non-Alcoholic Wine, Sparkling Non-Alcoholic Beverages, Non-Alcoholic Cocktails Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Consumer Demographics: Health-Conscious Consumers, Young Adults, Parents, Non-Drinkers Flavor Profile: Fruity, Spicy, Herbal, Sweet |
| Companies Covered | Heineken N.V., Anheuser-Busch InBev, Carlsberg, Suntory Beer, Molson Coors Beverage Company, Asahi Group Holdings, Diageo, BrewDog, Athletic Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Wine and Beer Market Emerging Trajectories
Technology convergence between traditional brewing and beverage formulation science is dissolving historical category boundaries, enabling new entrants to compete on sensory quality without legacy infrastructure investments.
Dealcoholization technology is expanding into craft-scale production workflows. Small-batch breweries in Belgium and the Netherlands are adopting spinning cone column systems previously reserved for industrial volumes. This capability compression is enabling regional producers to launch non-alcoholic portfolios without capital-intensive facility overhauls.
REACH compliance revisions are tightening packaging material specifications for European non-alcoholic beverages. Recycled content mandates and additive approval timelines are extending product development cycles. German and French producers are responding by front-loading regulatory submission phases and locking supplier qualification protocols earlier in R&D.
Consumer trial behavior is compressing repeat purchase cycles through subscription-based sampling. Direct-to-consumer platforms in the United Kingdom and Germany are displacing supermarket shelf discovery with curated monthly deliveries. This channel pivot is most visible among urban millennials seeking variety without commitment to full-case purchases.
Non-Alcoholic Wine and Beer Market Segmentation
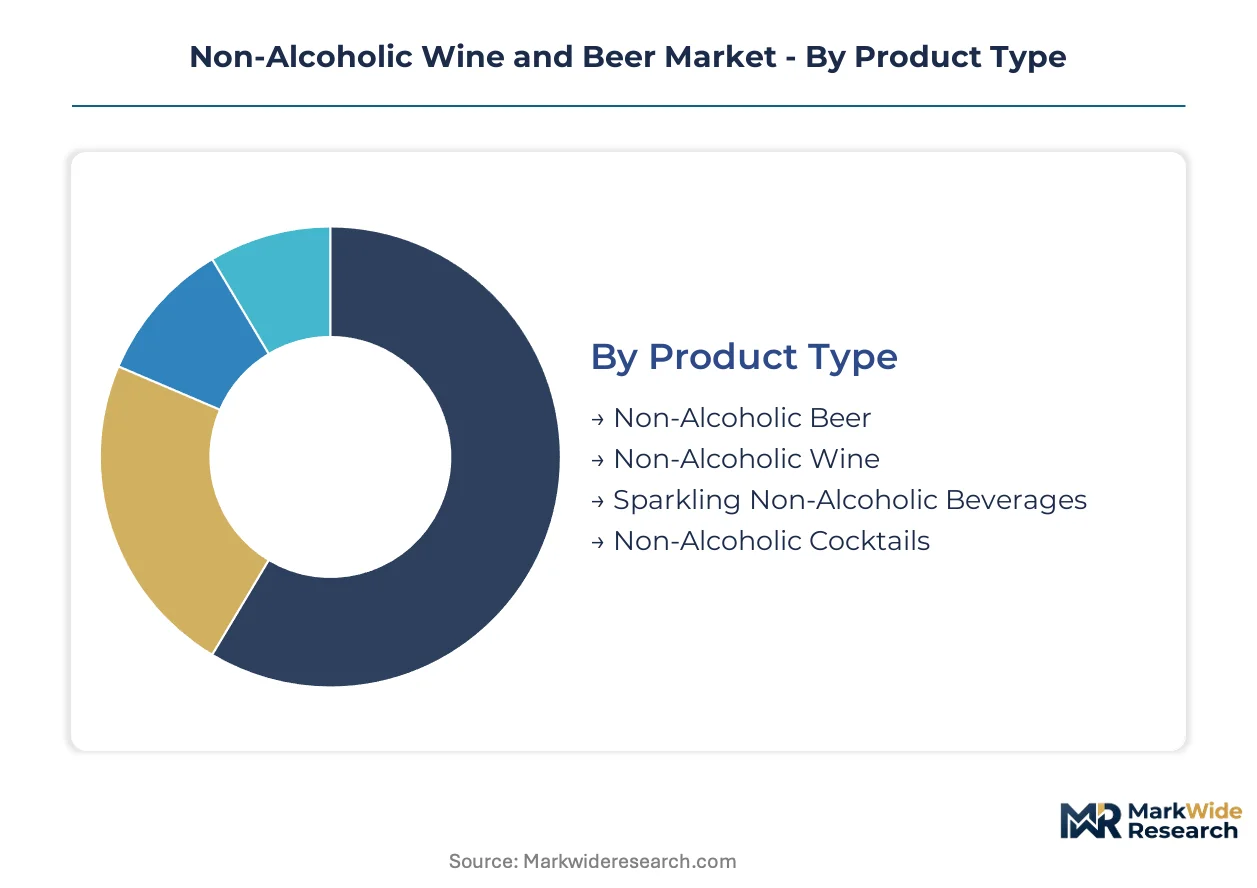
Segmentation in the non-alcoholic wine and beer market reveals distinct demand pockets shaped by consumption context, purchase behavior, and sensory preference. Manufacturers configure production lines and marketing investments around these divides to capture premium positioning or volume scale.
Product Type:
Standalone beverage categories command dedicated shelf space and brand recognition, while embedded formats blend into broader drinking occasions requiring different distribution strategies.
- Non-Alcoholic Beer:Vacuum-distilled or arrested-fermentation lagers and ales preserve malt backbone and hop aromatics. German retail chains and Munich hospitality venues account for disproportionate volume as brewing heritage normalizes alcohol-free consumption.
- Non-Alcoholic Wine:Reverse osmosis and spinning cone column processing remove ethanol from fermented grape must while retaining phenolic structure. French and Italian producers struggle with aroma compound loss in complex red varietals, constraining category expansion.
- Sparkling Non-Alcoholic Beverages:Carbonated grape juice and botanical infusions target celebratory occasions without fermentation. Premium positioning in UK direct-to-consumer channels exploits subscription trial behavior.
- Non-Alcoholic Cocktails:Pre-mixed RTD formats combine distilled botanicals with bitters and citrus for bar-equivalent experiences. Convenience store penetration in urban Netherlands clusters around commuter corridors.
Non-alcoholic beer leads volumes today; non-alcoholic cocktails are gaining share fastest.
Distribution Channel:
Channel selection determines margin structure and consumer education burden, with high-touch formats justifying premium pricing through curation.
- Supermarkets:Mass-market volume anchor with standardized planogram placement. German REWE and Edeka chains dedicate expanding shelf sets to alcohol-free beer, normalizing category visibility for casual purchasers.
- Online Retail:Direct-to-consumer platforms bypass three-tier distribution economics. UK subscription services compress repeat purchase cycles through curated monthly deliveries targeting urban millennials.
- Specialty Stores:Wine merchants and craft beverage shops provide staff education and tasting support. Concentrated in Berlin and Amsterdam neighborhoods with high health-conscious population density.
- Convenience Stores:Impulse-driven single-serve purchases with limited SKU depth. Rotterdam and Copenhagen transit-adjacent locations show strongest alcohol-free beer velocity.
Supermarkets dominate absolute volume; online retail climbs the fastest.
Consumer Demographics:
Demographic targeting shapes formulation intensity, with some segments demanding functional fortification and others prioritizing sensory authenticity.
- Health-Conscious Consumers:Fitness-oriented drinkers seek electrolyte-fortified or adaptogen-enhanced variants. Premium pricing tolerance peaks in Scandinavian markets where clean-label claims drive purchase decisions.
- Young Adults:Social occasion flexibility without intoxication risk. Berlin and London nightlife venues report strongest adoption of non-alcoholic beer on draft.
- Parents:Household purchasing agents balancing adult taste preferences with family-appropriate consumption. German suburban supermarkets show concentrated basket attachment to non-alcoholic wine.
- Non-Drinkers:Lifetime abstainers and recovered drinkers requiring sophisticated alternatives. UK specialty retailers cultivate loyalty through personalized subscription curation.
Health-conscious consumers anchor current revenue; young adults show steepest expansion trajectory.
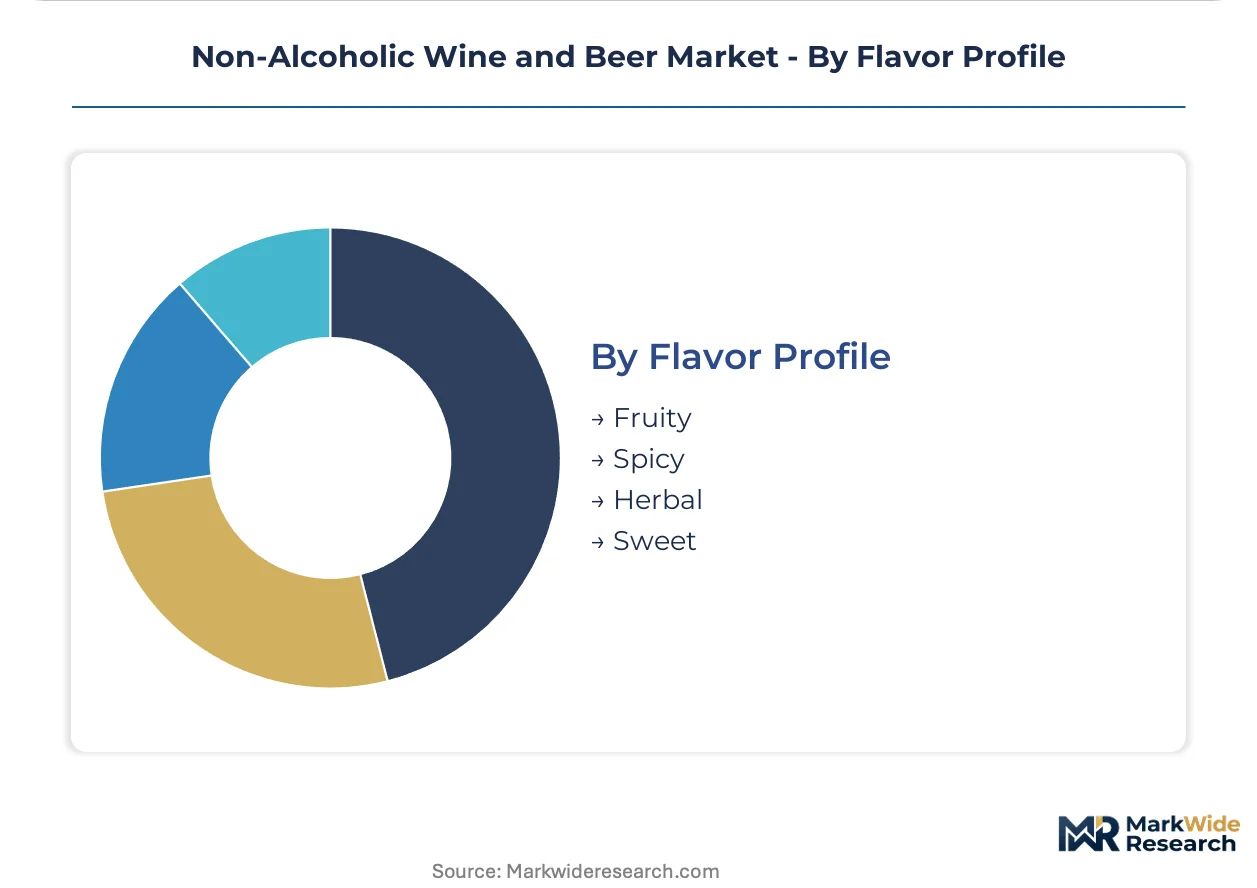
Flavor Profile:
Flavor architecture determines production input costs and technical complexity, with botanical sourcing and extraction methods varying dramatically by profile.
- Fruity:Grape-derived and berry-infused formulations leveraging natural sugar retention. Italian producers exploit indigenous varietal recognition for sparkling non-alcoholic positioning.
- Spicy:Ginger, pepper, and barrel-spice notes requiring precise extraction timing. Belgian craft brewers differentiate non-alcoholic winter ales through spice-forward recipes.
- Herbal:Botanical blends mimicking vermouth and amaro complexity. French aperitif traditions inform non-alcoholic cocktail development in Lyon and Marseille.
- Sweet:Residual sugar emphasis masking alcohol removal artifacts. German alcohol-free beer historically clustered here; market evolution pushes toward drier profiles.
Fruity profiles command current volume leadership; herbal formulations expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German brewing traditions established the technical foundation for modern dealcoholization, with Bavarian lager heritage shaping global production standards. Contemporary demand clusters reflect this lineage while expanding into new consumption contexts.
Germany
Health-conscious hospitality procurement and supermarket shelf normalization drive volume leadership. EFSA labeling harmonization under the EU Green Deal tightens permissible alcohol thresholds for cross-border sales. Munich and Berlin concentrate brewing R&D and draft distribution infrastructure.
United States
Fitness-oriented subscription commerce and craft brewery diversification accelerate category penetration. FDA threshold guidelines govern interstate labeling consistency. California and Colorado house the densest clusters of dealcoholization technology startups and DTC fulfillment operations.
United Kingdom
Urban millennial trial behavior through curated delivery services expands addressable occasions. REACH compliance revisions extend packaging material approval timelines. London and Manchester anchor specialty retail and subscription platform headquarters.
Netherlands
Transit-adjacent convenience consumption and corporate wellness programs sustain baseline demand. ECHA additive approval protocols affect botanical infusion formulations. Rotterdam and Amsterdam concentrate import-export logistics for Benelux distribution.
France
Aperitif culture adaptation and terroir-based positioning attempts for alcohol-free wine create premium opportunities. ANSM guidance on functional ingredient claims constrains adaptogen fortification marketing. Lyon and Marseille develop non-alcoholic cocktail formulations leveraging regional botanical knowledge.
Non-Alcoholic Wine and Beer Market Vendor Landscape
Capital-heavy brewers with legacy fermentation infrastructure compete with asset-light craft specialists outsourcing dealcoholization to toll processors. The market structures around three tiers: multinational beverage conglomerates with global distribution reach, mid-scale regional brewers leveraging proximity advantages, and venture-backed craft entrants prioritizing direct consumer relationships. Dominant competitive moves include portfolio diversification into alcohol-free variants and strategic partnerships with membrane filtration technology providers.
Among Dutch-based conglomerates, Heineken N.V. occupies a position exemplifying scale-driven infrastructure deployment. Anheuser-Busch InBev anchors mass-market penetration archetypes through supermarket channel density. Athletic Brewing Company represents the craft-specialist vector, targeting performance-oriented demographics with subscription-first distribution models.
| Leading Market Players |
|---|
| Heineken N.V. |
| Anheuser-Busch InBev |
| Carlsberg |
| Suntory Beer |
| Molson Coors Beverage Company |
| Asahi Group Holdings |
| Diageo |
| BrewDog |
| Athletic Brewing Company |
| Others |
Supply Flow & Price Mechanics
Barley futures volatility on the Euronext Paris exchange cascades through malt supply contracts into finished non-alcoholic beer pricing, compressing margin buffers for mid-tier producers while amplifying premium-tier pricing power for integrated brewers with captive grain sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the non-alcoholic wine and beer market, with certification grade under EFSA guidance and volume scale as primary differentiation drivers. Pricing pressure stems from hop and barley input volatility, particularly for German producers exposed to Bavarian agricultural commodity swings. Health-conscious consumers in Scandinavian markets show least price sensitivity, while convenience store impulse purchasers in Dutch transit corridors exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German brewing equipment manufacturers concentrated in Bavaria, where technical expertise for arrested fermentation systems clusters disproportionately. Raw material flows draw from French grape must suppliers, German maltsters, and Belgian hop processors. Tariff exposure on aluminum can imports from China threatens packaging cost stability. Distribution runs through supermarket chains in Germany and direct-to-consumer platforms in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-alcoholic wine and beer market functions as a stable compounder, with health-conscious consumption shifts providing durable demand tailwinds across economic cycles.
For Market Incumbents: Cement category ownership by locking long-term barley supply contracts with Bavarian cooperatives before agricultural commodity volatility intensifies. Acquire membrane filtration technology providers to internalize dealcoholization capabilities and defend against craft entrant erosion in subscription channels. For New Entrants and Emerging Players: Spinning cone column miniaturization offers a technology-first wedge into Spain and Italy, where Mediterranean wine cultures remain underpenetrated for alcohol-free red varietals. Target urban millennial trial behavior through curated direct-to-consumer sampling programs in London and Manchester, bypassing supermarket slotting fee barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with craft-scale breweries in Belgium and the Netherlands possessing installed spinning cone capacity but undermonetized brand equity. The five-to-ten-year viability window favors acquisition of regional producers with EFSA-compliant labeling infrastructure already validated. Watch German REWE and Edeka shelf allocation decisions as the inflection signal for category mainstreaming velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dealcoholization Technology Licensing | Spinning cone column patents enable craft breweries to enter non-alcoholic portfolios without capital-intensive facility overhauls. |
| Direct-to-Consumer Platform Launch | UK subscription services compress repeat purchase cycles through curated monthly deliveries targeting urban millennials. |
| EFSA Certification Investment | Early compliance with tightened alcohol threshold definitions secures cross-border sales access across German, French, and Dutch retail channels. |
| Functional Ingredient Partnership | Adaptogen and electrolyte fortification collaborations with Scandinavian wellness brands unlock premium pricing tiers. |
| Hospitality Channel Expansion | Berlin and Munich restaurant draft placements normalize alcohol-free consumption in social dining contexts. |
Methodological Framework
Multiple input streams — structured interviews with brewing R&D directors, procurement leads at German supermarket chains, and membrane filtration technology providers — were reconciled against secondary validation from EFSA guidance documents, REACH compliance filings, and Nielsen retail audit data. Bottom-up volume builds from individual SKU velocities in tracked channels were triangulated with top-down category spend estimates derived from national beverage consumption surveys.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation dimensions including product type, distribution channel, consumer demographic, and flavor profile. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for regulatory inflection points and technology adoption curves. Industry-specific forecast inputs incorporated EFSA labeling harmonization timelines and spinning cone column cost reduction curves.
The model holds under stable EU regulatory definitions and continued agricultural commodity accessibility; deviation in barley harvest yields or EFSA threshold revisions would shift volume trajectories materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Ice Tea Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Isotonic Drinks Market