
 Global Syrup Market | 2026-2036
Global Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Global Syrup Market Intelligence
The premium artisan syrup tier is rebalancing away from commodity corn sweeteners on ingredient provenance and clean-label positioning. Monin leverages its French botanical sourcing to command specialty café and mixology channels. Torani anchors West Coast beverage manufacturing with flavor innovation pipelines. Conagra Brands competes through retail scale and private-label versatility across pancake and ice cream segments.
Syrup denotes a viscous liquid sweetener typically comprising dissolved saccharides at concentrations exceeding 60 percent solids, manufactured through enzymatic hydrolysis, thermal evaporation, or tree tapping followed by filtration and pasteurization. Its primary commercial purpose spans food and beverage formulation where controlled sweetness, humectancy, and browning reactivity are functionally required. High fructose corn syrup dominates volume in beverage applications where cost efficiency and blending stability sustain its structural lead. Maple syrup commands premium margin pools in retail and Horeca channels driven by geographic origin certification and perceived natural authenticity. Fruit syrup is gaining fastest among dairy and confectionery segments as manufacturers replace artificial flavors with recognizable botanical sources.
The FDA governs added sugars disclosure on Nutrition Facts panels while the EPA regulates wastewater discharge from corn wet milling facilities, jointly elevating compliance costs for mass-market producers. EFSA and the EU Green Deal are tightening pesticide residue thresholds and deforestation-linked sourcing criteria for imported cane and palm-derived feedstocks. Stakeholders must monitor evolving sugar taxation schemes and carbon border adjustments that will restructure procurement geography and reformulation priorities.
Market Dynamics
The EU Green Deal's deforestation-linked sourcing criteria is forcing mass-market syrup producers to restructure procurement geography away from conventional cane and palm feedstocks toward certified botanical alternatives.
Growth Catalysts
- Clean-label mandates:EFSA pesticide residue thresholds are accelerating reformulation toward recognizable fruit and botanical sources in European dairy and confectionery applications.
- Functional beverage expansion:Carbonated drink manufacturers are adopting syrup systems for flavor layering and sweetness modulation in reduced-sugar formulations.
- Urban India:Packaged syrup adoption is displacing traditional jaggery and khandsari in metropolitan households seeking convenience and consistent quality.
Market Restraints
- Input cost volatility:Corn wet milling margins compress when natural gas prices spike, given thermal evaporation's energy intensity.
- Supply concentration risk:Quebec and Vermont dominate maple syrup certified production, creating geographic single-source vulnerability for premium positioning.
- Regulatory friction:FDA added sugars disclosure rules complicate formulation for beverage clients serving health-conscious retail channels.
Strategic Opportunities
- Carbon border adjustments:EU Green Deal mechanisms will reward low-carbon intensity sweetener sourcing from European beet and domestic fruit processors.
- Direct-to-café distribution:Specialty roasteries and independent coffee chains are bypassing traditional foodservice distributors for artisan syrup procurement.
- Pharma-grade excipients:High-purity syrup derivatives are meeting USP-NF standards for cough suppressant and pediatric formulation applications.
Industry Challenges
- Enzyme engineering talent:Scarcity of biochemists specializing in amylase optimization for specific dextrose equivalent targets constrains R&D throughput.
- Legacy system integration:Traceability software for EU deforestation compliance must interface with existing ERP platforms at mid-sized processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Syrup Market |
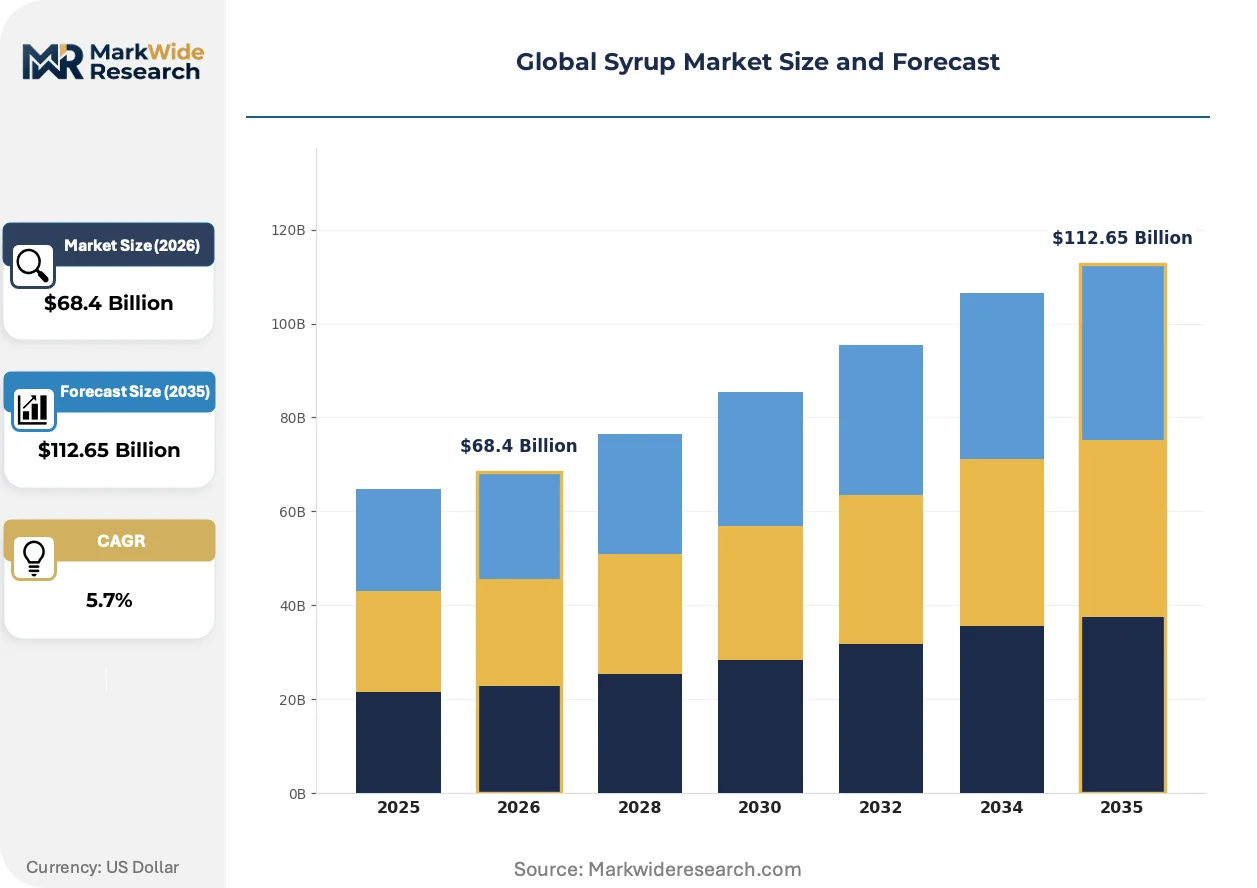
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Fructose Corn Syrup, Maple Syrup, Cane Syrup, Agave Syrup, Fruit Syrup, Malt Syrup Application: Beverages, Bakery Goods, Confectionery, Dairy Products, Pharmaceuticals, Sauces & Dressings End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Retailers, Horeca, Household Consumers Packaging Type: Glass Bottles, Plastic Bottles, Tetra Packs, Sachets, Bulk Containers, Pouches |
| Companies Covered | Monin, Torani, Conagra Brands, The Hershey Company, The Kraft Heinz Company, The J.M. Smucker Company, Nestlé, Cargill, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Syrup Market Strategic Shifts & Innovations
Enzymatic precision and regulatory traceability are compressing the gap between commodity efficiency and premium provenance claims across syrup manufacturing tiers.
Precision fermentation is integrating microbial-derived sweetener precursors into syrup production workflows. Beverage formulators in North American functional drink segments are piloting these inputs for glycemic index reduction. The technology is integrating carbohydrate specificity that thermal hydrolysis cannot achieve, enabling calibrated sweetness curves.
EU Green Deal due diligence requirements are mandating geospatial verification of cane and palm sourcing. Mass-market producers face compliance cost escalation for imported feedstocks. European bottlers are responding by qualifying domestic beet syrup suppliers with shorter chain-of-custody documentation.
Café operators are consolidating syrup SKUs around multi-functional flavor systems that reduce inventory complexity. Independent coffee chains are displacing single-purpose pancake and beverage syrups with cross-application botanical concentrates. This consolidation is most visible in Australian and UK metropolitan markets where labor cost pressures intensify back-of-house efficiency demands.
Global Syrup Market Segmentation
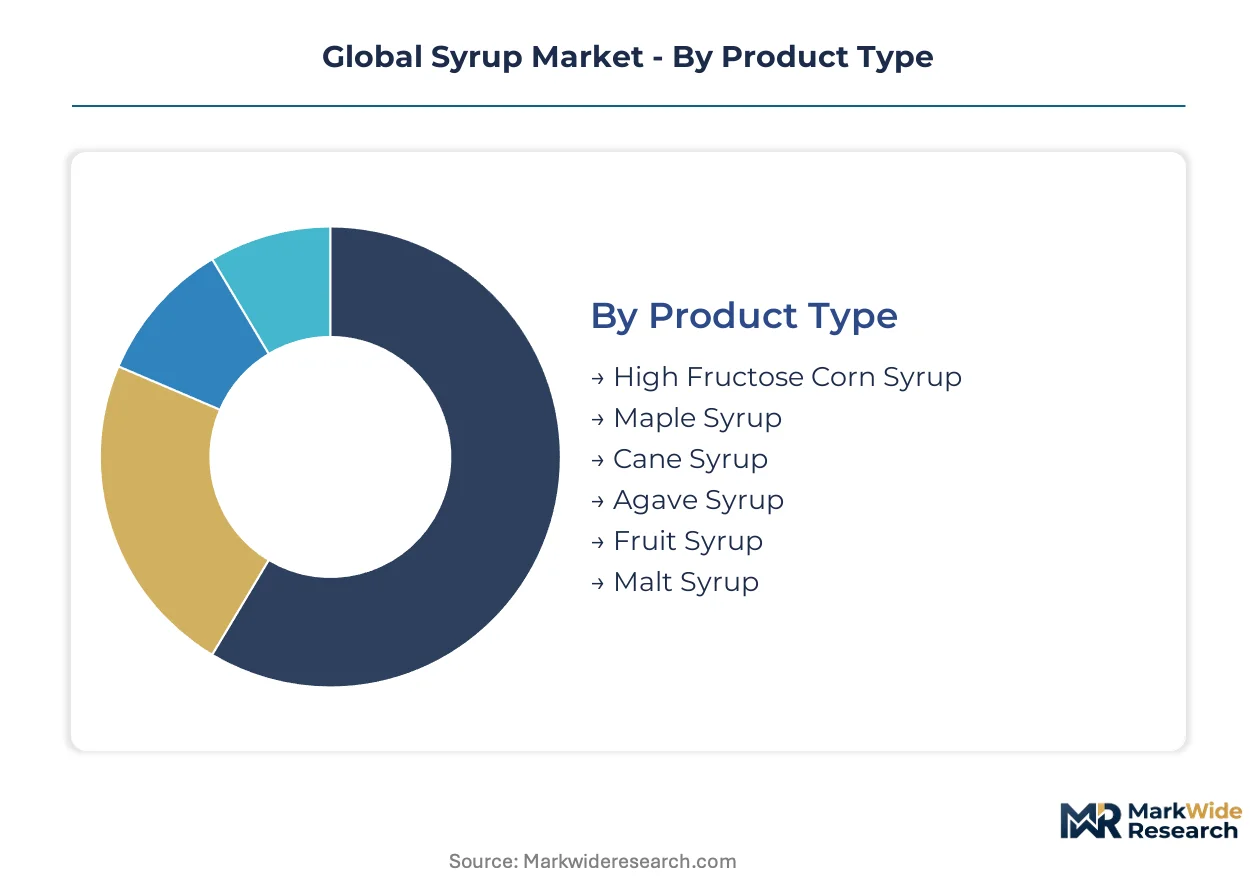
Syrup manufacturers configure production assets around viscosity specifications and saccharide profiles that align with distinct channel requirements. Each segmentation dimension reveals divergent margin structures and compliance burdens that reshape competitive positioning across formulation tiers.
Product Type:
Standalone sweetener syrups operate as finished goods in retail and foodservice channels, while embedded variants integrate into beverage and dairy manufacturing workflows as invisible inputs.
- High Fructose Corn Syrup:Manufactured through enzymatic isomerization of corn starch to achieve fructose concentrations between 42% and 90%. Carbonated beverage bottlers in the United States anchor procurement volumes where FDA added sugars disclosure rules intensify reformulation pressure.
- Maple Syrup:Derived from Acer saccharum sap boiled to 66% sucrose density with strict Quebec and Vermont origin certification. Premium retail positioning in Japanese and German gourmet channels sustains margin premiums despite geographic supply concentration.
- Cane Syrup:Evaporated sugarcane juice retaining molasses character and mineral content. Louisiana and Brazilian mills supply bakery manufacturers seeking Maillard browning control.
- Agave Syrup:Hydrolyzed inulin from Agave tequilana with high fructose ratio and low glycemic index. Natural food retailers in California and Texas drive adoption for clean-label positioning.
- Fruit Syrup:Concentrated fruit juices with added invert sugar for stability. European dairy processors favor these inputs for EFSA-compliant flavor layering in yogurts.
- Malt Syrup:Sprouted barley enzymatic conversion yielding maltose-dominant profile. Craft brewing and artisanal bread production in Belgium and Denmark sustain niche demand.
Volume placements concentrate in high fructose corn syrup; the faster expansion belongs to fruit syrup.
Application:
Cost tier differentiation separates commodity-scale manufacturing inputs from premium positioning in experiential consumption moments.
- Beverages:Carbonated soft drinks, functional waters, and ready-to-drink teas rely on syrup systems for sweetness modulation and flavor consistency. Indian urban bottlers are expanding capacity to displace traditional sweeteners in metropolitan markets.
- Bakery Goods:Humectancy and browning control drive pancake, muffin, and bread formulations. North American private-label manufacturers compete on corn syrup price efficiency.
- Confectionery:Hard candies and caramels require precise dextrose equivalent control for texture engineering. EFSA pesticide residue thresholds are accelerating botanical syrup adoption in European chocolate enrobing.
- Dairy Products:Flavored milk and ice cream applications favor fruit syrup for clean-label positioning. Australian processors lead SKU consolidation around multi-functional concentrates.
- Pharmaceuticals:USP-NF grade syrups serve as excipients in cough suppressants and pediatric suspensions. FDA current good manufacturing practice compliance elevates entry barriers.
- Sauces & Dressings:Viscosity and sheen requirements in barbecue and salad applications. Japanese and South Korean condiment manufacturers favor malt syrup for umami synergy.
Cost pressure dominates beverage procurement; pharmaceutical-grade specifications command the steepest margin premiums.
End User:
Customer type segmentation maps procurement sophistication from bulk commodity tenders to artisanal direct relationships.
- Food Manufacturers:Scale-driven buyers optimizing for blending stability and thermal processing tolerance. Corn wet milling procurement contracts dominate North American volume.
- Beverage Producers:Formulation-sensitive clients requiring calibrated sweetness curves and clean-label migration pathways. EU Green Deal deforestation compliance is restructuring their cane sourcing geography.
- Pharmaceutical Companies:Quality-critical purchasers demanding certificate of analysis documentation and excipient compatibility testing. FDA audit trails govern supplier qualification.
- Retailers:Private-label developers balancing shelf appeal with margin compression. Supermarket chains in the United Kingdom and Germany consolidate around multi-purpose botanical concentrates.
- Horeca:Hotels, restaurants, and cafés seeking origin storytelling and back-of-house efficiency. Australian independent coffee chains bypass distributors for direct artisan syrup procurement.
- Household Consumers:Premium retail purchasers responding to geographic origin certification and perceived natural authenticity. Quebec maple syrup commands loyalty in Japanese gift markets.
Procurement scale concentrates with food manufacturers; relationship-based direct sourcing is expanding fastest among Horeca operators.
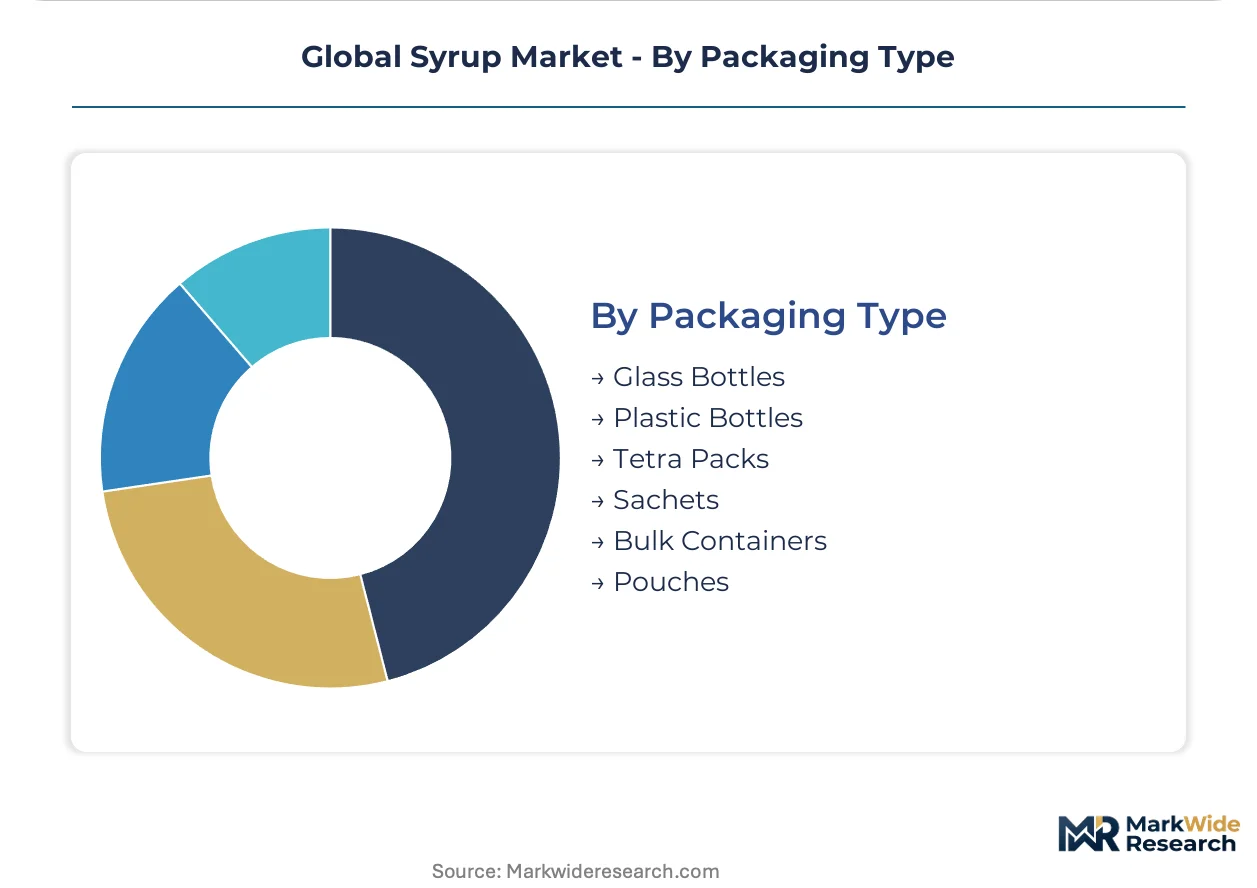
Packaging Type:
Supply chain configuration separates bulk industrial formats from consumer-facing convenience and premium presentation.
- Glass Bottles:Premium retail and gift positioning with superior barrier properties and aesthetic differentiation. Maple syrup producers in Vermont and Quebec favor this format for export markets.
- Plastic Bottles:Cost-efficient retail distribution with lightweight logistics. High fructose corn syrup retail sizes in United States mass channels dominate this segment.
- Tetra Packs:Aseptic processing compatibility for extended shelf stability. European fruit syrup suppliers to dairy manufacturers favor this format.
- Sachets:Single-serve convenience for foodservice and travel channels. Indian metropolitan households drive adoption for on-the-go sweetening.
- Bulk Containers:Tanker and drum formats for industrial manufacturing integration. Beverage bottlers in Brazil and Mexico optimize receiving logistics through this format.
- Pouches:Flexible packaging for refill and sustainability positioning. German and French natural food retailers are piloting this format for agave syrup.
Industrial volume flows through bulk containers; sustainability-driven pouch formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quebec's Saint-Lawrence Valley dominates maple syrup certified production, supplying Japanese gift markets and European gourmet channels with geographic origin authentication.
United States
Vermont and New York State anchor maple syrup output for premium retail positioning. FDA added sugars disclosure rules on Nutrition Facts panels intensify reformulation pressure for beverage bottlers. Corn wet milling clusters in Iowa and Illinois optimize procurement contracts for high fructose corn syrup integration.
Germany
EFSA pesticide residue thresholds accelerate botanical syrup adoption in dairy and confectionery applications. EU Green Deal deforestation-linked sourcing criteria restructure cane procurement geography toward domestic beet processors. Natural food retailers in Berlin and Hamburg pilot pouch formats for agave syrup sustainability positioning.
India
Urban households in Mumbai and Delhi displace traditional jaggery and khandsari with packaged syrups seeking convenience. FSSAI standards govern food additive safety and labeling requirements for sweetener products. Beverage bottlers in Maharashtra expand capacity to serve metropolitan markets shifting from conventional sweeteners.
Japan
Quebec maple syrup commands loyalty in Tokyo and Osaka gift markets driven by perceived natural authenticity. METI standards influence quality benchmarks for imported sweetener products. Specialty café chains in Kanto bypass distributors for direct artisan syrup procurement from French botanical suppliers.
Brazil
Louisiana-style cane syrup production in São Paulo State supplies bakery manufacturers seeking Maillard browning control. ANVISA regulates food additive safety and sweetener labeling for domestic and export markets. Beverage bottlers optimize receiving logistics through bulk container formats at Port of Santos.
Global Syrup Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the syrup manufacturing spectrum. Corn wet milling conglomerates sustain structural volume leads through thermal evaporation infrastructure and procurement scale. Specialty botanical houses command premium positioning via French and Vermont origin certification. Three archetypes dominate: commodity-scale processors, premium provenance specialists, and private-label versatile manufacturers. M&A activity concentrates on regional bottling assets, while capacity expansion targets enzymatic precision for glycemic index reduction.
Within the premium provenance tier, Monin and Torani exemplify botanical sourcing differentiation. Monin leverages its French heritage to anchor specialty café and mixology channels with clean-label positioning. Torani occupies a West Coast manufacturing position serving beverage innovation pipelines. Among diversified food conglomerates, Conagra Brands represents private-label versatility across retail pancake and ice cream segments. These three companies illustrate the competitive spread between artisan direct relationships and mass-market scale efficiency.
| Leading Market Players |
|---|
| Monin |
| Torani |
| Conagra Brands |
| The Hershey Company |
| The Kraft Heinz Company |
| The J.M. Smucker Company |
| Nestlé |
| Cargill |
| Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
EU Green Deal deforestation compliance criteria gates qualified supply access and premium-tier pricing power for mass-market producers dependent on imported cane and palm feedstocks. Certification investments separate botanical syrup suppliers commanding specialty margins from commodity processors facing margin compression.
Pricing Analysis
Yield-based pricing anchors maple syrup premiums to certified geographic origin and seasonal sap flow density. Three-tier pricing structure across premium, standard, and economy levels separates Quebec single-origin retail from blended private-label and industrial corn syrup contracts. Cost compression in high fructose corn syrup is intensifying because natural gas price spikes directly impact thermal evaporation economics. Beverage bottlers exhibit highest price sensitivity; pharmaceutical-grade buyers tolerate steepest premiums for USP-NF documentation.
Supply Chain Analysis
Single-source vulnerability sits with Quebec and Vermont maple syrup production, which supplies Japanese gift markets and European gourmet channels. Corn wet milling draws from Iowa and Illinois processing clusters; cane syrup sources from Louisiana and Brazilian mills. Tariff exposure on imported deforestation-linked feedstocks is restructuring procurement geography toward European beet processors. Distribution runs through bulk tanker formats for beverage manufacturers and direct-to-café relationships for artisan botanical houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-capable processors as EU Green Deal sourcing criteria force smaller importers into exit or acquisition.
For Market Incumbents: Deepen backward integration into certified beet and domestic fruit processing to secure deforestation-compliant feedstock pipelines. Expand enzymatic precision capacity for glycemic index reduction to defend against precision fermentation substitutes. Lock long-term offtake agreements with Quebec and Vermont maple cooperatives before supply concentration tightens further.
For New Entrants and Emerging Players: Capture direct-to-café distribution relationships in Australian and UK metropolitan markets where independent coffee chains bypass traditional foodservice networks. Target pharma-grade excipient qualification as the most penetrable premium tier, leveraging USP-NF standards to differentiate from commodity processors. Lead with geospatial traceability software as a bundled service offering to mid-sized European bottlers facing ERP integration challenges.
For Investors and Strategic Acquirers: EU carbon border adjustment implementation is the leading indicator that low-carbon intensity European beet processors will command sustained margin premiums over imported cane competitors. Position acquisition screening around mid-sized enzymatic specialists with amylase optimization capabilities and existing FDA audit trails. Watch FSSAI enforcement patterns in Indian metropolitan markets as the signal for packaged syrup displacement acceleration against traditional sweeteners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Feedstocks | EU Green Deal compliance secures premium channel access and defends against carbon border adjustment exposure. |
| Enzymatic Precision Capacity Expansion | Calibrated sweetness curves meet functional beverage glycemic index reduction requirements in North American markets. |
| Direct-to-Café Distribution Buildout | Australian and UK independent coffee chains reward origin storytelling with reduced distributor margin capture. |
| Pharma-Grade Excipient Qualification | USP-NF certification opens cough suppressant and pediatric formulation contracts with FDA-audit-compliant documentation. |
| Geospatial Traceability Software Integration | EU deforestation due diligence mandates create recurring revenue attachment to existing ERP platforms at mid-sized processors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with beverage formulation directors, corn wet milling procurement leads, specialty café chain buyers, and pharmaceutical excipient quality managers combined with FDA guidance documents, EFSA scientific opinions, EU Green Deal due diligence requirements, and FSSAI sweetener standards. Bottom-up capacity modeling across enzymatic processing facilities triangulated against top-down consumption estimates from dairy, confectionery, and beverage manufacturing channels.
Granularity-level modeling distinguished viscosity specifications, saccharide profiles, and certification tiers across the projection horizon. Segmentation dimensions included product type, application channel, end-user procurement sophistication, and packaging format, with regional regulatory cluster as an additional syrup-specific dimension. CAGRs derived from trend extrapolation of clean-label migration rates, urban India packaged adoption curves, and carbon border adjustment phase-in schedules. Industry-specific inputs incorporated natural gas price volatility impacts on thermal evaporation economics and enzyme engineering talent scarcity constraints on R&D throughput.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU deforestation enforcement stringency, precision fermentation cost curves, and Indian FSSAI implementation pacing. Forecasts reflect documented assumptions about regulatory phase-in timelines and technology adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Natural Berry Flavor Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Pine Bark Extract Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Citrus Flavors Market