
 Ready to Serve Cocktails Market | 2026-2036
Ready to Serve Cocktails Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Serve Cocktails Market Analytics
US-based craft distilleries is recalibrating production lines to meet surging premixed demand. Bacardi Limited leverages Caribbean rum heritage to dominate tropical-flavored canned formats. Diageo plc anchors its portfolio through spirits-forward formulations that command premium shelf placement. Constellation Brands competes aggressively in Mexican-inspired ready-to-serve agave expressions.
Ready to serve cocktails denote spirit-based beverages blended with mixers, preservatives, and flavor stabilizers, then packaged in single-serve aluminum cans or glass bottles with shelf lives of 12-18 months. These products eliminate bartender labor and equipment while delivering consistent alcohol-by-volume precision for hospitality and retail channels. Canned cocktails occupy the fastest-growing format position as aluminum recycling infrastructure and outdoor consumption occasions expand across North America and Western Europe. The low ABV category captures disproportionate margin attention as health-conscious consumers and daytime drinking occasions reshape formulation targets. Distribution through bars and restaurants remains the highest-margin channel despite retail stores generating larger absolute volumes.
The US TTB enforces strict formula approval and label disclosure requirements that constrain ingredient innovation timelines. The EU's F-Gas Regulation and packaging waste directives pressure producers toward lighter-weight containers and reduced carbon footprints in European supply chains. India's FSSAI maintains distinct additive and alcohol-content thresholds that complicate direct product porting from Western formulations. Stakeholders must monitor evolving excise tax structures and cross-border e-commerce alcohol regulations as channel fragmentation accelerates.
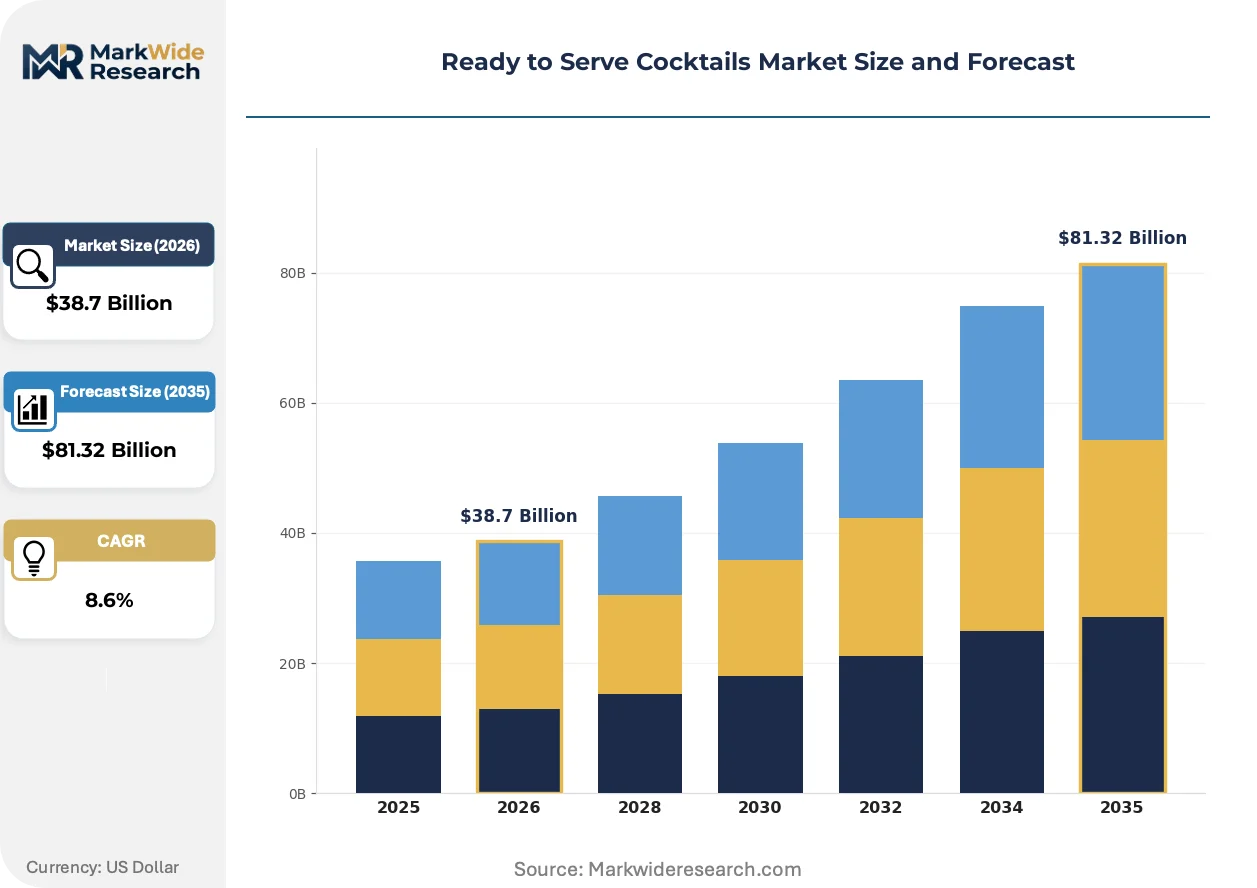
Market Dynamics
Aluminum can supply concentration and the US FDA's updated labeling guidelines are compressing formulation timelines while forcing capital reallocation toward packaging flexibility and compliance infrastructure across the ready to serve cocktails value chain.
Growth Catalysts
- Caribbean rum heritage positioning:Tropical-flavored canned formats leverage established distilling traditions to capture outdoor consumption occasions in coastal metropolitan clusters.
- EU F-Gas Regulation:Packaging waste directives accelerate producer migration toward lighter-weight containers with measurable carbon footprint reductions in European supply chains.
- Low ABV formulation science:Health-conscious daytime drinking occasions drive disproportionate margin attention from hospitality procurement teams seeking sessionable alternatives.
Market Restraints
- US TTB formula approval timelines:Strict label disclosure requirements constrain ingredient innovation cycles and extend product development schedules by quarters.
- Aluminum can supply concentration:North American smelter capacity limitations create input volatility for the fastest-growing format segment.
- India FSSAI additive thresholds:Distinct alcohol-content regulations complicate direct product porting from Western formulations into the subcontinent's retail channels.
Strategic Opportunities
- Mexican-inspired agave expressions:Unmet demand for tequila-based ready to serve formats exists in sun-belt states with Latin culinary influence.
- Cross-border e-commerce alcohol frameworks:Evolving excise tax structures enable direct-to-consumer channel development in jurisdictions liberalizing shipment rules.
- Spirits-forward premium placement:Higher alcohol-by-volume formulations command shelf positioning that captures trade-up revenue from at-home mixology abandonment.
Industry Challenges
- Flavor stability chemist scarcity:Formulation talent capable of delivering 12-18 month shelf life without quality degradation commands premium compensation in tight labor markets.
- Co-packer certification timelines:Third-party production facility approvals for alcohol handling extend go-to-market schedules beyond comparable non-alcoholic beverages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Serve Cocktails Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Cocktails, Bottled Cocktails, Draught Cocktails, Ready-to-Drink Cocktails Flavor Profile: Sweet, Sour, Spicy, Herbal Alcohol Content: Low ABV, Standard ABV, High ABV, Non-Alcoholic Distribution Channel: Retail Stores, Online Sales, Bars, Restaurants |
| Companies Covered | Bacardi Limited, Suntory Holdings, Anheuser-Busch InBev, Carlsberg, Heineken, Diageo plc, Brown-Forman, Constellation Brands, Pernod Ricard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Serve Cocktails Market Evolving Landscape
Reformulation priorities and packaging material science are converging to reshape competitive positioning, with regulatory compliance and consumption occasion fragmentation driving divergent technology investments across the value chain.
Aseptic canning technology with nitrogen dosing systems is electrifying shelf-life extension capabilities for low-ABV formulations. Boutique hotel chains and resort beverage programs are adopting these systems at accelerated procurement cycles. The technology is electrifying margin structures by reducing preservative loads while maintaining flavor integrity through 18-month distribution windows.
The EU F-Gas Regulation's phasedown schedule pressures producers toward alternative cooling technologies in European production facilities. Industrial consequence includes accelerated capital deployment into heat pump systems and hydrocarbon-based refrigeration. German and Dutch manufacturing sites face the most compressed compliance timelines, with facility retrofits consuming operational budgets through the forecast window.
Daypart-specific consumption patterns are fragmenting traditional evening-centric marketing strategies. Hospitality buyers are unbundling inventory into occasion-based SKUs targeting brunch, poolside, and pre-dinner moments. Coastal California and Florida resort corridors exhibit the most pronounced demand rotation toward sessionable daytime formats with sub-8% ABV targets.
Ready to Serve Cocktails Market Segmentation
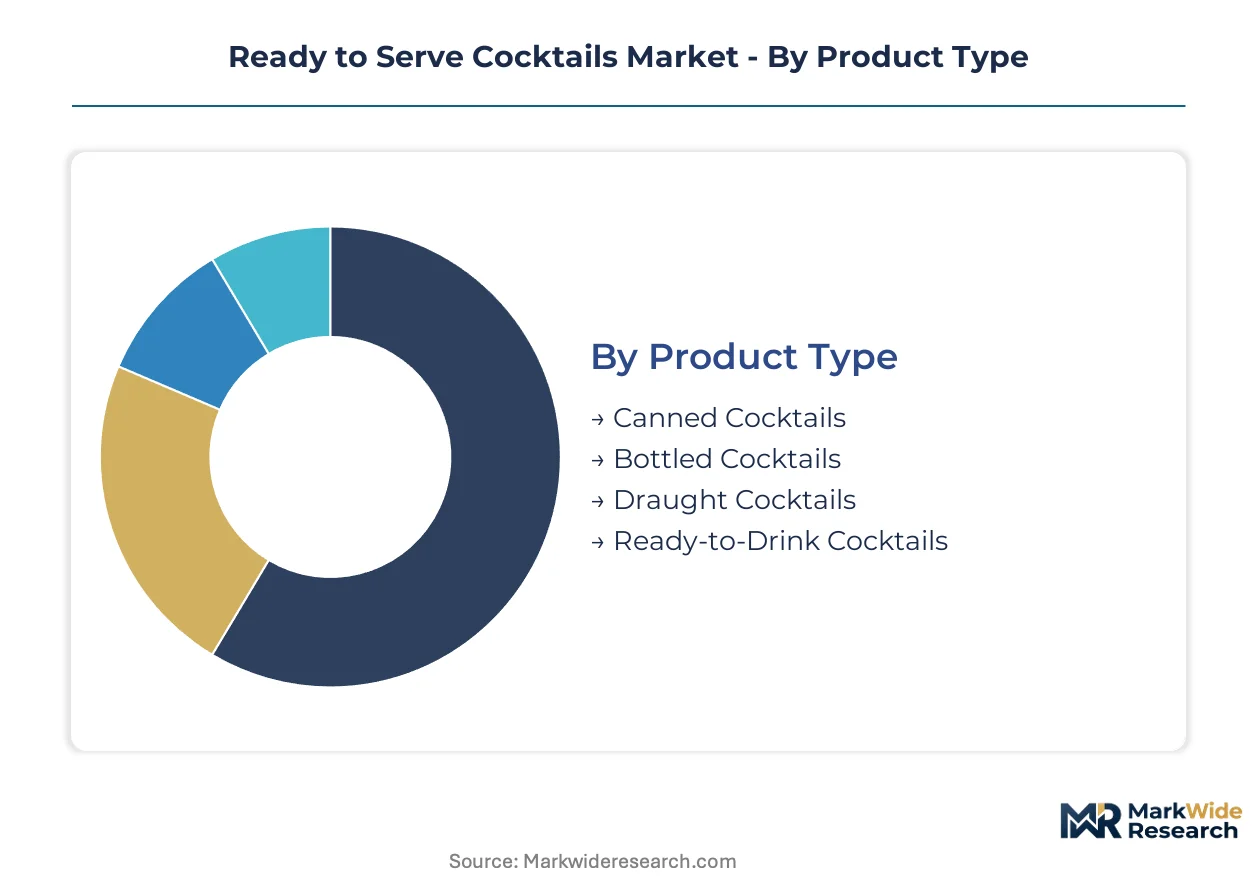
Segmentation in ready to serve cocktails reveals how packaging technology, consumption occasions, and channel economics fragment procurement priorities across hospitality and retail buyers. Distinct formulation requirements and shelf-life demands create divergent margin structures within each category.
Product Type:
Standardization versus customization tension runs deepest across packaging formats, with aluminum canning infrastructure driving economies of scale while draught systems demand bespoke dispensing equipment.
- Canned Cocktails:Single-serve aluminum vessels with nitrogen dosing enable 18-month shelf stability for outdoor consumption occasions. Coastal metropolitan clusters in the United States concentrate demand as recycling infrastructure and beachfront hospitality procurement expand in tandem.
- Bottled Cocktails:Glass packaging preserves spirits-forward formulations targeting premium at-home mixology substitution. German and Dutch retail channels show particular appetite for heritage-brand bottling with carbon footprint labeling under EU packaging waste directives.
- Draught Cocktails:Keg-based dispensing systems serve high-volume on-premise accounts with minimal packaging waste per serving.
- Ready-to-Drink Cocktails:Broader category encompassing pouch and tetrapak formats for emerging markets with limited cold-chain infrastructure.
Leading the category by volume: Canned Cocktails. Expanding most quickly: Draught Cocktails.
Flavor Profile:
Cost tier stratification separates commodity flavor houses from proprietary botanical extraction operations with captive ingredient sourcing.
- Sweet:Sugar-forward formulations dominate mass-market retail placement with tropical fruit and vanilla profiles. United States sun-belt states exhibit concentrated procurement from hotel poolside programs seeking sessionable daytime options.
- Sour:Citrus-driven acidity requires pH stabilization chemistry and preservative balancing for shelf-life integrity. Coastal California resort corridors favor these profiles for brunch occasion targeting.
- Spicy:Chili and ginger infusions command premium positioning in Latin culinary-influence markets.
- Herbal:Botanical complexity demands specialized extraction equipment and extended formulation timelines.
Volume concentration: Sweet. Margin premium capture: Herbal.
Alcohol Content:
Application occasion fragmentation drives formulation targets, with health-conscious daytime drinking reshaping procurement specifications across hospitality segments.
- Low ABV:Sub-8% formulations target sessionable consumption with reduced caloric load and extended drinking occasions. Florida resort chains and coastal California boutique hotels concentrate procurement for poolside and brunch inventory unbundling.
- Standard ABV:8-15% range delivers traditional cocktail equivalence for mainstream retail and bar placement.
- High ABV:Spirits-forward formulations above 15% capture trade-up revenue from at-home mixology abandonment in premium retail channels.
- Non-Alcoholic:Distilled botanical bases with zero ethanol target designated-driver occasions and health-restricted consumption.
Steepest expansion trajectory: Low ABV. Absolute revenue base: Standard ABV.
Distribution Channel:
Customer type separation distinguishes high-margin, low-volume hospitality accounts from scale-driven retail operations with divergent service requirements.
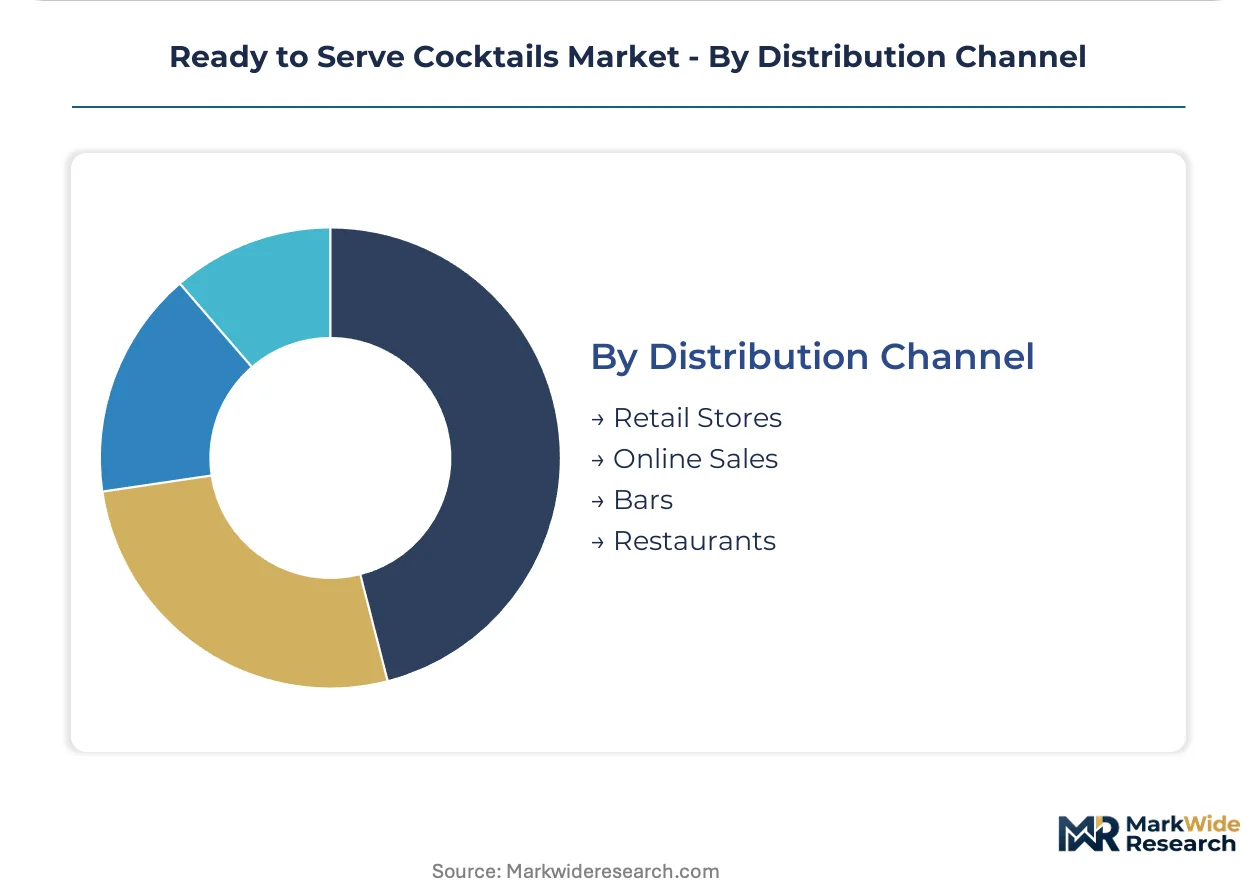
- Retail Stores:Grocery and liquor store placement generates largest absolute volumes with standardized pallet configurations and promotional calendar alignment. United States coastal metropolitan areas show densest point-of-sale concentration.
- Bars:On-premise dispensing commands highest per-unit margins despite smaller throughput, with backbar placement driving brand visibility and trial conversion.
- Restaurants:Food-pairing integration and by-the-glass program adoption create sticky procurement relationships with beverage directors.
- Online Sales:Direct-to-consumer and third-party delivery platforms navigate evolving excise tax structures and cross-border shipment regulations.
Margin leadership: Bars. Volume scale: Retail Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caribbean rum heritage anchors formulation expertise across coastal consumption clusters. Brazilian sugarcane derivatives feed ethanol supply chains for Latin American producers. Japanese precision fermentation techniques diffuse into quality stabilization protocols worldwide.
United States
Coastal metropolitan areas concentrate demand as beachfront hospitality procurement expands. The US TTB enforces strict formula approval timelines that constrain product development cycles. Florida resort chains and California boutique hotels drive sessionable daytime format adoption for poolside inventory.
Germany
Retail channels show appetite for heritage-brand bottling with carbon footprint labeling. The EU F-Gas Regulation pressures production facilities toward heat pump retrofits. Bavarian and North Rhine-Westphalian manufacturing sites face compressed compliance timelines through the forecast window.
Brazil
Sugarcane ethanol infrastructure supports cost-competitive spirit bases for regional formulation. ANVISA maintains distinct additive thresholds that complicate direct Western product porting. São Paulo and Rio de Janeiro metropolitan clusters concentrate both production capacity and premium consumption occasions.
Japan
Precision fermentation expertise enables extended shelf-life stability without quality degradation. METI standards govern alcohol-content disclosure and packaging material specifications. Tokyo and Osaka metropolitan corridors concentrate hospitality procurement for high-margin on-premise placement.
India
Rising disposable incomes in urban centers drive trial conversion for premium imported formats. FSSAI maintains distinct alcohol-content thresholds and additive regulations versus Western formulations. Maharashtra and Karnataka state markets exhibit densest retail channel development for ready-to-serve adoption.
Ready to Serve Cocktails Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue craft-distillery positioning and regional flavor specialization. The vendor base stratifies across multinational spirits conglomerates, legacy brewers diversifying into spirits-adjacent formats, and boutique distilleries scaling canning infrastructure. Three archetypes dominate: heritage rum houses leveraging Caribbean provenance, diversified beverage conglomerates optimizing cross-category distribution, and regional craft operators capturing local taste preferences. Competitive moves concentrate on co-packer network expansion and aluminum can supply contract securing.
Within the heritage spirits tier, Bacardi Limited and Diageo plc exemplify scale-driven formulation capabilities and established Caribbean and British distilling traditions respectively. Constellation Brands occupies a position representing North American beverage conglomerate diversification into agave-based expressions. These three anchors demonstrate how geographic origin and corporate structure shape strategic optionality across packaging format and flavor profile investments.
| Leading Market Players |
|---|
| Bacardi Limited |
| Suntory Holdings |
| Anheuser-Busch InBev |
| Carlsberg |
| Heineken |
| Diageo plc |
| Brown-Forman |
| Constellation Brands |
| Pernod Ricard |
| Others |
Value Network & Pricing Analysis
Florida resort chains' unbundling of inventory into occasion-based SKUs for poolside and brunch consumption is forcing co-packers to reconfigure production lines for smaller batch runs, compressing margins on standard-format contracts while rewarding flexible packaging infrastructure with pricing premiums.
Pricing Analysis
Warranty and service bundling separates contract terms in this market, with formulation stability guarantees and expedited TTB approval support commanding 15-20% markups over transactional spot purchasing. Three-tier pricing structure across premium, standard, and economy levels stratifies by ABV target and shelf-life specification, with spirits-forward formulations capturing trade-up revenue. Cost compression in the canned format segment is intensifying because aluminum can supply concentration limits negotiating leverage for mid-tier producers. Hospitality procurement teams exhibit lowest price sensitivity due to backbar placement value, while mass-market retail buyers drive aggressive promotional calendar negotiations.
Supply Chain Analysis
TTB formula approval and EU F-Gas Regulation compliance certification gates supplier qualification, extending vendor onboarding timelines beyond comparable non-alcoholic beverages. Manufacturing concentrates in the United States, Germany, and Brazil, with Caribbean rum feedstock anchoring tropical formulation supply. Raw material dependencies center on aluminum can sheet, nitrogen dosing systems, and aseptic canning equipment. Single-source vulnerability runs through North American smelter capacity for the fastest-growing format segment. Distribution runs through co-packer networks with alcohol-handling certifications, consolidating last-mile delivery to hospitality accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
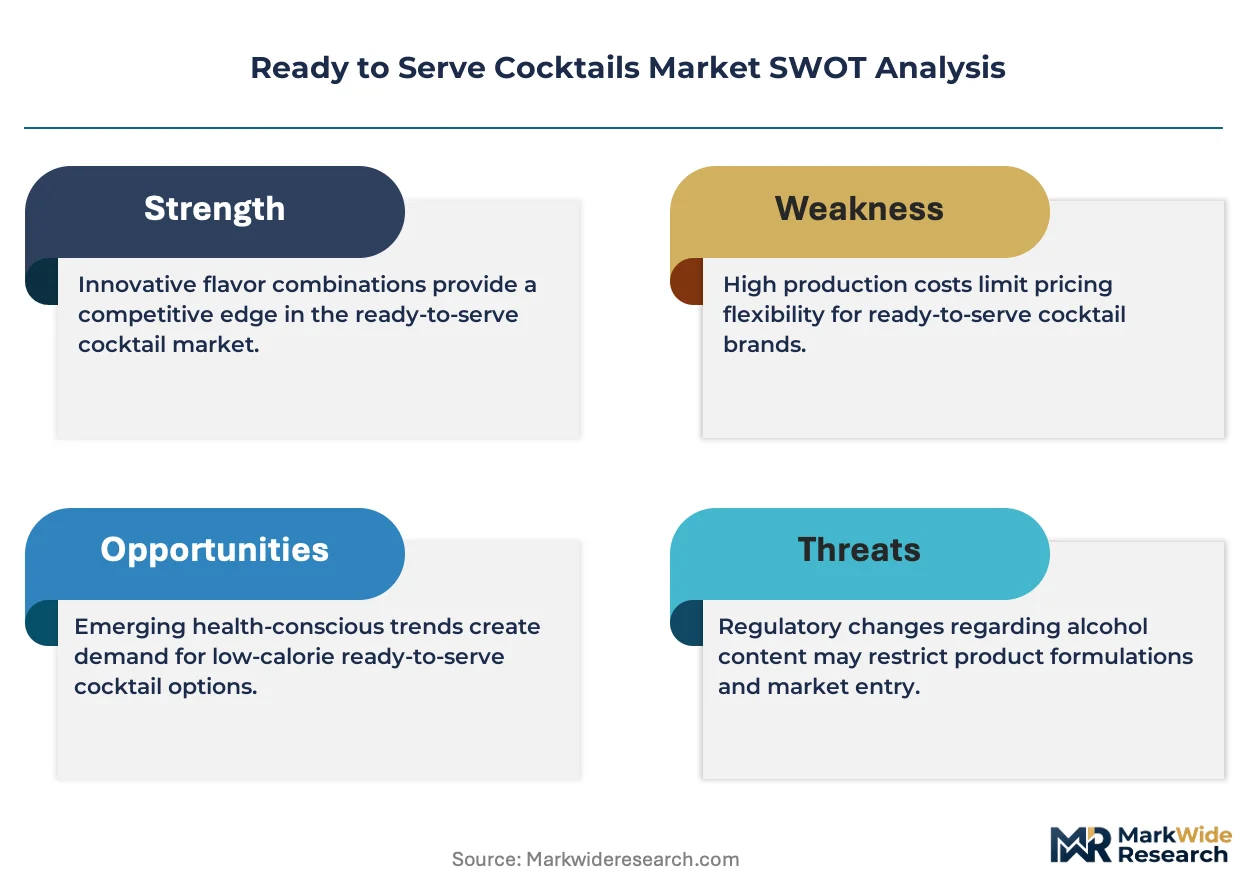
Aluminum can supply concentration and TTB approval bottlenecks are consolidating competitive position around capital-rich incumbents with secured input contracts and in-house regulatory affairs capacity, forcing craft-scale entrants toward niche flavor specialization or exit.
For Market Incumbents: Extend co-packer certification timelines into competitive moats by acquiring minority stakes in third-party production facilities with alcohol-handling licenses, securing capacity priority during input volatility. Deepen backward integration into aluminum can supply contracts with North American smelters to defend margin position against emerging entrants dependent on spot purchasing. The threat of craft-distillery scale-up in sun-belt states demands preemptive shelf-space investments in Latin culinary-influence markets. For New Entrants and Emerging Players: Cross-border e-commerce alcohol framework liberalization in select US states opens a window for direct-to-consumer channel development bypassing traditional three-tier distribution. White-space exists in Mexican-inspired agave expressions for poolside consumption occasions in Florida and coastal California, where heritage brands under-index. A regulatory-first go-to-market strategy targeting FSSAI-compliant formulations for Maharashtra and Karnataka bypasses saturated Western markets. For Investors and Strategic Acquirers: The window for entry favors craft-distillery operators with captive canning infrastructure and established TTB formula libraries. Long-term viability hinges on aluminum supply contract duration and co-packer network density rather than brand equity alone. The signal to watch is TTB approval queue length expansion, which indicates regulatory friction favoring incumbents with dedicated compliance teams and pressures valuations for acquisition targets lacking this capability.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Canning Technology Deployment | Nitrogen dosing systems extend shelf-life for low-ABV formulations targeting Florida resort procurement cycles. |
| Co-Packer Network Expansion | Alcohol-handling facility certification reduces go-to-market friction for boutique hotel chain adoption. |
| Regulatory Compliance Infrastructure | TTB formula approval expertise compresses product development timelines versus competitor submissions. |
| Agave Expression Portfolio Extension | Tequila-based formats capture unmet demand in sun-belt states with Latin culinary influence. |
| Sustainability Repositioning | EU F-Gas Regulation compliance enables German and Dutch retail channel access with carbon footprint labeling. |
Research Methodology
SEC 10-K filings, TTB formula approval databases, and EU packaging waste directive compliance records formed the secondary backbone, cross-referenced with primary interviews with beverage directors at coastal resort chains, co-packer operations managers, and aluminum procurement leads at canning facilities. Bottom-up and top-down triangulation validated volume estimates against customs records and hospitality procurement surveys.
Bottom-up modeling anchored volume projections in segment-level consumption occasion analysis, while top-down constraints applied macroeconomic filters across the projection horizon. Segmentation dimensions included packaging format, ABV tier, flavor profile, and channel economics. CAGRs derived from weighted average of historical trend extrapolation and scenario-adjusted elasticity modeling, with aluminum price volatility and TTB approval throughput as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for aseptic canning equipment would alter the outlook if nitrogen dosing systems displace alternative preservation methods faster than baseline assumptions. Forecasts embed assumptions regarding regulatory enforcement intensity and input material availability. A model refresh is warranted upon material change in aluminum smelter capacity utilization or TTB staffing levels affecting formula approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Australia and New Zealand Tequila Market