
 North America Spirulina Extract Market | 2026-2036
North America Spirulina Extract Market Size, Share, and Industry Trends Forecast 2026-2036
North America Spirulina Extract Market Analytics
The capital-intensity divergence between integrated cultivators and contract processors is bifurcating competitive dynamics across the North America spirulina extract landscape. Cyanotech Corporation leverages its Kona, Hawaii-based open-pond cultivation infrastructure to sustain year-round phycocyanin yields independent of continental climate volatility. DIC Corporation anchors its position through captive supply chains spanning Japanese parent technology and North American extraction capacity. Earthrise Nutritionals dominates California's Imperial Valley with controlled-environment raceway systems that compete on batch consistency for pharmaceutical-grade contracts.
North America spirulina extract comprises dried and processed biomass of Arthrospira platensis and Arthrospira maxima, typically standardized to phycocyanin concentrations between 5% and 25% by dry weight for commercial applications. The material functions primarily as a natural colorant, protein fortifier, and antioxidant active in food matrices and supplement formulations. Powder formats occupy the largest volume share within product type segmentation, though capsules are pulling ahead in pharmacy and practitioner channels where dosing precision commands premium positioning. Food & Beverage applications retain structural dominance in absolute tonnage, while Cosmetics represents the fastest-expanding margin pool as clean-label brands reformulate away from synthetic colorants.
The FDA exercises oversight through cGMP regulations for dietary supplements and New Dietary Ingredient pre-market notifications, while Health Canada/PMRA governs parallel import streams through Natural Health Product licensing requirements. The USDA National Organic Program certifies cultivation inputs and handling protocols, creating tiered market access where uncertified biomass faces exclusion from premium channels. Stakeholders must monitor pending FDA guidance on algae-derived ingredients in conventional foods, as any reclassification would reshape formulation strategies across CPG portfolios.
Market Dynamics
The FDA's cGMP enforcement escalation and New Dietary Ingredient notification backlog are compressing market entry timelines while concentrating procurement among established cultivators with compliant infrastructure.
Growth Catalysts
- USDA Organic certification tier:California's functional food cluster demands certified biomass, locking in premium channel access for compliant suppliers.
- Clean-label reformulation mandates:Cosmetics brands are eliminating synthetic colorants, redirecting formulation spend toward phycocyanin-derived alternatives.
- Pacific Northwest nutraceutical corridor:Contract manufacturers in Oregon and Washington are expanding dedicated spirulina extraction capacity to serve practitioner channels.
Market Restraints
- Energy input cost volatility:Controlled-environment raceway systems face margin pressure from electricity rate fluctuations in California's Imperial Valley.
- Single-source geography risk:Hawaii-based open-pond cultivation concentrates climate exposure in one volcanic soil zone.
- Pharmaceutical-grade batch inconsistency:Natural algae variability limits standardization below synthetic colorant performance thresholds.
Strategic Opportunities
- Canadian Natural Health Product licensing:Health Canada/PMRA's streamlined approval pathway offers faster market access than FDA NDI timelines.
- Texas functional beverage manufacturing:Underdeveloped spirulina sourcing infrastructure creates first-mover positioning for extraction facilities near Dallas-Fort Worth.
- Photobioreactor-automation convergence:Closed-system cultivation combined with AI-driven nutrient dosing promises yield stability independent of seasonal variation.
Industry Challenges
- Phycocyanin quantification skill scarcity:Analytical chemists with algae-specific spectrophotometry expertise command premium compensation in tight labor markets.
- USDA Organic handler certification timelines:Multi-month approval windows delay new entrant access to premium-priced retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Spirulina Extract Market |
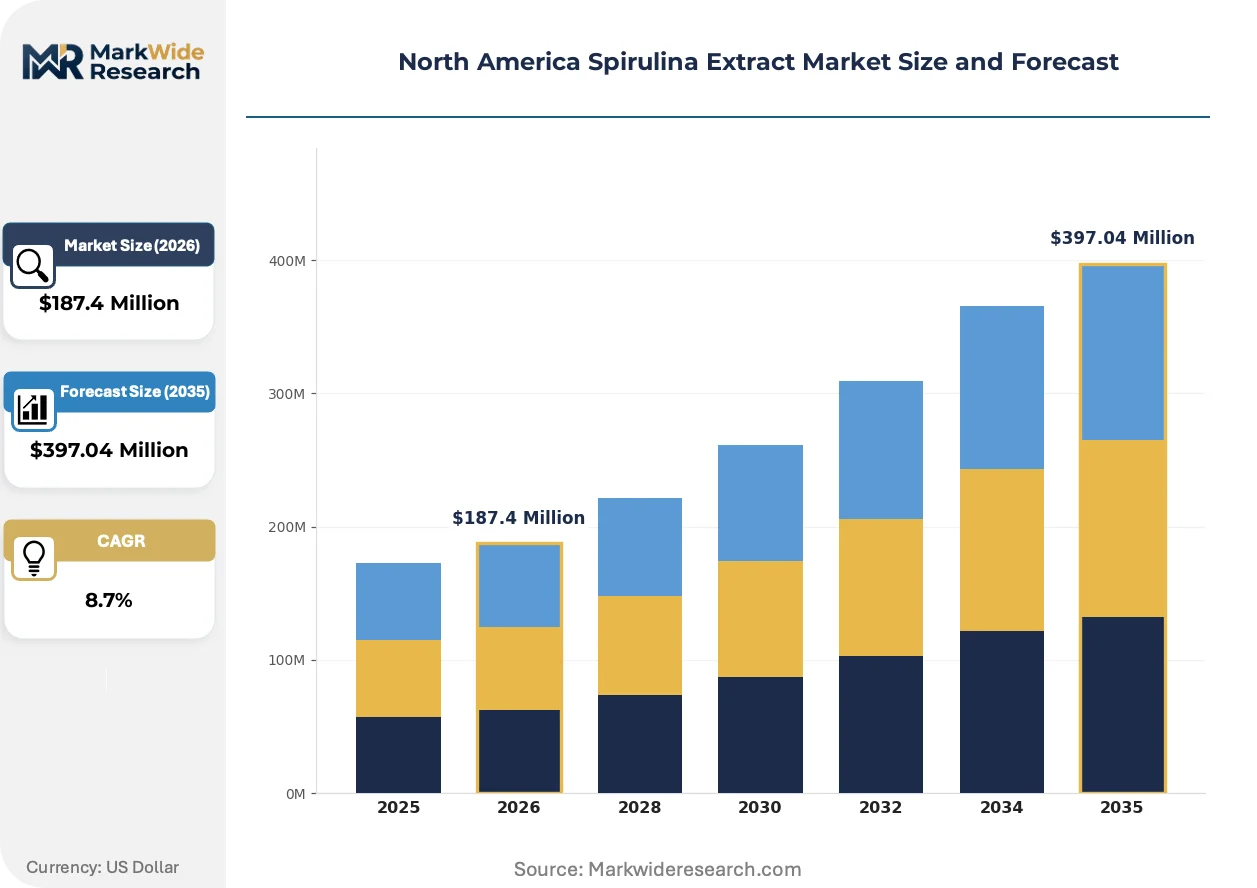
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablets, Capsules, Flakes Application: Food & Beverage, Nutraceuticals, Dietary Supplements, Cosmetics End User: Retail Consumers, Health Clubs, Food Manufacturers, Cosmetic Companies Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Chr. Hansen A/S, Dohler Group, Cyanotech Corporation, Givaudan, Aim Grow Biotech Co. Ltd, DIC Corporation, DDW The Color House, Earthrise Nutritionals, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Spirulina Extract Market Evolving Landscape
Photobioreactor technology is compressing cultivation cycles while regulatory clarity around algae-derived ingredients in conventional foods is reshaping formulation strategies across CPG portfolios.
Closed photobioreactor systems with LED-optimized light spectra are supplanting open-pond raceways in pharmaceutical-grade contract manufacturing. Precision nutrition brands in California and the Pacific Northwest are adopting these systems to guarantee phycocyanin concentrations above 20% dry weight. The shift is compressing batch-to-batch variability premiums that previously favored synthetic colorants.
Health Canada/PMRA's evolving Natural Health Product monograph for algae-derived ingredients is tightening purity specifications for heavy metals and microcystin contamination. Extraction facilities serving cross-border supply chains are retrofitting filtration infrastructure to meet the stricter Canadian thresholds. Dietary supplement brands with dual US-Canada distribution are reformulating around the higher standard to maintain single-SKU efficiency.
Practitioner-channel buyers are consolidating procurement around capsule formats with third-party phycocyanin assay certificates. Compounding pharmacies and integrative medicine clinics are displacing mass-market powder SKUs in their formulary recommendations. The behavior shift concentrates most visibly in California's Bay Area and Seattle metropolitan corridors where functional medicine adoption rates exceed national baselines.
North America Spirulina Extract Market Segmentation
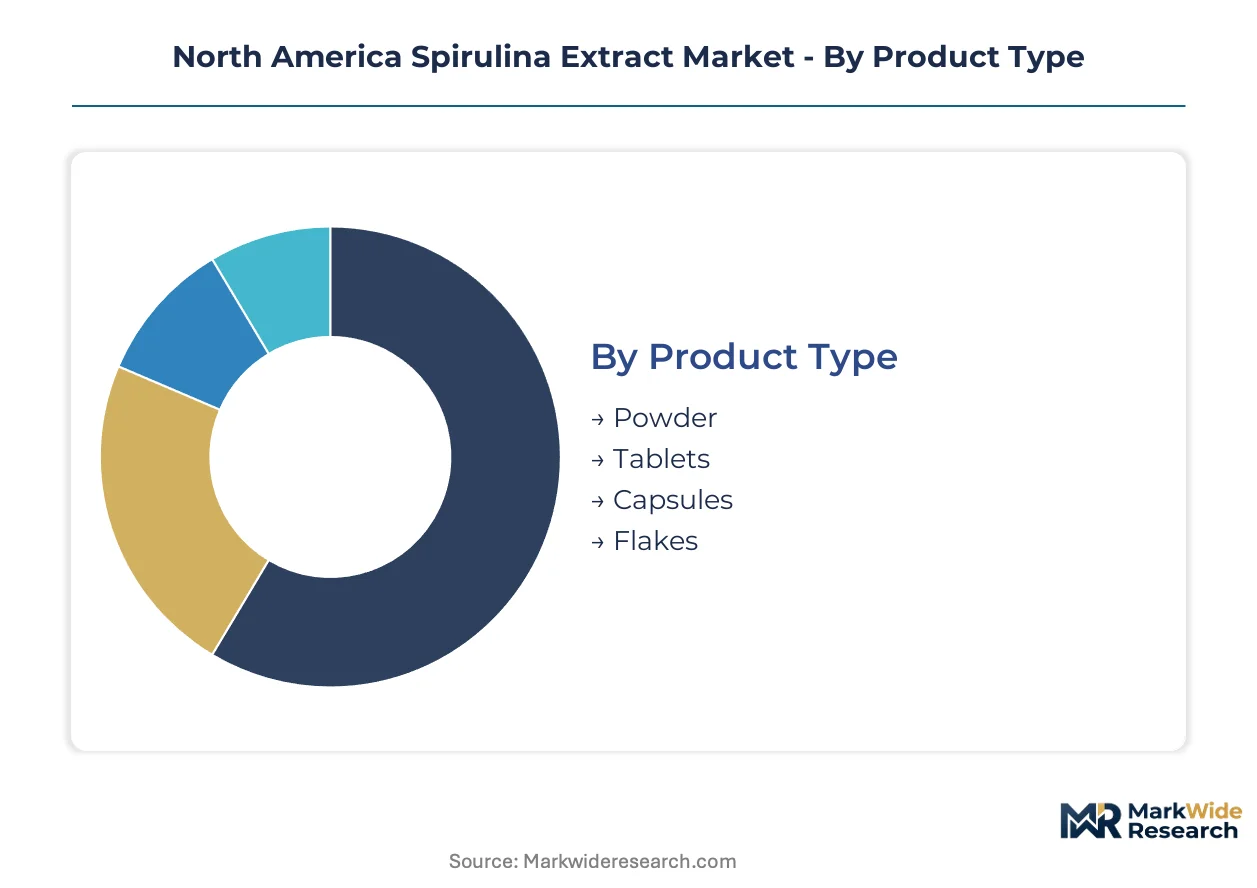
Channel dynamics in the North America spirulina extract market diverge sharply between bulk ingredient procurement and finished consumer goods. Understanding which segments flow through practitioner networks versus mass retail determines pricing power and compliance burden for suppliers.
Product Type:
Powder dominates bulk ingredient channels serving food manufacturers and contract supplement processors, while precision-dosed formats capture pharmacy and clinic procurement.
- Powder:Standardized biomass with phycocyanin concentrations between 5% and 25% dry weight serves as the foundational input for food fortification and bulk supplement manufacturing. California's functional food cluster and Pacific Northwest nutraceutical corridor absorb the majority of volume through direct B2B procurement. Powder's bulk density advantages minimize freight costs for cross-border shipments to Canadian Natural Health Product manufacturers.
- Capsules:Hard-shell and soft-gel encapsulation delivers dosing precision demanded by practitioner channels and compounding pharmacies. Third-party phycocyanin assay certificates have become mandatory for formulary inclusion in California's Bay Area and Seattle metropolitan integrative medicine clinics. Capsule formats command premium positioning through pharmacy and practitioner networks where reimbursement documentation requires exact active content.
- Tablets:Compressed formats with binders and coatings target mass-market supplement shelves where swallowability and shelf stability outweigh purity premiums.
- Flakes:Textured biomass appeals to specialty food applications and pet nutrition formulations seeking visual differentiation from standard powders.
By volume, Powder leads. By growth pace, Capsules are expanding most quickly.
Application:
Margin structures vary threefold across applications, with pharmaceutical-grade contracts demanding batch consistency that open-pond cultivation cannot reliably deliver.
- Food & Beverage:Natural blue colorant replacement drives reformulation in beverage, confectionery, and dairy applications seeking clean-label positioning. FDA pending guidance on algae-derived ingredients in conventional foods creates formulation uncertainty that favors early-mover brands with established supplier relationships. Phycocyanin's protein fortification function adds secondary value in sports nutrition and plant-based product lines.
- Cosmetics:Elimination of synthetic colorants redirects formulation spend toward phycocyanin-derived alternatives in skincare and color cosmetics. Clean-label mandates from Sephora, Ulta, and direct-to-consumer beauty brands are accelerating specification adoption. The segment's tolerance for premium pricing supports photobioreactor-cultivated biomass with guaranteed phycocyanin concentrations above 20%.
- Nutraceuticals:Practitioner-channel brands emphasize immune support and antioxidant positioning through clinically dosed phycocyanin extracts.
- Dietary Supplements:Mass-market positioning competes on cost per serving with other protein and antioxidant ingredients in crowded retail shelves.
Food & Beverage holds the volume base. Cosmetics generates the steepest margin expansion.
End User:
Procurement sophistication separates institutional buyers with in-house quality labs from retail consumers dependent on third-party certifications.
- Food Manufacturers:Large-scale CPG and functional food brands conduct vendor audits and require USDA Organic handler certification for premium channel access. California's cluster demands certified biomass with documented heavy metal and microcystin testing below Canadian Natural Health Product thresholds.
- Cosmetic Companies:Formulation chemists prioritize color stability and batch consistency for product lines reformulating away from synthetic dyes. Clean-label brand mandates from marketing departments override procurement cost minimization.
- Health Clubs:On-site smoothie bars and retail counters represent fragmented, low-volume procurement with limited quality verification capacity.
- Retail Consumers:E-commerce and mass retail purchases rely on label claims and third-party certifications without direct supplier relationships.
Food Manufacturers concentrate procurement volume. Cosmetic Companies are gaining share fastest as clean-label reformulation accelerates.
Distribution Channel:
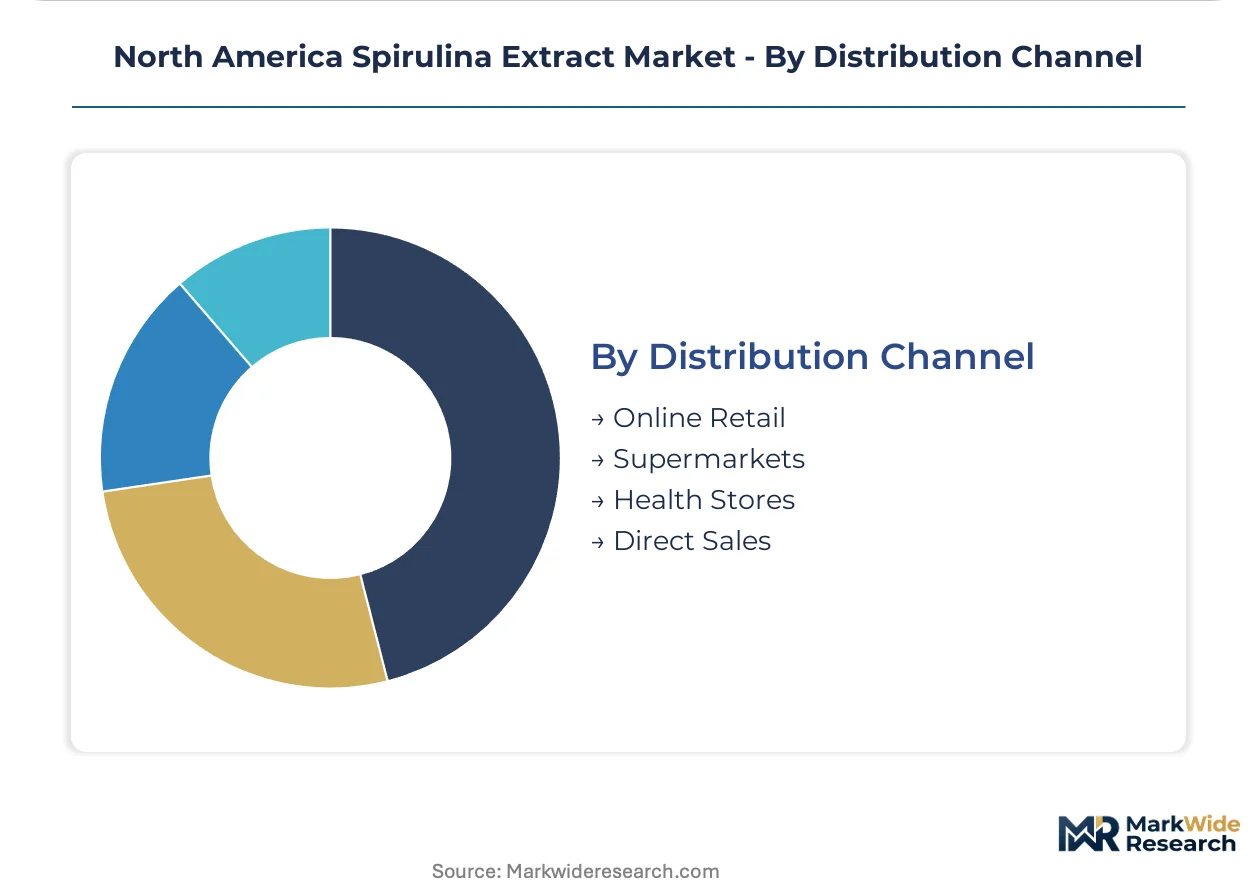
Channel selection determines margin capture, with direct sales preserving the most value and mass retail surrendering the deepest discounts.
- Online Retail:Amazon, Thrive Market, and direct-to-consumer brand sites aggregate fragmented demand with algorithmic search visibility determining SKU survival. Subscription models in practitioner-adjacent brands reduce customer acquisition costs and improve lifetime value metrics.
- Health Stores:Whole Foods, Sprouts, and independent natural retailers enforce USDA Organic certification and non-GMO verification as table stakes. Staff recommendation influence sustains premium pricing for capsule formats with visible third-party testing badges.
- Supermarkets:Mass-market grocery placement competes on shelf price with limited staff education and minimal quality differentiation signaling.
- Direct Sales:Practitioner-only and compounding pharmacy channels maintain the tightest quality specifications and highest price realization with documented phycocyanin assays.
Health Stores anchor volume in premium tiers. Online Retail shows the steepest expansion trajectory as subscription models penetrate practitioner-adjacent segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's functional food cluster commands premium pricing power over Texas and Midwest markets, while Canadian regulatory pathways accelerate product approval timelines relative to FDA processes in the United States.
United States
Dietary supplement brands in California's functional food cluster and the Pacific Northwest nutraceutical corridor are accelerating procurement of certified organic spirulina powders. The FDA's New Dietary Ingredient notification requirements and evolving cGMP enforcement elevate compliance costs for new entrants. Hawaii-based open-pond cultivation at Kona sustains year-round phycocyanin yields independent of continental climate volatility.
Canada
Health Canada/PMRA's Natural Health Product licensing offers streamlined approval pathways faster than FDA NDI timelines, attracting cross-border formulation strategies. Extraction facilities serving dual US-Canada distribution are retrofitting filtration infrastructure to meet stricter Canadian thresholds for heavy metals and microcystin contamination. Ontario and British Columbia manufacturers concentrate procurement for practitioner-channel capsule formats.
Mexico
Emerging functional beverage manufacturing in the Bajío Region and northern border states creates first-mover positioning for extraction facilities seeking proximity to US distribution networks. Mexican regulators are aligning food additive standards with FDA frameworks to facilitate ingredient imports. Guadalajara's growing nutraceutical packaging cluster supports regional formulation capabilities.
North America Spirulina Extract Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America spirulina extract landscape. Integrated cultivators with captive biomass supply compete against contract processors dependent on third-party sourcing. Three archetypes dominate: Hawaiian open-pond specialists, California controlled-environment raceway operators, and Japanese-parented multinationals with cross-border extraction networks. Competitive moves concentrate on photobioreactor automation partnerships and USDA Organic handler certification acquisitions.
Among Hawaii-based cultivators, Cyanotech Corporation exemplifies the integrated open-pond archetype with volcanic soil zone concentration. California's Imperial Valley hosts Earthrise Nutritionals as a representative of controlled-environment raceway systems competing on batch consistency. Japanese-parented DIC Corporation anchors the multinational extraction tier with technology transfer from parent operations. These three occupy positions across the technology-cost spectrum without overlapping strategic footprints.
| Leading Market Players |
|---|
| Chr. Hansen A/S |
| Dohler Group |
| Cyanotech Corporation |
| Givaudan |
| Aim Grow Biotech Co. Ltd |
| DIC Corporation |
| DDW The Color House |
| Earthrise Nutritionals |
| Sensient Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Phycocyanin substitution for synthetic Blue 1 is compressing supply geography toward USDA Organic-certified cultivation zones while elevating price premiums for batch-consistent biomass. California's functional food cluster and Hawaii's volcanic soil cultivation districts now anchor pricing power as cosmetic brands absorb photobioreactor cost premiums for guaranteed phycocyanin concentrations above 20% dry weight.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade contracts with documented assay certificates commands spreads exceeding 40% above standard powder grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by USDA Organic certification and phycocyanin concentration tiers. Price differentiation hinges on third-party testing documentation and captive cultivation versus contract-sourced biomass. Cost compression in standard powder tiers is intensifying because California electricity rate volatility pressures controlled-environment raceway operators. Mass-market supplement buyers exhibit highest price sensitivity while practitioner-channel capsule procurement absorbs premium positioning.
Supply Chain Analysis
Strategic stockpile preferences dominate among food manufacturers seeking buffer inventory against phycocyanin batch variability, while cosmetic brands favor just-in-time procurement from photobioreactor operators with guaranteed specifications. Supply concentrates in the United States, Canada, and Mexico with cultivation anchored in Hawaii, California, and emerging Texas extraction infrastructure. Raw material dependencies include volcanic soil-based open-pond systems, LED-optimized photobioreactors, and USDA Organic-certified nutrient inputs. Single-source geography risk in Hawaii's Kona district creates vulnerability to volcanic activity and climate disruption. Distribution runs through direct B2B procurement for bulk powder, practitioner-only channels for precision-dosed capsules, and health store retail for premium consumer formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America spirulina extract market functions as a certification-attach opportunity where USDA Organic handler status and third-party phycocyanin assay services expand recurring revenue faster than raw biomass cultivation. Subscription-based practitioner channel procurement and compounding pharmacy formulary services now outpace hardware-equivalent powder volume growth.
For Market Incumbents: Fortify position through backward integration into photobioreactor automation partnerships and captive USDA Organic certification capacity. Cyanotech Corporation's Hawaii-based open-pond infrastructure and Earthrise Nutritionals' controlled-environment raceways demonstrate how geographic diversification mitigates single-source climate risk. Prioritize Health Canada/PMRA Natural Health Product licensing to accelerate cross-border approval timelines relative to FDA NDI bottlenecks. Channel control through direct sales to practitioner networks preserves margin realization against mass retail price erosion. For New Entrants and Emerging Players: Differentiate on Texas functional beverage manufacturing proximity where spirulina sourcing infrastructure remains underdeveloped. The Dallas-Fort Worth corridor offers first-mover positioning for extraction facilities serving emerging CPG brands. Target cosmetic company procurement where clean-label reformulation mandates override cost minimization priorities. Pursue go-to-market alignment with Pacific Northwest nutraceutical contract manufacturers expanding dedicated extraction capacity for practitioner channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with California-controlled-environment raceway operators facing margin pressure from electricity rate volatility and Hawaiian open-pond specialists concentrated in volcanic soil zones. Long-term viability over the coming decade hinges on photobioreactor-automation convergence and AI-driven nutrient dosing capabilities. Acquisition focus should center on extraction facilities with dual US-Canada regulatory compliance infrastructure. The signal to watch is FDA guidance finalization on algae-derived ingredients in conventional foods, which would trigger reformulation demand inflection across CPG portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Automation Partnership | AI-driven nutrient dosing from precision agriculture vendors compresses batch-to-batch variability premiums. |
| USDA Organic Handler Certification Acquisition | California functional food cluster procurement locks out uncertified biomass from premium channel access. |
| Health Canada Natural Health Product Licensing | Streamlined PMRA approval pathways accelerate market entry versus FDA NDI notification backlogs. |
| Texas Extraction Facility Buildout | Dallas-Fort Worth proximity captures emerging functional beverage manufacturing demand with limited incumbent presence. |
| Practitioner Channel Direct Sales Expansion | Compounding pharmacy and integrative medicine clinic procurement commands highest price realization with documented assays. |
Research Methodology
Desk research of FDA cGMP guidance documents, Health Canada Natural Health Product monographs, and USDA National Organic Program standards preceded structured interviews with dietary supplement brand procurement directors, cosmetic formulation chemists, and nutraceutical contract manufacturing executives. Primary fieldwork with California functional food cluster stakeholders and Pacific Northwest extraction facility operators combined with secondary validation through SEC filings of publicly traded cultivators and customs records of spirulina biomass trade flows. Bottom-up volume modeling across powder, capsule, tablet, and flake formats triangulated against top-down market sizing from end-use application demand.
Variance decomposition across the projection horizon isolates volume, price, and mix effects by product type, application, and distribution channel dimensions. Segmentation modeling incorporates cultivation technology tier, phycocyanin concentration grade, and regulatory compliance status as forecast drivers. CAGRs derive from historical trajectory analysis adjusted for technology adoption curves and regulatory pathway acceleration effects. Forecast inputs include electricity rate projections for California controlled-environment operations and Health Canada/PMRA monograph evolution timelines.
Material uncertainties — FDA guidance finalization on algae-derived ingredients in conventional foods, California electricity rate volatility, and Hawaiian volcanic activity — sit outside the modeled envelope. Forecasts reflect assumptions around photobioreactor adoption pace and practitioner channel procurement consolidation. Revision becomes warranted when Health Canada/PMRA heavy metal and microcystin thresholds tighten beyond current retrofit capacity or when synthetic colorant regulatory restrictions accelerate phycocyanin substitution demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Asia-Pacific Beta-Glucan Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market