
 Liquor Flavored Ice Cream Market | 2026-2036
Liquor Flavored Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Liquor Flavored Ice Cream Market Foresight
Multi-pack bundling of single-serve alcohol-infused cups is recalibrating how consumers sample flavor varieties without committing to full pints. Tipsy Scoop leverages its brick-and-mortar scoop shops to control direct-to-consumer channel access. Haagen-Dazs sustains premium positioning through restrained alcohol integration that emphasizes dessert experience over intoxication. Mercer's Dairy anchors its competitive stance in upstate New York with farm-fresh dairy sourcing and regional distribution density.
Liquor flavored ice cream denotes frozen dairy or non-dairy desserts incorporating distilled spirits or liqueurs at concentrations typically below five percent alcohol by volume, requiring controlled-temperature homogenization to prevent alcohol-induced freezing point depression from destabilizing emulsion structure. The category serves adult consumers seeking novel sensory experiences that merge confectionery indulgence with cocktail culture associations. Premium Ice Cream commands the dominant value share due to higher permissible alcohol thresholds and superpremium pricing architecture, while Gelato attracts culinary enthusiasts through denser mouthfeel and intensified flavor delivery. Whiskey and Rum profiles lead flavor adoption in North American markets, reflecting established brown-spirit consumption patterns that transfer readily to dessert applications.
FDA alcohol labeling mandates and state-level dairy pasteurization codes create a bifurcated compliance landscape that elevates entry costs for new entrants lacking regulatory affairs infrastructure. The Alcohol and Tobacco Tax and Trade Bureau intersects with state liquor control boards to determine whether products classify as confectionery or alcoholic beverages, directly affecting distribution channel permissions and age verification requirements. Stakeholders must monitor evolving state-by-state classification determinations and invest in formulation flexibility that permits rapid alcohol content adjustment without compromising texture stability or flavor integrity.
Market Dynamics
FDA alcohol labeling mandates intersect with state liquor control board classifications to create a bifurcated compliance landscape that elevates entry costs and fragments distribution permissions across jurisdictions.
Growth Catalysts
- Multi-serve sampling formats:Single-serve cup bundling lowers trial barriers for flavor experimentation in premium ice cream parlors and specialty dessert shops.
- Controlled-temperature homogenization:Advances in emulsion stabilization technology permit higher alcohol thresholds without freezing point depression destabilizing product texture.
- Coastal metropolitan concentration:Dense demand clusters in United States coastal cities support direct-to-consumer channel economics and localized flavor development.
Market Restraints
- Dairy input volatility:Farm-fresh dairy sourcing requirements tie margins to regional milk price fluctuations and seasonal supply constraints.
- Regulatory classification friction:Alcohol and Tobacco Tax and Trade Bureau determinations vary by state, forcing parallel compliance tracks for confectionery versus alcoholic beverage designation.
- Substitute indulgence competition:Craft cocktail bars and ready-to-drink canned cocktails capture overlapping adult novelty-seeking occasions.
Strategic Opportunities
- Non-dairy base expansion:Oat and coconut milk formulations open allergen-sensitive and vegan-adjacent consumer segments previously excluded from dairy-dependent offerings.
- Age-gated retail channels:Dedicated adult dessert boutiques bypass conventional grocery slotting fees while enabling experiential marketing and controlled sampling environments.
- Flavor profile localization:Tequila and mezcal variants tailored to southwestern United States taste preferences leverage established agave spirit consumption patterns.
Industry Challenges
- Formulation talent scarcity:Food scientists capable of balancing alcohol integration with texture stability command premium compensation in a shallow labor pool.
- Cold chain integrity requirements:Maintaining precise temperature controls through last-mile delivery networks demands specialized fleet investments and real-time monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquor Flavored Ice Cream Market |
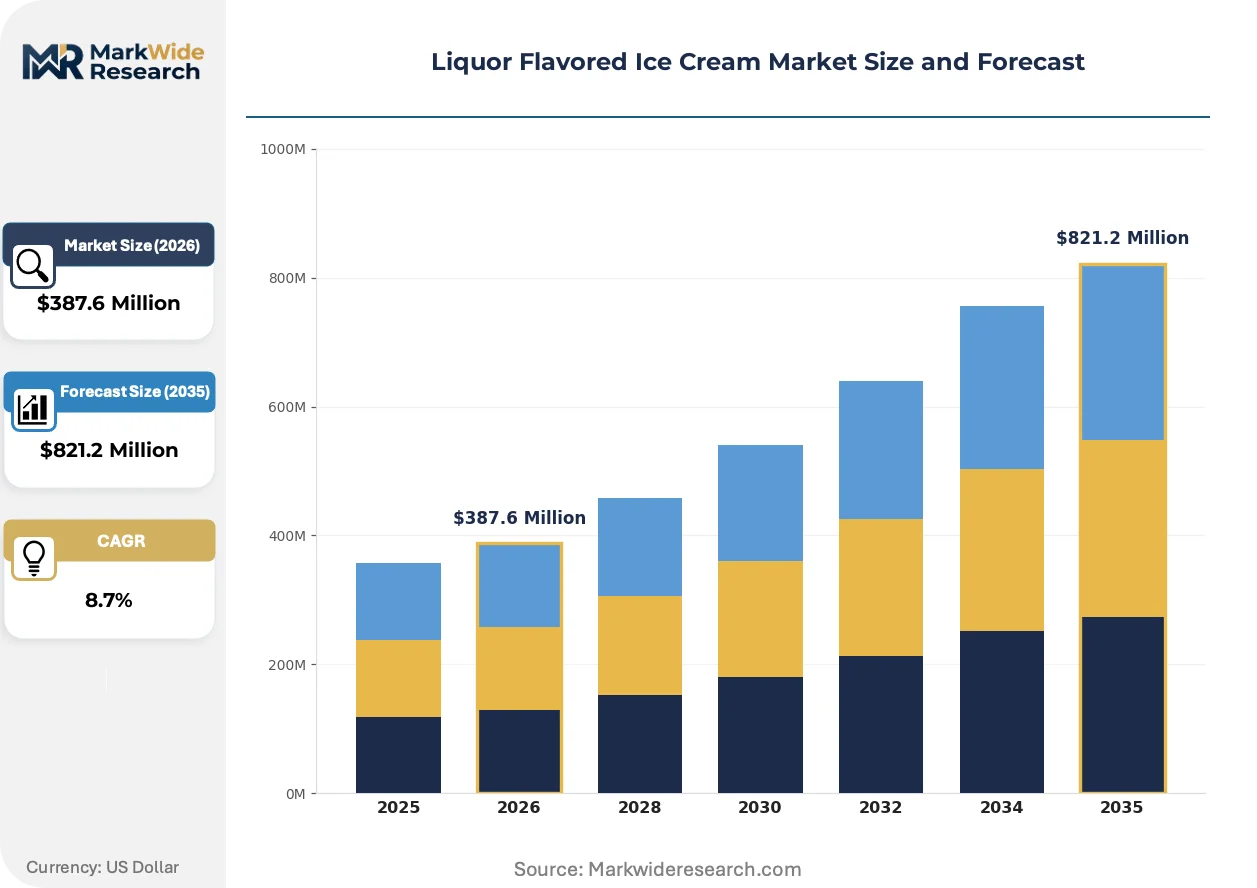
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelato, Sorbet, Soft Serve, Premium Ice Cream Flavor Profile: Whiskey, Rum, Vodka, Tequila Ingredient Source: Organic, Natural, Synthetic, Premium Target Consumer: Adults, Culinary Enthusiasts, Health-Conscious Consumers, Event Planners |
| Companies Covered | Tipsy Scoop, Haagen-Dazs, Mercer's Dairy, Ben & Jerry's, Buzz Bar, Frozen Pints, SnoBar Cocktails, Salt & Straw, Jeni's Splendid Ice Creams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquor Flavored Ice Cream Market Shifts & Advancements
Alcohol-infused frozen dessert production is converging with precision fermentation and flavor encapsulation techniques that reshape formulation possibilities and manufacturing economics.
Microencapsulation technology is unifying alcohol stability with extended shelf-life performance. Premium ice cream manufacturers deploy lipid-based encapsulation systems to prevent alcohol migration and flavor degradation during frozen storage. This convergence compresses reformulation cycles and enables cleaner label positioning.
State-level pasteurization code harmonization efforts are reducing interstate distribution friction. The National Conference on Food Protection model code adoption is creating regulatory alignment corridors that simplify multi-state market entry. Small-batch producers in upstate New York and coastal California markets are consolidating compliance documentation to exploit these alignment windows.
Direct-to-consumer subscription models are fragmenting traditional grocery channel dependence. Adult consumers in metropolitan United States markets now expect curated flavor assortments delivered on predictable replenishment cycles. This behavioral pivot is most visible in coastal cities where specialty dessert shops operate hybrid retail-subscription operations.
Liquor Flavored Ice Cream Market Segmentation
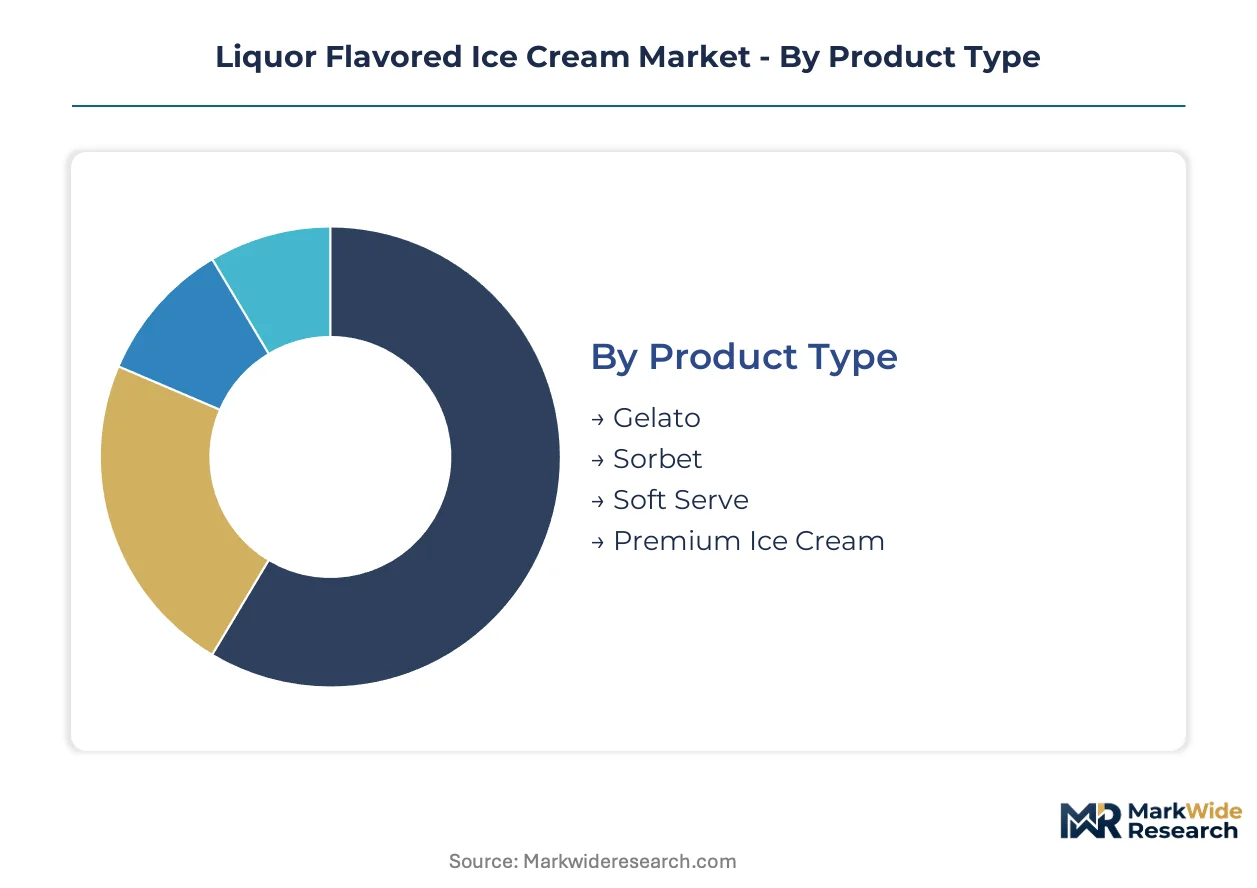
Liquor flavored ice cream segmentation reflects divergent consumer willingness to pay for alcohol integration, texture sophistication, and sourcing transparency. Manufacturers calibrate formulation complexity and channel strategy against these category boundaries to capture margin at distinct price tiers.
Product Type:
Cost tier separates casual purchasers from experiential buyers in this category.
- Premium Ice Cream:Higher butterfat bases accommodate elevated alcohol thresholds without emulsion breakdown. Demand concentrates in coastal metropolitan United States markets where direct-to-consumer parlors command superpremium pricing for controlled-temperature homogenization.
- Gelato:Denser overrun and lower serving temperatures intensify spirit flavor delivery through reduced fat interference. Culinary enthusiasts in specialty dessert shops drive adoption for its artisan positioning and intensified mouthfeel.
- Sorbet:Dairy-free formulations leverage fruit acid and alcohol synergy for clean-label positioning in allergen-sensitive segments.
- Soft Serve:Lower capital equipment requirements enable rapid flavor rotation in experiential retail formats.
Volume sits with Premium Ice Cream; growth tilts toward Gelato.
Flavor Profile:
Established spirit consumption patterns in target geographies determine flavor development priorities.
- Whiskey:Brown-spirit barrel characteristics transfer readily to caramel and vanilla base formulations. United States coastal metropolitan demand reflects established bourbon and rye consumption culture.
- Rum:Molasses and tropical fruit affinities suit multi-serve sampling formats in premium ice cream parlors. Caribbean and Latin American heritage markets in Florida and California anchor regional concentration.
- Vodka:Neutral alcohol profile permits cleaner flavor layering without competing taste compounds.
- Tequila:Agave spirit variants target southwestern United States taste preferences with localization potential.
Whiskey dominates current volume; Tequila claims the steepest expansion trajectory.
Ingredient Source:
Margin structure stratifies sharply between commodity dairy inputs and certified supply chains.
- Premium:Farm-fresh dairy sourcing with traceable provenance commands price premiums in upstate New York and coastal California markets. Mercer's Dairy leverages regional distribution density to defend this tier.
- Organic:USDA certification requirements add compliance overhead that limits entrant scale but secures shelf placement in natural channel grocers.
- Natural:Clean-label positioning without full organic certification captures cost-conscious quality seekers.
- Synthetic:Artificial flavor compounds and stabilizers serve price-sensitive foodservice accounts.
Premium captures value concentration; Organic is expanding most quickly.
Target Consumer:
Occasion-based purchasing separates impulse trial from planned replenishment behaviors.
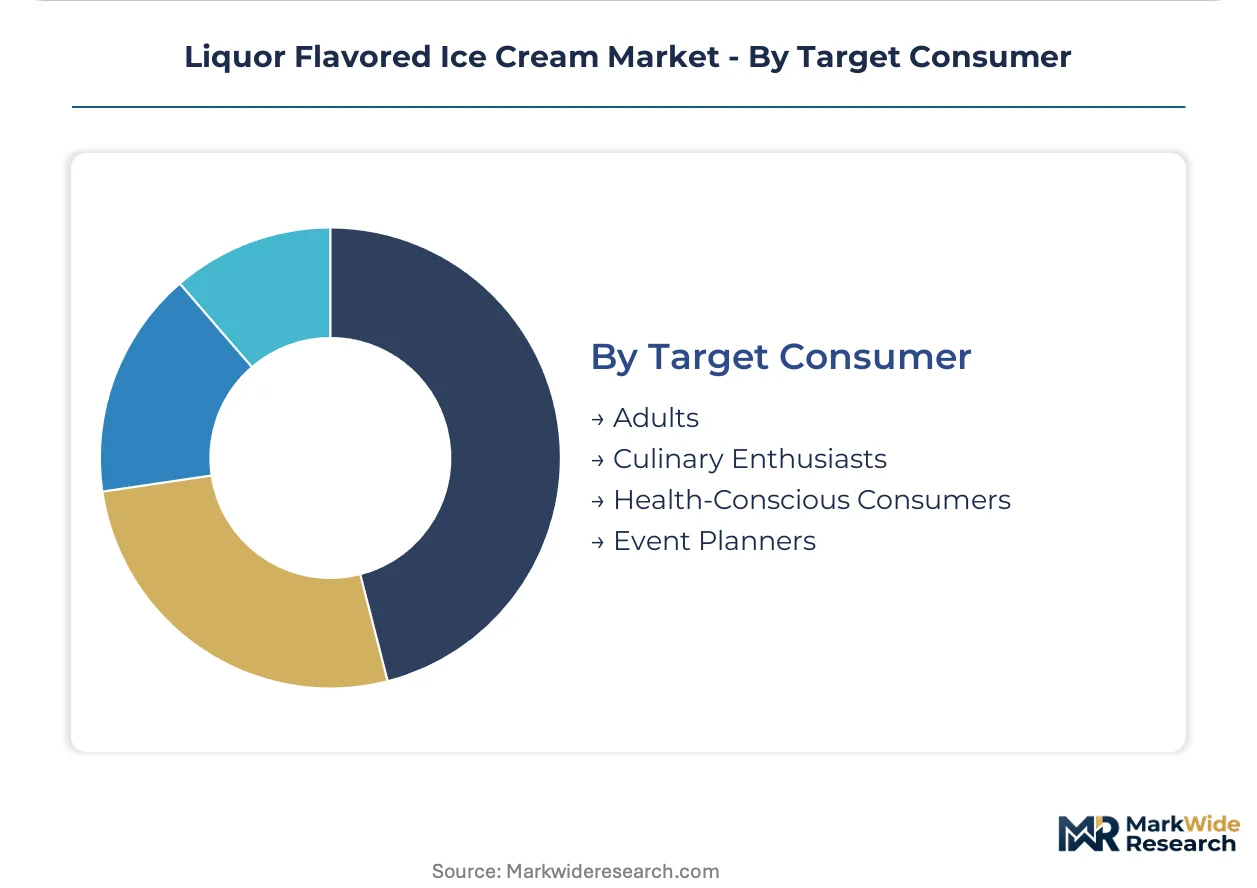
- Adults:Broad demographic seeking novelty experiences at social gatherings and private consumption occasions. FDA alcohol labeling compliance and age verification infrastructure shape channel access.
- Culinary Enthusiasts:Flavor-forward buyers prioritizing craft credentials and limited-batch releases. This segment sustains direct-to-consumer subscription economics in metropolitan markets.
- Health-Conscious Consumers:Calorie-aware buyers responsive to portion-controlled single-serve formats.
- Event Planners:B2B procurement for weddings and corporate functions demanding bulk customization.
Adults represent volume concentration; Culinary Enthusiasts are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in temperate dairy regions while consumption concentrates in affluent coastal metros. This geographic split shapes cold chain investments and flavor localization priorities across markets.
United States
Coastal metropolitan markets in California and New York drive premium-tier demand through direct-to-consumer parlor networks. FDA alcohol labeling mandates intersect with state liquor control board classifications, creating compliance fragmentation that elevates entry costs. Upstate New York anchors farm-fresh dairy sourcing clusters where Mercer's Dairy maintains regional distribution density.
Canada
Provincial liquor board retail monopolies constrain channel access but create protected shelf space for compliant entrants. Health Canada pasteurization standards align with FDA frameworks, simplifying cross-border formulation continuity. Toronto and Vancouver metropolitan areas concentrate culinary enthusiast demand for gelato-format products.
Germany
EFSA alcohol-in-food thresholds and BfR dairy safety protocols establish strict formulation boundaries for imported products. Bavaria and Baden-Württemberg host precision dairy processing infrastructure that supports contract manufacturing for European market entry. Berlin's experiential food retail scene incubates age-gated dessert boutique concepts.
United Kingdom
FSA novel food consultations and post-Brexit divergence from EU alcohol-in-confectionery standards create regulatory uncertainty for formulation planning. London's premium food hall networks provide high-visibility placement for imported American brands seeking European beachheads. Scottish whisky heritage regions supply flavor authenticity credentials for brown-spirit variants.
Australia
FSANZ alcohol labeling requirements and state-level dairy processing codes mirror North American bifurcation patterns. Sydney and Melbourne coastal metros replicate United States demand concentration for premium single-serve formats. Queensland dairy belt provides farm-fresh sourcing alternatives to seasonal New Zealand milk powder volatility.
Liquor Flavored Ice Cream Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-positioning bands. Market structure tilts toward fragmentation due to regulatory barriers that favor regional compliance expertise over scale economies. Three archetypes dominate: dairy-origin specialists leveraging farm-fresh provenance, alcohol-brand licensees extending spirit portfolios, and experiential retail operators controlling direct channel access. Competitive moves concentrate on flavor portfolio rotation speed and age-gated retail format expansion.
Among dairy-origin specialists, Mercer's Dairy exemplifies regional sourcing anchoring. Within the experiential retail tier, Tipsy Scoop occupies a position blending physical parlors with subscription logistics. Haagen-Dazs represents multinational scale advantages in formulation standardization across jurisdictions. These three entities illustrate how compliance infrastructure and channel control separate viable competitors from aspirational entrants.
| Leading Market Players |
|---|
| Tipsy Scoop |
| Haagen-Dazs |
| Mercer's Dairy |
| Ben & Jerry's |
| Buzz Bar |
| Frozen Pints |
| SnoBar Cocktails |
| Salt & Straw |
| Jeni's Splendid Ice Creams |
| Others |
Supply & Pricing Matrix
Class IV milk futures volatility cascades through farm-fresh dairy sourcing commitments into tiered pricing architectures that separate premium provenance claims from commodity formulations. Coastal metropolitan buyers absorb transport premiums for controlled-temperature homogenization, while inland markets trade off alcohol integration thresholds against cold chain economics.
Pricing Analysis
Margin tightening in the premium tier reflects farm-fresh dairy input premiums and FDA compliance documentation overhead. Three-tier pricing structure across superpremium, standard, and economy levels separates traceable-provenance products from natural-label and synthetic-stabilizer alternatives. Price differentiation centers on butterfat grade and alcohol integration certification tier. Cost compression in the economy segment accelerates because foodservice accounts prioritize portion-controlled unit costs over craft positioning. Culinary enthusiasts in direct-to-consumer channels exhibit lowest price sensitivity; event planners and bulk procurement buyers drive hardest bargaining.
Supply Chain Analysis
Dual-sourcing mandates from premium ice cream parlors and specialty dessert shops require qualifying both upstate New York dairy cooperatives and California Central Valley processors. Raw material flows draw from United States temperate dairy belts, Caribbean rum distilleries, and Scottish whisky cooperages. Supply chain risk concentrates in single-source vulnerability for aged spirit flavor extracts with multi-year barrel commitments. Distribution runs through cold-chain specialized fleets into direct-to-consumer parlors, bypassing conventional grocery slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story where formulation talent scarcity props pricing power for incumbents with captive food science capabilities.
For Market Incumbents: Acquire controlled-temperature homogenization patents and microencapsulation technology licenses to lock in texture stability advantages. Consolidate farm-fresh dairy sourcing through long-term offtake agreements with upstate New York cooperatives. Defend against ready-to-drink canned cocktail substitution by accelerating flavor rotation cycles in experiential retail formats. Prioritize regulatory affairs infrastructure investment to navigate state liquor control board classification fragmentation. For New Entrants and Emerging Players: The gap between superpremium parlor pricing and grocery economy tiers offers white-space entry at the natural-label mid-market. Target southwestern United States metropolitan markets with tequila and mezcal flavor localization. Penetrate the health-conscious consumer segment through oat milk base formulations with clean-label positioning. Launch through age-gated boutique retail to bypass incumbent slotting fee advantages. For Investors and Strategic Acquirers: The window for entry favors dairy-origin specialists with regional compliance expertise over diversified conglomerates lacking alcohol-in-food regulatory infrastructure. Long-term viability hinges on formulation flexibility permitting rapid alcohol content adjustment without emulsion destabilization. Monitor state-level pasteurization code harmonization adoption as inflection signal for multi-state distribution scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Lipid-based encapsulation systems prevent alcohol migration during frozen storage, extending shelf-life performance. |
| Farm-Fresh Dairy Sourcing Consolidation | Long-term offtake agreements with upstate New York cooperatives secure traceable provenance credentials. |
| Age-Gated Boutique Retail Expansion | Dedicated adult dessert parlors bypass conventional grocery slotting fees while enabling controlled sampling environments. |
| Non-Dairy Base Formulation Development | Oat and coconut milk variants open allergen-sensitive and vegan-adjacent consumer segments. |
| State Regulatory Affairs Infrastructure | Parallel compliance tracks for confectionery versus alcoholic beverage designation reduce interstate distribution friction. |
Research Methodology
Multi-period observation of FDA alcohol labeling enforcement patterns and state liquor control board classification determinations anchored the trend analysis, supplemented by interviews with formulation scientists at premium ice cream manufacturers, regulatory affairs leads at alcohol-in-food specialists, category buyers at coastal metropolitan specialty dessert shops, and procurement directors at farm-fresh dairy cooperatives. Secondary validation drew from FDA enforcement discretion letters, TTB classification rulings, National Conference on Food Protection model code adoption tracking, and state dairy pasteurization code databases. Bottom-up volume modeling triangulated against top-down value estimates across product type, flavor profile, and ingredient source segmentation.
Segment-weighting approaches applied differential growth assumptions to premium ice cream versus gelato formats, whiskey versus tequila flavor trajectories, and farm-fresh versus synthetic ingredient sourcing tiers across the projection horizon. CAGRs were derived from trend extrapolation of alcohol integration adoption rates and controlled-temperature homogenization technology diffusion curves. Forecast inputs incorporated coastal metropolitan demand concentration indices and dairy input price elasticity estimates.
Inputs from FDA enforcement databases and state regulatory filings were available through the study window; gaps in real-time TTB classification determination timelines introduce uncertainty bands around interstate distribution permission forecasts. Deviation in state-level pasteurization code harmonization adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Europe Tequila Market