
 Naturally Cultured Beverages Market | 2026-2036
Naturally Cultured Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Naturally Cultured Beverages Market Foresight
Subscription-based replenishment programs is restructuring how naturally cultured beverages reach repeat buyers, shifting volume from episodic retail purchases to predictable recurring revenue. GT's Living Foods leverages direct-to-consumer auto-ship models to sustain brand loyalty beyond shelf placement. Danone anchors its kefir portfolio through controlled dairy supply chains in North America. Health-Ade Kombucha differentiates via small-batch positioning and regional flavor profiles that occupy premium shelf space in specialty retailers.
Naturally cultured beverages are non-alcoholic drinks produced through controlled fermentation of tea, milk, fruits, or vegetables using symbiotic cultures of bacteria and yeast, typically yielding live probiotic counts exceeding one million CFU per serving at point of manufacture. These products serve commercial purposes spanning digestive health positioning, functional hydration, and sugar-reduced alternatives to conventional soft drinks. Kefir and kombucha lead product type segments, with kefir commanding established dairy aisle placement and kombucha capturing faster velocity in chilled natural sets. Bottles dominate packaging type due to consumer perception of premium quality and resealability, while cans gain traction in foodservice channels seeking stackability and lower shipping cube.
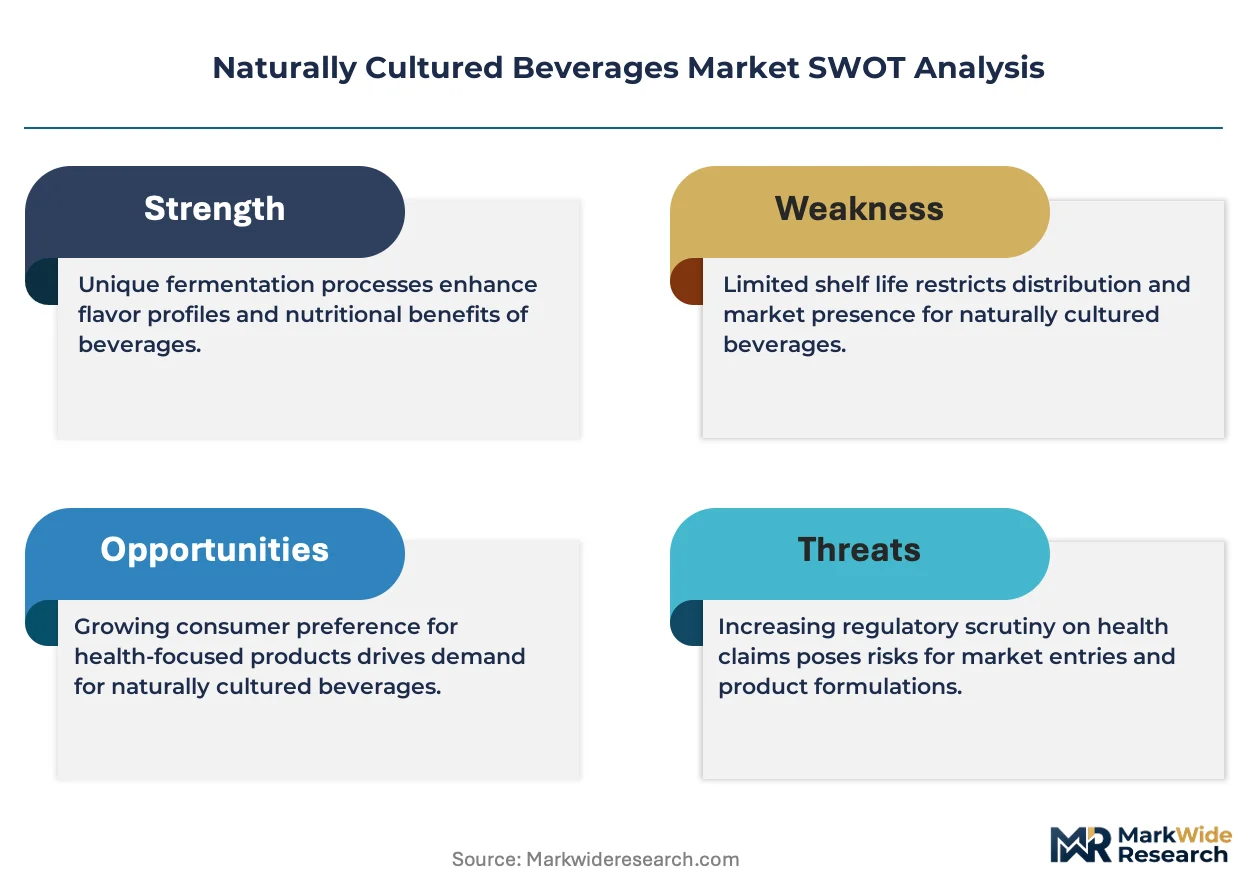
FDA oversight of fermented beverage health claims and USDA organic certification requirements shape formulation choices and label architecture for domestic producers. EFSA's novel food assessments and F-Gas Regulation compliance for cold chain refrigeration constrain European market entry and operating costs for imported brands. Stakeholders must monitor evolving probiotic strain-specific substantiation standards across jurisdictions to anticipate reformulation obligations and competitive positioning shifts.
Market Dynamics
Subscription-based replenishment programs are restructuring how naturally cultured beverages reach repeat buyers, shifting volume from episodic retail purchases to predictable recurring revenue streams that alter manufacturer cash flow patterns and inventory planning horizons.
Growth Catalysts
- USDA Organic Certification:Federal organic labeling standards create premium shelf positioning and price realization advantages for compliant producers in mainstream grocery channels.
- Health Club Channel Expansion:Boutique fitness centers and athletic facilities are building dedicated refrigerated sets for functional hydration products targeting post-workout gut health recovery.
- Cold Chain Infrastructure:Refrigerated logistics networks in the United States now support nationwide distribution of live-culture products with maintained probiotic viability through last-mile delivery.
Market Restraints
- Live Culture Input Concentration:Symbiotic SCOBY and kefir grain supply concentrates among a limited cohort of specialized fermentation laboratories, creating single-source vulnerability.
- FDA Health Claim Friction:Evolving enforcement discretion on probiotic structure-function claims forces conservative label language that limits consumer education effectiveness.
- Sugar Reduction Technical Ceiling:Fermentation biology requires residual substrate that constrains formulation below conventional soft drink sugar levels without compromising culture viability.
Strategic Opportunities
- Direct-to-Consumer Auto-Ship:Recurring revenue platforms bypass slotting fee structures and capture full margin while building proprietary consumption data assets.
- Functional Ingredient Convergence:Adaptogens and nootropics are integrating into fermented bases, creating hybrid positioning between digestive health and cognitive performance categories.
- IRA Clean Energy Provisions:Federal tax incentives for renewable-powered cold chain infrastructure reduce operating cost burdens for domestic fermentation facilities.
Industry Challenges
- Fermentation Science Talent Scarcity:Commercial-scale culture management requires specialized microbiology expertise that outpaces current vocational training pipeline output.
- Multi-Jurisdiction Label Compliance:Probiotic strain-specific substantiation standards vary across state and federal frameworks, complicating national SKU rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naturally Cultured Beverages Market |
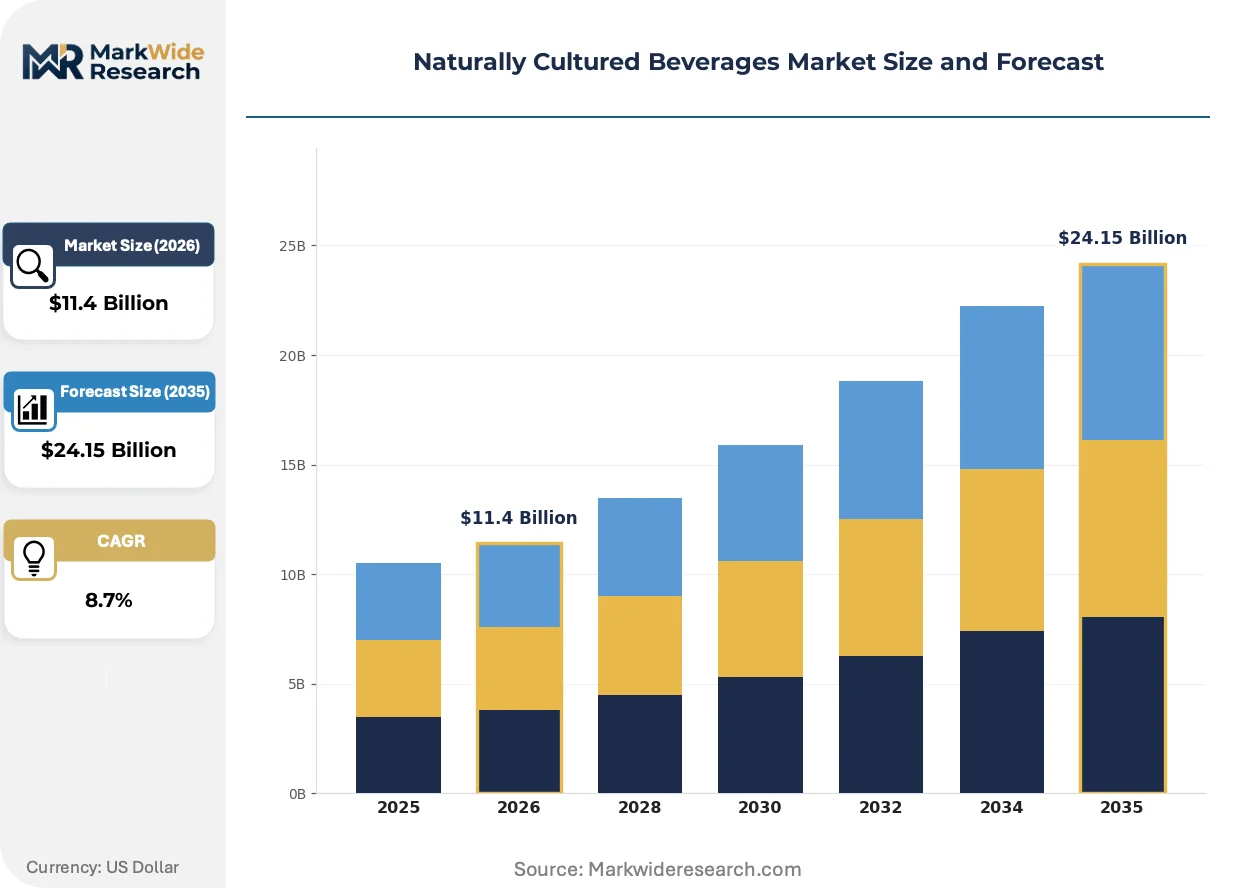
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Fermented Fruit Juice, Probiotic Water Main Ingredient: Tea, Milk, Fruits, Vegetables Packaging Type: Bottles, Cans, Tetra Packs, Kegs End User: Retail Consumers, Foodservice, Health Clubs, Online Buyers |
| Companies Covered | GT's Living Foods, Danone, Deane’s Kombucha, Lifeway Foods, Health-Ade Kombucha, Humm Kombucha, Brew Dr. Kombucha, Yakult Honsha, KeVita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naturally Cultured Beverages Market Shifts & Advancements
Live culture stabilization technologies are reshaping competitive positioning by extending shelf life without thermal pasteurization, enabling broader retail distribution while preserving the functional claims that differentiate this category from conventional beverages.
Precision fermentation monitoring systems are integrating IoT sensors and machine learning algorithms to optimize SCOBY health and metabolite production. Mid-sized producers in the United States are adopting these platforms to reduce batch failure rates and standardize flavor profiles. The technology is integrating quality control functions previously requiring dedicated laboratory staff, compressing operational overhead structures.
EFSA's novel food assessment pathways for postbiotic ingredients are creating regulatory precedent that shapes European formulation strategies. Strain-specific health claim substantiation requirements are forcing documentation investments that favor established players with clinical research budgets. Kefir producers targeting EU distribution are responding by isolating and patenting specific bacterial strains with documented gastrointestinal transit survival rates.
Athletic facility procurement patterns are rotating toward functional hydration contracts that specify live probiotic minimums. Corporate wellness programs and university recreation centers are displacing conventional sports drink exclusivity agreements with multi-brand fermented beverage rotations. This shift is most visible in California and Texas health club chains where gut-health positioning commands premium annual contract values.
Naturally Cultured Beverages Market Segmentation
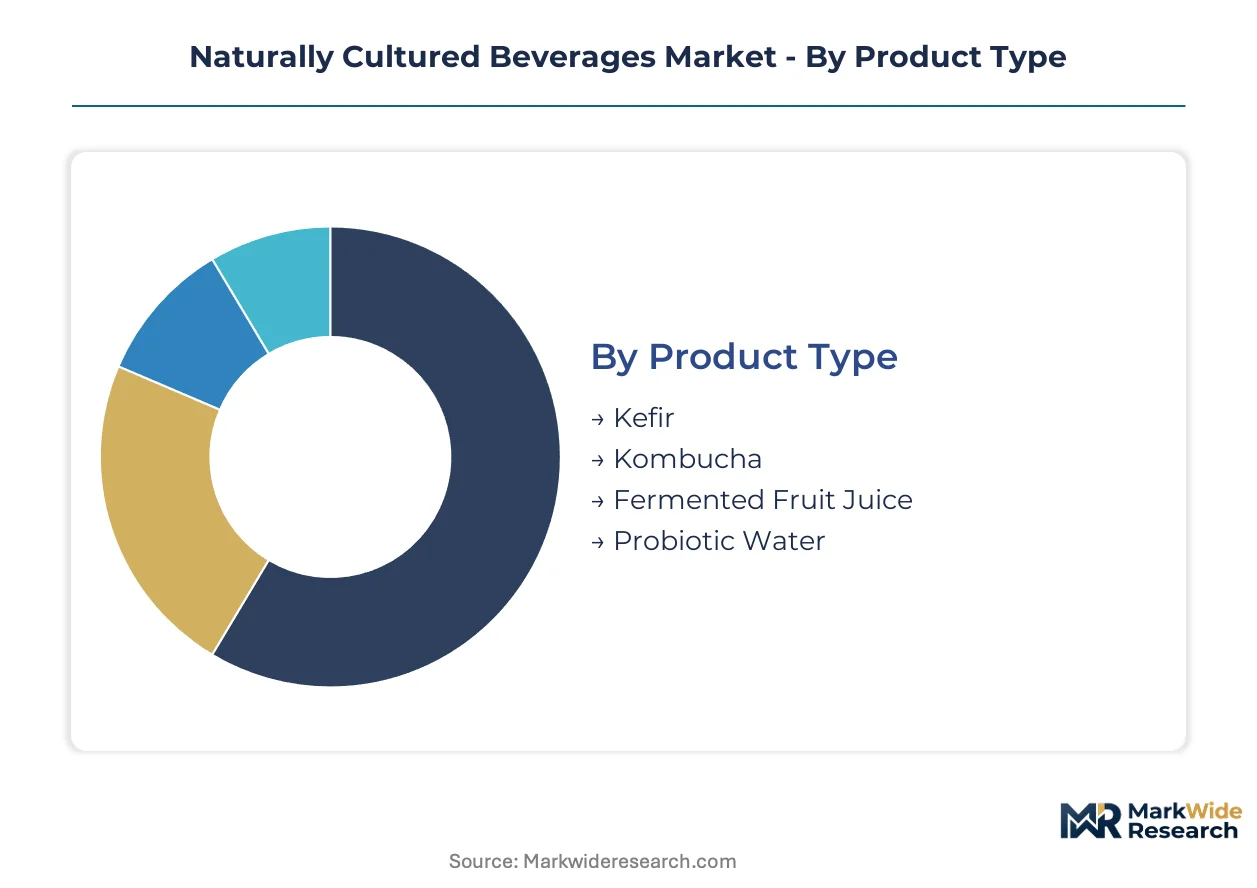
Segmentation in naturally cultured beverages determines shelf placement strategies, cold chain requirements, and margin structures. Product format and packaging choices directly constrain viable distribution channels and consumer price points. Ingredient sourcing and end-user targeting shape fermentation scale economics and brand positioning.
Product Type:
Supply concentration in dairy fermentation infrastructure favors kefir production, while tea-based SCOBY networks concentrate kombucha manufacturing in coastal fermentation clusters.
- Kefir:Fermented milk beverage using kefir grains containing lactic acid bacteria and yeasts, delivering high protein content alongside live cultures. Demand concentrates in conventional dairy aisles of premium grocery chains across the United States, where established cold chain networks support nationwide distribution with maintained probiotic viability.
- Kombucha:Fermented sweet tea utilizing symbiotic cultures of bacteria and yeast, producing organic acids and trace ethanol. Health clubs and boutique fitness centers in California and Texas are building dedicated refrigerated sets for post-workout gut health recovery, displacing conventional sports drink placements.
- Fermented Fruit Juice:Fruit-based fermentation yielding lower acidity than kombucha with broader flavor accessibility.
- Probiotic Water:Water-based delivery system with added live cultures, targeting sugar-conscious hydration seekers.
Today's leader: Kefir. Tomorrow's challenger: Kombucha.
Main Ingredient:
Ingredient sourcing geography dictates fermentation facility location and regulatory compliance burden for domestic producers.
- Tea:Camellia sinensis leaves providing polyphenol substrates for SCOBY metabolism, with organic certification commanding premium positioning in natural retail sets.
- Milk:Dairy substrates requiring controlled supply chain partnerships with regional cooperatives to secure consistent quality for kefir grain maintenance.
- Fruits:Apple, grape, and berry bases enabling seasonal flavor rotations that capture limited-time purchase behavior in specialty retailers.
- Vegetables:Beet, carrot, and ginger formulations occupying niche positioning in functional wellness channels with higher tolerance for savory flavor profiles.
Tea and milk substrates anchor current volume. Fruit and vegetable bases are climbing the fastest as flavor innovation accelerates.
Packaging Type:
Packaging format selection determines shipping economics, retail slotting feasibility, and consumption occasion targeting.
- Bottles:Glass and PET containers dominating premium retail placement due to consumer perception of quality and resealability for multi-serve consumption. Bottles capture the highest margin realization in natural grocery channels where visual branding drives purchase decisions.
- Cans:Aluminum formats gaining traction in foodservice channels seeking stackability, lower shipping cube, and single-serve convenience for athletic facility contracts.
- Tetra Packs:Aseptic carton technology enabling ambient distribution for probiotic waters with stabilized culture counts, reducing cold chain cost burden.
- Kegs:Stainless steel and disposable keg formats serving on-tap kombucha programs in urban foodservice locations with high throughput.
Bottles defend shelf position. Cans are gaining share fastest in foodservice expansion.
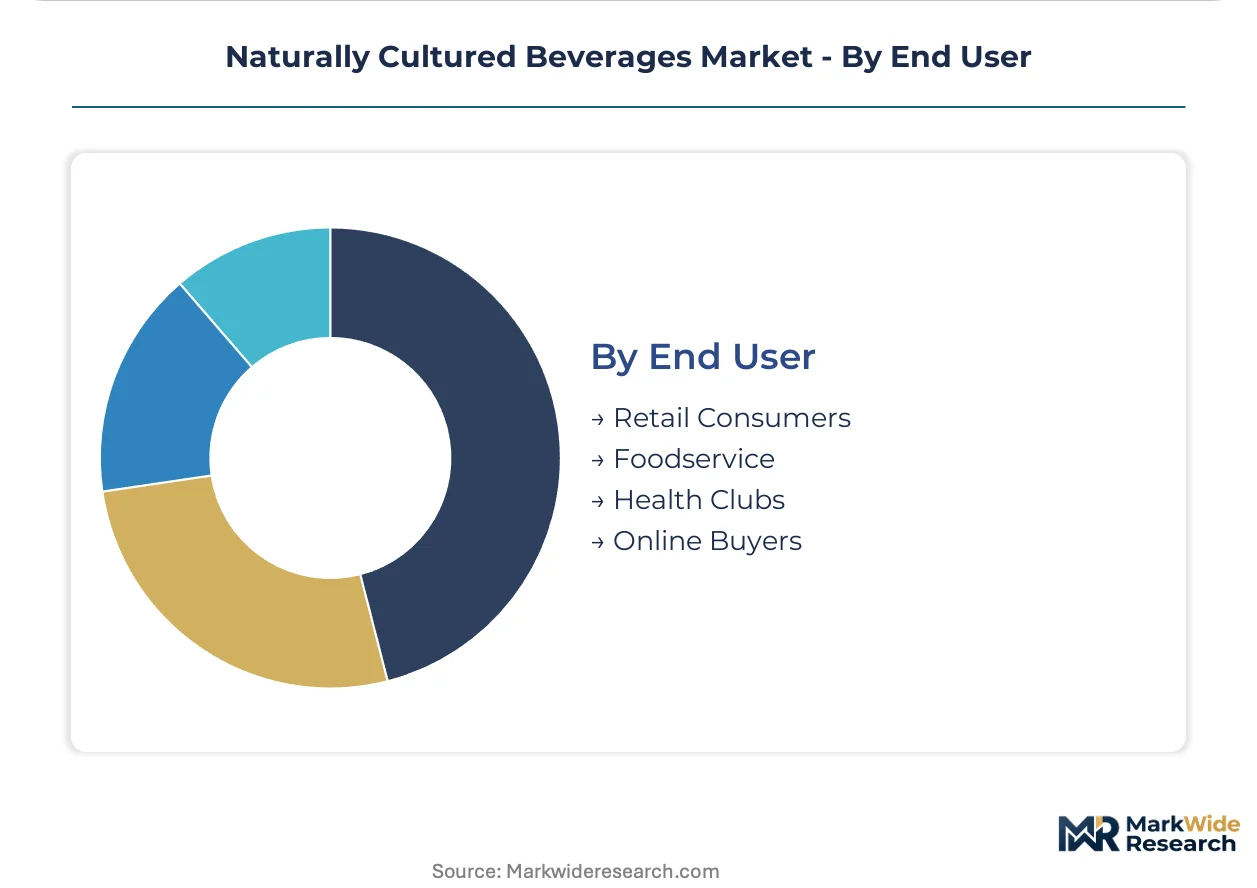
End User:
Channel concentration shapes pricing architecture, with direct-to-consumer platforms capturing full margin while retail incurs slotting fee structures.
- Retail Consumers:Individual purchasers through grocery, natural food, and convenience channels driving volume through repeat purchase behavior and brand loyalty programs.
- Foodservice:Restaurants, cafes, and institutional accounts specifying live culture minimums and rotating flavor portfolios for menu differentiation.
- Health Clubs:Boutique fitness centers and athletic facilities building dedicated refrigerated sets for functional hydration, with gut-health positioning commanding premium annual contract values in California and Texas chains.
- Online Buyers:Direct-to-consumer subscribers through auto-ship platforms generating predictable recurring revenue and proprietary consumption data assets.
Retail consumers anchor volume today. Health clubs represent the steepest expansion trajectory as athletic procurement rotates toward functional hydration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for naturally cultured beverages diverges sharply between the United States and Germany, where American consumers prioritize kombucha in fitness channels while German buyers favor kefir through established dairy retail networks.
United States
Health club procurement contracts and direct-to-consumer auto-ship platforms drive volume concentration in California and Texas metropolitan corridors. FDA enforcement discretion on probiotic structure-function claims shapes conservative label language that limits consumer education effectiveness. Austin and Los Angeles fermentation clusters host mid-sized SCOBY laboratories supplying regional kombucha brands.
Germany
Established dairy cooperative networks and kefir grain preservation traditions anchor consumer loyalty in Baden-Württemberg and Bavaria. EFSA novel food assessment pathways for postbiotic ingredients constrain formulation choices for imported brands seeking EU market entry. Berlin-based precision fermentation startups integrate IoT monitoring systems to reduce batch failure rates.
United Kingdom
Premium grocery channel expansion and sugar-reduction mandates reshape kombucha positioning in London and Southeast England retail sets. F-Gas Regulation compliance requirements for cold chain refrigeration elevate operating costs for domestic fermentation facilities. Manchester foodservice distributors build dedicated chilled sets for on-tap kombucha programs in urban cafés.
Australia
Organic certification premiums and gut-health positioning in corporate wellness programs drive adoption across New South Wales and Victoria. TGA probiotic strain-specific substantiation standards require clinical documentation investments that favor established players with research budgets. Melbourne fermentation cooperatives supply SCOBY cultures to regional craft producers.
Japan
Yakult-established probiotic consumption habits and convenience store refrigerated sets create distribution infrastructure for functional fermented beverages in Tokyo and Osaka metropolitan areas. METI clean energy provisions for renewable-powered cold chain reduce facility operating cost burdens. Kyoto-based dairy processors integrate traditional kefir grain maintenance with automated culture monitoring.
Naturally Cultured Beverages Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with kefir production concentrating around dairy-integrated players and kombucha fragmenting across craft fermentation labs. Tiered competitive structure separates premium small-batch positioning from mass-market refrigerated distribution. Three archetypes dominate: legacy dairy conglomerates with captive culture supply, dedicated kombucha specialists with direct-to-consumer platforms, and Asian probiotic pioneers with strain patent portfolios. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure fermentation science talent and cold chain infrastructure.
Within the dedicated kombucha specialist tier, GT's Living Foods and Health-Ade Kombucha exemplify divergent growth vectors—one leveraging auto-ship subscription retention, the other occupying premium shelf space through regional flavor differentiation. Danone represents the dairy-integrated archetype with controlled North American supply chain partnerships. Yakult Honsha anchors the strain-patent specialist category with documented gastrointestinal transit survival research. These three collectively illustrate how competitive positioning in naturally cultured beverages depends on culture supply security and distribution channel control rather than manufacturing scale alone.
| Leading Market Players |
|---|
| GT's Living Foods |
| Danone |
| Deane's Kombucha |
| Lifeway Foods |
| Health-Ade Kombucha |
| Humm Kombucha |
| Brew Dr. Kombucha |
| Yakult Honsha |
| KeVita |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up kombucha specialists anchor supply discipline through controlled SCOBY laboratory networks while enforcing subscription-based pricing floors that resist conventional retail discounting. Family-owned kefir cooperatives in the Upper Midwest tether margin structures to regional dairy commodity cycles, creating divergent pricing architectures across fermentation substrates.
Pricing Analysis
Capacity additions in California and Texas fermentation clusters are reshaping price floors for kombucha while kefir maintains stability through captive dairy supply chains. Three-tier pricing structure across premium small-batch, standard refrigerated, and economy ambient-stabilized levels segments buyer sensitivity, with health club procurement showing lowest price elasticity due to annual contract structures. Cost compression in standard-tier kombucha is intensifying because slotting fee inflation at premium grocery chains outpaces volume growth. Online direct-to-consumer subscribers exhibit highest price sensitivity, with auto-ship cancellation rates spiking above threshold pricing levels.
Supply Chain Analysis
Single-source vulnerability sits with specialized SCOBY laboratories concentrated in coastal United States fermentation clusters, where culture propagation expertise outpaces facility expansion. Raw material dependencies center on organic tea imports from India and Sri Lanka, dairy substrates from North American cooperatives, and organic cane sugar from Brazilian suppliers. Tariff exposure on glass bottle imports from China elevates packaging cost volatility for premium-positioned brands. Distribution runs through temperature-controlled third-party logistics networks with 2-8°C maintained viability requirements, constraining last-mile expansion into ambient retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's evolving enforcement discretion on probiotic structure-function claims functions as a regulatory compounder, with tightened substantiation standards favoring incumbents with clinical research budgets while raising compliance barriers for emerging entrants.
For Market Incumbents: Deepen backward integration into captive SCOBY and kefir grain production to insulate against single-source laboratory concentration. Secure fermentation science talent through university partnership pipelines in Austin and Los Angeles clusters, addressing the vocational training gap that constrains batch standardization. Expand direct-to-consumer auto-ship platforms to bypass slotting fee structures and capture proprietary consumption data assets.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for kombucha specialists seeking to bypass incumbent shelf dominance. Target health club and boutique fitness center procurement rotations in California and Texas metropolitan corridors, where gut-health positioning commands premium annual contract values. Leverage precision fermentation monitoring systems to reduce batch failure rates without dedicated laboratory overhead.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized craft kombucha producers lacking auto-ship infrastructure but holding regional flavor differentiation portfolios. Long-term viability over the next decade hinges on cold chain infrastructure ownership and strain-specific patent portfolios rather than manufacturing scale alone. Watch for FDA strain-specific substantiation guidance as the inflection indicator that will force consolidation among undercapitalized players unable to fund clinical documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Auto-Ship Platform Launch | Bypasses slotting fees and captures recurring revenue with proprietary data assets. |
| Precision Fermentation Monitoring Integration | IoT-enabled SCOBY health tracking reduces batch failure rates for mid-sized producers. |
| Health Club Channel Exclusivity Contracts | Annual procurement agreements in California and Texas displace conventional sports drinks. |
| Strain-Specific Patent Portfolio Development | Documented gastrointestinal transit survival rates enable EFSA novel food compliance. |
| Cold Chain Infrastructure Ownership | Refrigerated logistics control ensures probiotic viability through last-mile delivery. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Australia, with primary inputs from each region combining fermentation facility operators, health club procurement directors, grocery category buyers, and cold chain logistics providers. Secondary validation draws from FDA guidance documents, EFSA novel food assessments, USDA organic certification databases, and refrigerated trade flow records. Bottom-up volume modeling triangulates against top-down category spend estimates to anchor projection credibility.
Granularity-level framing applies product type, packaging format, end-user channel, and regional regulatory cluster dimensions at the SKU level across the projection horizon. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns in functional beverage categories. Forecast inputs incorporate cold chain infrastructure expansion timelines, probiotic strain substantiation documentation investments, and health club channel penetration rates by metropolitan corridor.
Regulatory enforcement shifts, cold chain cost volatility, and fermentation science talent scarcity are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented stakeholder assumptions rather than mechanistic extrapolation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Energy Drinks Market