
 Soft Drinks Market | 2026-2036
Soft Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Drinks Market Intelligence
Product development focused on functional and low-sugar formulations is reconfiguring the industry's margin landscape, shifting profitability away from traditional carbonated soft drinks. PepsiCo leverages its extensive distribution network to introduce healthier alternatives alongside its core brands. The Coca-Cola Company sustains market leadership through strategic acquisitions in high-growth categories. Monster Beverage Corporation dominates the energy drink segment with targeted branding and a focused product portfolio.
Soft drinks are non-alcoholic beverages, primarily composed of carbonated or still water, sweeteners, and natural or artificial flavorings. These products often undergo processes like carbonation, where carbon dioxide is dissolved under pressure, to ensure shelf stability. While carbonated beverages maintain a significant market share, the energy drinks and non-carbonated segments are experiencing more rapid expansion. Supermarkets and convenience stores form the backbone of distribution, but the online retail channel is gaining traction for multipack and specialty products.
Regulatory frameworks established by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) impose strict rules on sugar content and nutritional labeling. In countries like India, the FSSAI's standards for additives and contaminants directly influence product formulation and market access. Producers must now balance investments in natural sweeteners and functional ingredients against consumer price sensitivity in a competitive environment.
Market Dynamics
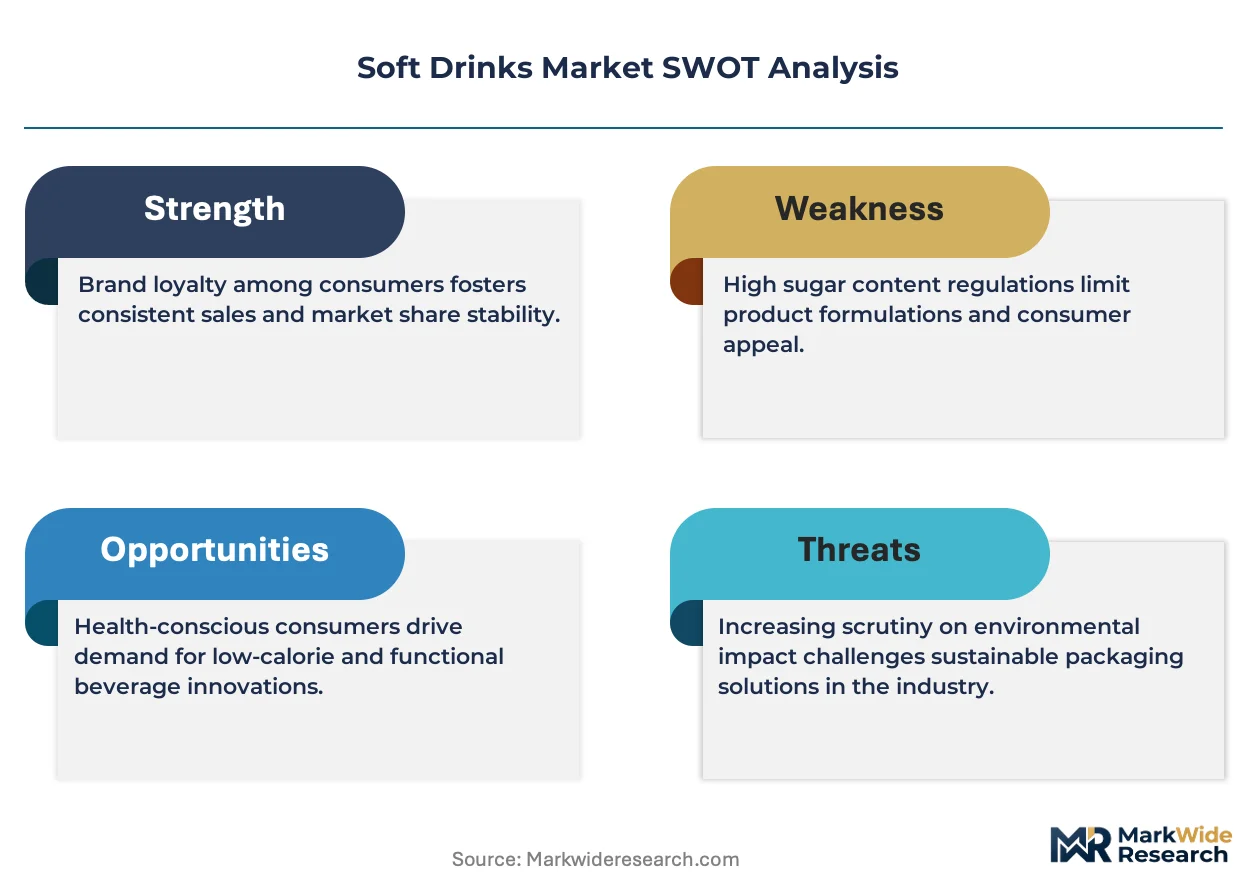
The central structural force shaping the soft drinks market is the consumer-led demand for wellness and functionality. This shift directly pressures manufacturers to reformulate products, moving away from traditional high-sugar, high-calorie beverages toward healthier, functional alternatives to satisfy both consumer preferences and new regulatory hurdles.
Growth Catalysts
- Urbanization in Developing Economies:Rapid urbanization and rising disposable incomes in countries like India and Brazil are expanding the addressable market for packaged and convenience-oriented beverages, creating new consumer segments.
- Functional Ingredient Integration:Consumer interest in proactive health management is driving demand for beverages fortified with functional ingredients such as probiotics, vitamins, and adaptogens, opening new avenues for product differentiation.
- E-commerce Channel Expansion:The growth of online retail and direct-to-consumer platforms provides an alternative route to market, enabling brands to bypass traditional retail gatekeepers for multipack and specialty product sales.
Market Restraints
- Sugar Taxation Policies:Fiscal measures like the UK's Soft Drinks Industry Levy directly increase production costs and consumer prices for high-sugar beverages, compressing margins and forcing product reformulation.
- Water Resource Constraints:The industry's high water consumption faces scrutiny and operational risk in water-stressed regions, impacting production costs and requiring investment in water stewardship programs.
- Stringent Packaging Regulations:Mandates from bodies like the European Union regarding single-use plastics and recycled content requirements increase packaging costs and necessitate significant supply chain adjustments.
Strategic Opportunities
- Natural Sweetener Development:Innovations in the formulation and sourcing of natural, non-caloric sweeteners like stevia and monk fruit enable the creation of low-sugar products that meet consumer taste expectations.
- Cannabinoid and Nootropic Infusions:Evolving regulatory landscapes in North America and parts of Europe create opportunities for functional beverages containing ingredients like CBD or nootropics, targeting wellness and cognitive benefits.
- Direct-to-Consumer Subscription Models:Digital platforms allow brands to offer personalized beverage subscriptions, fostering brand loyalty and capturing valuable consumer data while securing recurring revenue streams.
Industry Challenges
- Cold Chain Infrastructure Investment:Expanding into preservative-free and natural beverage categories requires substantial capital expenditure on refrigerated logistics and storage to ensure product stability and safety across the supply chain.
- Volatile Ingredient Sourcing:The supply chains for natural flavors, botanical extracts, and other functional ingredients are often fragmented and subject to agricultural price fluctuations, complicating cost forecasting and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Drinks Market |
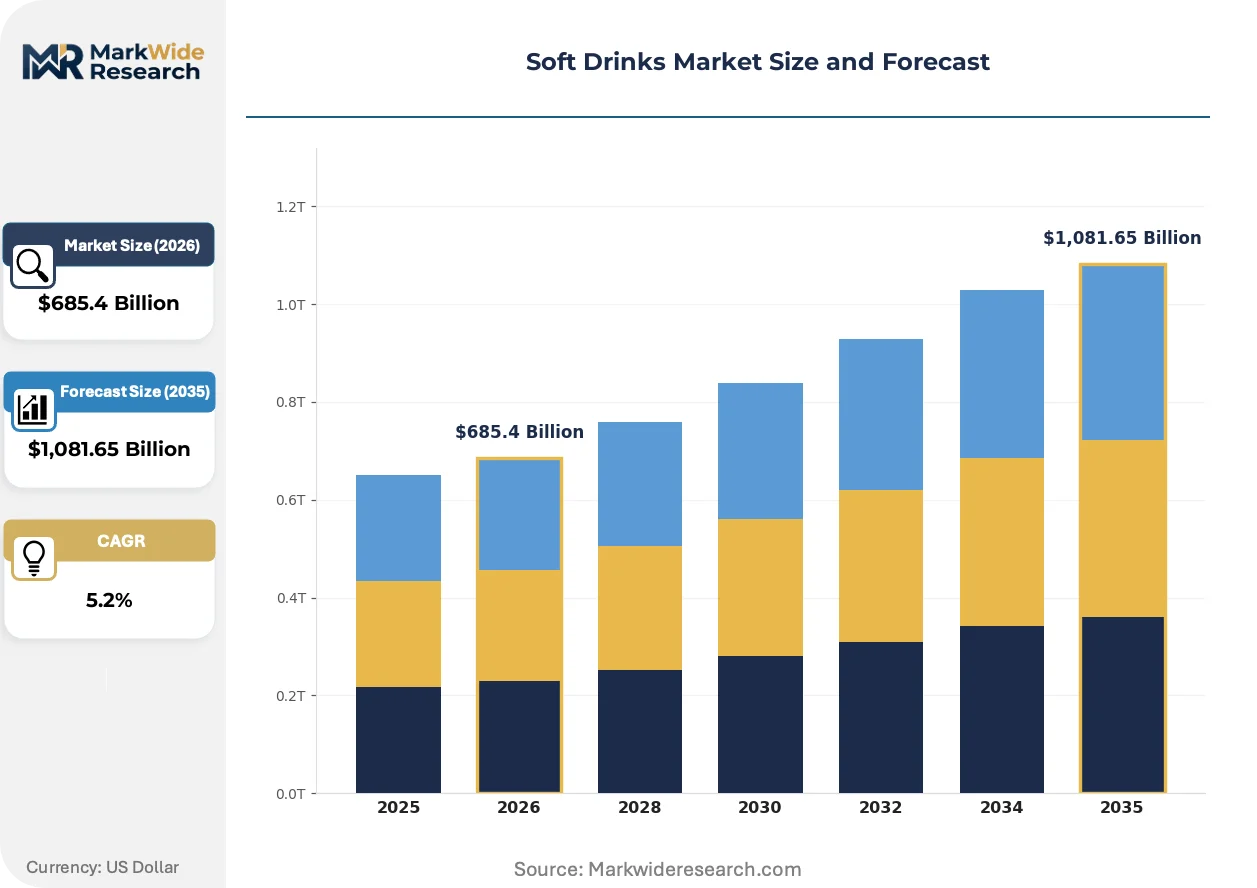
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,081.65 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Energy Drinks, Sports Drinks Flavor Profile: Citrus, Berry, Cola, Tropical Packaging Type: Bottles, Cans, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service |
| Companies Covered | Red Bull GmbH, Suntory Holdings Limited, The Coca-Cola Company, Britvic plc, Asahi Group Holdings, PepsiCo, Monster Beverage Corporation, Kirin Brewery Company Limited, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Drinks Market Strategic Shifts & Innovations
Product formulation is now a complex balance of health attributes, regulatory compliance, and sustainable sourcing. The industry's focus is shifting from taste and branding alone toward creating beverages that can demonstrate functional benefits and align with transparent labeling mandates.
Advanced filtration and cold-pasteurization methods, such as high-pressure processing (HPP), allow for the preservation of beverages without heat. Premium juice and functional drink manufacturers are steadily adopting this process to maintain nutrient integrity and flavor. This technology is rendering obsolete the reliance on thermal pasteurization and artificial preservatives for achieving shelf stability in high-value product segments.
Front-of-pack labeling (FOPL) systems, including the Nutri-Score framework in several European countries, are a significant regulatory development. These visual cues directly inform consumer choice at the point of purchase, penalizing products high in sugar, salt, or fat. The carbonated soft drink and sweetened juice categories are most affected, accelerating reformulation efforts to avoid poor ratings.
Consumer purchasing behavior is fragmenting away from monolithic weekly grocery trips. This change disrupts the traditional distribution model centered on hypermarkets, which is being replaced by an omnichannel strategy encompassing convenience stores, cafes, and rapid online delivery. This trend is most visible in dense urban centers across North America and Asia-Pacific where delivery infrastructure is most developed.
Soft Drinks Market Segmentation
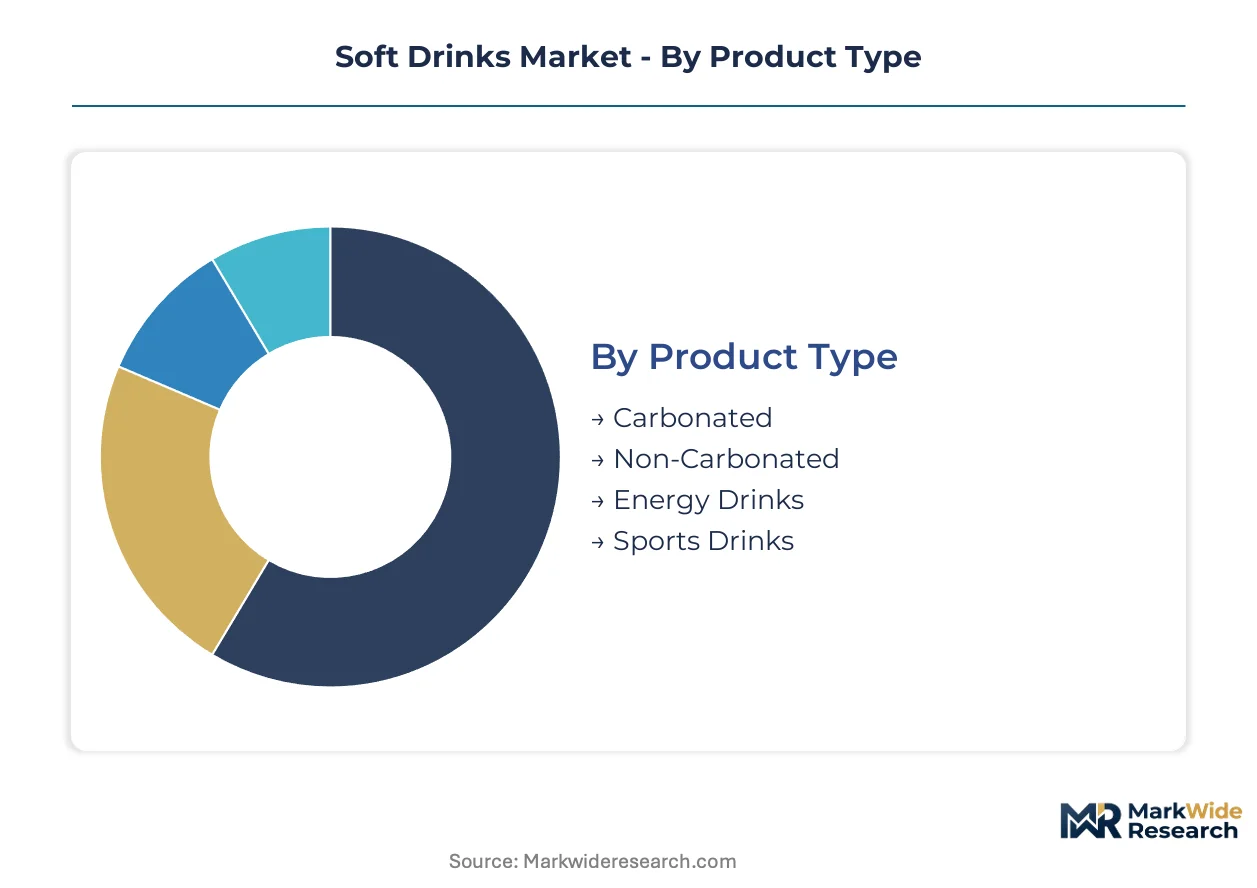
Segmentation provides a granular view of the soft drinks market, highlighting distinct consumer preferences and operational considerations across various product attributes and sales channels. This analysis helps manufacturers tailor product development and go-to-market strategies to specific consumer needs and regulatory environments. Understanding these segments is crucial for identifying areas of growth and potential market disruption.
Product Type:
Product type segmentation delineates the core beverage formulations available to consumers, reflecting diverse consumption occasions and health preferences.
- Carbonated:These beverages contain dissolved carbon dioxide, creating effervescence, and often include sweeteners and flavorings. Demand remains significant in established markets, particularly for traditional cola and lemon-lime variants.
- Non-Carbonated:This category includes still water, juices, iced teas, and ready-to-drink coffees, often formulated with natural ingredients and lower sugar content. Demand is rising in developing economies like India, fueled by health-conscious consumers and urbanization trends.
- Energy Drinks:These beverages contain stimulants like caffeine, taurine, and B vitamins, designed to boost mental alertness and physical performance. Demand is concentrating in urban centers across North America and Europe, driven by young adults seeking quick energy solutions for demanding lifestyles.
- Sports Drinks:Formulated to rehydrate and replenish electrolytes, sports drinks target athletes and active individuals. Demand is consistent among fitness enthusiasts and in performance-oriented consumer segments.
Carbonated products command the established base. The steepest expansion runs through Energy Drinks.
Flavor Profile:
Consumer preferences for specific taste experiences categorize the market by dominant flavor profiles.
- Citrus:Encompassing lemon, lime, orange, and grapefruit profiles, citrus flavors offer a refreshing and often tangy taste experience. This profile sees consistent demand in warm climates and for functional beverages, where its perceived freshness complements health attributes.
- Berry:Including strawberry, raspberry, and mixed berry notes, this profile is popular in fruit-based drinks and for its perceived natural sweetness. Demand is strong in health-conscious segments and for children's beverages.
- Cola:Characterized by its distinctive caramel, vanilla, and spice notes, cola remains a globally recognized and widely consumed flavor. Demand persists across all age groups, particularly in traditional markets where established brands maintain strong loyalty.
- Tropical:Featuring flavors such as mango, pineapple, and passion fruit, tropical profiles convey exoticism and often a sweeter, more intense taste. This profile appeals to consumers seeking novel and adventurous beverage experiences.
Cola flavors continue to hold significant appeal, while tropical infusions are gaining traction among adventurous palates.
Packaging Type:
The physical containment method for soft drinks varies significantly, influencing portability, cost, and environmental impact.
- Bottles:Primarily made from PET plastic or glass, bottles offer re-sealability and a premium feel, available in various sizes from single servings to family packs. Demand is widespread across all distribution channels, serving both individual consumption and household use in developed and developing markets.
- Cans:Typically aluminum, cans provide an effective barrier against light and oxygen, preserving product integrity and offering excellent recyclability. Demand is robust in convenience stores and for multipack sales, especially as brands emphasize sustainability and portability.
- Tetra Packs:Multi-layered carton packaging offers extended shelf life for aseptic products without refrigeration, often used for juices and dairy-based soft drinks. This packaging type is favored for its environmental footprint and efficiency in logistics.
- Pouches:Flexible, lightweight packaging, often with a spout, provides convenience and reduced material usage, popular for children's drinks and on-the-go consumption. Pouches are particularly prevalent in emerging markets due to their cost-effectiveness.
Bottles remain ubiquitous for individual servings, but cans offer a compact, recyclable alternative expanding quickly.
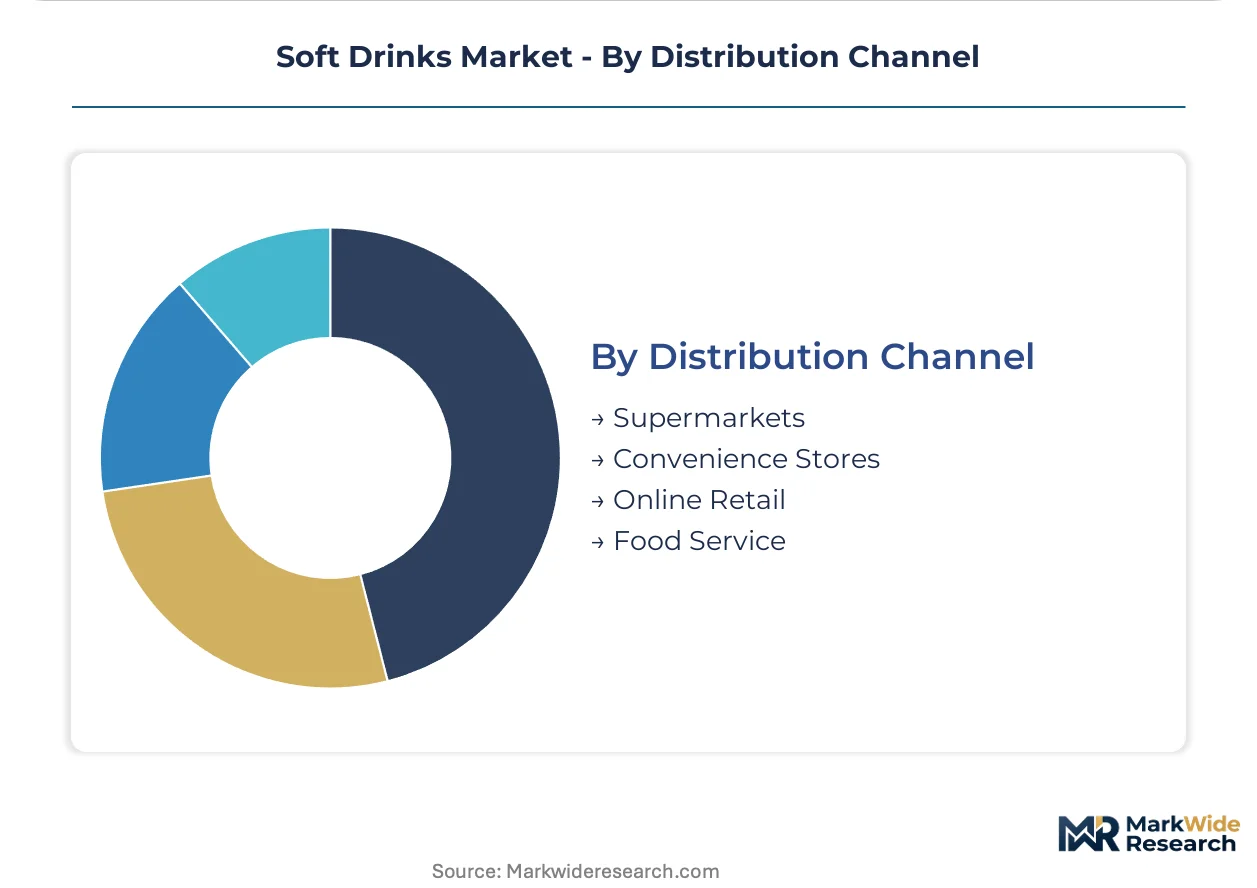
Distribution Channel:
Access points for soft drinks span various retail and consumption environments, each catering to distinct purchasing behaviors.
- Supermarkets:Large retail establishments offering a broad assortment of soft drinks, often at competitive prices, catering to bulk and weekly shopping needs. Demand is consistent globally, forming the backbone of sales for established brands and new product launches.
- Convenience Stores:Smaller retail outlets providing quick access to single-serve beverages, meeting immediate consumption needs and impulse purchases. These stores are critical for on-the-go consumption and high-frequency transactions.
- Online Retail:E-commerce platforms and direct-to-consumer websites facilitate the purchase of soft drinks, often specializing in multipacks, niche brands, and subscription services. Demand is surging in dense urban centers across North America and Asia-Pacific, driven by convenience and wider product selection.
- Food Service:This channel includes restaurants, cafes, hotels, and institutional catering, where beverages are consumed on-premise or as part of a meal. Food service sales are influenced by consumer dining habits and menu offerings.
Supermarkets continue to drive bulk purchases, while online retail is rapidly capturing specialty and multipack sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across global soft drinks markets, with some regions exhibiting high price sensitivity while others prioritize premium functional attributes. This contrast directly influences product innovation and market entry strategies for beverage manufacturers. Understanding these regional nuances is crucial for sustained growth in a dynamic industry landscape.
United States
Consumers in the United States show strong demand for functional beverages and low-sugar alternatives. The US FDA strictly regulates nutritional labeling and ingredient safety for all food and beverage products. Major beverage manufacturers in Atlanta and New York City consistently drive product innovation and market trends.
India
Rapid urbanization and rising disposable incomes in India significantly expand the addressable market for packaged soft drinks. The FSSAI sets stringent standards for food additives, contaminants, and labeling. Major production hubs in Maharashtra and Delhi-NCR are expanding capacity to meet this escalating demand.
Germany
German consumers increasingly seek natural, organic, and locally sourced soft drink alternatives. The European Food Safety Authority (EFSA) influences ingredient safety and marketing claims across the European Union. Munich and Hamburg are centers for craft beverage development and distribution.
Brazil
A growing middle class in Brazil increases demand for diverse and conveniently packaged soft drink options. ANVISA establishes comprehensive regulations for food and beverage safety and labeling. São Paulo hosts significant beverage production facilities and extensive distribution networks.
China
Urban Chinese consumers exhibit strong demand for imported and premium soft drinks, alongside traditional local brands. The State Administration for Market Regulation (SAMR) enforces strict food safety and labeling standards. Shanghai and Guangzhou are key metropolitan markets for new product introductions and consumption.
Soft Drinks Market Key Industry Players
Established beverage conglomerates and specialized energy drink players split the soft drinks market, driving distinct competitive dynamics. The market exhibits characteristics of both consolidation among traditional players and fragmentation within niche segments. Strategic partnerships and portfolio diversification are common competitive moves employed by industry participants.
Within the established beverage conglomerate archetype, The Coca-Cola Company and PepsiCo exemplify broad portfolio diversification across carbonated and non-carbonated segments. Monster Beverage Corporation anchors the energy drink segment, representing a highly specialized and targeted branding approach. These companies occupy a significant position in the market through extensive distribution networks and brand recognition.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Suntory Holdings Limited |
| The Coca-Cola Company |
| Britvic plc |
| Asahi Group Holdings |
| PepsiCo |
| Monster Beverage Corporation |
| Kirin Brewery Company Limited |
| Keurig Dr Pepper |
| Others |
Cost & Logistics Intelligence
The global sourcing of key ingredients like sugar and packaging materials from concentrated regions directly influences margin distribution across the soft drinks value chain. This upstream concentration can create leverage for suppliers, impacting downstream manufacturer profitability.
Pricing Analysis
Premium-tier functional beverages drive lifetime value through recurring purchases and brand loyalty. The dominant pricing structure remains per-unit transactional, with significant differentiation based on brand premium and the integration of novel functional ingredients. Pricing pressure stems from intense competition in traditional carbonated segments and escalating raw material costs. Mass-market consumers exhibit high price sensitivity, while health-conscious buyers for functional and specialty drinks are less sensitive.
Supply Chain Analysis
Upstream feedstock for sweeteners, particularly sugar, concentrates in countries like Brazil and India. Key raw material dependencies include water, sugar, natural flavorings, and packaging components such as PET plastic and aluminum. Commodity price volatility for sugar and aluminum represents a significant structural supply chain risk. Distribution runs through an omnichannel model, encompassing traditional supermarkets, convenience stores, online retail platforms, and the food service sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fragmentation of consumer purchasing behaviors across diverse channels shifts buying power towards agile online platforms and convenience retail. This dynamic necessitates strategic responses from market participants.
For Market Incumbents:Harden core brand positions by accelerating reformulation efforts to meet low-sugar mandates and evolving health preferences. Diversify product portfolios through strategic acquisitions of functional beverage brands, countering the threat from specialized niche players. Leverage extensive distribution networks to introduce healthier alternatives, controlling shelf space and consumer access. Invest in R&D for advanced natural sweeteners and sustainable packaging solutions.
For New Entrants and Emerging Players:Niche functional beverage categories, particularly those infused with adaptogens or nootropics, represent a penetrable entry point. Target urban health-conscious consumers in North America and Europe seeking proactive wellness solutions. A direct-to-consumer subscription model provides a viable go-to-market angle, fostering brand loyalty and capturing valuable consumer data. Focus on transparent labeling and unique flavor profiles to differentiate.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-cap functional beverage brands demonstrating strong growth in specific wellness categories. Long-term viability hinges on companies with robust R&D in natural ingredients and sustainable packaging technologies. The acquisition target archetype favors agile innovators with established brand equity in high-growth segments like energy drinks or plant-based alternatives. Watch for regulatory clarity on novel functional ingredients as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulate Core Product Lines | Reduces exposure to sugar taxes and aligns products with consumer health trends. |
| Acquire Functional Beverage Brands | Expands portfolio into high-growth segments, leveraging existing distribution infrastructure. |
| Invest in Sustainable Packaging | Addresses environmental concerns and meets evolving regulatory requirements from the European Union. |
| Develop D2C Subscription Platforms | Fosters brand loyalty and captures valuable first-party consumer data for personalized offerings. |
| Expand into Emerging Markets | Capitalizes on rising disposable incomes and urbanization in countries like India. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market reports anchors the qualitative findings. This approach integrates insights from beverage executives, R&D scientists, retail buyers, and regulatory experts. Secondary validation draws from government health agency guidelines, industry association reports, and public financial filings of leading beverage companies.
The calibration approach integrates a multi-dimensional analytical framework across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, packaging format, distribution channel, and regional regulatory compliance. Compound Annual Growth Rates were derived through a weighted average of historical trends and future projections. Per capita consumption trends and raw material price forecasts serve as key industry-specific forecast inputs.
Practitioners should monitor unforeseen regulatory shifts, sudden changes in consumer health trends, or major supply chain disruptions for early signals that could revise forecasts. Forecasts reflect assumptions regarding market dynamics and technological advancements. Cross-checking against named external benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market