
 Rtd Bubble Tea Market | 2026-2036
Rtd Bubble Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Rtd Bubble Tea Market Analytics
Subscription-based replenishment programs for home delivery is shifting how brands build recurring revenue in the RTD bubble tea category. Gong Cha leverages its direct-to-consumer platform to secure repeat orders with curated flavor rotations. CoCo Fresh Tea & Juice anchors its North American presence through controlled distribution in Asian grocery networks. Chatime competes via specialized manufacturing partnerships that preserve tapioca texture in shelf-stable formats.
Ready-to-drink bubble tea denotes a pre-packaged beverage containing brewed tea, milk or non-dairy creamer, sweeteners, and optional tapioca pearls or fruit jelly, manufactured through ultra-high-temperature processing and aseptic cold-fill protocols to achieve ambient stability. Its commercial purpose centers on delivering the experiential qualities of freshly prepared bubble tea through mass retail channels with extended shelf life. Milk tea formulations command the dominant share of value across product type segments due to consumer familiarity with classic flavor profiles. Pouch packaging represents the fastest-growing format among packaging type categories, driven by portability and lower per-unit price points that attract teen and young adult customer segments.
FDA oversight of food additive petitions and GRAS determinations shapes ingredient innovation for US-bound RTD bubble tea exports, while Taiwan's food safety regulator enforces strict preservative limits that influence formulation standards across major production hubs. China's SAMR implements labeling requirements for sugar content that affect how brands position health-oriented variants in that market. Stakeholders must monitor evolving sweetener regulations and packaging sustainability mandates as these forces determine which product architectures gain retail access in priority markets.
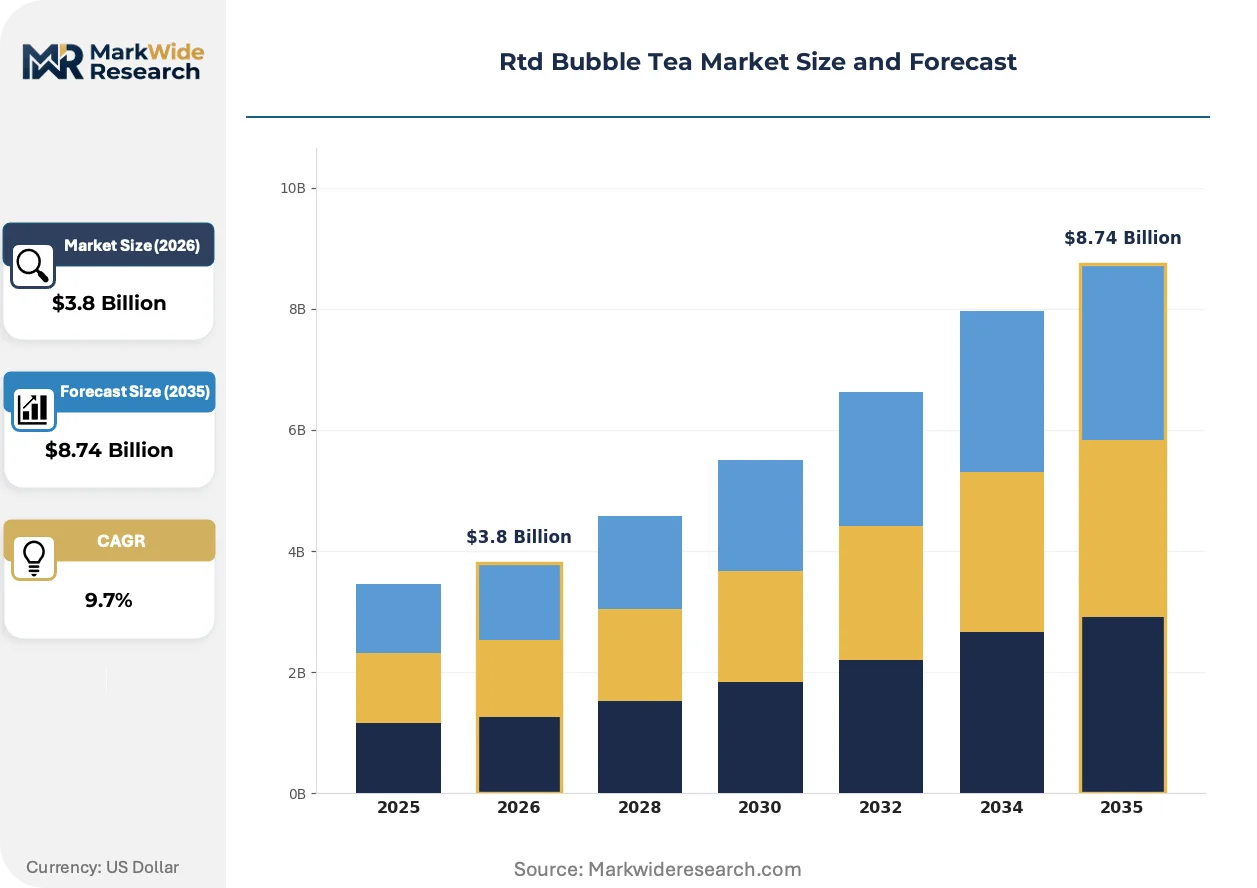
Market Dynamics
Subscription-based replenishment programs are restructuring revenue architecture across the RTD bubble tea category, converting episodic retail purchases into predictable recurring income streams that alter working capital requirements and customer lifetime value calculations.
Growth Catalysts
- ASEAN Convenience Retail Expansion:Chain stores across Vietnam, Thailand, and the Philippines are dedicating incremental shelf space to ambient-stable milk tea formats, creating physical availability in high-traffic urban locations.
- Taiwan Food Safety Authority Additive Rules:Tightened labeling requirements for preservatives and colorants are accelerating clean-label formulation investments that differentiate export-ready production.
- Ultra-High-Temperature Processing:Advanced UHT protocols paired with aseptic cold-fill lines are extending ambient shelf stability to 12-18 months without refrigeration infrastructure.
Market Restraints
- Tapioca Starch Supply Concentration:Cassava sourcing clusters in Thailand and Vietnam expose multiple brands to synchronized weather and currency volatility in Southeast Asian agricultural belts.
- Shelf-Stable Texture Degradation:Current aseptic processing limits prevent authentic tapioca pearl mouthfeel replication, constraining premium positioning against fresh-service competitors.
- China SAMR Sugar Labeling Mandates:Front-of-pack sugar disclosure rules complicate formulation strategies for brands targeting health-claim positioning in that market.
Strategic Opportunities
- Philippines Provincial Distribution:Metro Manila penetration rates exceed 60% while secondary cities like Cebu and Davao remain underserved by organized retail tea offerings.
- Pouch Format Channel Innovation:Flexible pouch packaging at sub-dollar price points is unlocking vending machine and school canteen channels previously inaccessible to rigid bottle formats.
- Non-Dairy Creamer Convergence:Oat and coconut milk processing advances are converging with UHT compatibility testing to enable plant-based line extensions without dedicated production lines.
Industry Challenges
- Aseptic Line Capex Intensity:Cold-fill sterilization equipment requires 18-24 month installation timelines and specialized cleanroom construction that strains mid-scale manufacturer balance sheets.
- Cross-Border Formulation Harmonization:Divergent preservative limits between Taiwan's food safety regulator and FDA GRAS determinations force SKU proliferation or lowest-common-denominator recipes.
- Tapioca Inclusion Certification Delays:Novel food approvals for modified starch pearls in the EU and Australia extend go-to-market timelines by 14-20 months for texture-innovative products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rtd Bubble Tea Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Tea, Fruit Tea, Herbal Tea, Specialty Tea Packaging Type: Bottles, Cans, Tetra Packs, Pouches Distribution Channel: Online, Supermarkets, Convenience Stores, Cafes Customer Type: Teens, Young Adults, Families, Professionals |
| Companies Covered | Gong Cha, CoCo Fresh Tea & Juice, The Alley, Chatime, Kung Fu Tea, Tiger Sugar, Sharetea, HeyTea, Lollicup USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rtd Bubble Tea Market Evolving Landscape
Aseptic processing advances and packaging format diversification are compressing the quality gap between freshly prepared and shelf-stable bubble tea, while regulatory transparency mandates reshape how brands communicate ingredient provenance to skeptical young adult consumers.
Modified atmosphere packaging with nitrogen flushing is overtaking conventional hot-fill methods for tapioca-inclusive varieties. Premium convenience store chains in Seoul and Taipei are adopting these lines to stock pearl-containing pouches with 90-day ambient stability. The technology is overtaking legacy retort processing by preserving chew texture without refrigeration dependency, enabling distribution into vending and transit retail channels previously closed to bubble tea.
Taiwan's food safety authority implemented additive batch disclosure requirements that now extend to imported RTD beverages. Manufacturers must submit complete stabilizer and flavor compound documentation before customs release. Milk tea exporters targeting that market are responding by consolidating supplier bases and investing in blockchain traceability systems that satisfy audit protocols.
Young adult consumers in Ho Chi Minh City and Manila are rotating purchases through direct-to-subscription platforms that bypass traditional grocery replenishment cycles. These digital-native buyers expect curated flavor rotations and limited seasonal drops delivered to residential addresses. Metro Vietnam households under age 35 now generate the highest repurchase frequency for home-delivery bubble tea programs, compressing the interval between order events to under 14 days.
Rtd Bubble Tea Market Segmentation
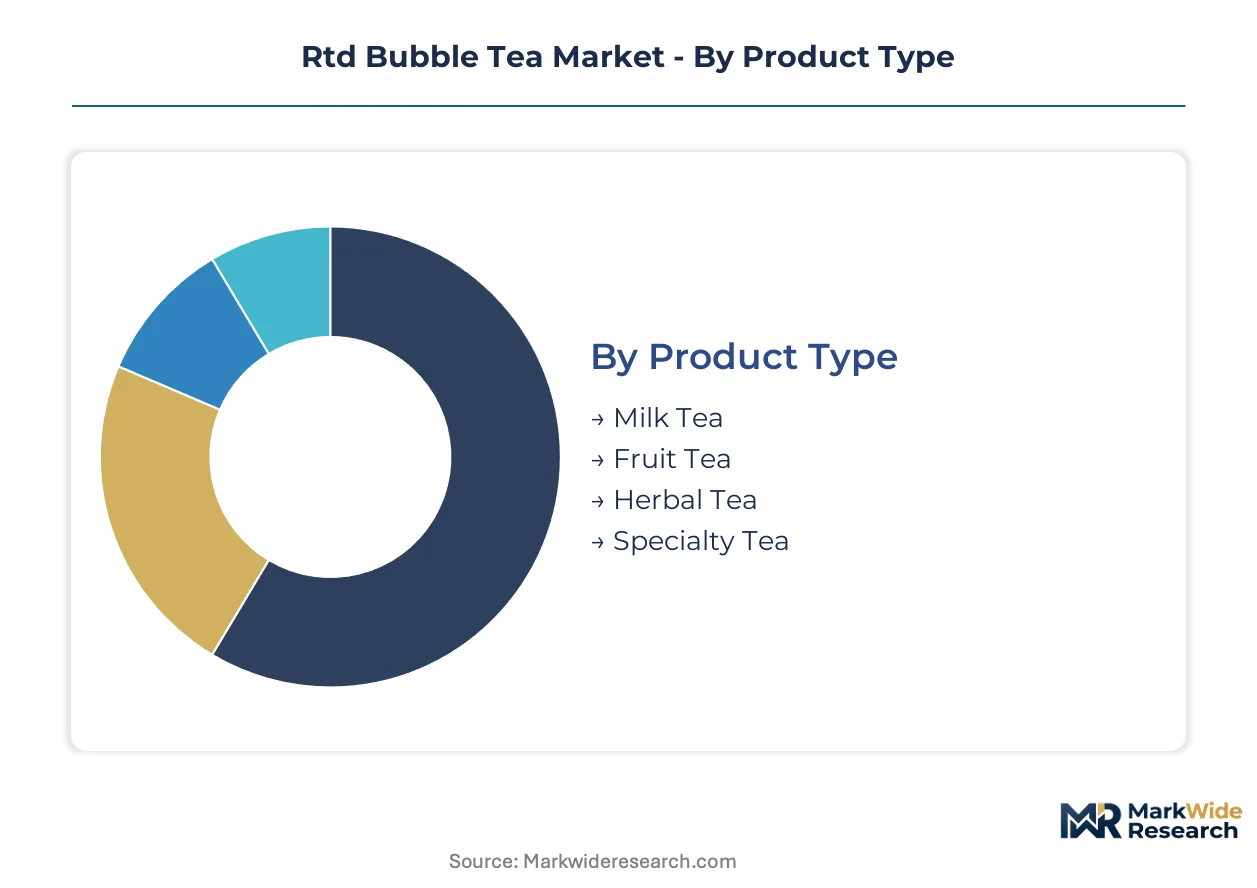
Segmentation in the RTD bubble tea market reveals how formulation chemistry, packaging engineering, and channel economics create distinct profit pools. Understanding these divides exposes where UHT processing investments generate returns and where flexible formats unlock new consumption occasions.
Product Type:
Volume concentration versus premium positioning splits this category cleanly, with heritage formulations commanding shelf presence while experimental blends capture margin.
- Milk Tea:Brewed black or green tea combined with dairy or non-dairy creamer, sweetened to 8-12 Brix. Demand clusters in Vietnamese and Filipino metropolitan areas where young adult consumers treat ambient milk tea as a daily caffeine ritual. Classic flavor profiles reduce trial risk for first-time RTD buyers.
- Fruit Tea:Tea base infused with fruit juice concentrates or purees, often with acidity regulators for shelf stability. Ho Chi Minh City households under 35 drive repeat purchases through subscription platforms, rotating between lychee, passionfruit, and mango variants seasonally.
- Herbal Tea:Rooibos, chrysanthemum, or barley-based formulations without Camellia sinensis. Functional positioning targets sleep and digestion claims in Taiwan's health-conscious convenience store channels.
- Specialty Tea:Oolong, pu-erh, or matcha-forward recipes with origin-specific marketing. Limited batch releases through Gong Cha's direct-to-consumer platform anchor this tier.
Mature deployment sits with Milk Tea. Newer deployment is concentrated in Specialty Tea.
Packaging Type:
Cost tier determines accessibility, with rigid formats defending premium positioning and flexible pouches penetrating price-sensitive channels.
- Bottles:PET or glass containers with tamper-evident closures, supporting 12-18 month ambient stability through nitrogen flushing. Premium convenience chains in Seoul and Taipei dedicate refrigerated sections to pearl-inclusive bottle formats.
- Pouches:Multi-layer flexible film with spout fitments, enabling sub-dollar price points. Philippine school canteens and vending machines previously closed to rigid formats now stock these for teen segment access.
- Cans:Aluminum two-piece containers suited for carbonated or nitrogenated tea variants. Chatime's manufacturing partnerships exploit canning lines for texture-preserving bubble tea distribution.
- Tetra Packs:Aseptic carton systems with straw perforations, dominant in European export markets where shelf-stable milk tea competes against juice cartons.
Established infrastructure sits with Bottles. Fastest channel expansion is occurring through Pouches.
Distribution Channel:
Customer type and purchase frequency reshape how brands allocate working capital across fulfillment models.
- Convenience Stores:7-Eleven, FamilyMart, and local chains across Thailand, Vietnam, and the Philippines expanding ambient tea shelf space. High-traffic urban locations generate impulse purchases with minimal marketing spend.
- Online:Direct-to-subscription platforms bypassing traditional grocery replenishment. CoCo Fresh Tea & Juice anchors North American presence through controlled Asian grocery network distribution alongside native digital channels.
- Supermarkets:Organized retail with dedicated beverage aisles, requiring slotting fees and promotional calendars. Secondary cities like Cebu and Davao remain underserved relative to Metro Manila saturation.
- Cafes:On-premise consumption with RTD grab-and-go sections, bridging fresh-service and packaged experiences.
Physical availability concentrates in Convenience Stores. Digital-native deployment is accelerating through Online.
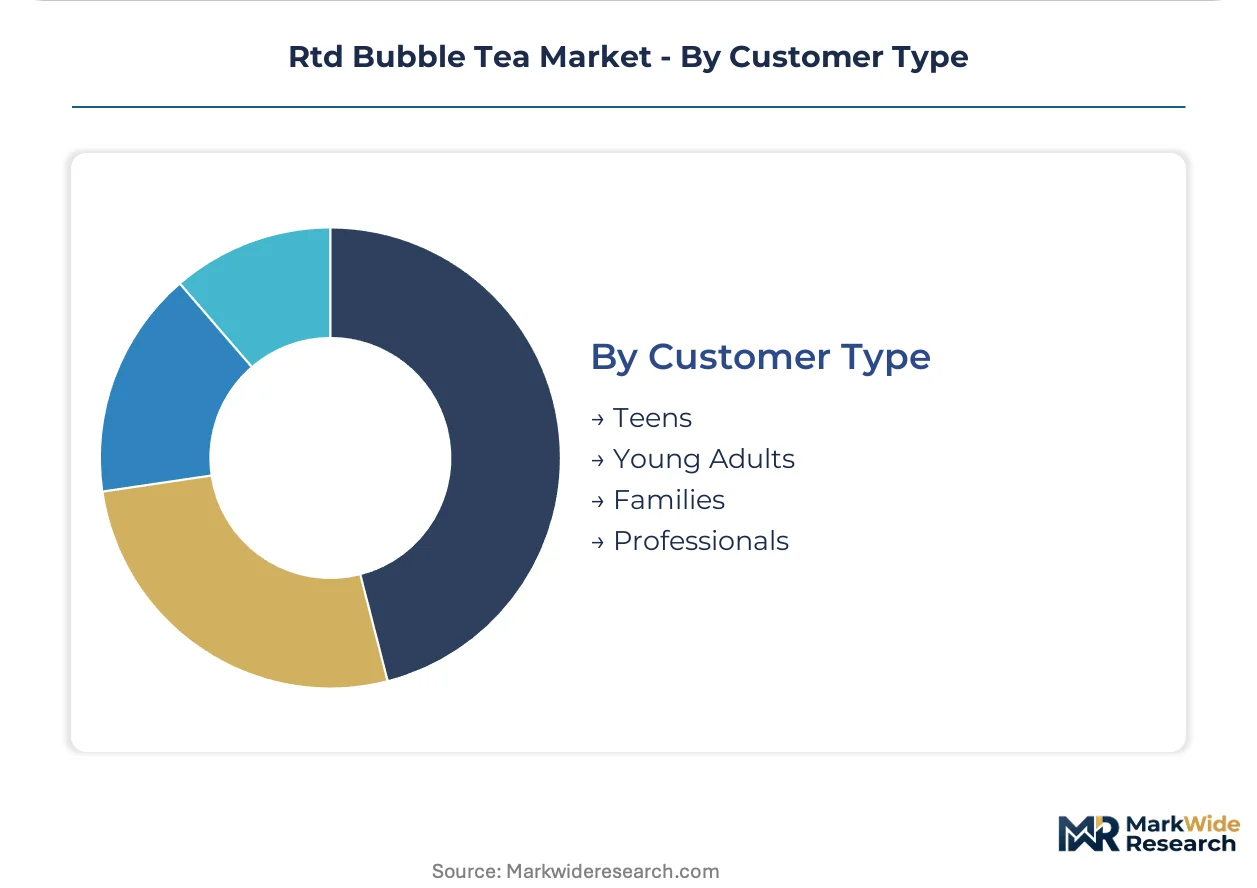
Customer Type:
Age cohort and consumption occasion determine flavor innovation pipelines and packaging size preferences.
- Young Adults:Consumers aged 18-35 with highest repurchase frequency for home-delivery programs. Curated flavor rotations and limited seasonal drops compress order intervals to under 14 days in metro Vietnam.
- Teens:Secondary school and university students with sub-dollar price sensitivity. Pouch format portability matches vending machine and canteen channel requirements.
- Professionals:Workplace consumption seeking caffeine convenience without coffee. Standard 350-500ml bottle formats dominate office pantry replenishment.
- Families:Multi-person households purchasing multi-packs for shared consumption. Value-oriented Tetra Pack formats reduce per-serving cost.
Repeat purchase intensity sits with Young Adults. New customer acquisition is targeting Teens through price-accessible formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of RTD bubble tea concentrates in Taiwan and Thailand, while consumption gravity shifts toward Vietnamese and Filipino metropolitan markets where convenience retail expansion outpaces manufacturing capacity.
Taiwan
Heritage tea houses and UHT processing facilities cluster around Taichung and Tainan, supplying export-ready formulations. The island's food safety authority enforces additive batch disclosure requirements that extend to imported beverages, forcing manufacturers to consolidate supplier bases. Taipei convenience store chains now dedicate refrigerated sections to pearl-inclusive pouches with nitrogen-flushed packaging.
Vietnam
Young adult consumers in Ho Chi Minh City generate the highest repurchase frequency for home-delivery bubble tea programs, compressing order intervals below 14 days. The country's Ministry of Health implements front-of-pack sugar labeling guidelines that complicate formulation strategies for health-claim variants. Da Nang and Can Tho secondary cities remain underserved relative to southern metro penetration rates.
Philippines
Metro Manila convenience stores exceed 60% RTD milk tea penetration while Cebu and Davao lack organized retail tea offerings. The Food and Drug Administration regulates sweetener declarations and preservative limits for shelf-stable beverages. Philippine school canteens and vending machines now stock sub-dollar pouch formats previously inaccessible to rigid bottle distribution.
Thailand
Cassava sourcing clusters in the Northeast and Central Plains expose multiple brands to synchronized weather volatility. The Thai Food and Drug Administration enforces strict clean-label standards that accelerate formulation investments for export-ready production. Bangkok convenience chains expand ambient tea shelf space in high-traffic urban locations.
United States
Asian grocery networks anchor controlled distribution for heritage brands entering North American markets. FDA oversight of food additive petitions and GRAS determinations shapes ingredient innovation for US-bound exports. Los Angeles and New York metropolitan areas concentrate demand among diaspora communities and young adult trialists.
Rtd Bubble Tea Market Competitive Landscape
Top-tier vendors anchor heritage tea house expansion into packaged formats, while mid-scale manufacturers compete through specialized processing partnerships. The vendor base stratifies across three tiers: established fresh-service chains converting to RTD, contract manufacturers with aseptic line investments, and emerging pouch-format specialists. Two strategic archetypes dominate: direct-to-consumer platform operators securing recurring revenue, and controlled distribution players leveraging Asian grocery networks. Competitive moves concentrate on manufacturing partnerships and curated flavor rotation programs.
Within the heritage tea house tier, Gong Cha exemplifies direct-to-consumer platform strategy through curated flavor rotations and subscription replenishment. CoCo Fresh Tea & Juice occupies a position anchored in controlled Asian grocery network distribution alongside native digital channels. Chatime sits within the specialized manufacturing partnership archetype, leveraging external aseptic processing capabilities to preserve tapioca texture in shelf-stable formats.
| Leading Market Players |
|---|
| Gong Cha |
| CoCo Fresh Tea & Juice |
| The Alley |
| Chatime |
| Kung Fu Tea |
| Tiger Sugar |
| Sharetea |
| HeyTea |
| Lollicup USA |
| Others |
Value Network & Pricing Analysis
Young adult subscription buyers in metro Vietnam and the Philippines anchor the dominant pricing model, with recurring home-delivery programs compressing order intervals below 14 days and forcing brands toward subscription-tiered structures that sacrifice per-unit margin for lifetime value capture.
Pricing Analysis
Pricing pressure intensifies in the economy pouch tier as Thai and Vietnamese cassava price volatility feeds through tapioca starch input costs. Three-tier pricing structure across premium nitrogen-flushed bottles, standard aseptic cartons, and economy spout pouches stratifies the market, with certification grade for Taiwan's additive disclosure rules and volume scale in ASEAN convenience chains serving as the primary differentiation levers. Teens in Philippine school canteens exhibit highest price sensitivity, while young adult subscribers in Ho Chi Minh City show lowest elasticity due to curated flavor rotation loyalty.
Supply Chain Analysis
Regional distribution centers in Bangkok, Taichung, and Ho Chi Minh City operate hub-and-spoke patterns that feed convenience store replenishment cycles. Manufacturing concentrates in Taiwan and Thailand, with cassava starch sourcing anchored in Northeast Thai and Central Plains agricultural belts. UHT processing equipment, aseptic cold-fill lines, and multi-layer flexible film packaging constitute critical input dependencies. Single-source vulnerability in Thai cassava regions exposes multiple brands to synchronized weather shocks. Distribution runs through controlled Asian grocery networks in North America and direct-to-consumer platforms in Southeast Asian metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RTD bubble tea market sits in a processing-technology transition, with nitrogen-flushed modified atmosphere packaging displacing legacy retort methods for pearl-inclusive formats.
For Market Incumbents: Extend aseptic line capacity in Taichung and Bangkok to defend against emerging pouch-format specialists exploiting lower capital intensity. Consolidate supplier bases to satisfy Taiwan's additive batch disclosure requirements. Channel control through direct-to-consumer platforms offers the strongest defensive lever against subscription-native entrants compressing order intervals. For New Entrants and Emerging Players: Aseptic-compatible plant-based creamer formulations offer a technology-first wedge into the non-dairy extension white space. Philippine secondary cities Cebu and Davao represent the most penetrable geography, with organized retail tea offerings lagging Metro Manila's saturation. Target school canteen and vending machine channels with sub-dollar pouch formats as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with installed aseptic cold-fill capacity and clean-label formulation capabilities. Long-term viability hinges on brands that can bridge fresh-service heritage with shelf-stable texture preservation. Watch for EU novel food approval timelines for modified starch pearls as the inflection signal for texture-innovative product expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Formulation Investment | Taiwan's FDA-equivalent additive disclosure rules force supplier consolidation and blockchain traceability adoption. |
| Pouch Format Channel Expansion | Flexible packaging unlocks Philippine school canteens and vending machines previously closed to rigid bottles. |
| Direct-to-Consumer Platform Buildout | Subscription replenishment in metro Vietnam compresses order intervals below 14 days and secures recurring revenue. |
| Aseptic Line Capacity Addition | UHT processing investments extend ambient stability to 12-18 months without refrigeration infrastructure dependency. |
| Plant-Based Line Extension | Oat and coconut milk processing advances enable non-dairy variants without dedicated production line segregation. |
Research Methodology
Document review covered customs records, FDA GRAS determinations, and Taiwan food safety authority filings, complemented by interviews with brand managers at heritage tea houses, category buyers at ASEAN convenience chains, UHT processing equipment specialists, and cassava starch procurement leads. Secondary validation drew from trade data, regulatory submission databases, and retail audit figures. Bottom-up demand modeling and top-down production capacity assessments were cross-referenced for triangulation.
Historical shipment patterns were cross-referenced against panel input from manufacturing executives to anchor the analytical framework across the analysis window. Segmentation dimensions included product type, packaging format, distribution channel, and customer age cohort. CAGRs were derived from curve-fitting approaches applied to volume and value trajectories, with inputs from UHT technology adoption curves and convenience store shelf-space expansion schedules.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts in preservative limits, cassava crop failures from climate events, and breakthroughs in ambient-stable tapioca texture replication. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
China Energy- Drinks Market