
 Low Fat Chocolate Cake Market | 2026-2036
Low Fat Chocolate Cake Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Chocolate Cake Market Analytics
ISO 22000 certification is rotating as the decisive qualification cycle separating contract manufacturers from branded players in low fat chocolate cake supply. General Mills leverages its refrigerated distribution network to dominate ready-to-eat placements in North American supermarkets. Mondelez International anchors its position through specialized cocoa processing capabilities that reduce fat content without compromising texture. Barry Callebaut AG competes by controlling chocolate liquor supply streams that enable precise fat calibration for industrial bakery customers.
Low fat chocolate cake denotes a baked dessert formulation containing reduced cocoa butter or alternative fat replacers while maintaining minimum chocolate solids content for flavor integrity; manufacturers employ emulsification systems and aeration techniques to compensate for moisture retention loss inherent in fat reduction. The ready-to-eat segment leads volume through convenience positioning in supermarket channels, though high-protein ingredient sourcing captures the fastest margin expansion as fitness-oriented consumers accept price premiums for macronutrient-dense alternatives. Organic ingredient sourcing sustains premium pricing in specialty shops where health food stores curate assortments for clean-label shoppers.
FDA nutrition labeling rules and the EU's Nutrition and Health Claims Regulation constrain permissible fat reduction claims while mandating disclosure of substitute ingredients. USDA organic certification and EFSA health claim assessments further segment market access between mass retail and premium channels. Stakeholders must monitor evolving sugar reduction mandates that threaten to compound formulation complexity beyond current fat replacement technologies.
Market Dynamics
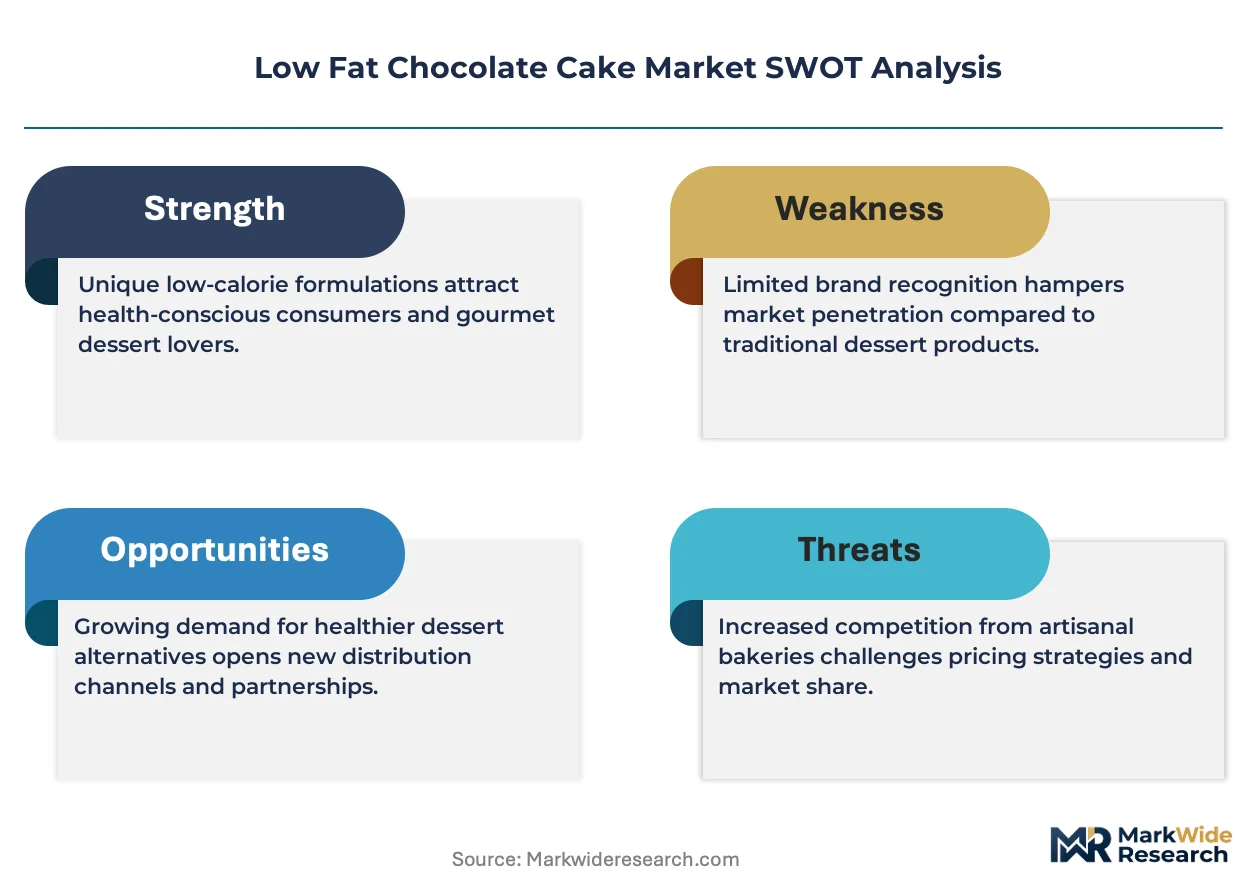
Fat replacer technology maturation is compressing formulation timelines while FDA and EFSA labeling constraints force simultaneous disclosure of substitute ingredients, creating a tension between speed-to-market and compliance depth.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Standardized fat reduction claim thresholds enable cross-border marketing consistency for reformulated products.
- Aeration technology advancement:Industrial bakeries deploy precision-controlled nitrogen injection systems to restore mouthfeel in reduced-fat formulations.
- Germany:Health food store density supports premium positioning for organic-certified low fat chocolate cake variants.
Market Restraints
- Cocoa butter price volatility:Confectionery-grade cocoa butter futures fluctuate with West African harvest cycles, compressing margin predictability for fat-replacer-dependent formulations.
- Emulsifier supply concentration:Specialty lecithin derivatives rely on a narrow supplier base in Southeast Asia.
- Moisture retention ceiling:Current hydrocolloid systems hit performance limits beyond 40% fat reduction without texture degradation.
Strategic Opportunities
- United States fitness channel:Gym-adjacent retail and protein-focused ecommerce platforms remain underpenetrated for macronutrient-optimized cake formats.
- USDA organic certification tailwind:Federal procurement preference for organic ingredients in school nutrition programs creates institutional demand.
- Plant protein convergence:Pea and fava protein isolates combine with reduced-fat chocolate matrices to capture dual-label shoppers.
Industry Challenges
- ISO 22000 certification timelines:Contract manufacturers face 8-14 month audit cycles that delay branded customer onboarding.
- Legacy equipment retrofit costs:Existing continuous mixing lines require capital-intensive modification for fat-replacer handling.
- Clean-label IP complexity:Proprietary emulsification patents create licensing friction for independent bakeries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Chocolate Cake Market |
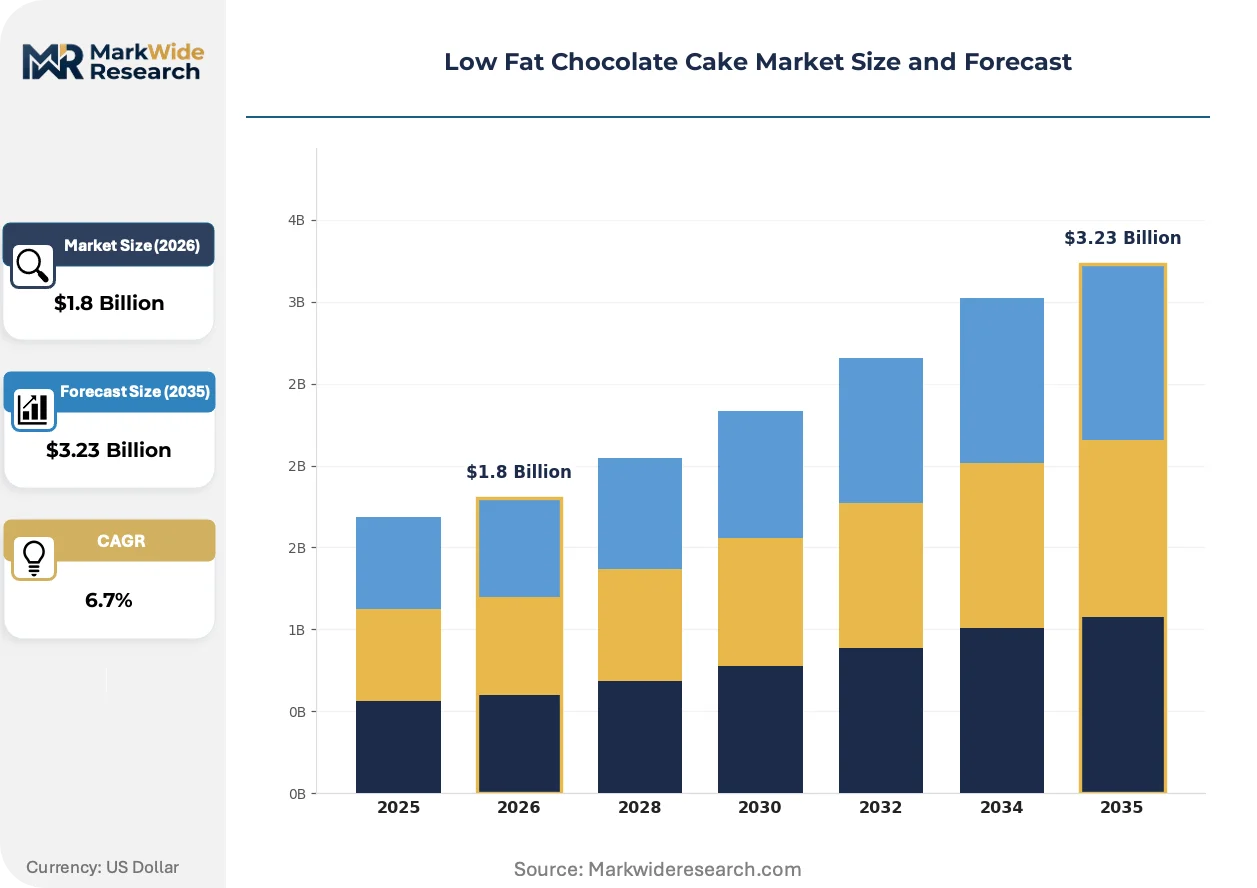
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Eat, Baking Mix, Frozen Dessert, Snack Bar Ingredient Source: Organic, Gluten-Free, Sugar-Free, High-Protein Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Specialty Shops Consumer Type: Health-Conscious Individuals, Dieters, Fitness Enthusiasts, Weight Watchers |
| Companies Covered | General Mills, Unilever, Mondelez International, Nestlé S.A., The Hershey Company, Grupo Bimbo, Hostess Brands, Danone S.A., Barry Callebaut AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Chocolate Cake Market Evolving Landscape
Formulation science is pivoting from single-ingredient fat substitution toward systems-level texture engineering, while regulatory disclosure requirements and channel fragmentation reshape how manufacturers prioritize R&D investment.
Microencapsulated water-in-oil emulsion technology is miniaturizing fat droplet distribution to sub-micron scale, enabling industrial bakeries to reduce cocoa butter content by 35% while preserving fracture mechanics. Ready-to-eat manufacturers in Germany and the United States are adopting these systems at pilot scale. The technology is miniaturizing the performance gap between full-fat and reduced-fat chocolate cake matrices, compressing the premium that clean-label formulations command.
EFSA health claim assessments are tightening evidentiary standards for fat reduction claims, requiring manufacturers to submit compositional data and consumer perception studies before market entry. This procedural density favors mid-cap players with dedicated regulatory affairs functions over smaller artisan producers. Clean-label segments in France and Italy are responding by pre-substituting sugar alongside fat to future-proof formulations against parallel sugar reduction mandates.
Direct-to-consumer subscription models are displacing traditional supermarket slotting-fee structures for specialty low fat chocolate cake brands, concentrating customer acquisition spend on retention metrics rather than retail placement. Fitness-oriented consumers in the United States demonstrate highest subscription stickiness when products carry dual protein-plus-reduced-fat positioning. This channel rotation is most visible in coastal metropolitan markets where cold-chain logistics density supports fresh delivery windows.
Low Fat Chocolate Cake Market Segmentation
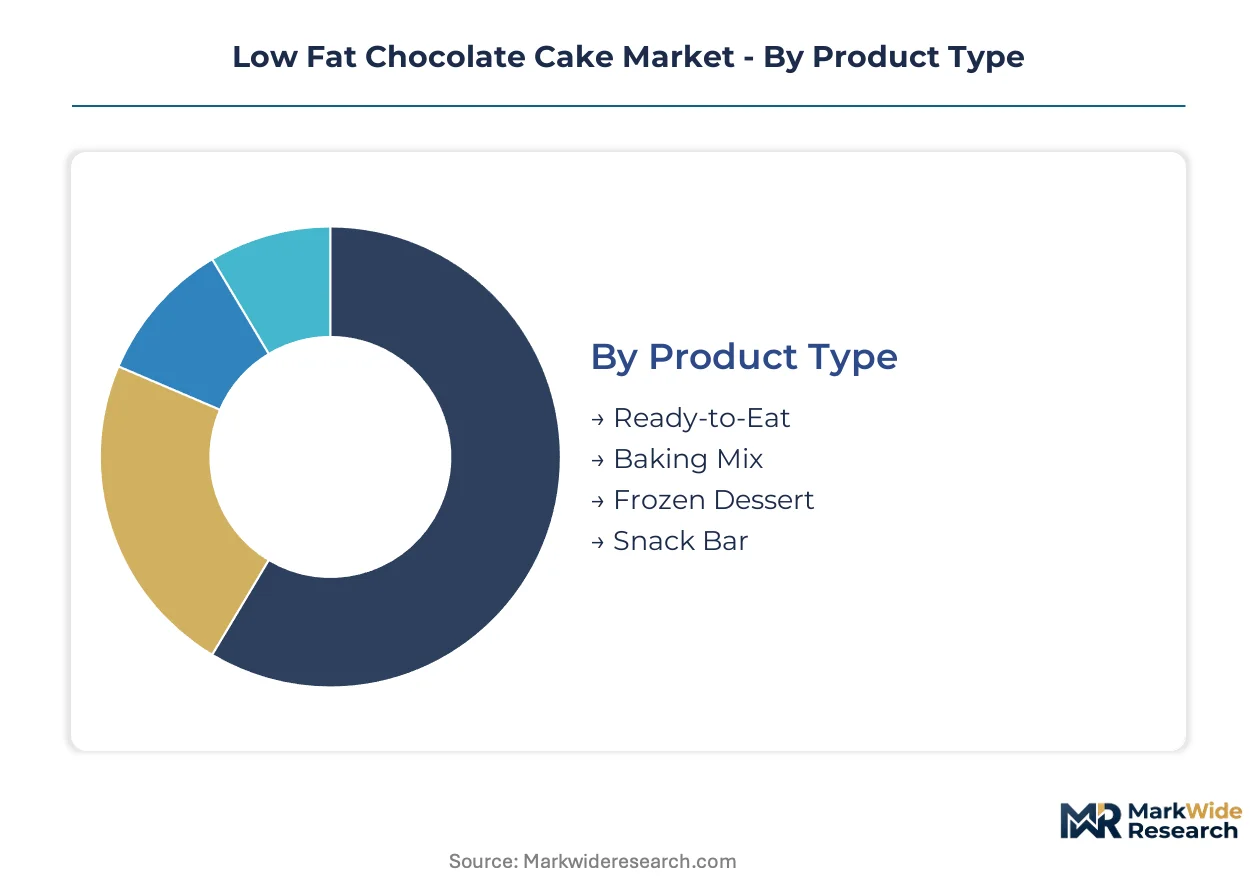
Segmentation in low fat chocolate cake markets reveals where formulation investments concentrate and which channel incentives reshape product architecture. Manufacturers calibrate fat replacer systems and certification levels to match margin structures across distinct consumption occasions.
Product Type:
Margin pools concentrate in convenience-positioned formats where refrigerated distribution and shelf-stable packaging create differentiated cost tiers.
- Ready-to-Eat:Pre-portioned cakes employ modified atmosphere packaging and emulsification systems to maintain moisture at 35-40% fat reduction. Demand clusters in United States supermarket refrigerated cases where slotting fees favor established bakery brands with cold-chain density.
- Baking Mix:Dry blends combine defatted cocoa powders with hydrocolloid stabilizers for home preparation. Germany's health food store networks sustain premium positioning for organic-certified variants with precise fat calibration instructions.
- Frozen Dessert:Blast-frozen formulations use cryoprotectant hydrocolloids to control ice crystal formation during fat reduction.
- Snack Bar:Extruded and enrobed formats integrate protein isolates with reduced-fat chocolate coatings for gym-adjacent retail.
Ready-to-Eat holds installed capacity. Snack Bar is rotating up the share rankings.
Ingredient Source:
Certification tiering separates mass retail access from specialty channel premiums, with protein fortification commanding the steepest expansion trajectory.
- High-Protein:Pea and fava protein isolates replace flour fractions while maintaining cake crumb structure, targeting fitness enthusiasts in United States ecommerce channels who accept price premiums for macronutrient density.
- Organic:USDA-certified formulations restrict fat replacer options to clean-label hydrocolloids and lecithin sources. Institutional demand from federal school nutrition programs in the United States reinforces supply contract stability.
- Gluten-Free:Rice and tapioca starch systems compensate for gluten network absence in reduced-fat matrices.
- Sugar-Free:Polyol sweeteners and high-intensity stevia derivatives compound formulation complexity alongside fat reduction mandates.
Organic holds installed capacity. High-Protein is rotating up the share rankings.
Distribution Channel:
Channel control determines whether manufacturers absorb slotting economics or capture direct customer lifetime value through subscription retention.
- Supermarkets:Refrigerated and ambient shelf placements dominate volume in United States and Germany, where category managers prioritize turn velocity and promotional fund participation over margin percentage.
- Online Retailers:Direct-to-consumer subscription models concentrate acquisition spend on retention metrics rather than retail placement fees, with highest stickiness among dual protein-plus-reduced-fat positioned products in coastal United States metropolitan markets.
- Health Food Stores:Curated assortments for clean-label shoppers sustain premium pricing for organic and allergen-free variants.
- Specialty Shops:Independent bakeries and confectioners command localized loyalty through freshness positioning and custom formulation services.
Supermarkets hold installed capacity. Online Retailers is rotating up the share rankings.
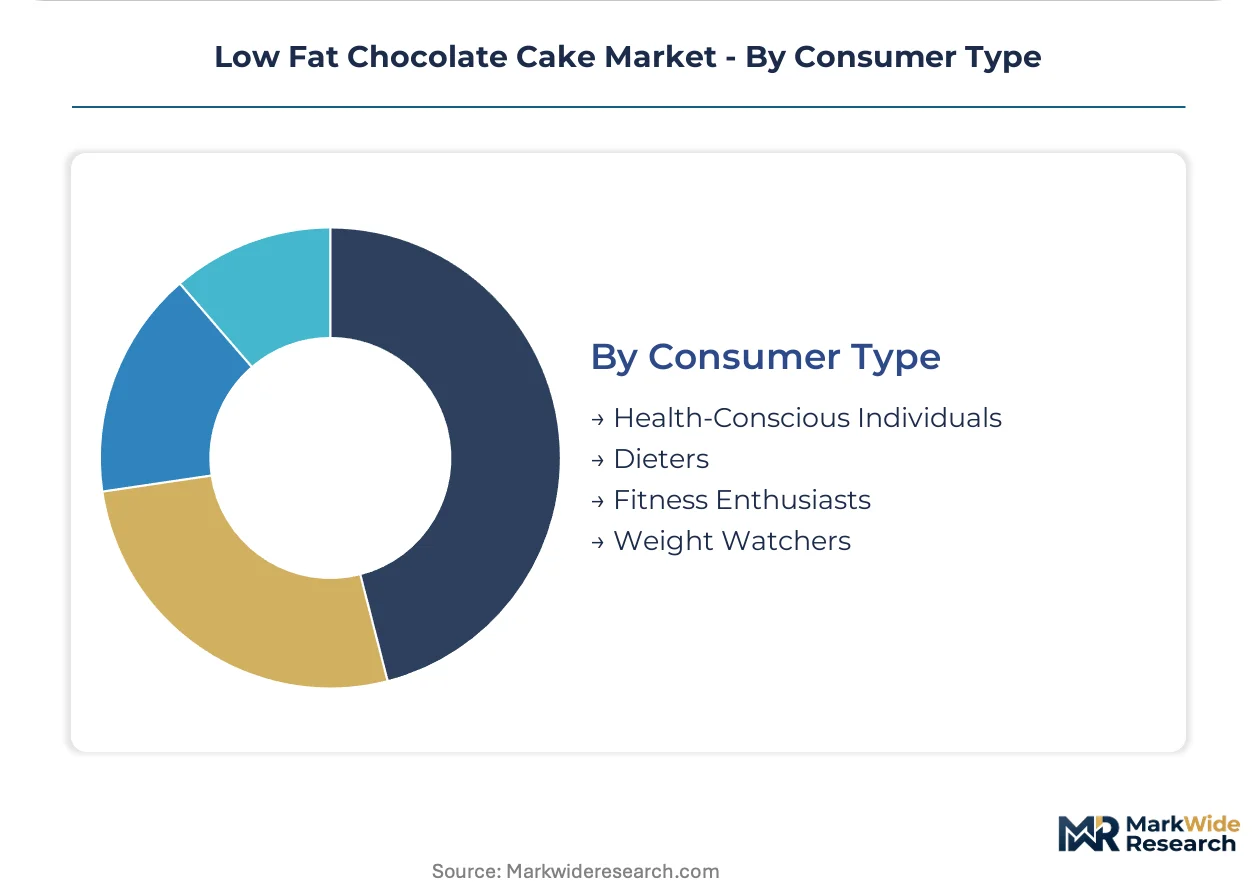
Consumer Type:
Behavioral segmentation aligns formulation architecture with distinct motivation profiles, from metabolic management to performance optimization.
- Fitness Enthusiasts:Macronutrient-tracking consumers prioritize protein-to-calorie ratios and post-workout glycemic response, driving fastest adoption of high-protein snack bar formats in United States gym-adjacent retail.
- Health-Conscious Individuals:Clean-label seekers evaluate ingredient panel length and certification marks, concentrating demand in Germany's organic-specialized retail and United States natural channel stores.
- Dieters:Calorie-controlled portion formats with explicit fat reduction claims attract consumers managing metabolic conditions under FDA and EFSA labeling constraints.
- Weight Watchers:Points-system compatibility and portion transparency influence purchase decisions in mass retail environments.
Health-Conscious Individuals hold installed capacity. Fitness Enthusiasts is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling rules and USDA school nutrition program incentives are concentrating low fat chocolate cake production capacity in North American markets. EFSA health claim assessments and EU organic certification standards are redirecting European formulation investments toward clean-label compliance.
United States
Fitness enthusiasts in coastal metropolitan markets drive demand for high-protein snack bar formats with dual reduced-fat positioning. FDA disclosure requirements for fat replacer ingredients mandate compositional transparency on packaging panels. Cold-chain logistics density in California and New York Metro supports direct-to-consumer subscription models for fresh ready-to-eat products.
Germany
Health food store networks sustain premium pricing for organic-certified baking mixes with precise fat calibration instructions. EFSA tightened evidentiary standards for fat reduction claims require pre-market submission of consumer perception studies. Industrial bakery clusters in Bavaria pilot microencapsulated emulsion technology to restore mouthfeel in reduced-fat formulations.
United Kingdom
Clean-label shoppers evaluate ingredient panel length and certification marks in supermarket ambient shelf placements. EU Nutrition and Health Claims Regulation standardized thresholds enable cross-border marketing consistency for reformulated products. Greater London and Southeast England concentrate direct-to-consumer subscription fulfillment infrastructure for specialty brands.
France
Artisan producers in Île-de-France pre-substitute sugar alongside fat to future-proof formulations against parallel sugar reduction mandates. ANSM and DGCCRF enforcement of nutritional claim standards constrains permissible marketing language. Lyon and Auvergne-Rhône-Alpes host mid-cap players with dedicated regulatory affairs functions navigating EFSA procedural density.
Canada
Health Canada and PMRA oversight of food additive approvals limits emulsifier sourcing options for fat-replacer-dependent formulations. Ontario and Quebec concentrate refrigerated distribution networks serving cross-border supermarket channels. Institutional procurement preferences for organic ingredients in federal nutrition programs reinforce supply contract stability for certified producers.
Low Fat Chocolate Cake Market Competitive Landscape
Listed leaders compete with private specialists across certification and channel access dimensions. The vendor base stratifies between scale-driven multinationals with cold-chain density and mid-cap players with dedicated regulatory affairs functions. Three archetypes dominate: diversified food conglomerates with refrigerated distribution networks, specialized cocoa processors with fat calibration capabilities, and contract manufacturers pursuing ISO 22000 certification. Competitive moves concentrate on backward integration into cocoa liquor supply streams and strategic partnerships with fitness-oriented ecommerce platforms.
Within the diversified conglomerate tier, General Mills and Mondelez International exemplify scale-driven positioning through refrigerated infrastructure and specialized processing capabilities respectively. Barry Callebaut AG occupies a distinct niche as a Swiss-based ingredients specialist controlling supply streams that enable precise fat calibration. These three entities anchor the competitive structure by representing divergent strategic bets on channel control versus ingredient technology.
| Leading Market Players |
|---|
| General Mills |
| Unilever |
| Mondelez International |
| Nestlé S.A. |
| The Hershey Company |
| Grupo Bimbo |
| Hostess Brands |
| Danone S.A. |
| Barry Callebaut AG |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, forcing contract manufacturers to absorb 8-14 month audit cycles while branded players command premiums for verified food safety management systems. FDA and EFSA labeling disclosure requirements for fat replacer ingredients further stratify pricing tiers, as compliant formulation transparency becomes a non-negotiable cost of market access.
Pricing Analysis
Certification level creates the primary spread between mass retail and premium channel pricing. Three-tier pricing structure across premium, standard, and economy levels reflects USDA organic certification, ISO 22000 compliance, and conventional formulation grades respectively. Cost compression in the standard tier intensifies because cocoa butter price volatility and emulsifier supply concentration squeeze margin predictability. Fitness enthusiasts demonstrate lowest price sensitivity for high-protein variants, while dieters in mass retail show highest elasticity to promotional pricing.
Supply Chain Analysis
Southeast Asian lecithin derivative concentration anchors emulsifier sourcing for fat-replacer-dependent formulations. West African cocoa butter harvest cycles and Southeast Asian specialty hydrocolloid production form the dual geographic spine of raw material procurement. Single-source vulnerability in confectionery-grade cocoa butter futures exposes manufacturers to margin compression during harvest disruptions. Distribution runs through refrigerated networks controlled by diversified conglomerates in North America and industrial bakery clusters in Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulated emulsion technology is disrupting texture engineering economics, compressing the performance gap between full-fat and reduced-fat matrices while EFSA evidentiary standards for health claims raise compliance barriers to entry.
For Market Incumbents: Fortify cold-chain density in coastal United States metropolitan markets where subscription retention metrics now outweigh supermarket slotting-fee economics. Deepen backward integration into cocoa liquor supply streams to control fat calibration precision and offset cocoa butter price volatility. Prioritize dedicated regulatory affairs functions to navigate EFSA procedural density that favors mid-cap players over artisan producers. For New Entrants and Emerging Players: Gym-adjacent retail service layers remain under-served by incumbent refrigerated distribution networks focused on supermarket velocity. Target United States fitness channel ecommerce platforms with dual protein-plus-reduced-fat positioning where consumer stickiness concentrates. Deploy direct-to-consumer subscription models to bypass slotting-fee structures and capture customer lifetime value through retention metrics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract manufacturing tiers as ISO 22000 certification standardizes quality infrastructure. Long-term viability favors mid-cap players with dedicated regulatory affairs functions navigating EFSA and FDA disclosure requirements. Acquisition target archetypes include specialized cocoa processors with fat calibration capabilities and fitness-oriented ecommerce platforms with proven retention metrics. Watch for inflection in sugar reduction mandate timing that compounds formulation complexity beyond current fat replacement technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cocoa Liquor Supply | Barry Callebaut AG's supply stream control enables precise fat calibration for industrial bakery customers. |
| Direct-to-Consumer Subscription Launch | Fitness-oriented consumers in California and New York Metro demonstrate highest retention for fresh ready-to-eat formats. |
| ISO 22000 Certification Investment | Contract manufacturers separate from branded players through 8-14 month audit cycles that delay customer onboarding. |
| High-Protein Formulation Extension | Pea and fava protein isolates capture dual-label shoppers seeking macronutrient density in gym-adjacent retail. |
| Microencapsulated Emulsion Technology Adoption | Bavaria industrial bakery clusters pilot sub-micron fat droplet distribution to restore mouthfeel at 35% cocoa butter reduction. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA nutrition labeling guidance documents, EFSA health claim assessment registers, and USDA organic certification databases. Interviews with refrigerated distribution network managers, contract manufacturing quality directors, health food store category buyers, and fitness channel ecommerce operators informed supply chain and channel dynamics. Secondary validation drew from customs records of cocoa butter and hydrocolloid trade flows, SEC filings of diversified food conglomerates, and EU Nutrition and Health Claims Regulation implementation reports. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Segmentation dimensions modeled span product type, ingredient source, distribution channel, and consumer motivation profile across the projection horizon. Ready-to-eat, baking mix, frozen dessert, and snack bar formats intersect with organic, high-protein, gluten-free, and sugar-free certification tiers. CAGRs were derived from volume trajectory analysis weighted by channel margin structures and regulatory access constraints. Industry-specific forecast inputs include cocoa butter futures price volatility indices and health food store network density metrics in Germany and the United States.
Underlying assumptions cover sustained FDA and EFSA labeling disclosure requirements, with deviation risk concentrated in accelerated sugar reduction mandate timelines and Southeast Asian emulsifier supply disruptions. Practitioners should keep alternative scenarios live as regulatory evidentiary standards and cold-chain logistics economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Improver Market
Bakery Products
Bread Market
Bakery Products
Toasted Flour Market
Bakery Products
Doughnuts Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Bakery Improvers Market
Bakery Products
India Cake Market
Bakery Products
Baking Mats Market
Bakery Products
No-Fat Cake Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Ezekiel Bread Market
Bakery Products
Dough Whitener Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Pizza Crust Market