
 US NFC Lemon Juice Market | 2026-2036
US NFC Lemon Juice Market Size, Share, and Industry Trends Forecast 2026-2036
US NFC Lemon Juice Market Outlook
Multi-source citrus procurement is realigning how US bottlers manage seasonality risk and flavor consistency. Florida's Natural Growers anchors its supply through cooperative grower networks across the Sunshine State. Langer Juice Company differentiates via specialized not-from-concentrate processing lines that preserve volatile aromatic compounds. Louis Dreyfus Company leverages global citrus trading infrastructure to buffer domestic harvest volatility.
Not-from-concentrate lemon juice denotes pasteurized citrus juice that bypasses evaporation and reconstitution, retaining natural Brix levels between 7.5 and 8.5 degrees and a minimum 4.5% citric acid content for food safety stability. Beverage applications dominate volume absorption, with organic product type commanding premium shelf positioning and margin concentration in specialty retail channels. Conventional product type sustains mainstream supermarket penetration where price elasticity remains acute.
FDA juice HACCP rules and USDA organic certification requirements shape processing standards, labeling claims, and interstate commerce compliance burdens. California's state-level Proposition 65 enforcement adds contaminant testing obligations that outpace federal minimums. Stakeholders must monitor water stress in Arizona and Texas growing regions alongside evolving EPA pesticide tolerance revisions.
Market Dynamics
Cold-press pasteurization technology is compressing thermal degradation windows while FDA juice HACCP updates force processor recertification cycles. These dual pressures are restructuring capital deployment timelines across California and Florida processing corridors.
Growth Catalysts
- Beverage manufacturer demand:Functional drink formulators are absorbing NFC lemon juice volumes for pH stabilization and clean-label positioning in sparkling water and kombucha lines.
- California Proposition 65 enforcement:Contaminant testing obligations exceeding federal minimums are creating compliance moats for certified processors who can verify heavy metal thresholds.
- Cooperative grower networks:Pooled citrus procurement across Florida's citrus belt is flattening seasonality volatility and securing year-round Brix consistency for bottlers.
Market Restraints
- Input cost volatility:Water stress in Arizona and Texas growing regions is elevating irrigation infrastructure spend and squeezing margin structures for Southwest suppliers.
- Supply concentration risk:California's Central Valley dominates domestic lemon cultivation, exposing processors to single-state climate disruption and labor availability shocks.
- Substitution pressure:Citric acid from fermented corn and synthetic flavor systems are capturing cost-sensitive beverage applications where aromatic fidelity is deprioritized.
Strategic Opportunities
- Organic certification tailwind:USDA organic label requirements are commanding premium shelf positioning in specialty retail channels where margin concentration exceeds conventional supermarket tiers.
- Emerging foodservice applications:Draft cocktail programs and craft mocktail menus in Texas and Florida metro markets are absorbing bulk NFC volumes for front-of-house citrus programs.
- EPA pesticide tolerance revisions:Tightening residue limits are creating first-mover advantages for processors with established integrated pest management documentation and third-party audit trails.
Industry Challenges
- Volatile aromatic compound retention:Maintaining flavor integrity through non-thermal pasteurization requires specialized equipment calibration expertise that outpaces current technician training pipelines.
- Interstate commerce compliance burden:Harmonizing California state-level testing with FDA juice HACCP rules is extending product launch timelines and multiplying documentation overhead for multi-state distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US NFC Lemon Juice Market |
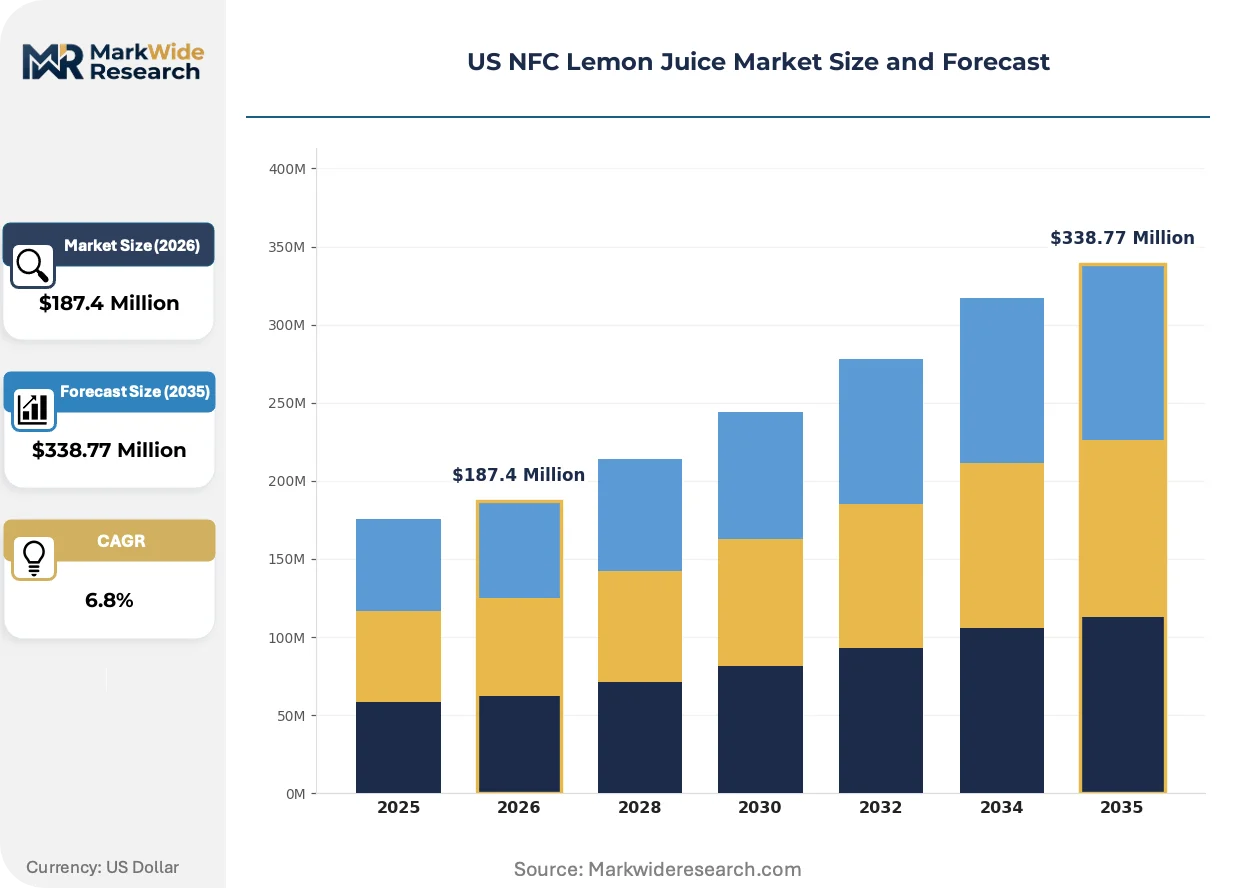
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Concentrate, Freshly Squeezed End Use: Beverages, Marinades, Dressings, Baking Packaging Type: Bottles, Cartons, Pouches, Jars Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Baor Products S.L., Florida's Natural Growers, Citrus World Inc., Louis Dreyfus Company, Langer Juice Company, Dream Foods International, Bevolution Group, Dohler GmbH, LemonConcentrate S.L., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US NFC Lemon Juice Market Strategic Shifts
Processing technology convergence and regulatory tightening are compressing operational margins while opening differentiation pathways for certified operators. These forces are reshaping capital allocation and procurement relationships.
High-pressure processing (HPP) systems are integrating into NFC lemon juice lines to eliminate thermal exposure while achieving 5-log pathogen reduction. Beverage manufacturers with organic portfolios are adopting HPP at accelerated rates to preserve enzymatic activity and volatile terpene profiles. This integration is enabling clean-label claims that command shelf price premiums in specialty retail channels.
FDA's updated juice HACCP regulations are mandating validated critical control points for enteric pathogen monitoring and corrective action documentation. Processors must now maintain continuous temperature logging and supplier verification records that exceed prior enforcement intensity. California and Florida bottlers are responding by consolidating supplier audits and investing in in-house microbiology testing capacity.
Direct procurement relationships between processors and foodservice operators are displacing traditional distributor intermediaries in high-volume metro markets. Restaurant groups and hospitality chains are negotiating bulk tanker deliveries and custom Brix specifications that bypass wholesale channels. This disintermediation is most visible in Florida's tourism corridor and Texas urban centers where volume concentration justifies dedicated logistics arrangements.
US NFC Lemon Juice Market Segmentation
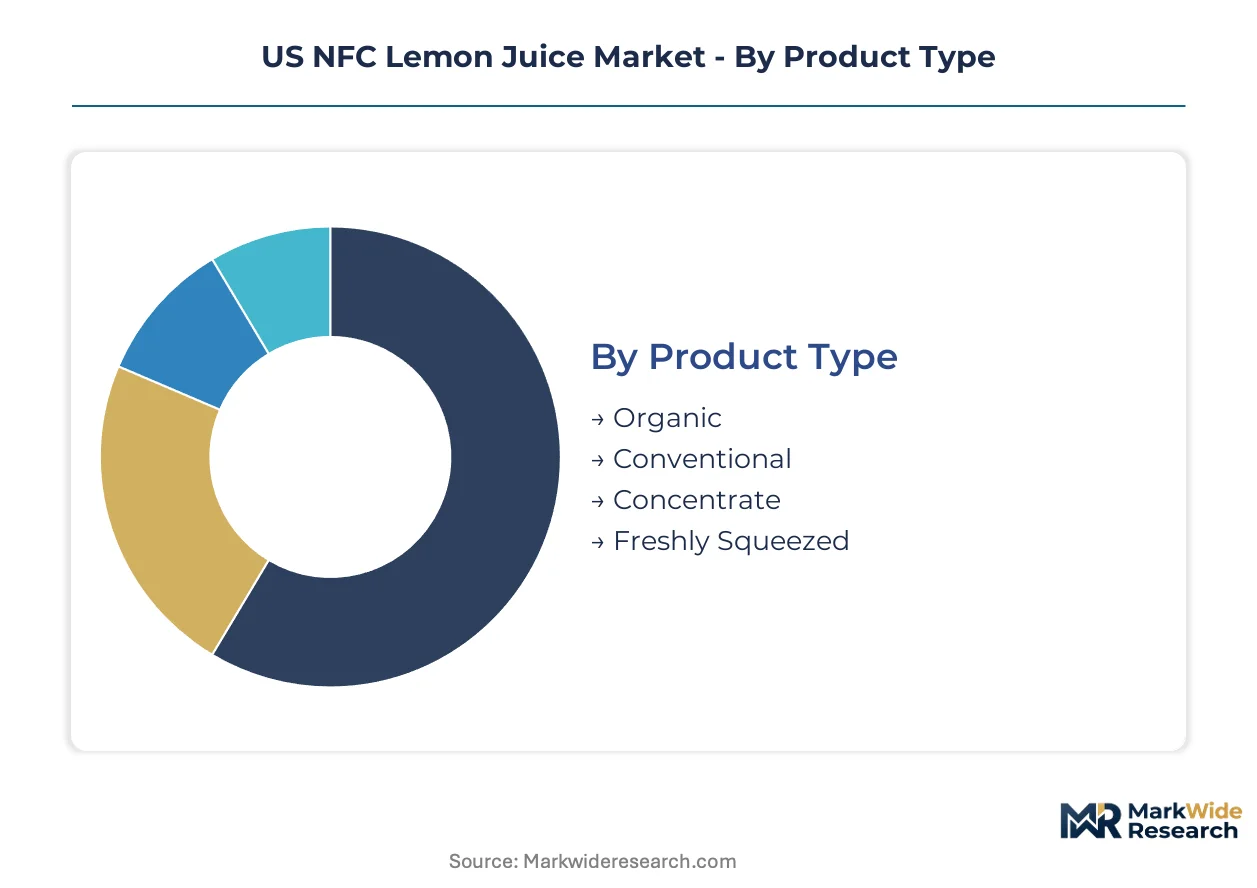
NFC lemon juice segmentation reveals how product positioning, packaging economics, and channel access create distinct margin tiers. Processors must align certification levels and format choices with specific buyer workflows to capture value.
Product Type:
Organic certification sits as a standalone premium tier with dedicated supply chains, while conventional and concentrate grades embed into broader ingredient systems where cost efficiency dominates procurement decisions.
- Organic:USDA-certified juice maintains traceable grower documentation and third-party audit trails. Beverage manufacturers in California's Central Valley absorb volumes for clean-label sparkling water lines where citric acid alternatives fail aromatic benchmarks. FDA juice HACCP compliance adds documentation overhead that smaller processors struggle to sustain.
- Conventional:Pasteurized NFC juice at standard Brix levels serves mainstream supermarket private labels. Florida's citrus belt cooperative networks supply year-round volumes to bottlers prioritizing price stability over volatile compound retention. Margin compression is acute as citric acid from fermented corn captures cost-sensitive applications.
- Concentrate:Reconstituted juice reduces logistics spend for long-haul distribution. Food manufacturers in Texas metro markets specify concentrate for processed sauces where flavor fidelity is secondary to shelf stability.
- Freshly Squeezed:Unpasteurized product with minimal processing retains enzymatic activity. High-end foodservice operators in Florida's tourism corridor specify tanker deliveries for front-of-house cocktail programs.
Conventional leads volumes today; organic is gaining share fastest.
End Use:
Application segmentation tracks how pH stabilization requirements and aromatic intensity thresholds reshape procurement relationships across buyer categories.
- Beverages:Functional drink formulators absorb NFC volumes for kombucha and sparkling water pH control. Cold-press pasteurization preserves terpene profiles that HPP-equipped processors leverage for clean-label claims. California Proposition 65 enforcement creates compliance moats for certified suppliers.
- Marinades:Acidic tenderization applications prioritize citric acid content over volatile aromatics. Meat processors in Texas specify bulk tanker deliveries with custom acidity specifications.
- Dressings:Emulsion stability requirements drive Brix consistency demands. Refrigerated salad dressing manufacturers source through wholesale channels with quarterly volume commitments.
- Baking:Leavening activation and flavor enhancement use cases tolerate wider specification ranges. Commercial bakeries in Arizona and New Mexico absorb lower-grade concentrate volumes.
Beverages command premium pricing; marinades show steepest volume expansion trajectory.
Packaging Type:
Format selection hinges on shelf-life extension requirements, logistics density, and retail channel merchandising constraints.
- Bottles:PET and glass formats dominate refrigerated retail sections. Florida bottlers invest in lightweight PET lines to reduce freight costs for supermarket distribution.
- Cartons:Aseptic carton technology enables ambient distribution with extended shelf stability. California processors deploy cartons for organic lines targeting specialty retail channels.
- Pouches:Flexible formats reduce material costs and shipping cube. Foodservice bulk pouches serve Texas hospitality chains with dedicated logistics arrangements.
- Jars:Glass jar positioning targets premium pantry segments. Small-batch processors in Florida's citrus belt use jars for direct-to-consumer channels.
Bottles retain volume leadership; pouches are climbing the fastest as foodservice disintermediation accelerates.
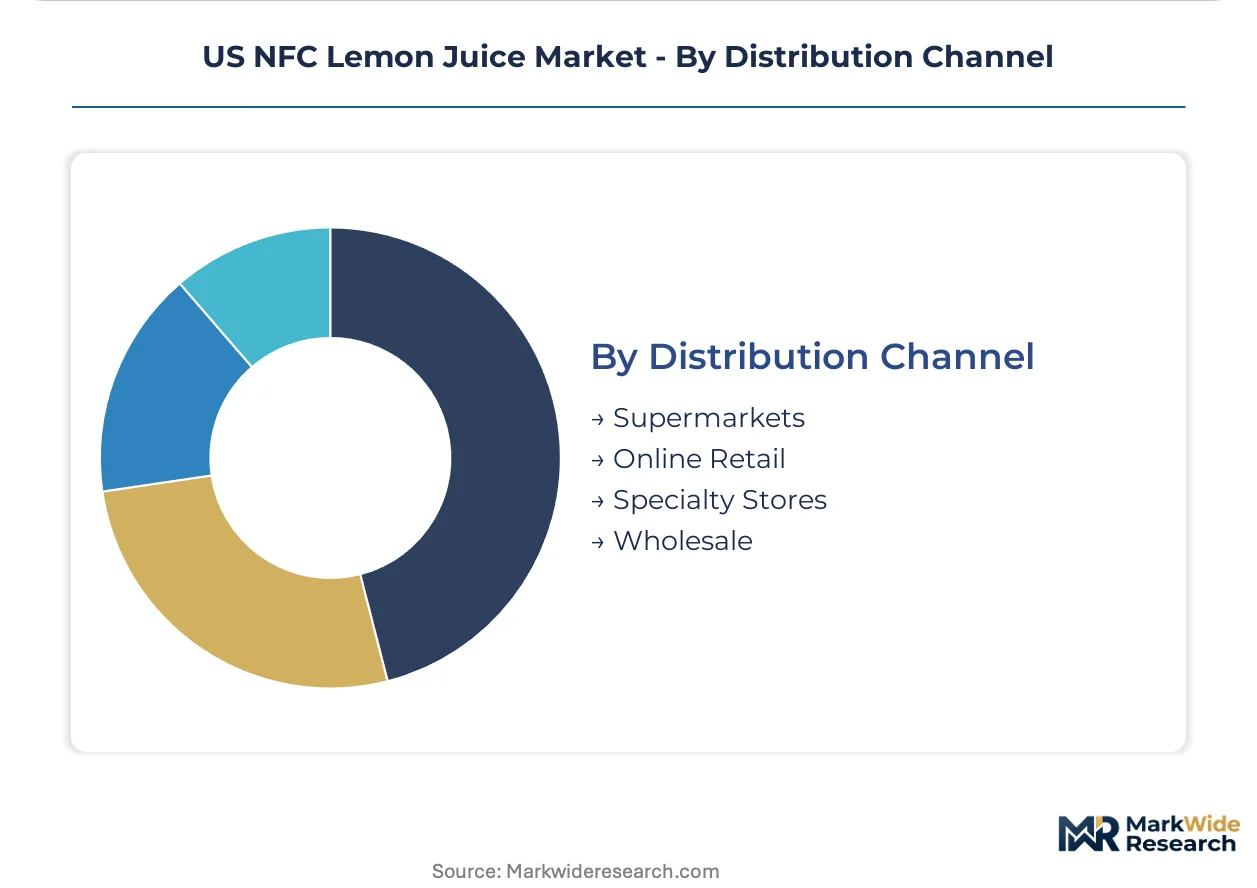
Distribution Channel:
Channel segmentation tracks how direct procurement relationships are restructuring traditional wholesale intermediation in high-volume metro markets.
- Supermarkets:Mainstream retail chains absorb conventional product through centralized distribution centers. Price elasticity remains acute as private labels compete on shelf positioning.
- Online Retail:Direct-to-consumer subscription models concentrate in organic segments. California-based processors leverage EPA pesticide tolerance documentation for digital marketing claims.
- Specialty Stores:Independent retailers command premium shelf placement for certified organic SKUs. Margin concentration exceeds conventional supermarket tiers by significant spreads.
- Wholesale:Traditional distributor intermediaries face displacement as restaurant groups negotiate direct tanker deliveries. Florida's tourism corridor and Texas urban centers drive this disintermediation.
Supermarkets anchor volume absorption; online retail shows sharpest share acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley anchors US NFC lemon juice production capacity, with processing corridors concentrated in Fresno and Tulare counties where cooperative packing houses handle seasonal volume surges.
California
Beverage manufacturers in Los Angeles and San Francisco Bay Area absorb organic-certified volumes for clean-label product lines. FDA juice HACCP compliance costs escalate under state-level Proposition 65 enforcement, which mandates heavy metal testing beyond federal minimums. Central Valley processors in Tulare County are consolidating supplier audits to manage documentation overhead.
Florida
Florida's citrus belt cooperative networks supply year-round volumes to bottlers prioritizing price stability. The state's Department of Citrus administers quality inspection protocols that exceed baseline USDA standards. Orlando and Miami metro markets drive foodservice disintermediation as restaurant groups negotiate direct tanker deliveries for cocktail programs.
Texas
Meat processors in Houston and Dallas specify bulk NFC lemon juice for marinade applications with custom acidity specifications. EPA pesticide tolerance revisions are tightening residue limits for imported citrus used in border-state processing. San Antonio hospitality chains are absorbing pouch-format volumes through dedicated logistics arrangements.
Arizona
Water stress in Yuma County elevates irrigation infrastructure spend for lemon growers supplying Southwest processors. The state's Department of Environmental Quality enforces groundwater monitoring requirements that add compliance layers to agricultural operations. Phoenix-area food manufacturers tolerate wider specification ranges for baking applications using lower-grade concentrate volumes.
US NFC Lemon Juice Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue organic certification and cold-press technology differentiation. The vendor base clusters around three strategic archetypes: cooperative-backed citrus processors with captive grower networks, global trading houses leveraging international supply buffers, and specialized not-from-concentrate bottlers preserving aromatic compound integrity. Dominant competitive moves include backward integration into grower cooperative structures and technology licensing for high-pressure processing systems.
Within the cooperative-processor tier, Florida's Natural Growers and Citrus World Inc. exemplify grower-owned structures that flatten seasonality volatility through pooled procurement. Louis Dreyfus Company represents the global trading house archetype, occupying a position that buffers domestic harvest fluctuations through international citrus infrastructure. Langer Juice Company anchors the specialized processing segment, sitting within the tier of operators differentiated by not-from-concentrate line configurations.
| Leading Market Players |
|---|
| Baor Products S.L. |
| Florida's Natural Growers |
| Citrus World Inc. |
| Louis Dreyfus Company |
| Langer Juice Company |
| Dream Foods International |
| Bevolution Group |
| Dohler GmbH |
| LemonConcentrate S.L. |
| Others |
Value Chain & Pricing Dynamics
Family-owned cooperative processors across Florida's citrus belt anchor supply discipline through pooled grower financing, translating captive procurement into pricing stability that insulates year-round contract rates from spot-market citrus volatility. Their collective ownership structure compresses margin leakage at origin, passing cost efficiency downstream to bottlers while maintaining Brix consistency premiums.
Pricing Analysis
Input-cost pass-through from irrigation infrastructure spend in water-stressed Arizona and Texas growing regions is compressing margins for Southwest suppliers, forcing contract renegotiations with Texas meat processors. Pricing stratifies across premium organic certification, standard conventional pasteurized grades, and economy concentrate tiers, with USDA organic documentation commanding shelf price premiums in California specialty retail. Cost compression in conventional segments is intensifying because citric acid from fermented corn captures pH-sensitive beverage applications. Beverage manufacturers show least price sensitivity for aromatic fidelity, while commercial bakeries tolerate widest specification ranges for leavening-grade concentrate.
Supply Chain Analysis
Single-source vulnerability sits with California's Central Valley, which dominates domestic lemon cultivation and exposes processors to climate disruption and labor availability shocks. The supply chain draws from California, Florida, and Arizona growing regions, with raw material dependencies on irrigation water access, seasonal labor pools, and citrus peel oil co-product markets. Tariff exposure on imported citrus concentrate creates margin pressure for border-state processors in Texas. Distribution runs through cooperative packing houses in Fresno and Tulare counties, direct tanker deliveries to Florida and Texas foodservice operators, and wholesale channels serving supermarket private labels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US NFC lemon juice market reads as a late-cycle quality story, with beverage manufacturer demand shifting toward cold-press pasteurization and organic certification as non-negotiable specifications for clean-label positioning.
For Market Incumbents: Anticipate substitution pressure from synthetic flavor systems by deepening backward integration into Florida cooperative grower networks and investing in in-house high-pressure processing capacity. Secure Proposition 65 compliance documentation as a defensive moat against California enforcement escalation. Channel control through direct procurement relationships with Texas and Florida restaurant groups protects volume absorption against wholesale disintermediation. For New Entrants and Emerging Players: Cold-press pasteurization technology offers a technology-first wedge into organic beverage manufacturing segments where aromatic compound retention commands premium pricing. Target Arizona and New Mexico baking applications as the most penetrable volume tier, where specification tolerance permits lower-grade concentrate entry. A foodservice-focused go-to-market angle leveraging bulk pouch logistics to Texas hospitality chains bypasses entrenched supermarket distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among conventional processors exposed to citric acid substitution and water stress margin compression. Long-term viability favors operators with integrated pest management documentation and established organic certification pipelines. The signal to watch is EPA pesticide tolerance revision timing, which would accelerate consolidation toward compliant processors with third-party audit trails.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grower Cooperatives | Captive supply from Florida's citrus belt flattens seasonality volatility and secures year-round Brix consistency. |
| High-Pressure Processing Capacity Investment | HPP systems enable 5-log pathogen reduction without thermal degradation, preserving terpene profiles for organic clean-label claims. |
| Direct-to-Foodservice Distribution Expansion | Bulk tanker deliveries to Texas and Florida restaurant groups displace wholesale intermediaries and capture margin. |
| Organic Certification Pipeline Development | USDA traceable grower documentation commands premium shelf positioning in California specialty retail channels. |
| Proposition 65 Compliance Infrastructure | California heavy metal testing capacity exceeds federal minimums, creating regulatory moats against enforcement escalation. |
Study Parameters
Direct dialogue with citrus processors, cooperative grower representatives, beverage manufacturer procurement leads, and foodservice distribution managers grounded qualitative findings in operational reality. Secondary validation drew from FDA juice HACCP guidance documents, USDA organic certification databases, EPA pesticide tolerance registers, and California Department of Public Health enforcement records. Bottom-up volume triangulation across product type, end use, packaging format, and distribution channel segments converged with top-down market sizing.
Bottom-up modeling tracked volume absorption by application tier and certification grade across the analysis window, while top-down validation assessed aggregate citrus processing capacity and utilization rates. Segmentation dimensions included product type, end use, packaging format, and distribution channel, with geographic production cluster as an industry-specific overlay. CAGRs were derived from trend extrapolation of beverage manufacturer demand and organic certification penetration rates, calibrated against irrigation cost inflation and labor availability constraints.
The model holds under stable FDA enforcement intensity and cooperative grower network continuity; deviation in EPA pesticide tolerance timelines or California water allocation policy would shift volume trajectories. Forecasts reflect documented assumptions regarding cold-press technology adoption curves and foodservice disintermediation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Flavored Water Market