
 GCC Non-Alcoholic Beer Market | 2026-2036
GCC Non-Alcoholic Beer Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Non-Alcoholic Beer Market Intelligence
Aftermarket service revenue from keg refurbishment and draft system maintenance is reconfiguring margin pools away from pure product sales across the GCC hospitality channel. Heineken N.V. leverages its established brewing infrastructure to dominate the lager segment in Saudi Arabia. ERDINGER Weißbräu anchors its position through German purity law credentials that resonate with quality-focused consumers. Aujan Group Holding controls regional distribution networks that sustain its competitive reach into smaller retail formats.
Non-alcoholic beer denotes a fermented malt beverage containing less than 0.5% alcohol by volume, typically produced through arrested fermentation, vacuum distillation, or reverse osmosis to preserve hop aromatics while meeting halal compliance thresholds. The product serves Islamic markets where religious prohibition intersects with social drinking rituals and wellness-oriented consumption. Lager formulations occupy the dominant volume position given their lighter profile alignment with regional taste preferences and hot climate refreshment needs. Malt beverages capture expanding shelf space as hybrid products blur boundaries with traditional soft drinks. Distribution through hotels and restaurants commands premium pricing power despite retail channels moving greater absolute volume.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce halal certification and alcohol-content thresholds that determine market access eligibility across the Gulf. The UAE's National In-Country Value program and Saudi PLI scheme incentivize localized production investments that reshape supply chain economics. Stakeholders must monitor evolving fatwa interpretations from national Islamic councils that could redefine permissible thresholds or ingredient disclosures.
Market Dynamics
Halal certification mandates from Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology are compressing product development cycles while vacuum distillation investments concentrate production capability among capitalized brewers.
Growth Catalysts
- SFDA Halal Certification Pathways:Streamlined approval timelines for sub-0.5% ABV formulations accelerate product launches across Saudi retail channels.
- UAE Hospitality Procurement:Hotel and restaurant chains in Dubai and Abu Dhabi expand dedicated non-alcoholic beverage programs to capture wellness-oriented tourists.
- Vacuum Distillation Scale-Up:Capital deployment into arrested fermentation systems preserves volatile hop compounds previously lost to thermal degradation.
Market Restraints
- Barley Input Volatility:Malt supply contracts face pressure from climate-induced harvest variability in Black Sea sourcing regions.
- Equipment Supplier Concentration:German and Czech brewing system manufacturers control 80% of regional vacuum distillation hardware deployment.
- Flavor Authenticity Ceiling:Current dealcoholization methods strip ester profiles that define traditional lager sensory signatures.
Strategic Opportunities
- Kuwait Retail Underpenetration:Modern trade expansion in Kuwait City creates shelf space for premium lager formats absent from current portfolios.
- Saudi PLI Manufacturing Incentives:Production-linked incentive schemes offset capital costs for localized brewing facility construction.
- Reverse Osmosis-Hop Extract Convergence:Hybrid processing techniques enable cold separation with enhanced aromatic retention.
Industry Challenges
- Halal Auditor Certification Bottlenecks:Limited pool of SFDA-accredited auditors extends compliance timelines for new product registrations.
- Draft System Integration Complexity:Hospitality venues require reconfigured dispensing infrastructure to prevent cross-contamination with alcoholic lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Non-Alcoholic Beer Market |
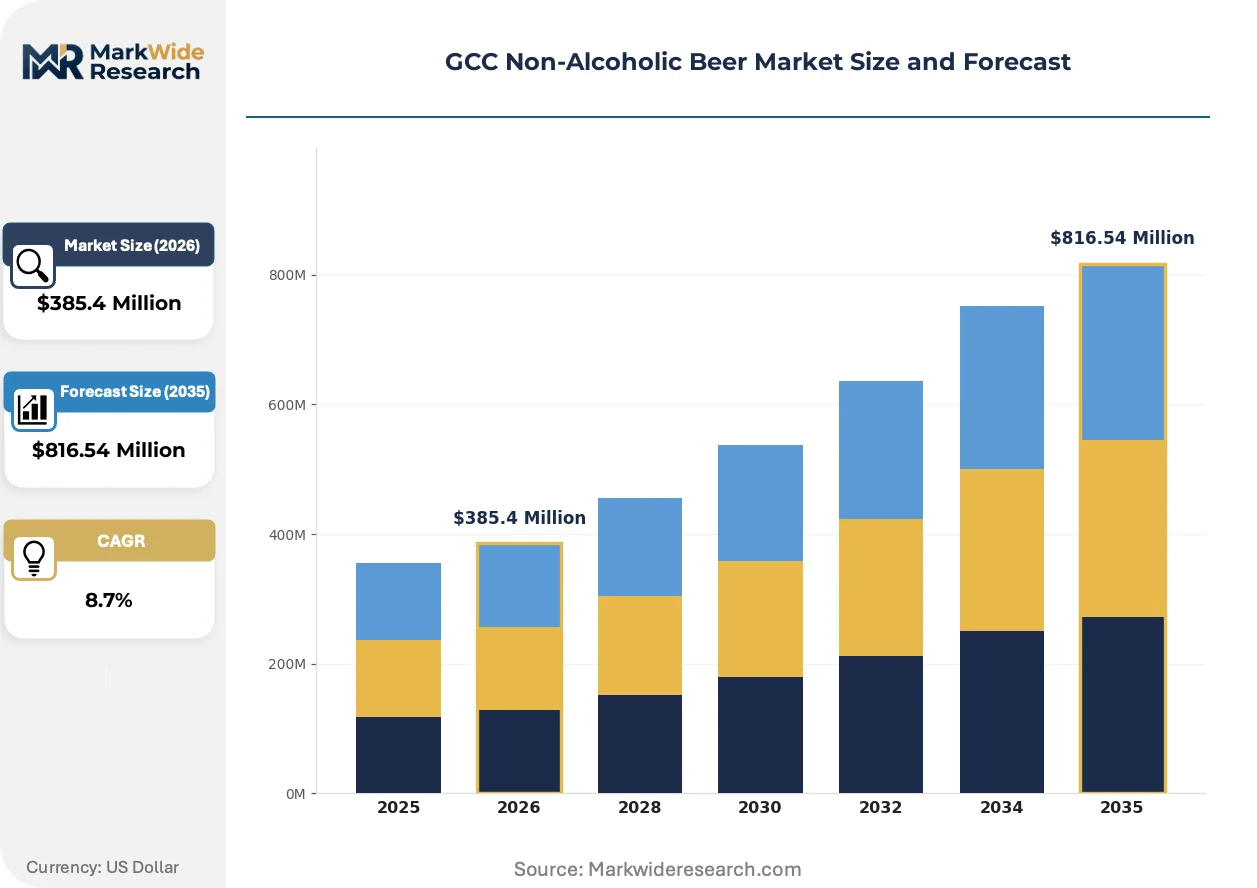
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Malt Beverage Packaging Type: Can, Bottle, Keg, Draft Distribution Channel: Retail, Online, Bars, Restaurants End User: Health-Conscious Consumers, Religious Groups, Athletes, Casual Drinkers |
| Companies Covered | Aujan Group Holding, ERDINGER Weißbräu, Anheuser-Busch InBev, Nirvana Brewery, Moussy, Heineken N.V., Clausthaler, Mahmood Saeed, Carlsberg Group, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Non-Alcoholic Beer Market Strategic Shifts & Innovations
Vacuum distillation advances and evolving fatwa interpretations are compressing traditional brewing economics while opening formulation white space previously closed to malt beverage producers.
Membrane-based dealcoholization systems are rendering obsolete thermal evaporation methods that degraded hop aromatics. Saudi brewers adopting ceramic nanofiltration modules report 40% improvement in volatile compound retention. This technology shift enables premium positioning previously unattainable for non-alcoholic lagers.
Emirates Authority for Standardization and Metrology tightened ABV measurement protocols in 2023, requiring gas chromatography verification for all halal-certified products. The mandate forced reformulation of borderline 0.3-0.5% ABV offerings. UAE hospitality distributors now demand batch-level certificates, compressing supplier qualification timelines.
Wellness-oriented consumption rituals are displacing traditional social drinking patterns among Gulf expatriate professionals. Hotel bars in Dubai International Financial Centre report 60% of after-work orders now specify zero-alcohol alternatives. This behavioral pivot concentrates volume in premium price tiers where margin structures exceed standard soft drinks by 3x.
GCC Non-Alcoholic Beer Market Segmentation
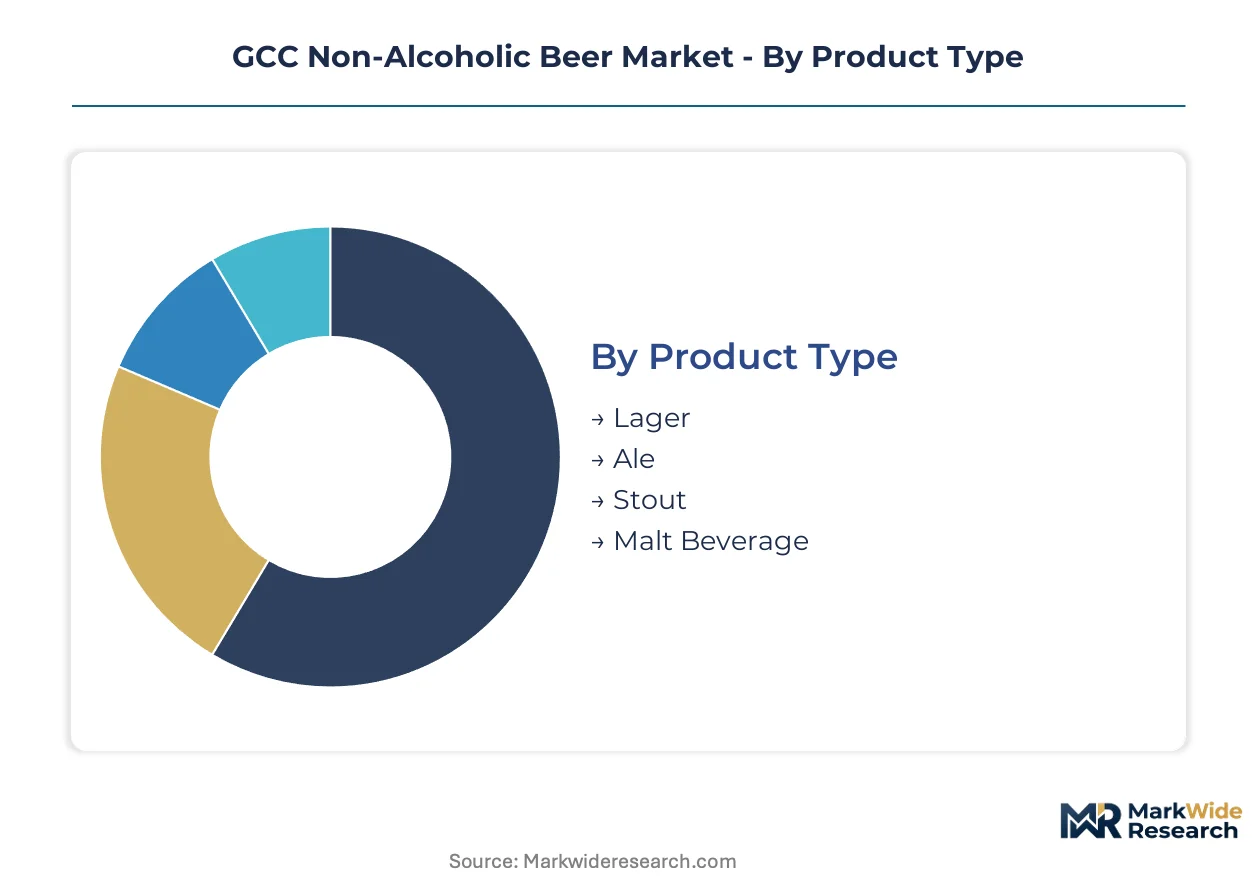
Segmentation in the GCC non-alcoholic beer market reveals how religious compliance, climate preferences, and hospitality infrastructure create distinct demand pockets. Each dimension carries regulatory and technical implications that reshape product development priorities across Saudi Arabia and the United Arab Emirates.
Product Type:
Mature lager formulations dominate volume, while emerging hybrid categories blur traditional beverage boundaries.
- Lager:Light-bodied fermented malt beverages with arrested fermentation preserving crisp hop profiles. Demand concentrates in Saudi Arabian retail channels where health-conscious consumers seek refreshment aligned with hot climate consumption patterns and halal compliance thresholds.
- Malt Beverage:Hybrid formulations incorporating fruit extracts and carbonation systems that diverge from traditional brewing methods. Shelf space expansion in UAE hypermarkets accelerates as these products attract younger demographics seeking sensory variety within permissible frameworks.
- Ale:Top-fermented varieties with fuller malt character and aromatic complexity. Niche positioning targets expatriate professionals in Dubai's hospitality venues.
- Stout:Dark roasted malt beverages with creamy texture profiles. Limited penetration reflects regional taste preferences favoring lighter refreshment categories.
Lager retains volume leadership; malt beverage holds the steepest expansion curve.
Packaging Type:
Cost tier differentiation separates premium hospitality formats from mass-market convenience channels.
- Can:Aluminum single-serve containers with barrier coatings preserving volatile aromatics. Saudi retail chains prioritize can formats for their portability and shelf stability in high-temperature distribution environments.
- Bottle:Amber and clear glass variants with crown cork or screw cap closures. UAE hotels specify premium bottle presentations for poolside and dining service occasions.
- Keg:Stainless steel returnable containers with CO2 pressurization systems. Draft program expansion in Dubai International Financial Centre venues drives refurbishment service revenue.
- Draft:Direct-draw dispensing from refrigerated cellar systems. Installation complexity limits penetration to established hospitality operators with dedicated non-alcoholic lines.
Can formats command retail volume leadership; draft systems deliver the steepest margin expansion trajectory.
Distribution Channel:
Application context determines pricing power, with on-premise hospitality commanding premium positioning over off-premise retail velocity.
- Retail:Supermarkets, hypermarkets, and convenience stores across Saudi Arabia and the UAE. Shelf space allocation intensifies as beverage category managers expand dedicated non-alcoholic sections.
- Restaurants:Full-service dining establishments with curated beverage programs. Dubai's hotel restaurant chains now mandate zero-alcohol alternatives for every menu category.
- Bars:Licensed and unlicensed hospitality venues serving after-work professionals. Wellness-oriented consumption rituals displace traditional social drinking patterns in Abu Dhabi's central business district.
- Online:E-commerce platforms and direct-to-consumer delivery services. Regulatory verification requirements for halal certification documentation complicate pure-play digital expansion.
Retail channels move absolute volume leadership; restaurant programs capture the steepest value-per-liter expansion.
End User:
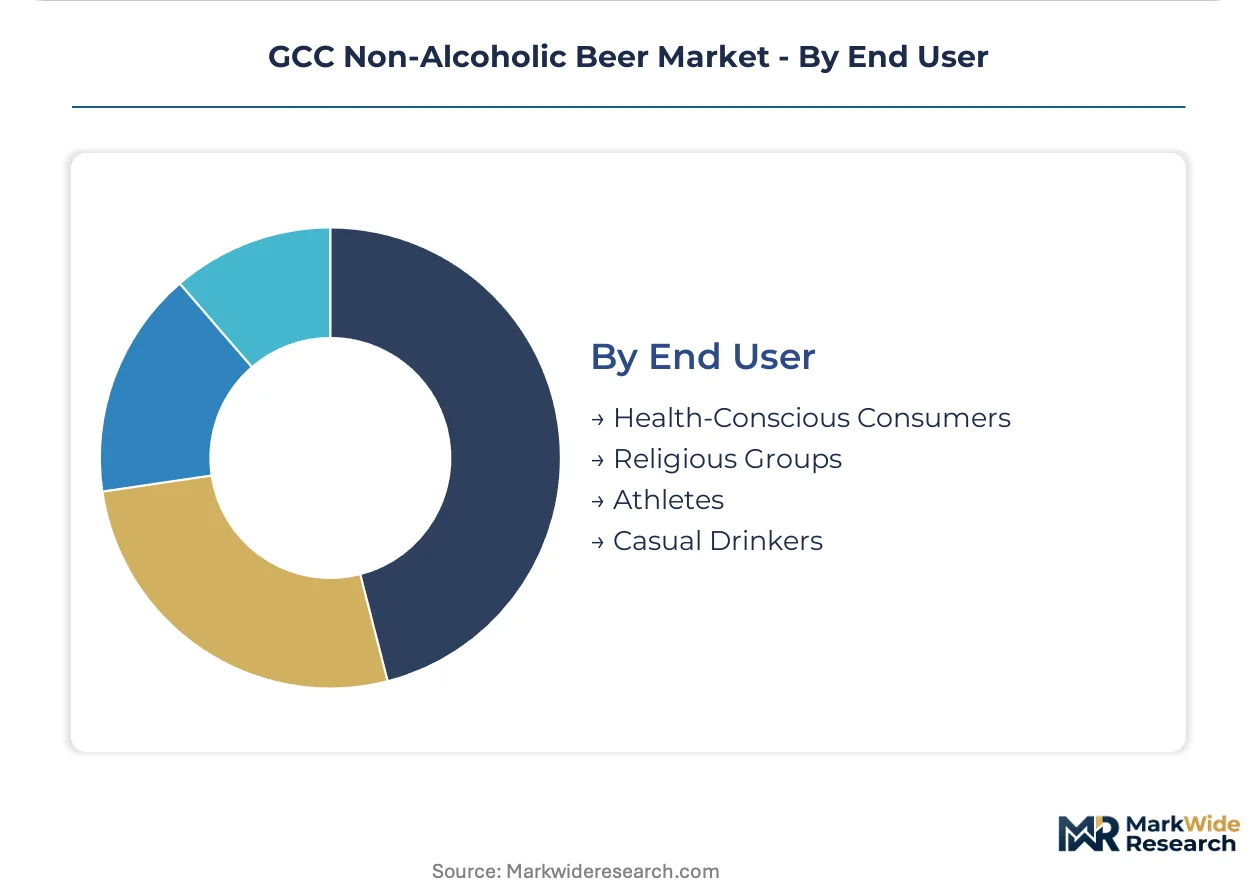
Customer type segmentation reflects the intersection of religious obligation, athletic performance optimization, and casual social ritual.
- Health-Conscious Consumers:Wellness-focused individuals prioritizing low-calorie hydration alternatives. Saudi Arabia's fitness culture expansion drives protein-aligned malt beverage experimentation.
- Religious Groups:Islamic consumers observing halal dietary restrictions as non-negotiable practice. Fatwa interpretations from national Islamic councils directly influence permissible threshold expectations.
- Athletes:Performance-oriented individuals seeking isotonic recovery properties. UAE sports clubs in Dubai and Abu Dhabi trial dedicated non-alcoholic recovery programs.
- Casual Drinkers:Social participants seeking beverage ritual without intoxication effects. Expatriate professionals in the Emirates normalize zero-alcohol ordering in professional networking contexts.
Religious groups anchor volume leadership; health-conscious consumers demonstrate the steepest adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes non-alcoholic beer primarily through retail channels for home consumption, while the UAE drives on-premise hospitality volume. This divergence shapes distribution investments and product format priorities across the Gulf.
Saudi Arabia
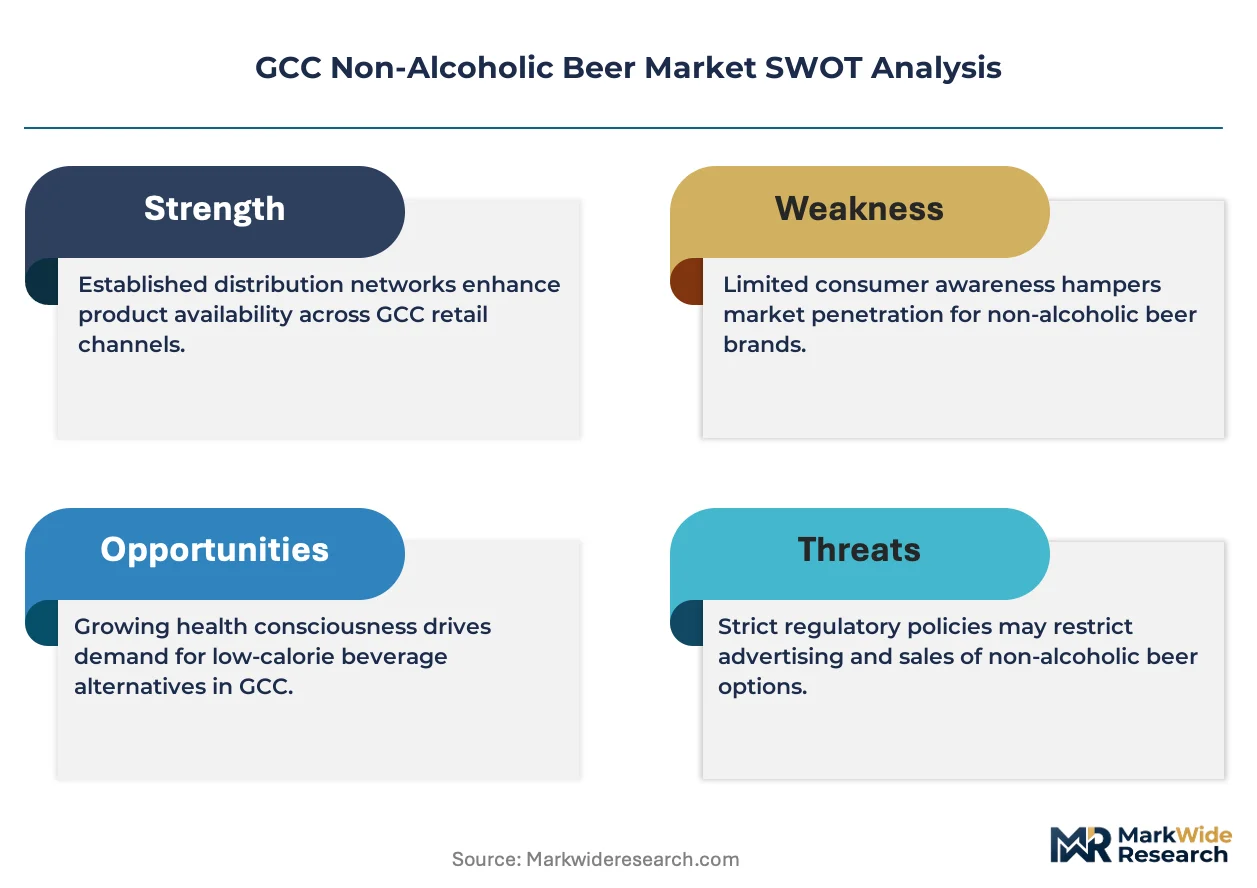
Health-conscious consumers and religious observance anchor domestic demand for sub-0.5% ABV lagers. The Saudi Food and Drug Authority enforces halal certification pathways that compress product registration timelines. Riyadh's retail chains expand dedicated non-alcoholic beverage sections to capture wellness-oriented purchasing.
United Arab Emirates
Tourism flows and expatriate professionals concentrate demand in Dubai's hotel bars and restaurants. The Emirates Authority for Standardization and Metrology mandates gas chromatography verification for all halal-certified products. Dubai International Financial Centre venues report majority zero-alcohol orders during after-work networking occasions.
Kuwait
Modern trade expansion in Kuwait City creates shelf space for premium lager formats absent from current portfolios. The country's national food safety regulator maintains strict import documentation requirements for malt beverages. Retail infrastructure investments in urban centers attract regional distributor attention.
Qatar
Hospitality procurement for sporting and cultural events drives concentrated demand spikes in Doha. The Qatar General Organization for Standardization oversees halal compliance verification for all fermented malt imports. Lusail's entertainment district venues specify dedicated non-alcoholic draft programs.
Bahrain
Cross-border shopping patterns and expatriate communities sustain steady retail velocity in Manama. The national standards body aligns halal certification requirements with GCC harmonization frameworks. Northern Governorate hypermarkets trial expanded malt beverage assortments targeting younger demographics.
GCC Non-Alcoholic Beer Market Key Industry Players
Capability concentration sits with specialized brewers possessing vacuum distillation expertise; scale advantage sits with multinational beverage conglomerates leveraging established distribution infrastructure. The market structure shows tiered consolidation with premium positioning held by heritage European brands and volume leadership contested by global brewing networks. Two strategic archetypes dominate: German purity-law credential holders and Gulf-based distribution network controllers. Competitive moves center on localized production investments under Saudi PLI schemes and hospitality channel draft system integration.
Within the heritage brewing tier, ERDINGER Weißbräu represents German purity law credentials that resonate with quality-focused consumers. Heineken N.V. occupies a position exemplifying multinational scale deployment across Saudi retail channels. Aujan Group Holding anchors the regional distribution archetype, controlling networks that sustain competitive reach into smaller retail formats across the Gulf.
| Leading Market Players |
|---|
| Aujan Group Holding |
| ERDINGER Weißbräu |
| Anheuser-Busch InBev |
| Nirvana Brewery |
| Moussy |
| Heineken N.V. |
| Clausthaler |
| Mahmood Saeed |
| Carlsberg Group |
| Others |
Cost & Logistics Intelligence
Barley input volatility from Black Sea sourcing regions compresses margin pools across premium and economy tiers while forcing brewers toward long-term malt supply contracts that reshape working capital requirements. This commodity exposure simultaneously widens price spreads between heritage-positioned lagers and private-label alternatives and concentrates supply chain investments in climate-resilient sourcing corridors.
Pricing Analysis
Long-term offtake agreements for malted barley anchor cost predictability for Saudi and UAE brewers, though spot market exposure persists for smaller regional entrants. Three-tier pricing structure across premium, standard, and economy levels separates German purity-law credentialed imports from locally produced lagers and private-label alternatives. Pricing pressure stems from vacuum distillation equipment supplier concentration among German and Czech manufacturers, which inflates capital recovery premiums. Retail channels in Saudi Arabia exhibit highest price sensitivity; Dubai hospitality venues demonstrate lowest sensitivity due to wellness-positioned menu pricing.
Supply Chain Analysis
Contract manufacturing concentration for vacuum distillation systems sits with German and Czech brewing equipment specialists controlling regional hardware deployment. Malted barley draws primarily from Black Sea regions, Germany, and France; hop extracts source from Germany and the Czech Republic; aluminum can stock feeds from Gulf-based rolling mills. Single-source vulnerability in ceramic nanofiltration module supply creates chokepoint exposure for Saudi brewers scaling arrested fermentation capacity. Distribution runs through Aujan Group Holding's regional networks into Saudi retail chains and UAE hospitality procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC non-alcoholic beer market sits at an early-cycle recovery phase driven by tourism normalization and expatriate workforce expansion across the Emirates. Halal certification pathway streamlining and wellness consumption ritual adoption provide cyclical momentum that favors positioned incumbents over speculative entrants.
For Market Incumbents: Harden halal certification moats through SFDA auditor relationship investments that extend compliance timelines for challengers. Deepen backward integration into localized brewing capacity under Saudi PLI schemes to offset equipment supplier concentration premiums. Lock long-term malt offtake contracts before Black Sea harvest variability intensifies cost compression in economy tiers. For New Entrants and Emerging Players: Establish a beachhead in Kuwait City modern trade expansion where premium lager shelf space remains underallocated relative to regional distributor attention. Target malt beverage hybrid formats with fruit extract positioning that attracts younger demographics seeking sensory variety within halal frameworks. Pursue co-manufacturing partnerships with Saudi-based arrested fermentation facilities to bypass capital-intensive vacuum distillation equipment procurement. For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors regional distribution network controllers over pure-brand licensors. Long-term viability hinges on localized production economics overcoming import-dependent margin structures. Acquisition target archetype: Gulf-based distributors with SFDA certification expertise and draft system service capabilities. Monitor quarterly halal auditor pool expansion rates as inflection indicator for new entrant qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Brewing Facility Construction | Saudi PLI incentives offset German equipment supplier premiums for arrested fermentation scale-up. |
| Halal Certification Pathway Investment | SFDA auditor relationship depth determines product launch velocity against compliance bottlenecks. |
| Draft System Service Expansion | Keg refurbishment and line maintenance revenue reconfigures margin pools beyond pure product sales. |
| Malt Beverage Hybrid Development | Fruit extract formulations capture UAE hypermarket shelf space from younger demographic trial. |
| Vacuum Distillation Technology Licensing | Ceramic nanofiltration module adoption preserves volatile hop compounds for premium positioning. |
Research Approach
The analysis maps lager, malt beverage, ale, and stout sub-sectors, each validated through brewing technology directors, hospitality procurement managers, retail category buyers, and halal certification consultants. Primary interview intelligence triangulates against SFDA regulatory filings, Emirates Authority for Standardization and Metrology protocols, GCC customs trade records, and hospitality industry procurement databases. Bottom-up volume builds from SKU-level retail audit data and top-down demand validation from tourism flow projections reconcile through iterative stakeholder cross-checking.
Assumption sets held halal certification threshold interpretations and fatwa council guidance constant while varying tourism recovery trajectories, expatriate workforce growth, and barley harvest yield scenarios across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user archetype. CAGRs derive from logarithmic trend fitting against normalized historical volume baselines, with vacuum distillation technology adoption curves and wellness consumption behavioral shifts as key forecast inputs.
Stress conditions across Black Sea barley supply disruption, SFDA auditor capacity constraints, and UAE hospitality procurement cycle volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification pathway timelines and equipment supplier pricing stability. Quarterly review of halal auditor pool expansion rates, Saudi PLI scheme participation levels, and Dubai International Financial Centre zero-alcohol order penetration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
India Energy Drinks Market