
 North America Soy Beverages Market | 2026-2036
North America Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soy Beverages Market Analytics
Multi-source procurement of organic soybeans is consolidating as processors seek supply security amid volatile commodity markets. Danone leverages its integrated North American dairy-alternative infrastructure to secure consistent non-GMO bean flows. SunOpta anchors its position through specialized organic processing facilities in the Upper Midwest. Pacific Foods of Oregon competes on regional sourcing relationships with Willamette Valley growers.
Soy beverages are aqueous extracts of whole soybeans or soy protein isolates, typically homogenized and heat-treated to achieve colloidal stability and a protein content of 2.5–4.0 grams per 100 milliliters, serving as functional dairy alternatives in retail and foodservice channels. Flavored variants command widening shelf space as younger demographics reject unpalatable legacy formulations, while fortified lines with added calcium and vitamin D capture margin pools from aging consumers seeking nutritional parity with dairy. Organic certification within product type segmentation extracts price premiums that standard offerings cannot match, though supply constraints limit volume scalability.
The U.S. FDA oversees labeling standards for plant-based milk alternatives, while USDA Organic certification governs ingredient integrity and processing claims across the value chain. Canada's CFIA enforces bilingual labeling and compositional standards that create incremental compliance burdens for cross-border suppliers. Stakeholders must monitor evolving protein content thresholds and allergen disclosure requirements that could reshape formulation economics and regional manufacturing footprints.
Market Dynamics
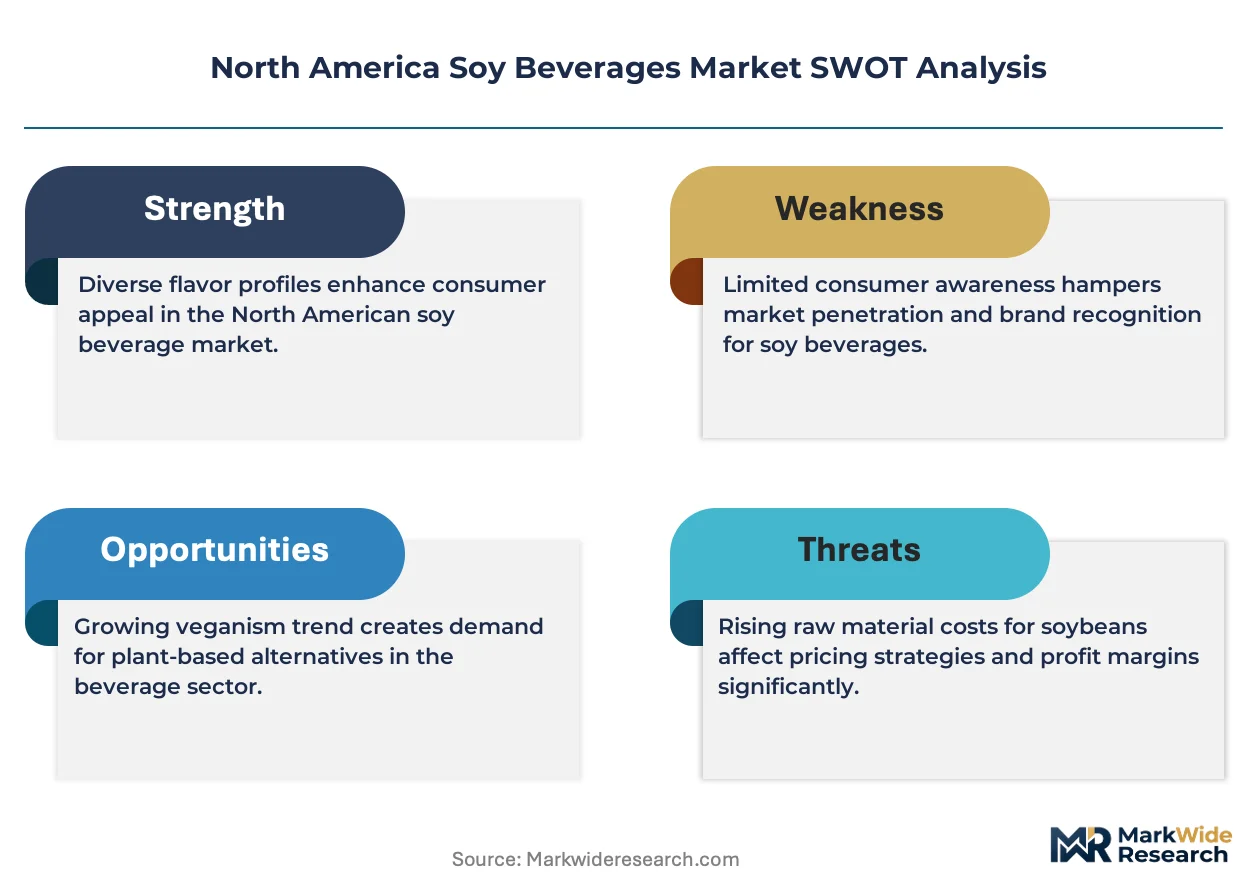
The U.S. FDA's updated plant-based milk labeling guidelines are forcing processors to reformulate protein fortification levels and allergen disclosure formats, compressing margins while creating compliance-driven competitive separation between integrated and commodity-dependent suppliers.
Growth Catalysts
- Protein Fortification Mandates:The FDA's revised compositional standards for dairy alternatives are pushing processors to elevate protein density in soy beverages, creating technical differentiation that rewards R&D-capable manufacturers.
- Café Channel Expansion:Foodservice operators across the United States and Canada are multiplying plant-based menu options, embedding soy milk as a default offering rather than specialty upcharge.
- Organic Retail Density:California and Pacific Northwest grocery networks maintain the highest concentration of certified organic shelf space, concentrating demand pull in these coastal markets.
Market Restraints
- Input Cost Volatility:Organic soybean prices fluctuate with Midwest growing conditions and export demand from Asian processors, squeezing margin stability for non-integrated brands.
- Supply Concentration Risk:The Upper Midwest dominates domestic organic soybean processing infrastructure, creating geographic vulnerability to weather disruptions and logistics bottlenecks.
- Technical Limitation:Beany off-flavor compounds in conventional soy protein isolates persist as a sensory barrier, limiting penetration in taste-sensitive pediatric and senior segments.
Strategic Opportunities
- Underpenetrated Geography:The U.S. Southeast and Mountain West show lower per-capita soy beverage consumption than coastal markets, offering expansion headroom for targeted distribution investments.
- Regulatory Tailwind:Canada's CFIA bilingual labeling requirements create incremental compliance burdens that favor established cross-border suppliers with dedicated Canadian packaging lines.
- Technology Convergence:Precision fermentation and enzymatic debittering are converging to reduce flavor masking additive loads, enabling cleaner-label positioning in premium tiers.
Industry Challenges
- Certification Timeline Compression:USDA Organic and Non-GMO Project verification cycles are lengthening due to inspector backlogs, delaying new product launches and reformulation rollouts.
- Talent Scarcity:Food scientists with dual expertise in plant protein chemistry and dairy-alternative processing command premium compensation, constraining mid-tier processor R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soy Beverages Market |
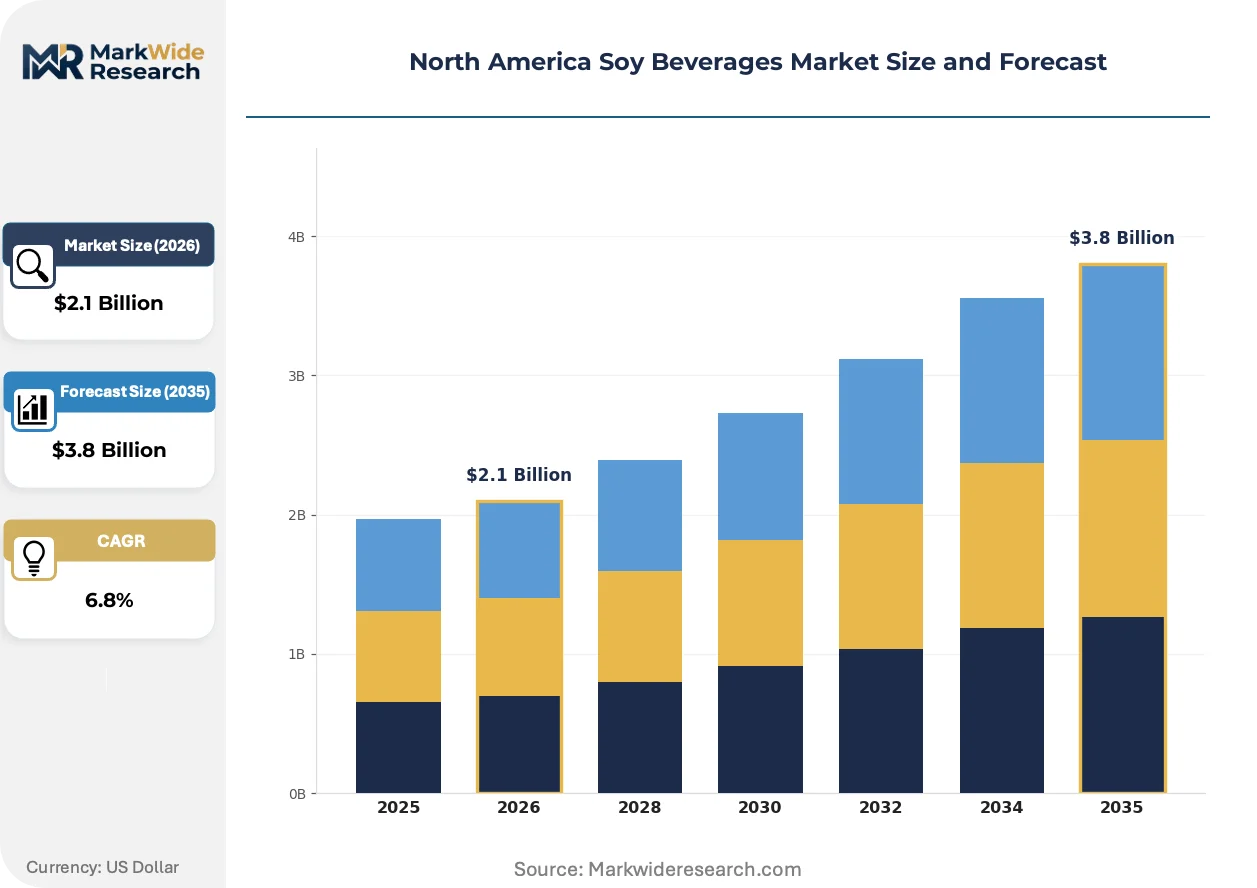
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Organic, Fortified End User: Households, Restaurants, Cafes, Retailers Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores Packaging Type: Bottles, Cartons, Tetra Packs, Cans |
| Companies Covered | Danone, The Hain Celestial Group, Kikkoman, Organic Valley, Eden Foods, Trader Joe's, SunOpta, Pacific Foods of Oregon, Earth’s Own Food Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soy Beverages Market Evolving Landscape
Reformulation investments are accelerating across the North American value chain as processors respond to labeling clarity mandates and sensory quality expectations from younger demographics rejecting legacy formulations.
Enzymatic debittering technology is overtaking traditional masking approaches in premium soy beverage production. The process uses targeted lipoxygenase inhibition to reduce hexanal and pentanal off-flavor precursors without heavy sugar or flavor additive loads. West Coast organic processors are adopting this at pilot scale, enabling cleaner-label products that command shelf space in Whole Foods and regional co-op networks. This technical shift is compressing the viable market position of legacy brands dependent on vanilla and chocolate masking.
The FDA's draft guidance on nutrient content claims for plant-based milk alternatives is reshaping fortification strategies. Processors must now meet minimum protein, calcium, and vitamin D thresholds to use "milk" terminology, forcing reformulation investments or label downgrades. Fortified lines targeting aging consumers seeking nutritional parity with dairy face the highest compliance burden, with some brands pivoting to "beverage" positioning to avoid nutrient density thresholds.
Younger demographics are rejecting unpalatable legacy soy formulations and driving flavor innovation across the category. Strawberry, matcha, and turmeric-ginger variants are displacing plain and original offerings in urban retail clusters. This preference shift is most visible in Los Angeles, Portland, and Toronto café channels, where barista-specific foaming formulations now outpace standard retail SKUs in volume velocity.
North America Soy Beverages Market Segmentation
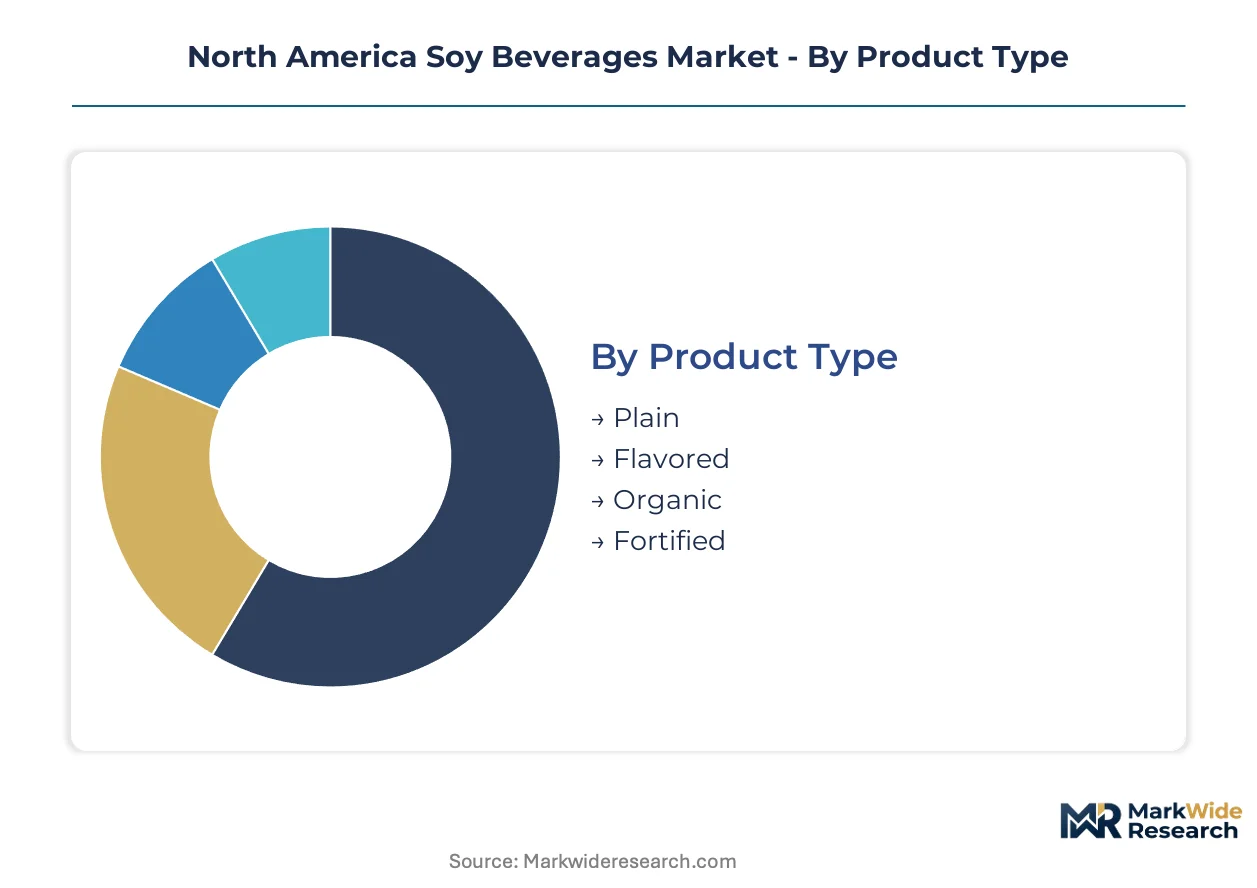
Soy beverage processors configure product portfolios around four intersecting dimensions that determine margin capture and channel access. Reformulation cycles and packaging upgrades now dominate capital allocation decisions as FDA labeling clarity mandates reshape competitive positioning.
Product Type:
Upgrade cycles in this category center on protein fortification investments and organic certification transitions that command shelf space premiums.
- Plain:Unflavored formulations with 2.5–3.5 grams protein per 100 milliliters serve cost-conscious bulk purchasers and foodservice operators seeking neutral blending bases. Pacific Northwest café chains specify plain variants for barista-customized beverages, though volume growth lags as younger consumers reject unpalatable legacy tastes.
- Flavored:Strawberry, matcha, and turmeric-ginger variants displace original formulations in Los Angeles, Portland, and Toronto urban retail clusters. These SKUs capture velocity advantages in Whole Foods and regional co-op networks where sensory innovation determines repeat purchase rates.
- Organic:USDA-certified offerings extract price premiums that standard formulations cannot match, though Upper Midwest supply constraints limit volume scalability for non-integrated processors.
- Fortified:Calcium and vitamin D enrichment targets aging consumers seeking nutritional parity with dairy, facing the highest FDA compliance burden for "milk" terminology usage.
Plain formulations sit at the top of the volume ranking, with flavored variants climbing the fastest.
End User:
Cost tier differentiation separates institutional procurement from premium retail positioning across the value chain.
- Households:California and Pacific Northwest grocery networks concentrate demand for certified organic SKUs, with per-capita consumption running above national averages.
- Restaurants:Multi-unit operators specify barista-grade foaming formulations for latte and cappuccino applications, embedding soy milk as default rather than specialty upcharge.
- Cafes:Independent and chain coffee shops across the United States and Canada drive velocity for chilled single-serve formats, with Toronto and Vancouver showing particular density.
- Retailers:Private label development accelerates as supermarket chains seek margin protection against branded price volatility.
Households dominate absolute volume, with cafes expanding most quickly.
Distribution Channel:
Channel economics favor high-velocity formats that minimize spoilage risk in temperature-sensitive soy protein formulations.
- Online:Direct-to-subscription models capture recurring revenue from organic-focused consumers, though shipping costs compress margins on shelf-stable cartons.
- Supermarkets:Mass retail placement in California and the Pacific Northwest determines brand visibility, with refrigerated section expansion outpacing ambient shelf growth.
- Specialty Stores:Regional co-ops and natural food retailers enforce stringent ingredient transparency standards that filter out commodity-dependent suppliers.
- Convenience Stores:Single-serve chilled bottles target grab-and-go consumption in urban corridors, with placement concentrated in West Coast metropolitan areas.
Supermarkets anchor volume distribution, with specialty stores gaining share fastest.
Packaging Type:
Supply concentration in aseptic carton manufacturing shapes procurement strategies for mid-tier processors.
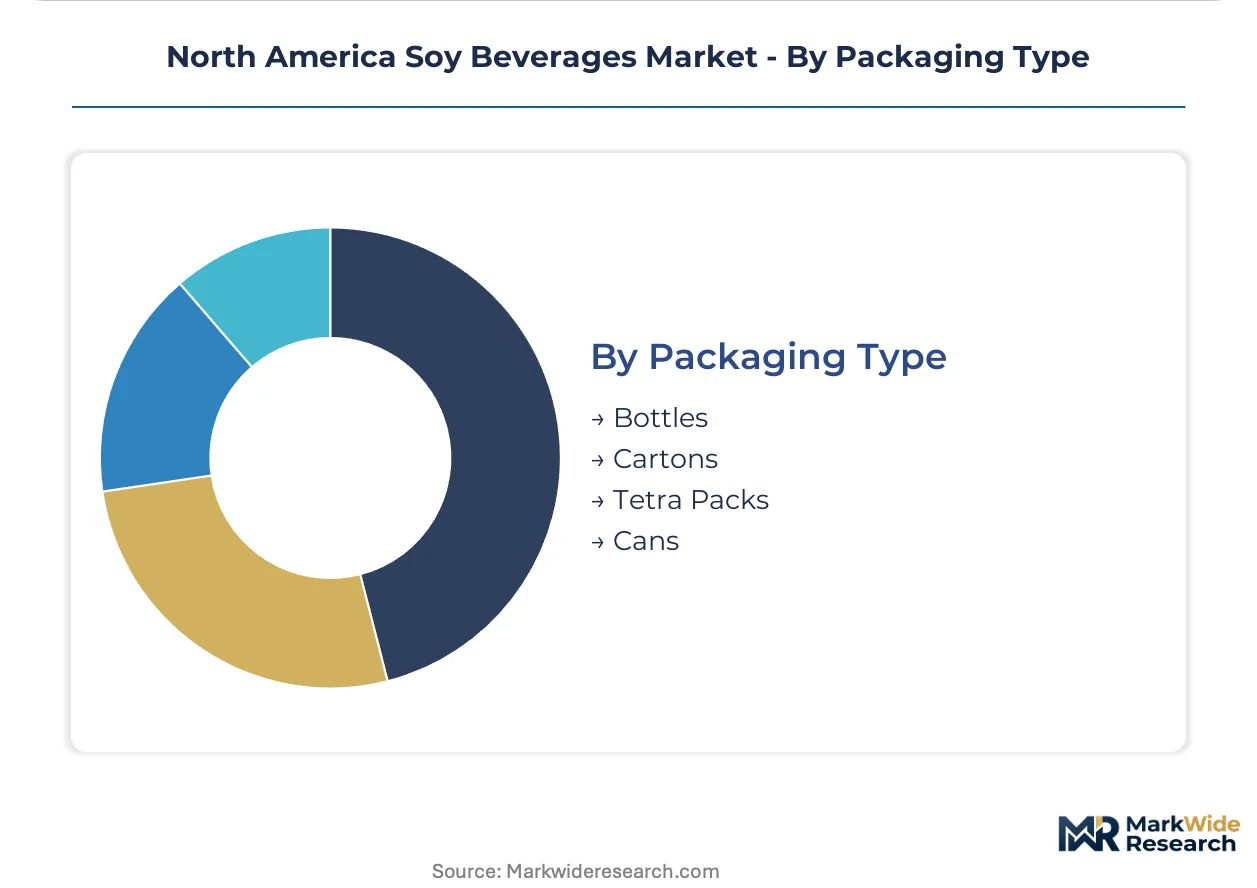
- Bottles:PET and HDPE formats dominate foodservice fountain and refrigerated retail applications, offering resealability for multi-serve household consumption.
- Cartons:Gable-top refrigerated cartons capture mainstream supermarket placement, with Midwest dairy-alternative processing infrastructure supporting regional distribution efficiency.
- Tetra Packs:Aseptic brick formats enable ambient distribution to Southeast and Mountain West markets lacking cold chain density.
- Cans:Aluminum formats serve niche ready-to-drink and bar-mix applications, with limited penetration outside specialty beverage channels.
Cartons lead volume ranking, with Tetra Packs climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Northwest organic retail corridor anchors North American soy beverage demand, with California and coastal urban clusters driving per-capita consumption premiums that exceed national benchmarks by considerable margins.
United States
California health-conscious consumer clusters and Pacific Northwest organic grocery density concentrate demand pull for certified organic SKUs. The FDA's updated plant-based milk labeling guidelines are forcing reformulation investments across domestic processors. Los Angeles and Portland café channels embed soy milk as default offerings, displacing specialty upcharges in latte and cappuccino applications.
Canada
Toronto and Vancouver metropolitan areas show particular density for chilled single-serve soy beverage velocity in independent coffee shops. The CFIA enforces bilingual labeling and compositional standards that create incremental compliance burdens favoring established cross-border suppliers with dedicated Canadian packaging infrastructure. Quebec and Ontario retail networks drive private label development as supermarket chains seek margin protection against branded price volatility.
Mexico
Mexico City Metro and Guadalajara urban corridors represent emerging demand frontiers with lower per-capita penetration than U.S. coastal markets. The country's national food safety regulator maintains evolving standards for plant-based dairy alternatives that processors monitor for future alignment investments. Northern border states show cross-border retail influence from U.S. organic certification requirements, creating early-adopter consumer pockets.
U.S. Southeast
Florida and Georgia metropolitan areas demonstrate underpenetrated consumption relative to coastal benchmarks, offering expansion headroom for targeted distribution investments. Regional supermarket chains are expanding refrigerated section placement for plant-based alternatives, though organic certification density lags Pacific Northwest standards. Atlanta and Miami foodservice operators are piloting soy milk default positioning in multi-unit café concepts.
U.S. Mountain West
Colorado Front Range and Arizona Sun Corridor urban clusters show intermediate per-capita consumption between coastal leaders and Southeast laggards. Cold chain infrastructure gaps in intermountain regions favor ambient Tetra Pack distribution over refrigerated carton formats. Denver and Phoenix specialty retailers are enforcing ingredient transparency standards that filter commodity-dependent suppliers from premium shelf placement.
North America Soy Beverages Market Competitive Landscape
Global majors compete with regional champions across procurement infrastructure and café channel access, producing a tiered structure where integrated processors command supply security premiums over commodity-dependent brands. The vendor base separates into three strategic archetypes: multinational dairy-alternative conglomerates with captive organic soybean flows, specialized organic processors with regional sourcing relationships, and private label contractors serving retail chain margin protection strategies. Dominant competitive moves include backward integration into Upper Midwest organic processing infrastructure and technology licensing for enzymatic debittering capabilities.
Among North American integrated processors, Danone and SunOpta exemplify contrasting approaches to supply security—Danone through multinational dairy-alternative infrastructure and SunOpta through specialized organic processing facilities. Pacific Foods of Oregon occupies a position within the regional sourcing archetype, anchoring Willamette Valley grower relationships that support coastal market penetration. These three entities represent the competitive spectrum from global scale to regional specialization without overlapping strategic positioning.
| Leading Market Players |
|---|
| Danone |
| The Hain Celestial Group |
| Kikkoman |
| Organic Valley |
| Eden Foods |
| Trader Joe's |
| SunOpta |
| Pacific Foods of Oregon |
| Earth’s Own Food Company |
| Others |
Value Network & Pricing Analysis
Family-owned organic processors in the Upper Midwest anchor supply discipline through multi-generational grower contracts that buffer spot-market volatility and sustain premium pricing tiers for certified non-GMO soybeans. This ownership pattern concentrates procurement leverage among integrated players while commodity-dependent brands absorb margin compression from organic soybean price swings.
Pricing Analysis
Organic soybean cost pass-through operates on 6-12 month lags, creating margin squeeze for non-integrated processors when Midwest growing conditions tighten supply. Pricing stratifies across USDA Organic certified, Non-GMO Project verified, and conventional tiers, with certification premiums widening during supply shortages. Cost compression in the conventional tier is intensifying because private-label entrants are undercutting branded shelf prices. Foodservice operators show lowest price sensitivity due to menu-margin absorption, while mass-market retailers negotiate hardest on case-rate discounts.
Supply Chain Analysis
Organic soybean supply rests on Upper Midwest processing infrastructure concentrated in Minnesota, Iowa, and Wisconsin, with secondary sourcing from Ontario's expanding organic acreage. Critical inputs include identity-preserved non-GMO seed stock, specialized aseptic packaging substrates, and enzymatic debittering cultures. Single-source vulnerability runs through the Upper Midwest organic crush capacity, where weather disruptions or logistics bottlenecks cascade through national availability. Distribution runs through temperature-controlled networks serving coastal metropolitan clusters, with ambient Tetra Pack formats penetrating cold-chain-deficient interior markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America soy beverages market functions as a regulatory compounder where FDA protein fortification mandates are accelerating R&D spend and consolidating competitive position among compliance-capable processors.
For Market Incumbents: Extend backward integration into Willamette Valley and Upper Midwest organic soybean acreage to secure identity-preserved supply streams against commodity price volatility. Deepen barista-grade formulation capabilities to defend café channel positioning against oat and pea protein substitutes encroaching on foodservice default status. Prioritize enzymatic debittering technology licensing to maintain cleaner-label differentiation as flavor-masking additive loads face regulatory scrutiny. For New Entrants and Emerging Players: Capture underpenetrated geography in the U.S. Southeast and Mountain West where per-capita consumption lags coastal benchmarks by substantial margins. Target Atlanta and Miami foodservice pilots embedding soy milk as default offerings in multi-unit café concepts. Lead with direct-to-subscription models capturing recurring organic-focused household revenue before attempting mass retail shelf placement. For Investors and Strategic Acquirers: Multinational dairy-alternative conglomerates are the most active acquirers in this space, seeking captive organic supply and coastal brand equity. The 5-10 year viability window favors processors with demonstrated FDA compliance track records and established Canadian CFIA bilingual packaging infrastructure. Watch for USDA Organic certification timeline compression as inspector backlogs create supply-constrained pricing power for verified incumbent processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Soybean Supply | Captive Upper Midwest acreage insulates margin stability from commodity volatility and export demand competition. |
| Enzymatic Debittering Technology Licensing | Cleaner-label positioning captures Whole Foods and regional co-op shelf space from legacy flavor-masked formulations. |
| CFIA-Compliant Canadian Packaging Infrastructure | Dedicated bilingual lines create compliance moats favoring established cross-border suppliers over U.S.-only entrants. |
| Barista-Grade Foaming Formulation Development | Café channel default positioning displaces specialty upcharges in Los Angeles and Portland latte applications. |
| Direct-to-Subscription Channel Launch | Recurring revenue models bypass mass retail slotting fees and capture organic-focused household lifetime value. |
Research Methodology
Bottom-up foodservice and retail channel modeling reconciled against top-down organic soybean supply tracking forms the analytical core of this study. Primary interviews with soy beverage processors, category buyers at natural food retailers, foodservice procurement directors, and organic certification auditors combined with secondary validation from FDA guidance documents, USDA Organic integrity database records, CFIA labeling standards, and Nielsen retail audit data. Triangulation across these sources ensures volume estimates reflect actual shelf placement rather than shipment disclosures alone.
Input-output matrices map organic soybean crush capacity through aseptic processing infrastructure to downstream channel placement across the projection horizon. Segmentation dimensions include product type, end-user archetype, distribution channel, and packaging format, with regional regulatory clusters capturing FDA and CFIA compliance burden differentials. CAGRs derive from modeled protein fortification investment cycles and café channel penetration curves, with enzymatic debittering adoption rates and organic certification inspector capacity serving as industry-specific forecast inputs.
Regulatory guidance revisions, organic commodity price shocks, and substitute protein technology breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding FDA labeling clarity finalization timelines and Upper Midwest organic acreage expansion trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market