
 Coffee Substitute Market | 2026-2036
Coffee Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Substitute Market Analysis
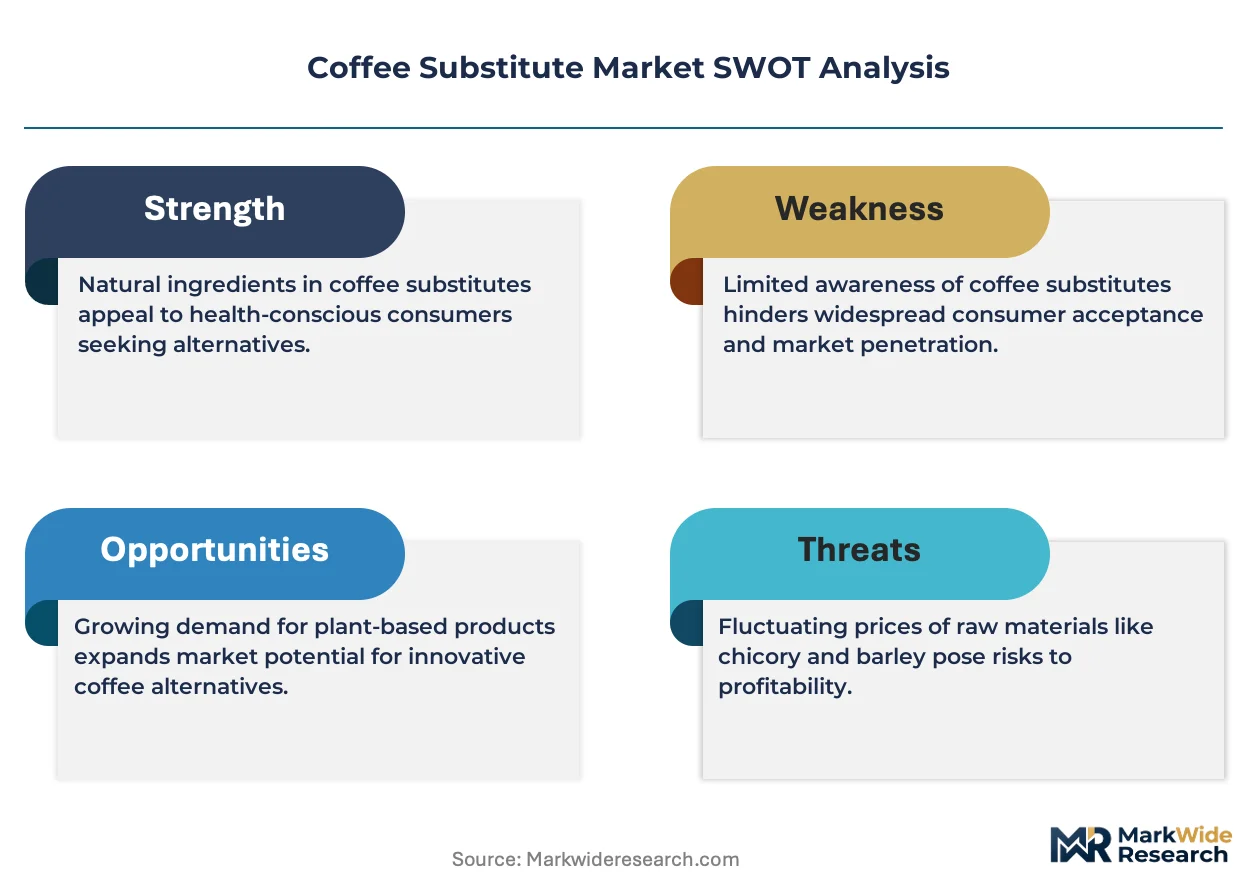
Chicory root is broadening its role as the foundational roasted material in caffeine-free formulations, displacing higher-cost arabica alternatives in price-sensitive channels. Teeccino Caffe leverages its herbal roasting expertise to dominate the North American natural-foods shelf. Nestlé S.A. sustains mass-market penetration through its instant grain-beverage portfolio in European supermarkets. Four Sigmatic differentiates by occupying the functional-mushroom positioning tier, commanding premium placement in wellness-oriented retail.
Coffee substitutes comprise roasted, ground, and brewed plant materials formulated to replicate the sensory experience of coffee without caffeine content, typically processed through drum-roasting at 180–220°C followed by extraction or instant-drying. The primary commercial purpose is serving consumers with caffeine intolerance, pregnancy-related dietary restrictions, or evening consumption routines that exclude stimulants. Cereal-based and chicory segments lead volume due to established supply chains and flavor familiarity, while mushroom-based formulations represent the fastest-growing margin pool as adaptogenic claims attract premium buyers. Powder and liquid forms capture divergent use-cases, with powder dominating at-home preparation and liquid concentrates gaining traction in foodservice dispensing systems.
Regulatory frameworks including EFSA food-labeling standards, FDA GRAS determinations for novel botanical ingredients, and EU Organic Regulation 2018/848 shape product composition claims and cross-border market access for substitute manufacturers. These bodies enforce strict boundaries on caffeine-free assertions and organic certification, directly influencing formulation investments and label compliance costs. Stakeholders must monitor evolving novel-food approvals for emerging mushroom extracts, as regulatory clearance timelines will determine which entrants can scale beyond niche positioning.
Market Dynamics
The EU Green Deal's agricultural sustainability requirements are compressing conventional supply chains and forcing roasters toward certified organic chicory sourcing, reshaping procurement relationships across European markets.
Growth Catalysts
- EU Green Deal agricultural mandates:Sustainability certification requirements are accelerating organic chicory acreage expansion across France and Belgium. Roasters secure long-term supply contracts to meet compliance deadlines.
- Caffeine sensitivity prevalence:Rising consumer intolerance to stimulants is expanding the addressable base for grain-based and botanical formulations in evening consumption occasions.
- Drum-roasting equipment modernization:Automated temperature control systems at 180–220°C ranges are improving batch consistency and reducing flavor variability in commercial production.
Market Restraints
- Chicory root supply concentration:Northern France and Belgium dominate raw material cultivation, creating geographic vulnerability to weather shocks and crop disease.
- Arabica price volatility spillover:Coffee commodity fluctuations distort substitute pricing power as consumers benchmark against conventional coffee value perceptions.
- EFSA novel-food approval timelines:Emerging mushroom extract formulations face 18–24 month regulatory clearance periods that delay commercial scaling beyond niche positioning.
Strategic Opportunities
- German specialty cafe channel expansion:Independent beverage retailers in Berlin and Munich are adding dedicated grain-drink menu sections, creating premium placement opportunities.
- Foodservice liquid concentrate dispensing:Automated brewing systems in workplace and hospitality settings are adopting ready-to-dispense formats for operational efficiency.
- EU Organic Regulation 2018/848 certification:Harmonized standards across member states reduce cross-border compliance fragmentation for multi-national brand expansion.
Industry Challenges
- Herbal roasting expertise scarcity:Formulation chemists with dual competency in botanical extraction and sensory profiling command premium compensation, constraining R&D team scaling.
- Adaptogenic claim substantiation:EFSA health claim rejections for functional mushroom benefits require costly clinical trial investments to support marketing assertions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Substitute Market |
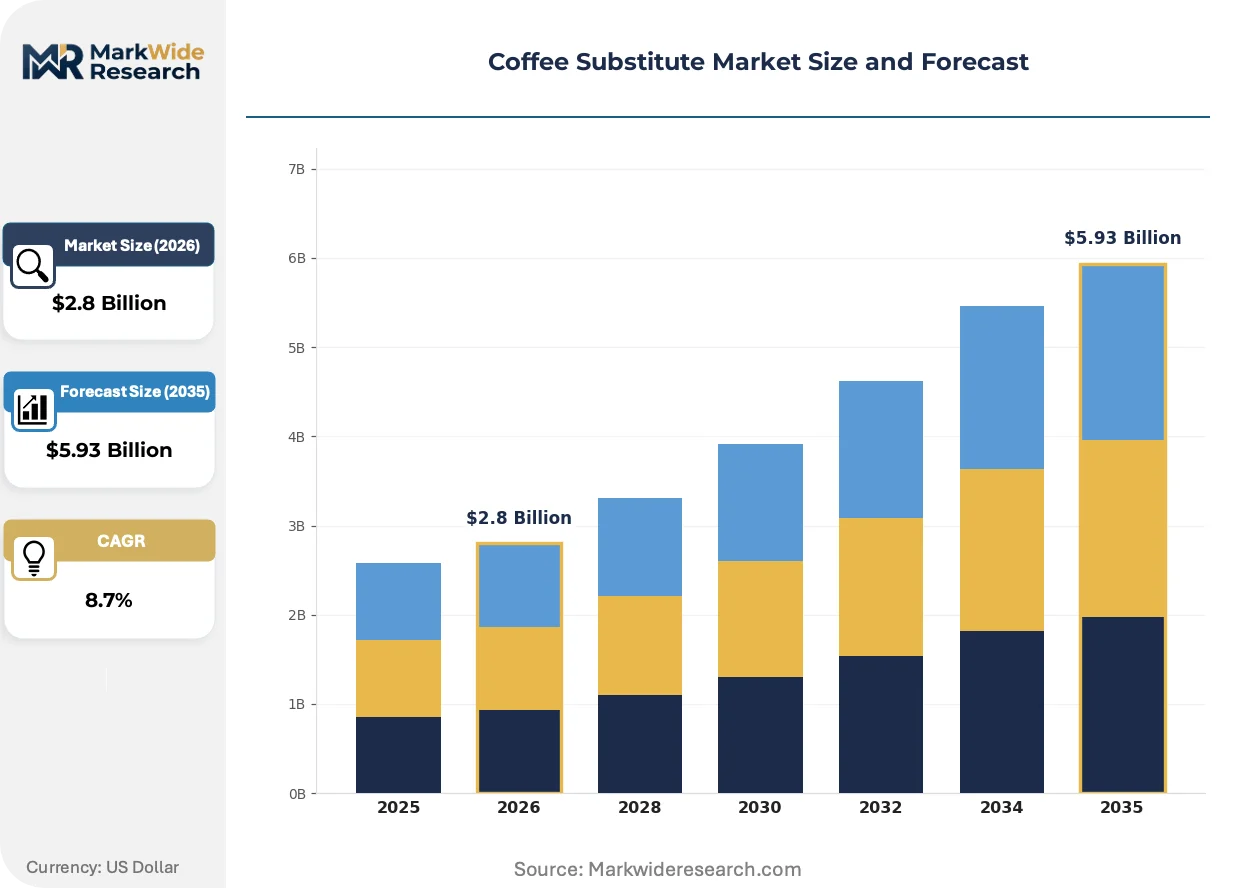
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal-Based, Chicory, Herbal, Mushroom Form: Powder, Liquid, Granules, Capsules Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Customer Type: Health Conscious, Environmentally Friendly, Vegan, Organic Enthusiasts |
| Companies Covered | Barleycup International Limited, Inka Food Sp. z o.o., Nestlé S.A., Teeccino Caffe, Post Consumer Brands, LLC, Kraft Heinz Company, Dandy Blend Limited, Four Sigmatic, The Roasted Grain Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Substitute Market Emerging Trajectories
Formulation science and regulatory harmonization are compressing development cycles while demand fragmentation across wellness, sustainability, and sensory fidelity priorities is forcing portfolio diversification strategies.
Precision drum-roasting with real-time moisture monitoring is consolidating quality control standards across mid-scale producers. Specialty beverage manufacturers in France and Germany are retrofitting equipment to achieve batch-to-batch consistency previously limited to large industrial roasters. This technology compression is narrowing the quality gap between artisan and mass-market positioning tiers.
EFSA food-labeling standards for caffeine-free assertions are tightening enforcement scope across member states. Manufacturers must reformulate products testing above trace thresholds or face relabeling costs and retail delisting. The chicory-dominant segment faces highest exposure given traditional processing methods that occasionally retain residual alkaloids.
Direct-to-consumer subscription models are capturing repeat purchase loyalty previously held by supermarket shelf placement. Wellness-oriented buyers in urban France and Germany prioritize convenience and personalization over traditional retail discovery. This channel pivot is most pronounced among mushroom-based entrants targeting adaptogenic benefit seekers.
Coffee Substitute Market Segmentation
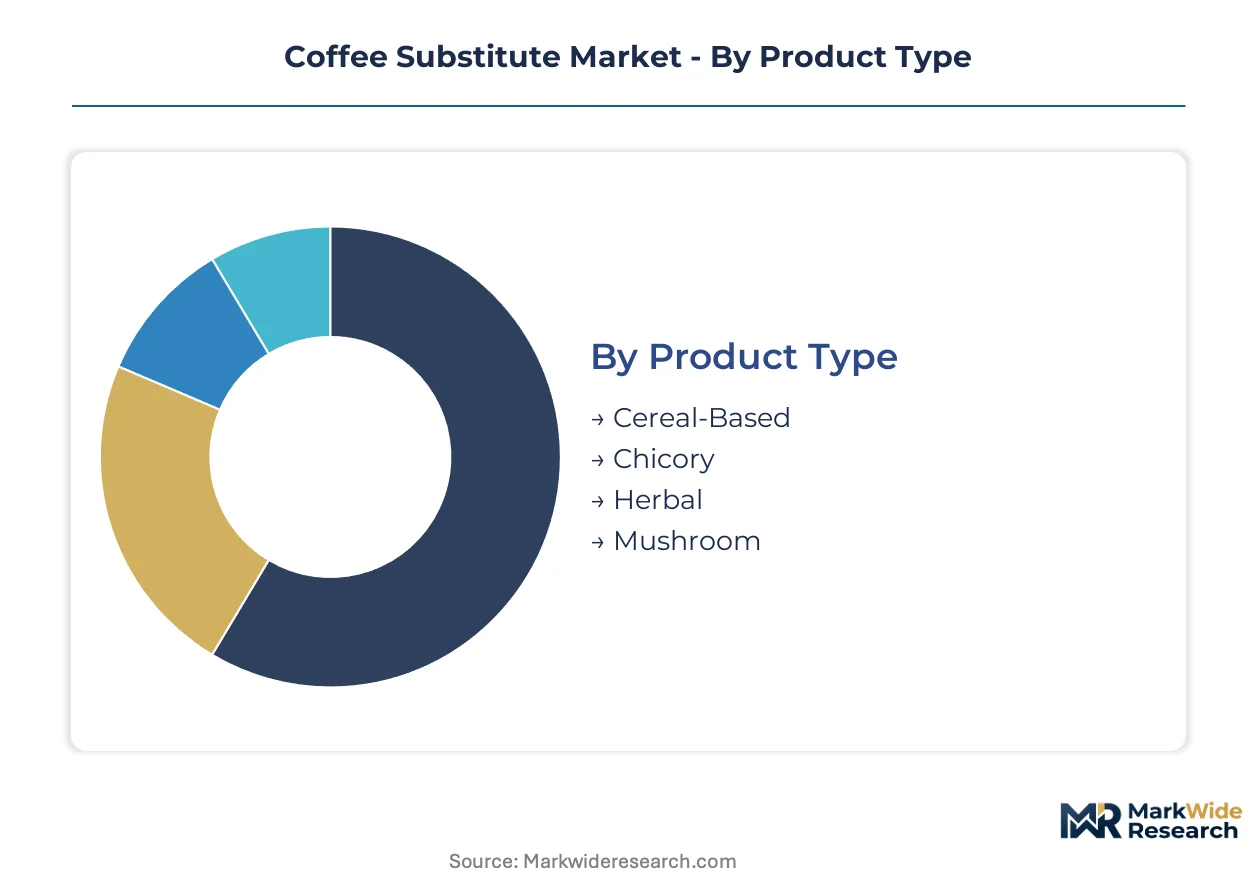
Coffee substitute manufacturers calibrate portfolio depth across four intersecting dimensions: botanical composition determines sensory fidelity and functional positioning; physical form dictates preparation convenience and channel economics; distribution architecture shapes margin capture and brand discovery mechanics; buyer psychography separates premium wellness seekers from mass-market converts.
Product Type:
Roasting temperature profiles and raw material provenance distinguish competitive positioning within caffeine-free formulations.
- Cereal-Based:Barley, rye, and spelt undergo drum-roasting at 180–220°C to develop Maillard-reaction complexity mimicking arabica depth. German specialty cafes in Berlin and Munich feature dedicated grain-drink menu sections, responding to rising caffeine sensitivity among evening consumers.
- Chicory:Roasted Cichorium intybus root delivers bitter, woody notes with inulin prebiotic content. Northern France and Belgium concentrate cultivation, creating geographic supply vulnerability that EU Green Deal organic mandates are accelerating through certified acreage expansion.
- Herbal:Dandelion, carob, and fig blends offer milder flavor profiles for transition-stage coffee abandoners. Formulation chemists with dual botanical-sensory competency command premium compensation, constraining R&D scaling.
- Mushroom:Lion's mane, chaga, and reishi extracts occupy functional positioning tiers with adaptogenic claims. EFSA novel-food approval timelines of 18–24 months delay commercial scaling beyond wellness-oriented niches in urban France.
Mature deployment sits with chicory across traditional French consumption. Newer deployment is concentrated in mushroom formulations gaining premium placement.
Form:
Preparation modality separates at-home ritual from foodservice operational efficiency, with powder and liquid capturing divergent margin structures.
- Powder:Instant-dried granules dominate supermarket shelf presence and subscription-direct channels. Wellness buyers in France and Germany prioritize convenience over retail discovery, consolidating repeat purchase loyalty.
- Liquid:Concentrates enable automated dispensing in workplace and hospitality settings. Foodservice adoption climbs fastest as operational efficiency demands streamline brewing systems.
- Granules:Agglomerated particles dissolve faster than conventional powder for impatient preparation. German health stores feature granule formats prominently in grain-beverage sections.
- Capsules:Single-serve pods compatible with espresso machines target premium convenience seekers. Compatibility certification with proprietary brewing systems limits brand proliferation.
Volume concentration rests with powder across European retail. Margin expansion concentrates in liquid concentrates for foodservice penetration.
Distribution Channel:
Channel selection determines discovery mechanics and pricing autonomy, with digital and physical retail serving distinct buyer journey stages.
- Online Retail:Direct-to-consumer subscriptions capture personalization demand and bypass slotting-fee economics. Urban French and German wellness buyers drive repeat purchase velocity through curated delivery.
- Supermarkets:Mass-market penetration requires trade investment for shelf placement and promotional support. Nestlé S.A. sustains European presence through instant grain-beverage portfolio distribution.
- Health Stores:Natural-foods independents provide educational selling environment for ingredient-story differentiation. Teeccino Caffe dominates North American placement through herbal roasting expertise.
- Specialty Shops:Curated beverage retailers offer premium positioning and tasting consultation. Four Sigmatic secures functional-mushroom tier placement in wellness-oriented retail.
Established volume flows through supermarkets. Channel expansion accelerates fastest in online retail capturing subscription loyalty.
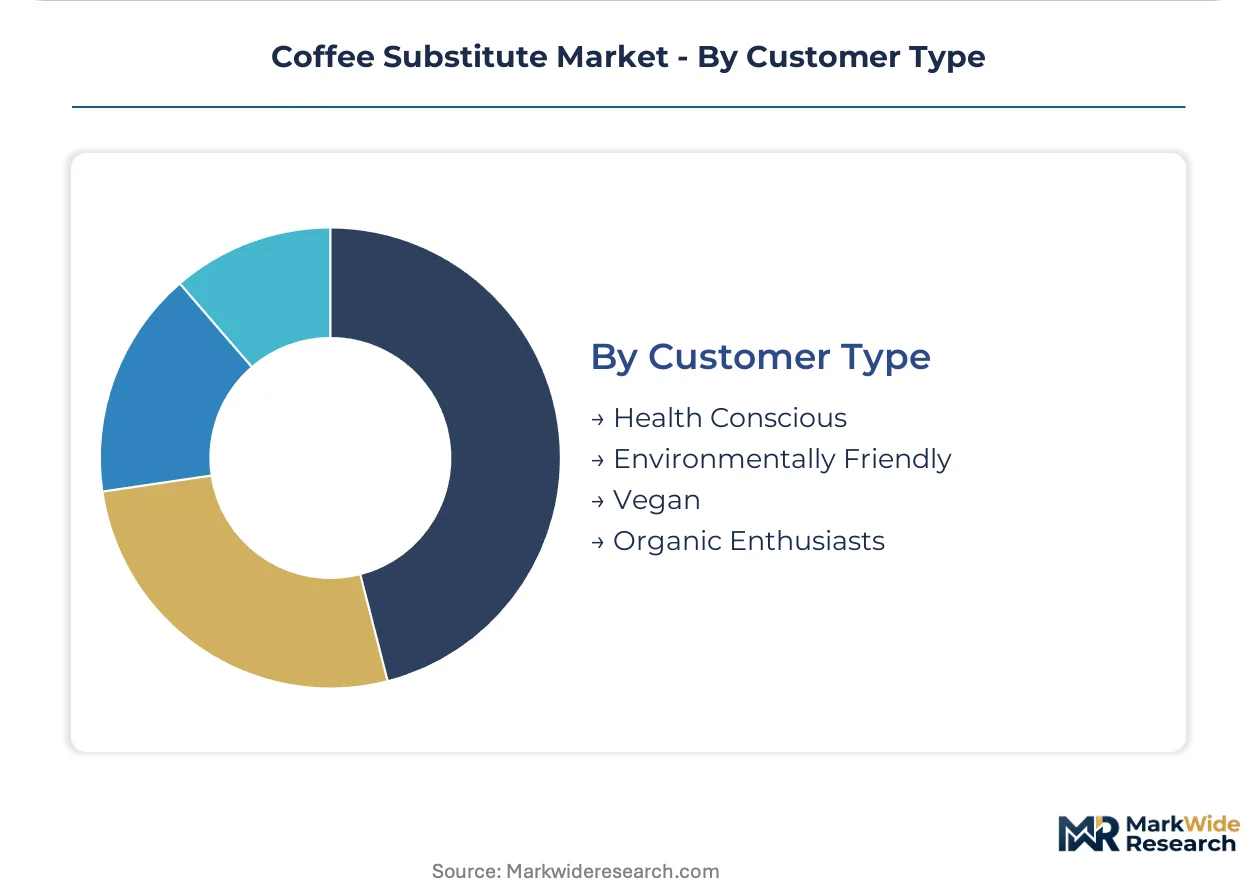
Customer Type:
Psychographic segmentation separates price-insensitive wellness seekers from values-driven sustainability adopters, informing formulation and certification investment.
- Health Conscious:Caffeine-intolerant and pregnancy-restricted buyers prioritize physiological compatibility over sensory exactitude. Evening consumption routines exclude stimulants, expanding addressable base.
- Environmentally Friendly:Carbon footprint and agricultural practice transparency drive purchase decisions. EU Green Deal sustainability requirements compress conventional supply chains toward certified sourcing.
- Vegan:Plant-based purity verification attracts buyers avoiding animal derivatives across ingredient and processing stages. Label scrutiny intensity exceeds conventional coffee categories.
- Organic Enthusiasts:EU Organic Regulation 2018/848 harmonized standards reduce cross-border compliance fragmentation for multi-national brand expansion. Certification investment separates premium from conventional tiers.
Core demand anchors with health-conscious buyers managing caffeine sensitivity. Fastest expansion occurs among organic enthusiasts as harmonized standards enable scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Western Europe where traditional chicory consumption intersects with emerging functional-mushroom adoption. France and Germany anchor volume through established retail infrastructure and specialty cafe expansion.
France
Traditional chicory consumption in Hauts-de-France and Île-de-France provides volume foundation while mushroom-based entrants gain premium placement in Paris wellness retail. EU Organic Regulation 2018/848 harmonization reduces cross-border compliance costs for multi-national brands. Lille and Roubaix industrial clusters concentrate roasting equipment manufacturing for drum-roasting modernization.
Germany
Berlin and Munich specialty cafes expand dedicated grain-drink menu sections as caffeine sensitivity rises among evening consumers. EU Green Deal agricultural mandates accelerate certified organic chicory sourcing contracts across Bavaria and North Rhine-Westphalia. Hamburg port infrastructure handles bulk chicory root imports from Belgian cultivation zones.
Belgium
Wallonia and Flanders cultivation belts supply raw chicory root to French and German roasters under tightening sustainability certification requirements. EFSA food-labeling standards enforcement drives reformulation investments for trace alkaloid removal. Antwerp logistics hubs coordinate cross-border distribution to Dutch and German manufacturing facilities.
United States
FDA GRAS determinations for novel botanical ingredients shape mushroom extract formulation investments in California and Colorado wellness markets. Natural-foods independents in Los Angeles and Denver provide educational selling environments for herbal roasting expertise. Pacific Northwest direct-to-consumer subscription models capture repeat purchase loyalty through curated delivery.
United Kingdom
London specialty retailers blend continental European chicory traditions with emerging adaptogenic positioning for urban wellness buyers. Post-Brexit regulatory divergence from EFSA standards creates dual compliance burden for pan-European brands. Midlands distribution centers handle grain-based beverage consolidation for supermarket channel penetration.
Coffee Substitute Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with mass-market penetration requiring trade investment while premium tiers reward ingredient-story differentiation. The vendor base spans multinational food conglomerates, regional roasting specialists, and venture-backed functional wellness entrants. Three archetypes dominate: heritage grain-roasting houses, botanical extraction specialists, and adaptogenic positioning innovators. Competitive moves concentrate on long-term organic supply contracts and direct-to-consumer channel infrastructure.
Within the heritage grain-roasting tier, Barleycup International Limited and Inka Food Sp. z o.o. exemplify European manufacturing concentration. Nestlé S.A. occupies a position representing mass-market conglomerate scale. Teeccino Caffe and Four Sigmatic anchor the North American premium positioning spectrum, with the former exemplifying herbal roasting expertise and the latter representing functional-mushroom tier innovation. Post Consumer Brands, LLC and Kraft Heinz Company sit within diversified food portfolio structures. Dandy Blend Limited represents single-category specialization.
| Leading Market Players |
|---|
| Barleycup International Limited |
| Inka Food Sp. z o.o. |
| Nestlé S.A. |
| Teeccino Caffe |
| Post Consumer Brands, LLC |
| Kraft Heinz Company |
| Dandy Blend Limited |
| Four Sigmatic |
| The Roasted Grain Company, Inc. |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with dual competency in botanical extraction and sensory profiling concentrate in Northern France and Belgium, where labor-cost premiums widen spreads between artisan-roasted premium tiers and mass-market economy positioning. This workforce scarcity forces manufacturers to absorb specialist compensation premiums or sacrifice batch consistency, compressing margins at the standard tier while insulating premium pricing from downward pressure.
Pricing Analysis
Volume concentrates in powder-form cereal-based and chicory segments traded through supermarket channels, while margin expansion accrues to liquid concentrates and mushroom-based formulations in specialty retail and direct-to-consumer subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates EU Organic Regulation 2018/848 certified artisan roasters from conventional drum-roasted grain beverages and private-label economy alternatives. Cost compression in the standard tier is intensifying because EFSA novel-food approval investments for mushroom extracts amortize across smaller production runs. Health-conscious buyers managing caffeine sensitivity exhibit lowest price sensitivity, while evening-consumption routine adopters benchmark against conventional arabica value perceptions.
Supply Chain Analysis
Chicory root supply rests on Northern France and Belgium cultivation belts, with secondary sourcing from Dutch contract growers under EU Green Deal sustainability mandates. Raw material dependencies center on Cichorium intybus rootstock, automated drum-roasting equipment with 180–220°C temperature control systems, and certified organic acreage expansion financing. Single-source vulnerability concentrates in Belgian chicory genetics and French roasting equipment manufacturing clusters concentrated around Lille and Roubaix. Distribution runs through Antwerp and Hamburg port infrastructure for bulk root imports, with finished goods flowing through supermarket central warehouses, health store independents, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chicory root supply concentration in Northern France and Belgium creates a structural capacity bottleneck that props pricing power for certified organic roasters holding long-term cultivation contracts. This supply constraint favors incumbents with secured acreage and disadvantages speculative entrants facing 18–24 month EFSA novel-food approval timelines for alternative botanical inputs.
For Market Incumbents: Hedge against chicory supply disruption by securing backward integration into certified organic acreage expansion across Wallonia and Flanders under EU Green Deal compliance deadlines. Diversify formulation portfolios toward mushroom-based adaptogenic tiers to capture premium placement in wellness-oriented retail, insulating margin exposure from arabica price volatility spillover that distorts grain-based beverage value perceptions. For New Entrants and Emerging Players: Enter via German specialty cafe channel expansion in Berlin and Munich, where independent beverage retailers are adding dedicated grain-drink menu sections with limited incumbent penetration. Target foodservice liquid concentrate dispensing systems in workplace and hospitality settings, leveraging operational efficiency demands to bypass supermarket slotting-fee economics that favor Nestlé S.A. scale advantages. For Investors and Strategic Acquirers: The window for entry favors heritage grain-roasting houses with established EU Organic Regulation 2018/848 certification and captive chicory supply contracts. Acquisition targets should demonstrate formulation chemist retention and drum-roasting equipment modernization. The signal to watch is EFSA novel-food approval acceleration for lion's mane and chaga extracts, which would unlock commercial scaling beyond current wellness-oriented niche positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU Organic Certification Investment | EU Organic Regulation 2018/848 harmonization reduces cross-border compliance fragmentation for multi-national brand expansion. |
| Direct-to-Consumer Subscription Launch | Urban French and German wellness buyers prioritize convenience and personalization over traditional retail discovery channels. |
| Foodservice Liquid Concentrate Expansion | Automated brewing systems in workplace and hospitality settings adopt ready-to-dispense formats for operational efficiency gains. |
| Long-term Chicory Supply Contracting | EU Green Deal agricultural mandates accelerate certified organic acreage expansion across France and Belgium cultivation belts. |
| Functional Mushroom Formulation Pipeline | EFSA novel-food approval timelines determine which adaptogenic entrants can scale beyond niche wellness positioning. |
Methodological Framework
Trade publications, EU regulatory filings, and customs import records formed the secondary backbone, cross-referenced against primary interviews with roasting equipment manufacturers, chicory cultivation cooperative managers, specialty cafe procurement leads, and EFSA regulatory affairs consultants. Bottom-up volume estimates derived from drum-roasting capacity utilization across Northern France and Belgium production clusters, validated against top-down category spend analysis from supermarket and health store channel data.
Historical trendline analysis tracked chicory acreage expansion, certified organic conversion rates, and mushroom-based formulation patent filings across the analysis window. Segmentation modeling incorporated botanical composition, physical form, distribution architecture, and buyer psychography dimensions. CAGRs were derived from elasticity-adjusted demand projections for caffeine-intolerant and pregnancy-restricted consumer segments, with cross-validation against arabica price correlation coefficients and EU Green Deal compliance investment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA novel-food approval delays, chicory crop disease outbreaks in concentrated cultivation zones, and arabica price volatility spillover effects. Forecasts reflect assumptions documented in regulatory clearance timelines, organic certification conversion rates, and specialty cafe channel expansion trajectories. A small set of named triggers warrants ongoing watch: EFSA adaptogenic health claim determinations, EU Green Deal subsidy allocation shifts, and drum-roasting equipment automation cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Ice Tea Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market