
 Non-Alcoholic Malt Beverages Market | 2026-2036
Non-Alcoholic Malt Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Malt Beverages Market Outlook
Buyer concentration among health-conscious retail consumers is hardening as fitness-oriented millennials and Gen Z shoppers consolidate purchasing power around zero-alcohol portfolios. Anheuser-Busch InBev leverages its brewing infrastructure to scale non-alcoholic malt production across multiple continents. Heineken N.V. differentiates through premium positioning and sustained investment in flavor authenticity. Carlsberg Group anchors its strategy in European markets where moderation trends have deepest roots.
Non-alcoholic malt beverages are brewed cereal-based drinks where alcohol content is reduced below 0.5% ABV through vacuum distillation, arrested fermentation, or reverse osmosis, yielding products that replicate the mouthfeel and aromatic complexity of traditional beer without intoxicating effects. Malt beer occupies the mature volume core of the category, while flavored malt beverages capture the fastest-growing margin pool as younger consumers seek novel taste profiles. Supermarkets and online retailers together dominate distribution channel value capture, though convenience stores are gaining velocity in urban grab-and-go occasions.
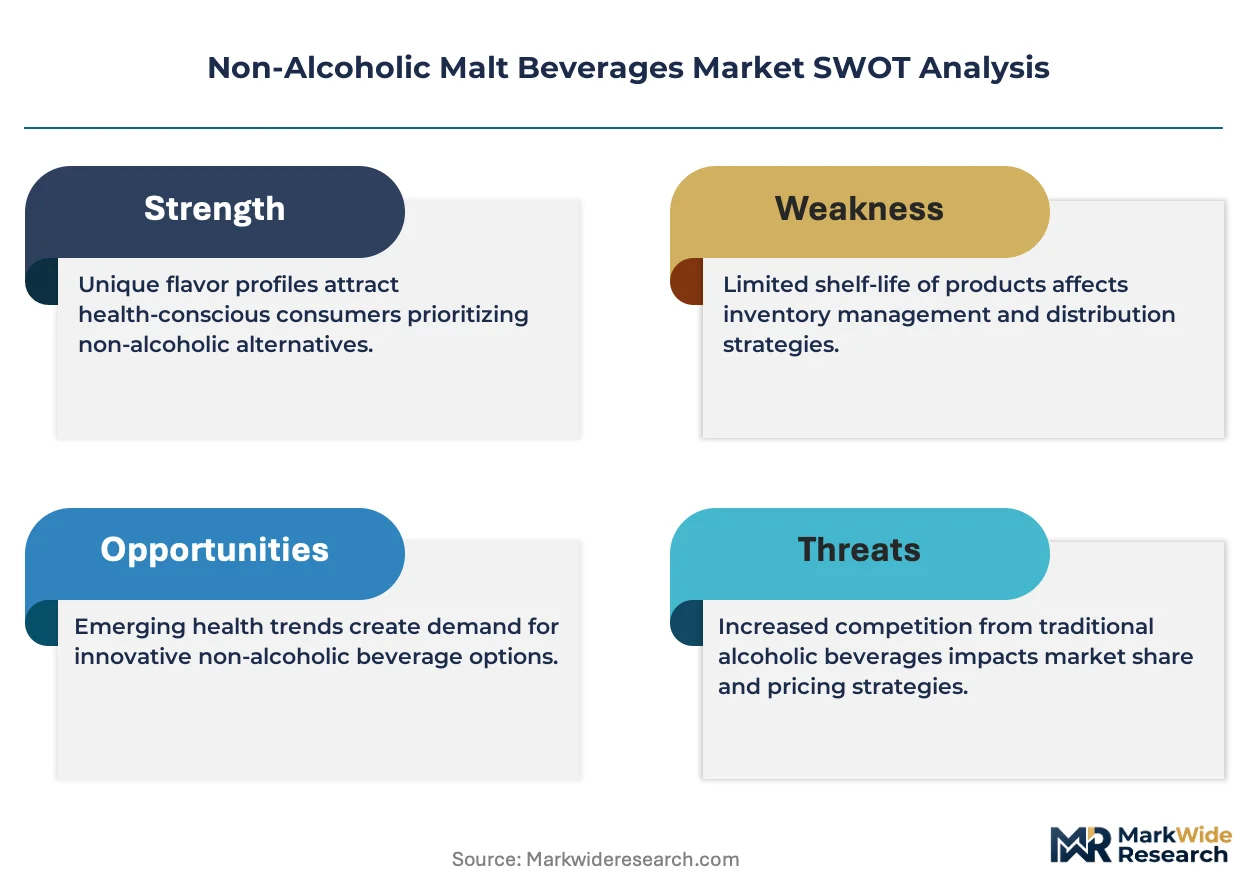
FDA labeling requirements in the United States, EU REACH standards on packaging materials, and Saudi Arabia's SFDA halal certification protocols collectively shape formulation transparency and market access conditions across major producing regions. Stakeholders must monitor evolving national definitions of "non-alcoholic" as regulatory divergence between 0.0% and 0.5% ABV thresholds threatens to fragment product standardization and complicate cross-border trade strategies.
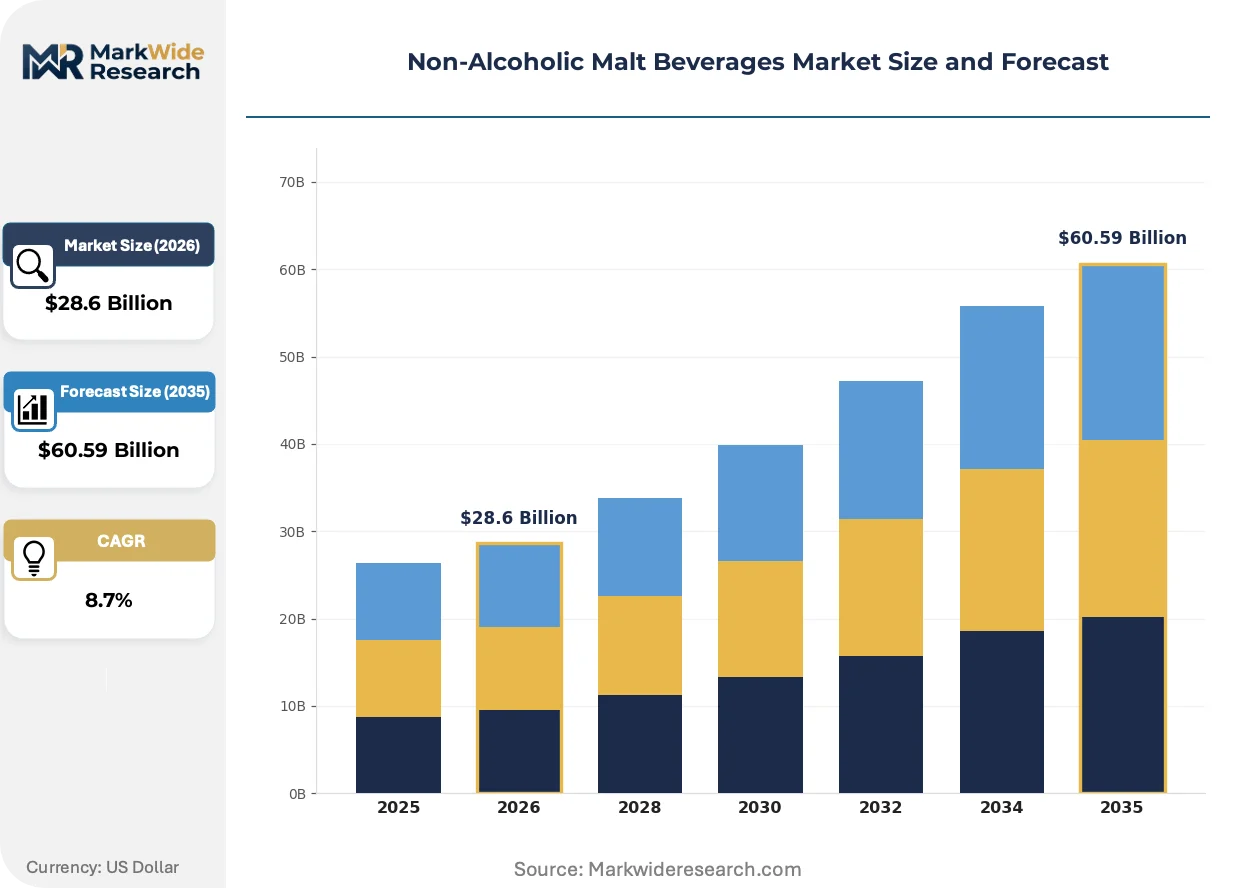
Market Dynamics
Wellness-oriented consumption patterns are consolidating purchasing power around zero-proof alternatives, forcing brewers to reconfigure fermentation infrastructure and reformulate for sub-0.5% ABV thresholds while maintaining sensory authenticity.
Growth Catalysts
- EU REACH packaging standards:Harmonized material safety protocols are streamlining cross-border formulation transparency, reducing compliance duplication for malt beverage exporters.
- Arrested fermentation technology:Advanced yeast strain management and temperature-controlled brewing processes are enabling precise alcohol limitation without flavor degradation.
- Saudi Arabia halal certification:SFDA protocols are creating formal market access pathways, converting religious dietary requirements into structured demand anchors.
Market Restraints
- Barley input cost volatility:Climate-driven supply fluctuations in major cereal-producing regions are compressing margin predictability for malt extract sourcing.
- 0.0% versus 0.5% ABV regulatory divergence:Inconsistent national intoxicant thresholds between Saudi Arabia, Germany, and Brazil are fragmenting product standardization and complicating inventory pooling.
- Sparkling water substitution:Unflavored carbonated alternatives at lower price points are capturing casual refreshment occasions from entry-level malt beverages.
Strategic Opportunities
- Brazilian urban convenience channels:Grab-and-go retail formats in São Paulo and Rio de Janeiro are underpenetrated for chilled non-alcoholic malt SKUs versus traditional beer.
- Reverse osmosis and vacuum distillation convergence:Hybrid dealcoholization systems are opening precision control over aromatic compound retention previously lost to thermal processing.
- German moderation incentive frameworks:Workplace wellness subsidies and employer-sponsored Dry January programs are institutionalizing trial behavior among white-collar demographics.
Industry Challenges
- Flavor chemist talent scarcity:Brewing science programs produce insufficient specialists in non-alcoholic sensory replication, extending R&D cycle timelines for authentic mouthfeel development.
- Halal certification audit complexity:Multi-stage SFDA facility inspections and supply chain documentation requirements are delaying product launches by 8-14 months in Gulf markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Malt Beverages Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malt Beer, Malt Beverage Mixes, Flavored Malt Beverages, Non-Alcoholic Cocktails End User: Retail Consumers, Restaurants, Bars, Cafes Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Distributors Packaging Type: Cans, Bottles, Tetra Packs, Draft |
| Companies Covered | Coca-Cola Company, Diageo plc, Anheuser-Busch InBev, Kirin Holdings Company, Asahi Group Holdings, Heineken N.V., PepsiCo, Inc., Molson Coors Beverage Company, Carlsberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Malt Beverages Market Strategic Shifts
Dealcoholization technology maturation is intersecting with regulatory precision demands and channel fragmentation, creating three distinct vectors of competitive differentiation across formulation, compliance, and distribution architecture.
Reverse osmosis membrane systems are expanding into commercial-scale production lines, enabling selective alcohol permeation while preserving volatile ester profiles. German and Brazilian craft breweries are retrofitting existing equipment at accelerating rates. This technology is expanding into premium positioning strategies where aromatic complexity commands price premiums over thermal-distilled alternatives.
EU F-Gas Regulation phase-down mandates are pressuring refrigeration-dependent supply chains to adopt lower-global-warming-potential cooling agents. Malt beverage distributors with captive cold-chain networks face accelerated equipment replacement cycles. German supermarket chains and Saudi Arabian hospitality wholesalers are prioritizing suppliers with certified low-emission transport fleets.
Fitness-tracking app integrations are emerging as novel trial-generation mechanisms, with wellness platforms in Germany and Brazil embedding zero-alcohol malt recommendations into post-workout hydration protocols. Traditional on-premise sampling is losing share to digital-native discovery channels. This behavioral pivot is most pronounced among urban millennials in São Paulo and Berlin, where gym membership correlates strongly with non-alcoholic beverage trial rates.
Non-Alcoholic Malt Beverages Market Segmentation
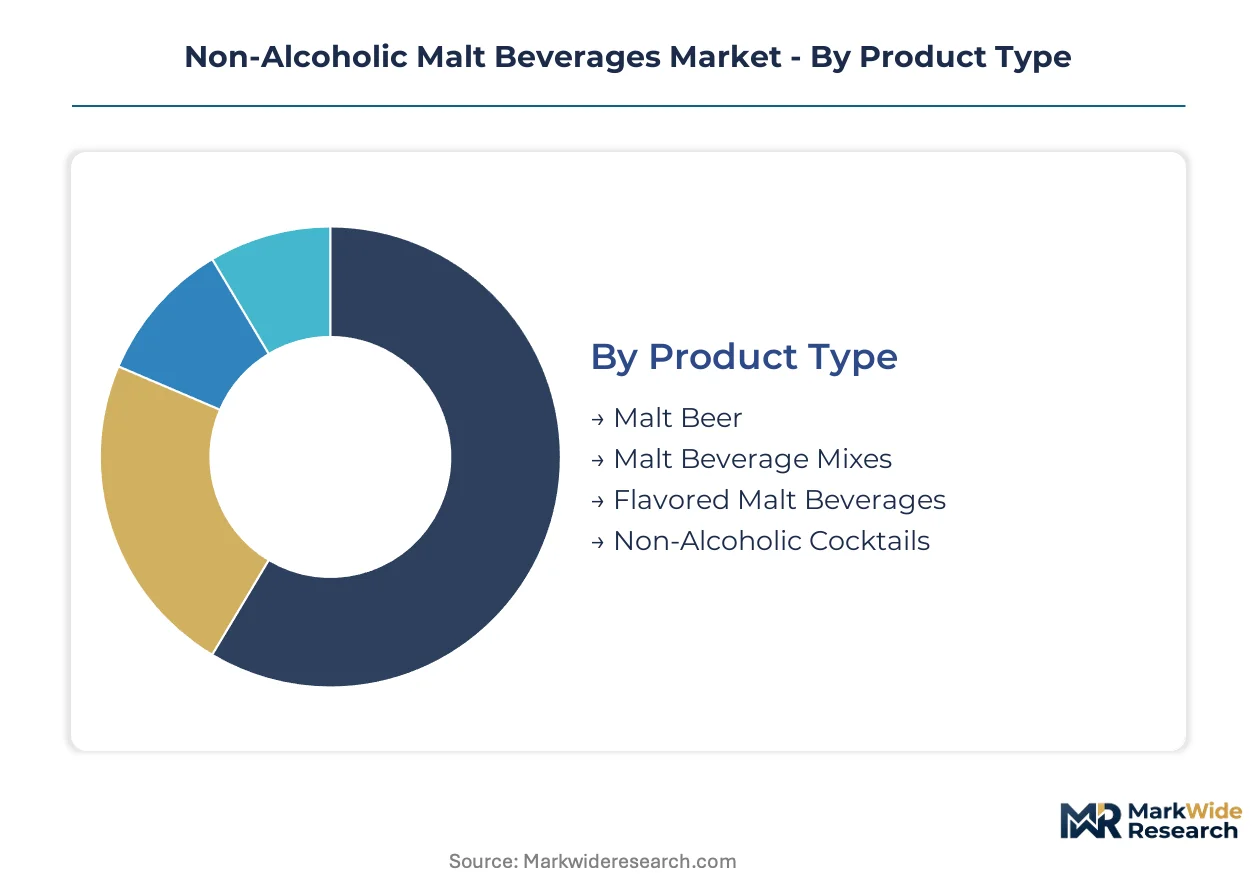
Segmentation in the non-alcoholic malt beverages market reveals how brewing technology, channel economics, and consumption occasions fragment into distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure, requiring tailored formulation and distribution strategies.
Product Type:
Upgrade cycles in dealcoholization equipment are pushing brewers toward product lines that maximize return on arrested fermentation and membrane system investments.
- Malt Beer:Traditional cereal-based formulations brewed to sub-0.5% ABV through vacuum distillation or controlled fermentation. German retail consumers anchor volume demand through established moderation habits, though margin compression from barley cost volatility constrains pricing flexibility.
- Flavored Malt Beverages:Fruit-infused and spice-modified variants targeting younger demographics seeking novel sensory profiles. Brazilian urban consumers in São Paulo and Rio de Janeiro drive trial velocity through convenience channel availability, with flavor innovation cycles accelerating to match sparkling water competition.
- Malt Beverage Mixes:Concentrated or powdered formats requiring consumer dilution. Saudi Arabian hospitality channels favor these for halal-certified beverage programs where storage efficiency matters.
- Non-Alcoholic Cocktails:Ready-to-serve mixed formulations mimicking classic cocktails. Premium positioning in German workplace wellness programs and Brazilian fitness-oriented retail.
Malt Beer sits at the top of the volume ranking, with Flavored Malt Beverages climbing the fastest.
End User:
Cost tier differentiation separates institutional buyers with negotiated supply contracts from discretionary retail purchasers.
- Retail Consumers:Individual purchasers through supermarkets and online channels. German Dry January participants and Brazilian gym-membership correlates form the core growth demographic, with trial-to-repeat conversion determining lifetime value.
- Restaurants:Full-service dining establishments incorporating non-alcoholic options into beverage menus. Saudi Arabian halal-certified establishments require SFDA-compliant supply chains, extending procurement timelines.
- Bars:On-premise venues where zero-proof alternatives compete with traditional beer for moderation occasions. German moderation incentive frameworks subsidize employer-sponsored trial programs.
- Cafes:Daytime consumption venues where malt beverages compete with coffee and tea. Brazilian urban grab-and-go formats show underpenetration versus traditional beer.
Retail Consumers command the largest absolute spend, with Restaurants expanding most quickly as menu integration accelerates.
Distribution Channel:
Volume concentration in cold-chain-dependent formats shapes logistics investment priorities across geographies.
- Supermarkets:Full-assortment retail with dedicated chilled beverage sections. German chains prioritize suppliers with EU F-Gas Regulation-compliant transport fleets, filtering vendor pools.
- Online Retailers:Direct-to-consumer platforms with subscription and bulk-purchase options. Brazilian fitness app integrations drive discovery-to-purchase conversion among urban millennials.
- Convenience Stores:Urban grab-and-go formats with high-velocity chilled turnover. São Paulo and Rio de Janeiro locations show particular underpenetration for non-alcoholic malt SKUs.
- Distributors:Wholesale intermediaries serving on-premise and off-premise accounts. Saudi Arabian hospitality wholesalers demand halal certification documentation across multi-stage audits.
Supermarkets retain volume leadership, with Online Retailers showing steepest expansion trajectory as digital-native discovery displaces traditional sampling.
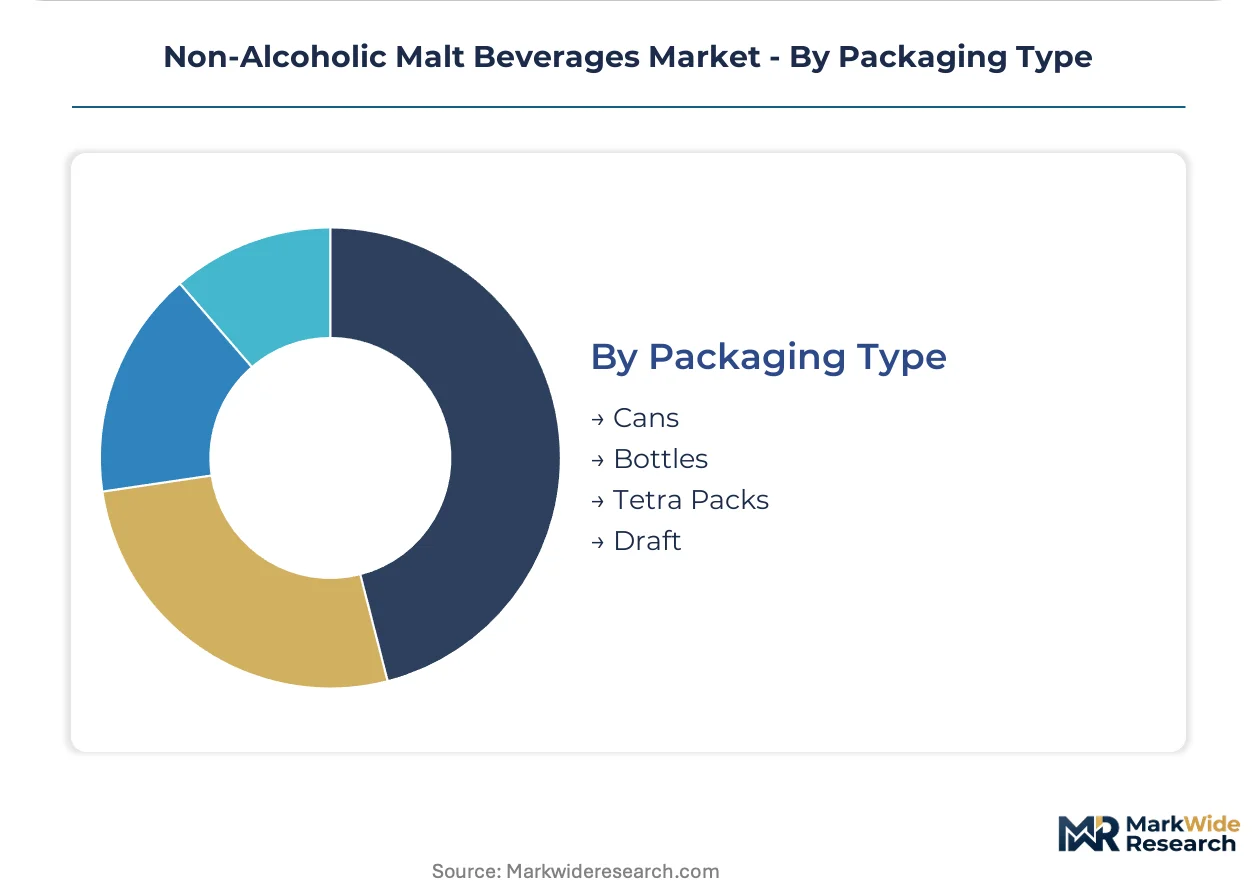
Packaging Type:
Margin structure varies sharply by material input costs and recycling compliance burdens across regulatory jurisdictions.
- Cans:Aluminum single-serve formats with extended shelf stability. German and Brazilian craft brewery retrofitting favors canning lines for arrested fermentation products.
- Bottles:Glass packaging for premium positioning and draft-style aesthetics. EU REACH packaging standards streamline cross-border shipment compliance.
- Tetra Packs:Aseptic carton formats for ambient distribution in markets with underdeveloped cold chains. Saudi Arabian retail channels favor these for storage efficiency.
- Draft:Keg-based dispensing for on-premise accounts. German bars and Brazilian restaurants drive keg economics through high-throughput moderation occasions.
Cans dominate production volume, with Tetra Packs gaining share fastest in ambient-distribution markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brewing science talent pools in Germany, Brazil, and Saudi Arabia anchor regional innovation capacity. Each market channels distinct regulatory frameworks and consumption occasions into divergent growth trajectories.
Germany
Fitness-oriented millennials and workplace wellness programs drive trial velocity for zero-proof alternatives. The EU F-Gas Regulation mandates lower-global-warming-potential cooling agents across refrigerated supply chains. Bavaria's brewing clusters retrofit arrested fermentation equipment at accelerating rates to maintain sensory authenticity in sub-0.5% ABV formulations.
Brazil
Urban millennials in São Paulo and Rio de Janeiro consolidate purchasing power around flavored malt beverages through convenience channel discovery. ANVISA oversees labeling standards and alcohol threshold definitions that shape product standardization. The São Paulo metropolitan area shows pronounced underpenetration for chilled non-alcoholic malt SKUs versus traditional beer.
Saudi Arabia
Religious dietary requirements convert into structured demand anchors through formal halal certification pathways. The SFDA conducts multi-stage facility inspections and supply chain documentation audits extending product launch timelines. Riyadh and Jeddah hospitality wholesalers prioritize suppliers with certified low-emission transport fleets under tightening procurement standards.
United States
Health-conscious retail consumers expand purchases of zero-proof alternatives through supermarket and online channels. FDA labeling requirements govern alcohol content declarations and nutritional disclosures. California and New York Metro fitness-tracking app integrations embed malt beverage recommendations into post-workout hydration protocols.
United Kingdom
Moderation trends and Dry January participation institutionalize repeat purchasing among white-collar demographics. REACH standards on packaging materials streamline cross-border formulation transparency for exporters. London's on-premise venues and Southeast retail chains drive keg economics through high-throughput moderation occasions.
Non-Alcoholic Malt Beverages Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered competitive positions. Consolidation pressures concentrate volume leadership among multinational beverage holdings with captive brewing infrastructure. Three strategic archetypes dominate: diversified conglomerates leveraging cross-category distribution, brewing specialists investing in dealcoholization technology, and soft drink incumbents entering through flavored malt extensions. Capacity expansion in arrested fermentation systems and strategic partnerships for halal certification compliance represent the dominant competitive moves reshaping market access.
Within the diversified conglomerate tier, Coca-Cola Company and PepsiCo, Inc. occupy positions spanning soft drink and malt beverage portfolios. Among brewing specialists, Anheuser-Busch InBev anchors scale-driven production across multiple continents, while Heineken N.V. exemplifies premium positioning through sustained flavor authenticity investment. Carlsberg Group represents European market anchoring where moderation trends have deepest roots. Molson Coors Beverage Company and Kirin Holdings Company sit within mid-tier competitive positions balancing geographic diversification with category focus. Asahi Group Holdings and Diageo plc exemplify beverage holding company structures extending into non-alcoholic malt through portfolio breadth rather than pure-play concentration.
| Leading Market Players |
|---|
| Coca-Cola Company |
| Diageo plc |
| Anheuser-Busch InBev |
| Kirin Holdings Company |
| Asahi Group Holdings |
| Heineken N.V. |
| PepsiCo, Inc. |
| Molson Coors Beverage Company |
| Carlsberg Group |
| Others |
Value Chain & Pricing Dynamics
German workplace wellness subsidies and employer-sponsored Dry January programs are hardening procurement specifications around zero-proof authenticity, forcing suppliers to absorb arrested fermentation equipment costs and compressing margin pools for thermal-distilled alternatives.
Pricing Analysis
Capacity additions in Bavaria's brewing clusters are reshaping price floors for sub-0.5% ABV formulations as retrofitting spreads across German craft breweries. Three-tier pricing structure across premium, standard, and economy levels separates membrane-system products from vacuum-distilled alternatives, with flavor chemist scarcity and halal certification tiers adding further differentiation. Cost compression in entry-level malt beer is intensifying because sparkling water substitutes capture casual refreshment occasions. Brazilian urban millennials through fitness app integrations show lowest price sensitivity, while Saudi Arabian hospitality buyers negotiating multi-year supply contracts drive hardest terms.
Supply Chain Analysis
Direct-to-retail channels handle German supermarket and Brazilian convenience store demand, while distributor intermediaries manage Saudi Arabian hospitality procurement with SFDA documentation requirements. Barley sourcing concentrates in Germany, Brazil, and Australia, with malt extract production drawing from Bavarian and São Paulo brewing clusters. Supply chain vulnerability centers on climate-driven cereal price volatility and EU F-Gas Regulation compliance costs for refrigerated transport fleets. Distribution runs through cold-chain-dependent supermarket and convenience formats in urban German and Brazilian markets, with ambient Tetra Pack formats penetrating Saudi Arabian retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-alcoholic malt beverages constitute a late-cycle quality story as wellness-oriented buyers consolidate purchasing power around aromatic authenticity and halal-certified supply chains.
For Market Incumbents: Extend arrested fermentation capacity in Bavaria and São Paulo to defend sensory differentiation against thermal-distilled private labels. Deepen backward integration into barley sourcing to buffer climate-driven input volatility. Secure multi-stage SFDA facility pre-approval to compress Gulf market entry timelines against halal certification audit delays. For New Entrants and Emerging Players: Fitness-tracking app partnerships in Berlin and São Paulo offer lower customer acquisition costs than traditional on-premise sampling. Brazilian convenience channel underpenetration for chilled non-alcoholic malt SKUs presents the most penetrable white-space. Target employer-sponsored workplace wellness programs with subscription-format trial bundles. For Investors and Strategic Acquirers: Asymmetric upside sits with brewing specialists possessing captive dealcoholization technology and established halal certification pathways. Five-to-ten year viability favors assets with arrested fermentation R&D depth and Brazilian-German geographic diversification. Watch for SFDA audit timeline compression as signal of Gulf market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Arrested Fermentation Capacity Expansion | Bavarian equipment retrofits preserve volatile ester profiles that vacuum distillation destroys. |
| Halal Certification Pre-Approval Investment | SFDA multi-stage facility audits compress launch timelines by 8-14 months in Riyadh and Jeddah. |
| Fitness App Integration Partnerships | Berlin and São Paulo wellness platforms convert post-workout hydration occasions into trial generation. |
| EU F-Gas Compliant Cold Chain Upgrade | German supermarket chains filter vendor pools based on low-emission transport fleet certification. |
| Flavor Chemist Talent Acquisition | Brewing science program shortages extend R&D cycles for authentic mouthfeel development. |
Study Parameters
Bottom-up retail consumer and hospitality procurement modeling reconciled against top-down brewing capacity and dealcoholization equipment tracking forms the analytical core. Primary interviews with Bavarian brewing science directors, São Paulo category buyers at convenience chains, Riyadh hospitality procurement managers, and German supermarket sustainability officers combined with secondary validation from EU F-Gas Regulation filings, ANVISA labeling standards, SFDA halal certification protocols, and customs data on malt extract trade flows. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map barley sourcing through malt extract production to finished beverage distribution across product type, end user, channel, packaging, and geographic segments over the projection horizon. CAGRs derive from segment-level adoption curves calibrated against moderation trend penetration and regulatory threshold evolution. Forecast inputs include arrested fermentation technology diffusion rates and SFDA audit completion timelines.
The model assumes a particular technology adoption path; alternative pathways for reverse osmosis membrane systems versus hybrid vacuum distillation would alter the outlook. Forecasts reflect assumptions about EU-Gulf regulatory alignment on 0.0% versus 0.5% ABV thresholds and Brazilian convenience channel velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
Isotonic Drinks Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
China Energy- Drinks Market