
 Water Vending Machine Market | 2026-2036
Water Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Water Vending Machine Market Outlook
Skilled filtration technician availability is redrawing competitive boundaries across the water vending machine landscape. Culligan leverages its captive service infrastructure to sustain recurring revenue streams in North American commercial corridors. Azkoyen Group anchors European market penetration through precision engineering capabilities in compact footprint systems. Midea Group dominates cost-optimized manufacturing scales across Asian deployment networks.
A water vending machine is a self-service dispensing unit integrating pressurized filtration, UV sterilization, and payment authentication modules to deliver potable water in unmanned commercial environments. These systems typically operate at 50-150 psi feed pressure with multi-stage purification trains designed for continuous duty cycles in high-traffic locations. Freestanding configurations command the dominant installed base owing to their capacity for high-volume reservoir integration and flexible site placement. Reverse osmosis technology leads filtration modality adoption where source water total dissolved solids exceed regional potability thresholds. Wall-mounted units represent the fastest-growing physical format as urban real estate constraints intensify across dense commercial districts.
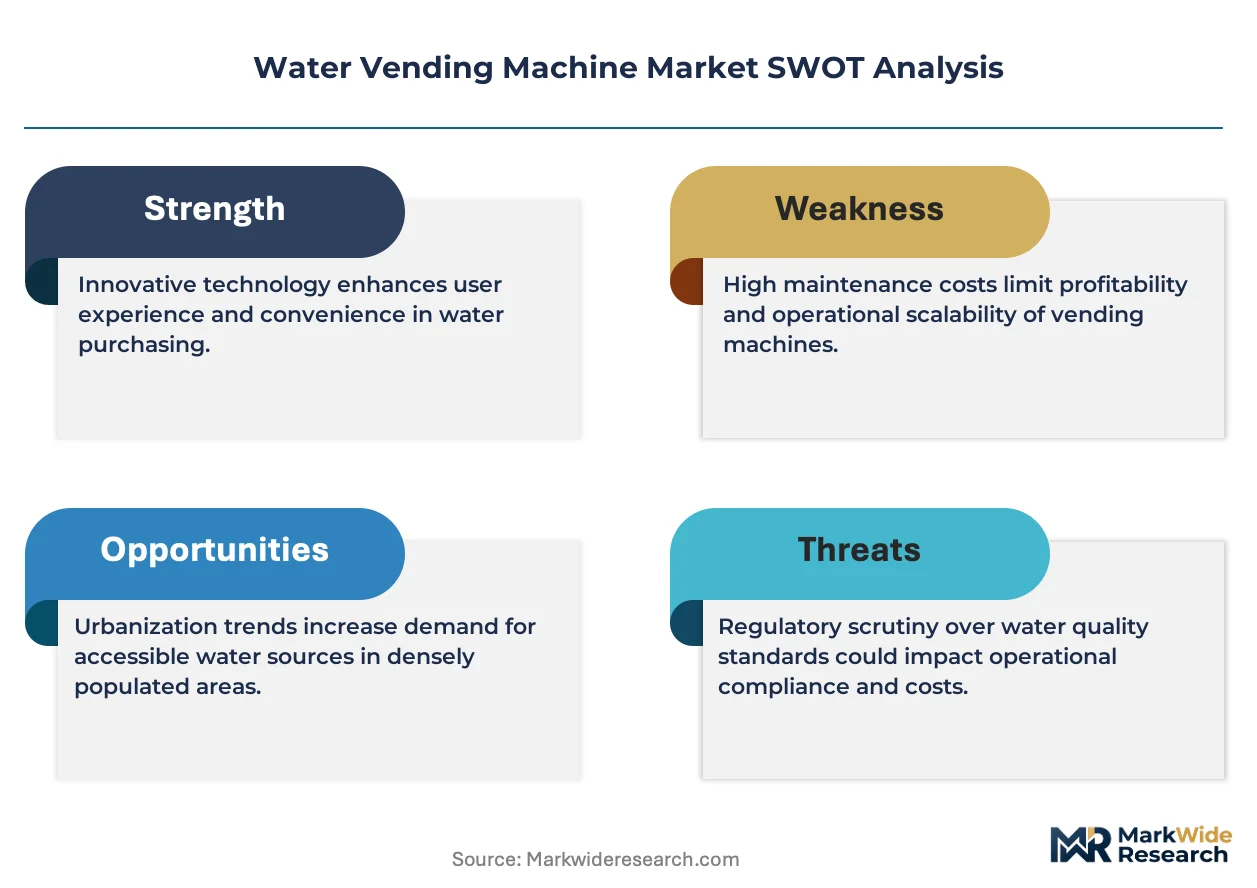
EPA Safe Drinking Water Act standards and EU Drinking Water Directive compliance frameworks elevate certification burdens for cross-border equipment suppliers. FDA bottled water equivalence protocols in the United States further constrain material selection and sanitization cycle specifications. BIS IS 10500 alignment requirements in India create additional testing obligations for membrane and housing assemblies. Stakeholders must monitor evolving PFAS detection mandates and their downstream implications for activated carbon and reverse osmosis replacement intervals.
Market Dynamics
Reverse osmosis certification mandates from the EPA and EU Drinking Water Directive are compressing equipment procurement timelines while elevating technical barriers for new entrants across public transit and commercial corridor deployments.
Growth Catalysts
- EPA Safe Drinking Water Act alignment:Municipal water quality failures in developing urban centers are accelerating machine deployments in high-traffic public corridors where bottled water access remains unreliable.
- UV-LED sterilization convergence:Mercury-free UV modules are reducing maintenance cycles and enabling compact wall-mounted formats in dense commercial districts with severe real estate constraints.
- Southeast Asian corridor density:Informal retail networks across Indonesia, Vietnam, and Thailand lack refrigerated last-mile hydration infrastructure, creating unmanned dispensing opportunities.
Market Restraints
- Membrane supply concentration:Reverse osmosis membrane fabrication concentrates among Korean and Japanese specialty chemical suppliers, exposing equipment manufacturers to input volatility and extended lead times.
- PFAS detection mandates:Emerging state-level requirements in the US and draft EU restrictions on per- and polyfluoroalkyl substances are forcing premature activated carbon and RO replacement interval compression.
- Substitute beverage proliferation:Flavored functional waters and low-sugar electrolyte drinks in PET formats compete directly with unflavored vending outputs in convenience-oriented channels.
Strategic Opportunities
- Indian railway corridor electrification:BIS IS 10500 certification requirements and expanding platform commercialization create demand for ruggedized high-capacity units across 7,000+ stations.
- Contactless payment integration:NFC and QR-code authentication modules are enabling subscription-based hydration passes in corporate campuses and university networks.
- EU Green Deal circularity incentives:Refill infrastructure deployment targets in the Packaging and Packaging Waste Regulation create procurement preferences for machines with recycled housing content.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction EPA, FDA, and EU Drinking Water Directive testing creates 14-18 month approval cycles that delay revenue recognition for new product introductions.
- Filtration technician scarcity:Specialized membrane replacement and pressure vessel maintenance skills concentrate among legacy water treatment service networks, constraining rapid geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Vending Machine Market |
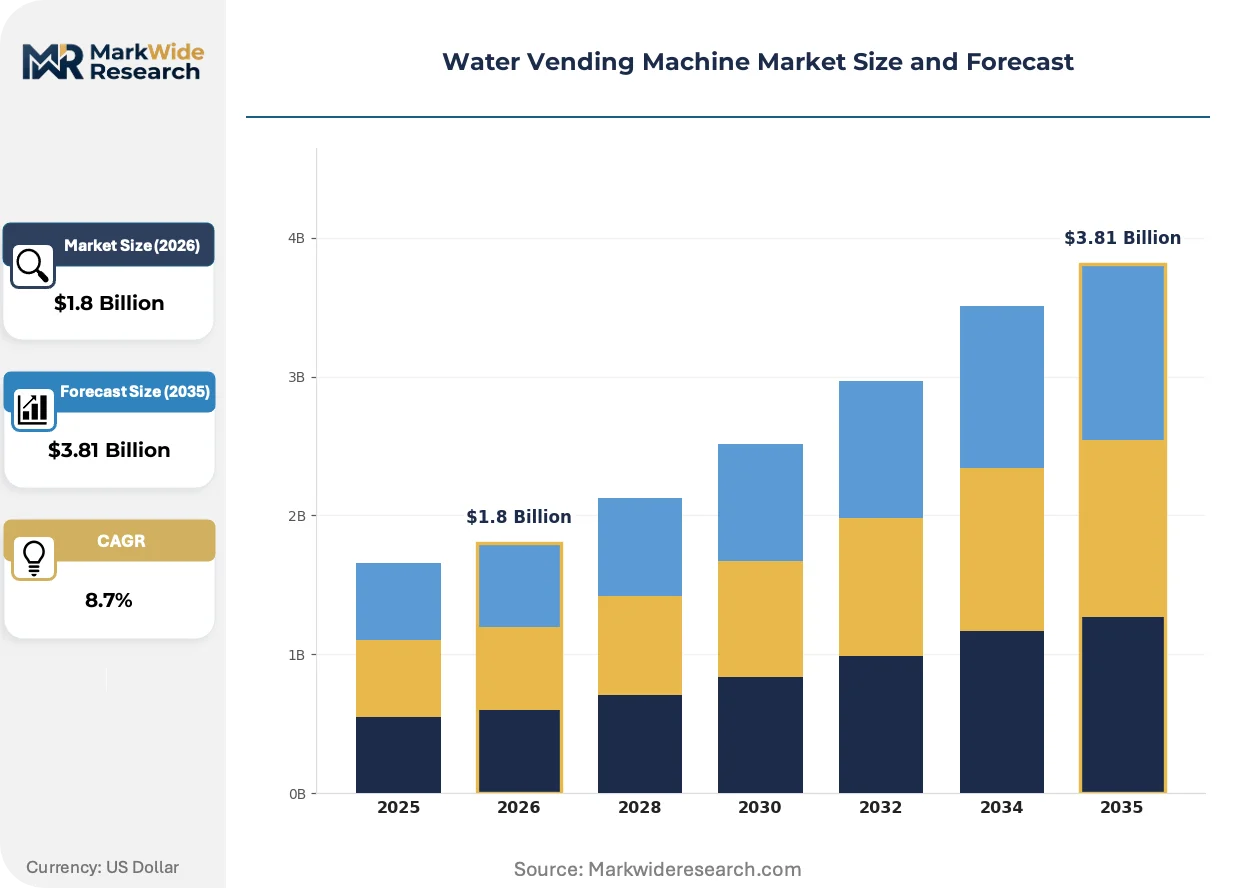
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Wall-Mounted, Tabletop, Portable Technology: Reverse Osmosis, UV Filtration, Carbon Filtration, Nanofiltration End User: Public Spaces, Offices, Gyms, Educational Institutions Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets |
| Companies Covered | Azkoyen Group, Evoca Group, Waterlogic, Ice House America, Midea Group, Culligan, Bianchi Vending Group S.p.A., Canaletas, Primo Water Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Vending Machine Market Strategic Shifts
Equipment form factors and sterilization modalities are converging around space-constrained urban deployment models, while regulatory detection thresholds for emerging contaminants are rewriting maintenance protocols and component specifications.
Advanced oxidation processes combining UV-LED arrays with titanium dioxide photocatalytic surfaces are supplanting legacy mercury-vapor lamp systems in compact wall-mounted units. Transit authorities and commercial property managers in Singapore and Tokyo are specifying these configurations for 24-hour unmanned corridors. The technology is compressing allowable equipment footprints by 40% while eliminating hazardous material handling requirements that previously restricted installation sites.
REACH restrictions on per- and polyfluoroalkyl substances are forcing membrane housing manufacturers toward fluoropolymer-free sealing materials and alternative barrier polymers. Equipment suppliers serving EU member states must now validate material migration profiles against evolving ECHA substance lists before CE marking approval. German and Dutch municipal procurement frameworks are already embedding these compliance prerequisites into technical specifications for public hydration infrastructure.
Corporate facility managers are unbundling after-sales service contracts from initial equipment procurement, selecting third-party filtration specialists for membrane replacement and calibration protocols. This pattern fragments vendor revenue streams while elevating transparency requirements for component lifecycle data. The shift is most pronounced in North American commercial real estate portfolios where sustainability reporting obligations under CSRD-aligned corporate standards demand granular maintenance documentation.
Water Vending Machine Market Segmentation
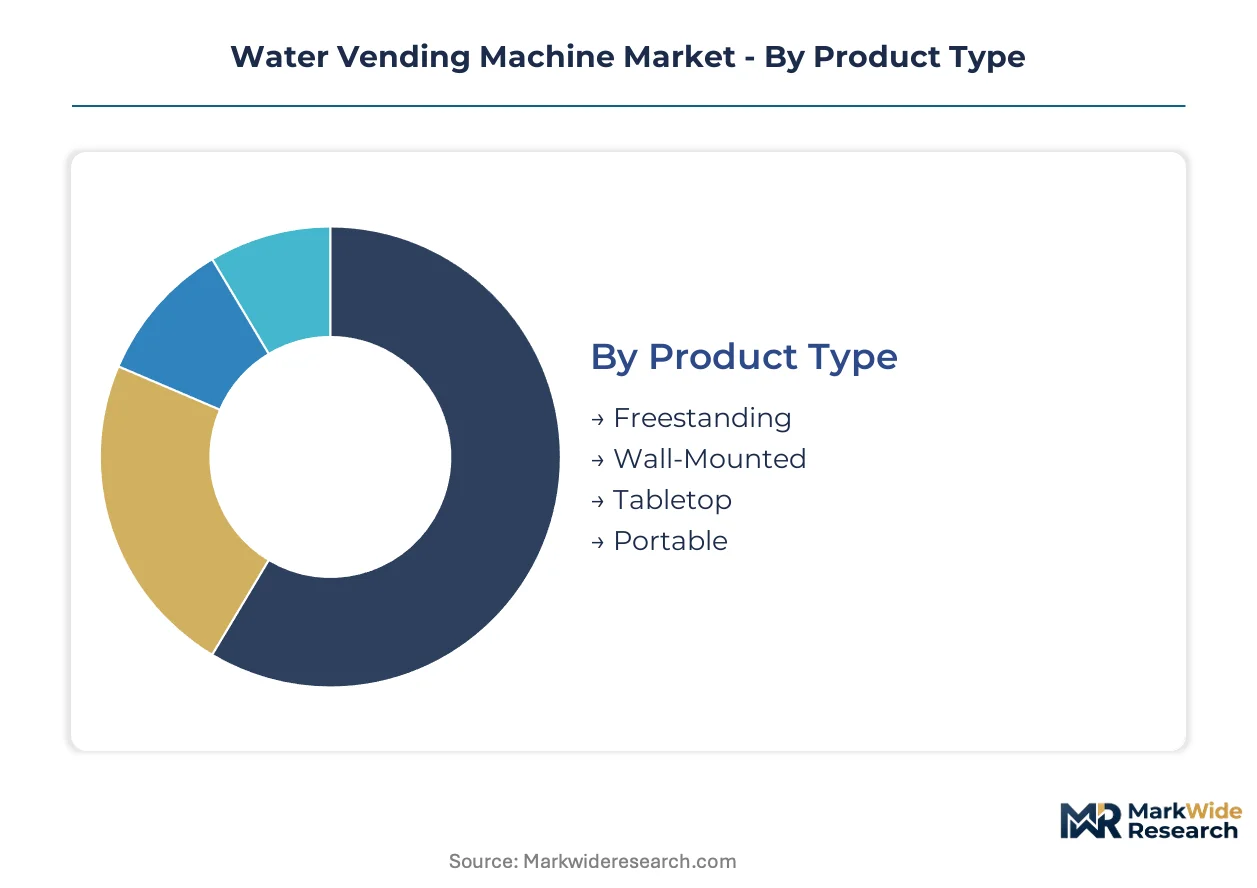
Water vending machine segmentation reveals distinct procurement patterns across deployment environments. Product format selection depends on real estate constraints and traffic density, while filtration modality choices track source water chemistry and regulatory compliance burdens.
Product Type:
Freestanding units flow through distributor networks into high-traffic transit corridors and shopping centers, while wall-mounted formats concentrate in direct sales channels targeting corporate real estate portfolios with severe spatial limitations.
- Freestanding:These systems integrate pressurized multi-stage purification trains with high-capacity reservoir tanks designed for continuous duty cycles. Demand concentrates across Indonesian and Vietnamese transit corridors where municipal water reliability remains inconsistent and unmanned hydration infrastructure fills gaps in informal retail networks.
- Wall-Mounted:Compact configurations deploy UV-LED sterilization arrays and reduced-footprint membrane housings for dense commercial districts. Singapore and Tokyo property managers specify these units for 24-hour corridors where hazardous material handling restrictions previously blocked mercury-vapor lamp installations.
- Tabletop:Countertop units serve limited-volume settings with simplified filtration stages and reduced feed pressure requirements.
- Portable:Mobile configurations target temporary deployment scenarios with battery-powered pumps and collapsible reservoir systems.
Freestanding units dominate installed base across Southeast Asian commercial corridors. Wall-Mounted formats are where expansion concentrates in dense urban districts with escalating real estate constraints.
Technology:
Filtration modality selection follows source water total dissolved solids profiles and evolving contaminant detection mandates, with cost tiers separating premium RO systems from basic carbon configurations.
- Reverse Osmosis:Semi-permeable membrane systems operating at elevated feed pressures remove dissolved ions and emerging contaminants below regulatory thresholds. Indian railway corridor electrification drives demand for ruggedized RO units certified to BIS IS 10500 standards across 7,000+ station platforms.
- UV Filtration:Mercury-free LED arrays deliver germicidal dose rates without hazardous material handling protocols. Wall-mounted format adoption in EU member states accelerates as REACH restrictions constrain legacy lamp system procurement.
- Carbon Filtration:Activated carbon stages target chlorine reduction and taste improvement in source water with favorable baseline chemistry.
- Nanofiltration:Looser membrane pore structures retain divalent ions while passing monovalent salts for selective hardness reduction applications.
Reverse Osmosis commands premium pricing tiers where source water quality fails potability standards. UV-LED convergence is climbing the fastest as maintenance cycle compression and format miniaturization reshape competitive specifications.
End User:
Customer type determines payment authentication complexity and service contract structure, with public sector procurement favoring subscription models and corporate buyers unbundling maintenance from initial equipment acquisition.
- Public Spaces:Transit authorities and municipal operators specify contactless payment modules and 24-hour remote monitoring capabilities. Deployment concentrates in Indonesian and Thai corridors where informal retail networks lack refrigerated last-mile hydration infrastructure.
- Offices:Corporate facility managers prioritize subscription-based hydration passes with NFC authentication and granular usage tracking for sustainability reporting obligations.
- Gyms:Fitness center operators demand high-flow dispensing rates and bottle-filling station integration.
- Educational Institutions:University networks specify vandal-resistant housings and multi-user authentication protocols for campus-wide deployment.
Public Spaces anchor volume procurement through municipal infrastructure budgets. Offices are gaining share fastest as corporate real estate portfolios standardize unmanned amenity provisioning.
Distribution Channel:
Channel structure reflects equipment complexity and geographic expansion requirements, with technical product categories concentrating in direct sales and standardized formats fragmenting across retail and digital touchpoints.
- Direct Sales:Manufacturer-led technical specification and installation support dominates large-format freestanding procurement for transit and railway corridor deployments.
- Distributors:Regional inventory positioning and local service networks capture mid-scale commercial installations across fragmented urban markets.
- Online Sales:Digital channels concentrate compact wall-mounted and tabletop configurations with simplified installation requirements.
- Retail Outlets:Brick-and-mortar touchpoints serve replacement component and consumable demand from existing installed base operators.
Direct Sales commands project-based revenue concentration for institutional procurement. Distributor networks are expanding most quickly as equipment manufacturers seek geographic coverage without captive service infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water vending machine consumption patterns diverge sharply between developed and emerging economies. North American and European deployments emphasize corporate amenity integration and sustainability compliance. Southeast Asian corridors prioritize high-volume transit infrastructure and informal retail network penetration.
United States
Corporate campus deployments and municipal transit corridors drive equipment procurement. EPA Safe Drinking Water Act alignment requirements and FDA bottled water equivalence protocols compress certification timelines for new market entrants. Installation clusters concentrate in California and Texas urban centers where real estate constraints favor wall-mounted UV-LED configurations.
Germany
EU Green Deal circularity incentives and REACH restrictions on fluorinated substances reshape material specifications and procurement preferences. CE marking approval cycles extend 14-18 months for cross-border equipment suppliers. Industrial demand centers on Bavaria and North Rhine-Westphalia commercial districts where corporate sustainability reporting obligations mandate granular maintenance documentation.
India
Railway corridor electrification and platform commercialization across 7,000+ stations create demand for ruggedized high-capacity units. BIS IS 10500 certification requirements impose additional testing obligations for membrane and housing assemblies. Deployment concentrates in Maharashtra and Gujarat transit corridors where municipal water reliability remains inconsistent.
Indonesia
Informal retail networks and high-traffic public corridors lack refrigerated last-mile hydration infrastructure, accelerating unmanned dispensing adoption. Municipal water quality failures in Jakarta and Surabaya urban centers propel machine installations. Procurement flows through distributor networks capturing mid-scale commercial installations across fragmented urban markets.
Singapore
Transit authorities specify 24-hour unmanned corridor configurations with mercury-free UV-LED sterilization arrays. Dense commercial district real estate constraints intensify demand for compact wall-mounted formats. Property managers in the central business district and Marina Bay cluster prioritize hazardous material elimination and space efficiency.
Water Vending Machine Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with mid-scale regional fabricators occupying fragmented geographic niches. Equipment complexity and certification burdens favor incumbents with captive service infrastructure and established regulatory relationships. Two strategic archetypes dominate: vertically integrated water treatment specialists leveraging recurring revenue streams, and precision engineering firms optimizing compact footprint systems. Competitive moves concentrate on geographic expansion through distributor partnerships and technology licensing arrangements that compress time-to-market for UV-LED and reverse osmosis configurations.
Within the integrated service tier, Culligan and Azkoyen Group exemplify contrasting geographic anchoring strategies. Culligan occupies a position tied to North American commercial corridor penetration through recurring maintenance contracts. Azkoyen Group represents European market specialization through precision engineering capabilities. Midea Group anchors the cost-optimized manufacturing archetype across Asian deployment networks. These three entities collectively illustrate how captive infrastructure, engineering specialization, and manufacturing scale define competitive positioning boundaries.
| Leading Market Players |
|---|
| Azkoyen Group |
| Evoca Group |
| Waterlogic |
| Ice House America |
| Midea Group |
| Culligan |
| Bianchi Vending Group S.p.A. |
| Canaletas |
| Primo Water Corporation |
| Others |
Value Chain & Pricing Dynamics
Mercury-free UV-LED sterilization modules replacing legacy mercury-vapor lamp systems are simultaneously shifting procurement geography toward East Asian semiconductor foundries and compressing maintenance-pricing premiums that previously sustained service revenue tiers. This substitution dynamic redistributes value capture from hazardous material handling specialists toward electronics-integrated system assemblers.
Pricing Analysis
Long-term service contracts with bundled membrane replacement schedules dominate institutional procurement in transit corridors, while spot-equipment purchases concentrate in fragmented commercial deployments. Three-tier pricing structure across premium RO-certified, standard UV-LED, and economy carbon-filtration levels tracks certification burden and feed pressure specifications. Cost compression in mid-tier configurations is intensifying because Korean and Japanese membrane suppliers command extended lead times. Municipal transit authorities exhibit lowest price sensitivity due to budgeted infrastructure allocations, whereas small commercial property managers in Indonesian urban markets demonstrate acute sensitivity to upfront capital outlays.
Supply Chain Analysis
Strategic stockpiling of reverse osmosis membranes and UV-LED driver components prevails among established equipment manufacturers confronting 14-18 month certification timelines, while just-in-inventory approaches dominate downstream distributor networks. Fabrication concentrates in South Korea, Japan, and China for membrane elements, with precision pressure vessel machining anchored in Germany and Italy. Raw material dependencies span polyamide thin-film composites, titanium dioxide photocatalytic coatings, and food-grade stainless steel housings. Single-source vulnerability concentrates in Korean specialty chemical suppliers for RO membrane substrates. Distribution runs through regional distributor networks capturing mid-scale commercial installations with local service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane replacement and calibration service contracts are expanding faster than hardware unit sales, creating a service-attach opportunity where recurring revenue multiples exceed equipment margins. This shift rewards stakeholders who consolidate aftermarket capabilities before technician scarcity hardens competitive barriers.
For Market Incumbents: Fortify captive service infrastructure through technician certification programs and regional membrane inventory positioning. Consolidate distributor relationships in Indonesian and Vietnamese corridors where informal retail networks lack technical service depth. Culligan's North American maintenance contract model and Azkoyen's European precision-service footprint illustrate defensible positioning against emerging Asian cost-optimized entrants. Priority investment in BIS IS 10500 pre-certification for Indian railway electrification corridors secures first-mover procurement advantage. For New Entrants and Emerging Players: EPA Safe Drinking Water Act fast-track certification partnerships with established testing laboratories compress 14-18 month approval cycles. White-space concentration exists in wall-mounted UV-LED configurations for Singapore and Tokyo commercial districts where real estate constraints intensify. Corporate campus subscription-based hydration passes with NFC authentication represent the most penetrable end-use segment. Go-to-market execution should anchor on third-party filtration specialist partnerships that unbundle maintenance from equipment procurement. For Investors and Strategic Acquirers: EU Drinking Water Directive PFAS detection mandates reshape the acquisition landscape toward equipment suppliers with activated carbon and RO replacement interval optimization capabilities. Five-to-ten year viability centers on recurring service revenue multiples rather than hardware shipment volumes. Target acquisition archetype: regional distributors with captive technician networks in Southeast Asian commercial corridors. Signal to watch: BIS IS 10500 certification completion rates among mid-scale fabricators as Indian railway procurement accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| UV-LED Technology Licensing | Mercury-free sterilization modules unlock 24-hour corridor deployments under REACH restrictions. |
| Backward Integration into Membrane Fabrication | In-house polyamide thin-film production mitigates Korean supplier concentration risk. |
| Railway Corridor Certification Fast-Track | BIS IS 10500 pre-approval secures platform commercialization across 7,000+ Indian stations. |
| Contactless Payment Platform Integration | NFC and QR-code modules enable subscription hydration passes in corporate campuses. |
| Regional Service Network Acquisition | Technician-scarce Southeast Asian markets reward consolidated aftermarket capabilities. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with transit authority procurement officers, commercial property managers, filtration technician service heads, membrane supplier account executives, and distributor network principals. Secondary validation drew from EPA Safe Drinking Water Act filing databases, EU Drinking Water Directive implementation reports, BIS certification registries, and customs records for RO membrane and UV-LED component trade flows. Bottom-up unit deployment estimates across Indonesian, Vietnamese, Thai, Indian, and Singaporean corridors were triangulated against top-down market value reconstruction from equipment manufacturer revenue disclosures.
Across the analysis window, projections integrate product format segmentation by freestanding, wall-mounted, tabletop, and portable configurations; filtration modality differentiation across reverse osmosis, UV-LED, carbon, and nanofiltration tiers; and end-use stratification between public transit corridors, corporate offices, fitness centers, and educational institutions. CAGRs were derived from logistic diffusion curves fitted to observed penetration rates in comparable infrastructure equipment categories. Industry-specific forecast inputs include railway electrification timelines, REACH restriction implementation phases, and corporate sustainability reporting adoption curves.
Underlying assumptions cover membrane supply continuity, certification timeline stability, and municipal procurement budget persistence, with deviation risk concentrated in PFAS detection mandate acceleration and Korean-Japanese trade policy shifts. Revision becomes warranted when UV-LED cost curves cross mercury-vapor lamp parity thresholds or when Indian railway platform commercialization delays exceed two fiscal cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
United States Energy Drink Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market