
 Non-Alcoholic Beer Market | 2026-2036
Non-Alcoholic Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Beer Market Analysis
Buyer concentration across hospitality and foodservice channels is repositioning procurement leverage toward large-format restaurant groups and stadium concessionaires. Heineken leverages its global distribution infrastructure to secure draft placements in European football venues. Athletic Brewing Company anchors its position through direct-to-consumer subscriptions and specialty retail partnerships. Carlsberg competes aggressively on price in Scandinavian supermarket chains where private-label alternatives proliferate.
Non-alcoholic beer denotes brewed beverages containing less than 0.5% alcohol by volume, typically produced through arrested fermentation, vacuum distillation, or reverse osmosis membrane filtration to preserve volatile aromatic compounds. The product serves consumers seeking sensory ritual without intoxication, spanning designated drivers, pregnant women, athletes, and medication-conscious drinkers. Lager formulations dominate volume due to scalable production and familiar flavor profiles, while ale and stout variants capture premium margins through craft positioning and limited-batch releases. Online retailers represent the fastest-growing sales channel, though supermarkets still control the majority of physical volume and promotional visibility.
Germany's BfR and the United States FDA enforce the 0.5% ABV threshold that defines non-alcoholic classification, while EU Regulation 1169/2011 mandates precise labeling of alcohol content and caloric values. These frameworks shape reformulation investments and cross-border shipment compliance costs. Stakeholders must monitor evolving low-alcohol tax classifications and minimum unit pricing schemes that could alter margin structures in key European markets.
Market Dynamics
Dealcoholization technology maturation is compressing the flavor-quality gap between alcoholic and non-alcoholic formulations, forcing incumbent breweries to accelerate R&D cycles or cede premium positioning to craft entrants. Vacuum distillation and reverse osmosis membrane advances now preserve volatile aromatic compounds previously lost in thermal processing.
Growth Catalysts
- EU Regulation 1169/2011:Mandatory alcohol content and caloric labeling has standardized transparency requirements across member states, reducing consumer skepticism and accelerating trial conversion in German and British supermarket channels.
- Foodservice channel expansion:Stadium concessionaires and large-format restaurant groups in the United States are adding dedicated draft lines, normalizing consumption occasions beyond traditional retail.
- Arrested fermentation protocols:Craft breweries in Denmark and the Netherlands deploy modified yeast strains that halt sugar-to-alcohol conversion at sub-0.5% thresholds, preserving body and mouthfeel without secondary processing.
Market Restraints
- Hop supply concentration:Pacific Northwest growers supply over seventy percent of aroma varieties to European brewers, exposing margin stability to climate volatility and irrigation cost spikes.
- Technical flavor ceiling:Reverse osmosis strips polyphenols and hop-derived bitterness compounds, requiring expensive reconstitution steps that elevate unit costs above mass-market lager equivalents.
- Cross-border tariff friction:Post-Brexit customs documentation has lengthened shipment clearance times for British craft brands entering German retail, compressing shelf-life windows and raising compliance overhead.
Strategic Opportunities
- Indian urban markets:Mumbai and Bangalore hospitality clusters show rising trial rates among health-conscious professionals, with local regulators permitting 0.5% ABV classification under FSSAI beverage standards.
- Direct-to-subscription channels:Specialty retailers in California and Texas are building recurring revenue models through curated mixed-format deliveries, bypassing slotting fee battles in conventional grocery.
- Hybrid fermentation systems:Convergence of precision bioreactor controls with AI-driven sensory profiling enables small-batch consistency at scale, opening limited-release positioning for regional breweries.
Industry Challenges
- Sensory scientist scarcity:Breweries in the United Kingdom and Germany compete for flavor chemists trained in gas chromatography-mass spectrometry analysis, slowing reformulation timelines.
- Equipment certification delays:Vacuum distillation systems require FDA and BfR compliance verification that extends procurement cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Beer Market |
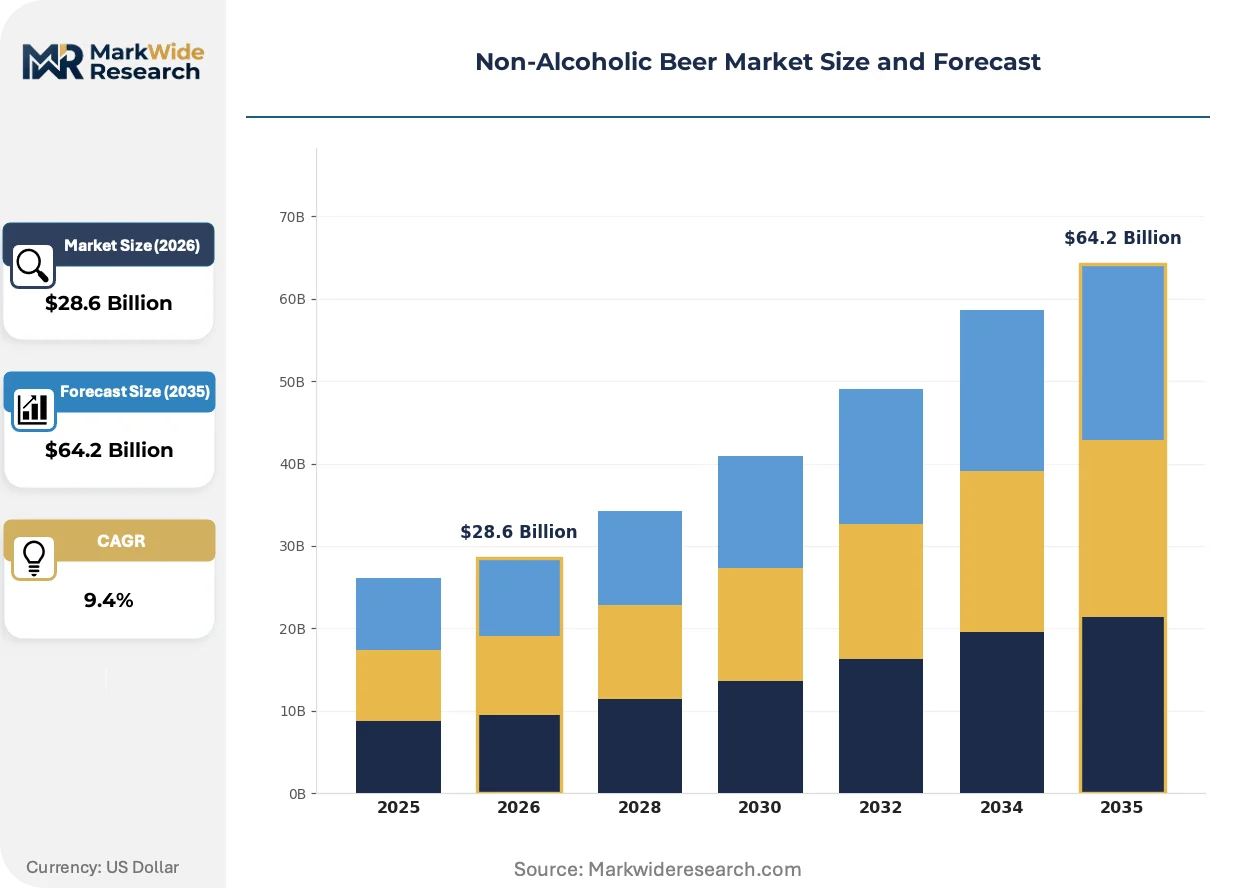
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Wheat Beer Sales Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops Packaging Type: Bottles, Cans, Kegs, Drafts Consumer Type: Health-Conscious Consumers, Non-Drinkers, Athletes, Millennials |
| Companies Covered | Guinness, Bitburger, Athletic Brewing Company, Asahi, Carlsberg, Heineken, BrewDog, Kirin, Budweiser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Beer Market Emerging Trajectories
Flavor parity engineering now dominates competitive investment, with sensory replication replacing simple alcohol removal as the technical frontier. Three developments are compressing development cycles and reshaping procurement patterns.
Membrane filtration is unifying production workflows by integrating dealcoholization with sterile filtration in single-pass systems. Mid-sized craft breweries in Bavaria and Flanders are retrofitting existing brewhouses rather than building greenfield facilities. This convergence is unifying capital deployment decisions around modular equipment upgrades rather than standalone processing lines.
REACH substance restrictions on certain hop extraction solvents are forcing European brewers to validate alternative aroma recovery methods. The industrial consequence is accelerated adoption of supercritical CO2 extraction in German and Czech production facilities. Lager-focused facilities face the steepest compliance costs, while ale specialists leverage existing dry-hopping protocols to bypass solvent-dependent processes.
Buyer concentration among stadium concessionaires and cinema chains is consolidating procurement authority into fewer decision-makers. These operators are replacing fragmented local distributor relationships with national beverage management contracts. The United States and United Kingdom exhibit the most visible consolidation, with venue operators demanding exclusive pouring rights and marketing support commitments.
Non-Alcoholic Beer Market Segmentation
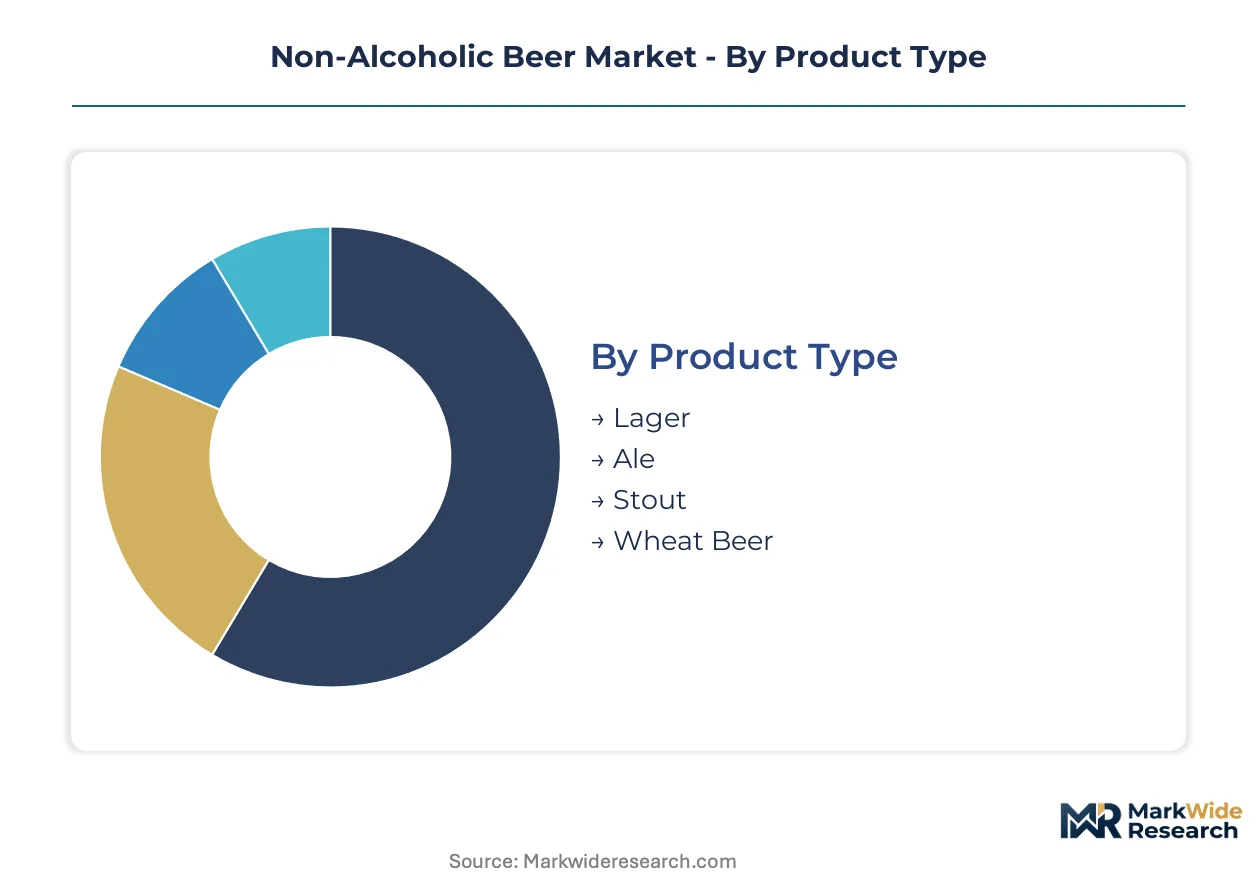
Non-alcoholic beer segmentation reveals divergent production economics and channel strategies across product formats and buyer profiles. Dealcoholization method selection, packaging durability requirements, and occasion-based consumption patterns create distinct margin structures that reward specialized positioning over mass-market replication.
Product Type:
Standardization dominates lager production while craft positioning drives ale and stout differentiation through arrested fermentation protocols and specialty malt bills.
- Lager:Brewed with bottom-fermenting Saccharomyces pastorianus strains at cooler temperatures, then subjected to vacuum distillation or reverse osmosis to achieve sub-0.5% ABV. German and United States supermarket channels concentrate volume here, with scalability pressures compressing per-unit margins below craft alternatives.
- Ale:Top-fermented at warmer temperatures using modified yeast strains that halt alcohol conversion naturally. Craft breweries in Denmark and the Netherlands exploit this pathway to preserve body without secondary processing, capturing premium shelf positioning in specialty retail.
- Stout:Roasted barley and specialty malts create flavor density that masks dealcoholization artifacts. Limited-batch releases in United Kingdom pubs and North American craft taprooms sustain price premiums through scarcity positioning.
- Wheat Beer:High protein content from malted wheat requires modified filtration protocols. Bavarian producers leverage regional Reinheitsgebot heritage to differentiate from mass-market lager alternatives.
Most installed capacity flows through Lager. Expansion is steepest in Ale.
Sales Channel:
Channel selection determines margin capture versus volume velocity, with direct relationships rewarding subscription economics and wholesale partnerships trading margin for reach.
- Supermarkets:Control majority physical volume through promotional visibility and slotting fee structures. German and British chains demand multi-SKU commitments that favor breweries with diversified product portfolios.
- Online Retailers:Curated mixed-format subscriptions in California and Texas bypass slotting battles while building recurring revenue through direct consumer relationships.
- Convenience Stores:Impulse-driven single-serve purchases concentrate in urban United States locations where chilled grab-and-go placement drives trial conversion.
- Specialty Shops:Staff-curated selections in Copenhagen and Amsterdam hospitality clusters emphasize provenance storytelling and limited releases unavailable through mass retail.
Supermarkets anchor current volume leadership. Online Retailers are climbing the fastest.
Packaging Type:
Packaging economics reflect consumption occasion fragmentation, with on-premise draft installations competing against off-premise portability requirements.
- Bottles:Amber and clear glass variants dominate German retail, with label real estate supporting regulatory compliance for ABV disclosure and caloric content under EU Regulation 1169/2011.
- Cans:Aluminum formats reduce shipping weight and enable opaque branding that signals craft authenticity. United States outdoor recreation occasions favor this format for portability and chilling efficiency.
- Kegs:Stainless steel returnable systems serve stadium concessionaires and cinema chains consolidating procurement under national beverage management contracts.
- Drafts:Dedicated tap lines in large-format restaurant groups normalize consumption occasions beyond traditional retail, with Heineken securing European football venue placements through exclusive pouring rights.
Bottles retain the largest installed base. Cans are gaining share fastest.
Consumer Type:
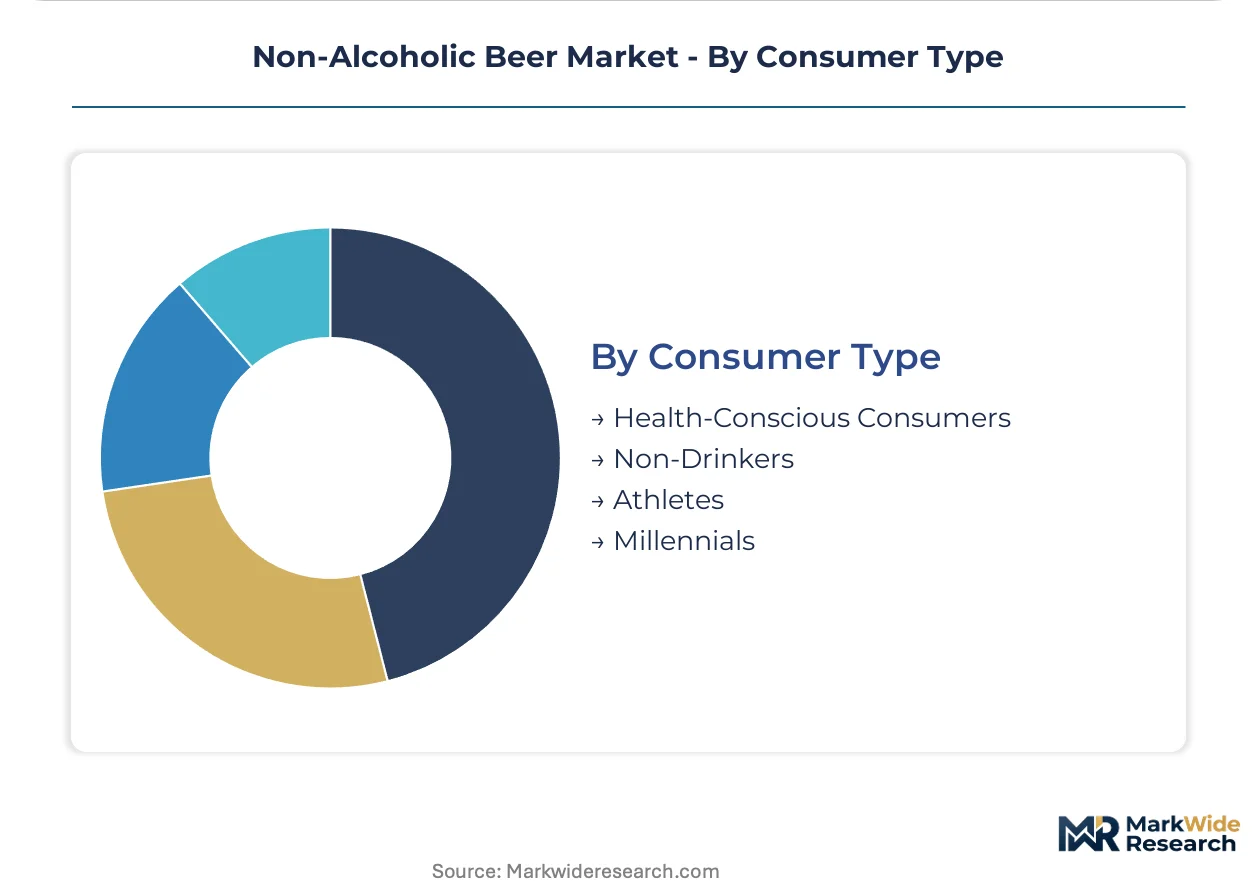
Buyer motivation splits between health optimization and social inclusion, with messaging and channel strategy diverging accordingly.
- Health-Conscious Consumers:Caloric reduction and medication compatibility drive repeat purchase. Mumbai and Bangalore hospitality clusters show rising trial rates among professionals monitoring alcohol intake.
- Non-Drinkers:Designated drivers and pregnancy-conscious buyers seek sensory ritual without intoxication. Foodservice draft normalization supports social occasion participation.
- Athletes:Post-training recovery positioning emphasizes electrolyte content and rapid rehydration. Specialty retail partnerships with fitness adjacent brands support credibility.
- Millennials:Experimentation with craft variants and willingness to pay premium for provenance storytelling. Direct-to-subscription channels capture this cohort through curated discovery models.
Health-Conscious Consumers represent the dominant current base. Millennials show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest installed production base for non-alcoholic beer, while the United States leads channel innovation through direct-to-subscription models and stadium draft normalization.
Germany
Health-conscious consumers and designated drivers sustain supermarket volume leadership. The BfR enforces the 0.5% ABV classification threshold that shapes reformulation investments. Bavarian producers in Munich and Ingolstadt leverage Reinheitsgebot heritage to differentiate wheat beer variants from mass-market lagers.
United States
Millennial experimentation and athlete recovery positioning accelerate craft ale adoption. FDA labeling requirements for alcohol content and caloric disclosure standardize transparency. California and Texas specialty retailers build recurring revenue through curated mixed-format subscription deliveries.
United Kingdom
Pub culture normalization and limited-batch stout releases capture premium margins. Post-Brexit customs documentation lengthens shipment clearance times for craft brands entering European retail. London hospitality clusters and Manchester brewery taprooms anchor domestic consumption.
India
Mumbai and Bangalore professionals monitoring alcohol intake drive rising trial rates in urban hospitality clusters. FSSAI beverage standards permit 0.5% ABV classification, enabling market entry. Karnataka and Maharashtra state regulators shape distribution licensing requirements for non-alcoholic variants.
Denmark
Craft breweries deploy modified yeast strains that halt alcohol conversion naturally, preserving body without secondary processing. REACH substance restrictions on hop extraction solvents force validation of alternative aroma recovery methods. Copenhagen specialty shops emphasize provenance storytelling for limited releases.
Non-Alcoholic Beer Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning strata. Global beverage conglomerates leverage existing distribution infrastructure and brand recognition to secure draft placements and retail shelf space. Craft specialists concentrate on arrested fermentation protocols and direct-to-consumer channels. Strategic moves center on exclusive pouring rights negotiations with stadium concessionaires and specialty retail partnership development.
Within the diversified multinational tier, Heineken and Carlsberg occupy positions anchored by global scale and existing route-to-market density. Athletic Brewing Company exemplifies the pure-play craft archetype, representing specialists who bypass conventional grocery slotting fees through subscription economics. Guinness and Bitburger sit within heritage-brand positioning, leveraging centuries-old brewing credentials to validate non-alcoholic line extensions.
| Leading Market Players |
|---|
| Guinness |
| Bitburger |
| Athletic Brewing Company |
| Asahi |
| Carlsberg |
| Heineken |
| BrewDog |
| Kirin |
| Budweiser |
| Others |
Supply Flow & Price Mechanics
Hop futures indices out of the Pacific Northwest cascade through three-tier pricing structures across premium, standard, and economy levels, with aroma variety scarcity compressing margins at the craft tier while mass-market lager producers absorb volatility through long-term contract coverage.
Pricing Analysis
Capacity additions in Bavaria and Flanders are reshaping price floors for ale variants, where arrested fermentation protocols command premium positioning against vacuum-distilled lagers. Price differentiation separates craft subscription tiers from supermarket promotional slots, with health-conscious buyers in Mumbai and Bangalore showing lowest price sensitivity. Cost compression in standard lager runs through private-label proliferation in Scandinavian chains.
Supply Chain Analysis
Direct-to-specialty-retail channels handle curated mixed-format demand in California and Texas, while national beverage management contracts serve stadium concessionaires in the United States and United Kingdom. Raw material flows draw from German maltsters, Czech Saaz hop cooperatives, and Danish yeast laboratories. Single-source vulnerability concentrates in Pacific Northwest aroma hop supply. Distribution runs through fragmented local distributors consolidating under venue operator procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Regulation 1169/2011 operates as a regulatory compounder, with mandatory alcohol content and caloric labeling standardizing transparency requirements that accelerate trial conversion across German and British retail channels.
For Market Incumbents: To counter craft entrant subscription economics, Heineken and Carlsberg should deepen exclusive pouring rights negotiations with European football venues and cinema chains, while accelerating R&D investment in membrane filtration convergence to preserve volatile aromatic compounds without secondary processing steps. For New Entrants and Emerging Players: The price-point gap between premium craft ale and economy private-label lager opens white-space targeting in Indian urban hospitality clusters and direct-to-consumer channels in Texas and California. Arrested fermentation protocols offer a technical differentiation angle for regional breweries seeking provenance positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play craft specialists possessing proprietary yeast strain libraries and established subscription infrastructure. Long-term viability over the coming decade hinges on flavor parity engineering capabilities. The signal to watch is consolidation velocity among stadium concessionaires and cinema chains as procurement authority centralizes.| Strategic Initiative | Industry Significance |
|---|---|
| Dealcoholization Technology Licensing | Membrane filtration patents enable craft breweries to bypass greenfield facility investments in Bavaria. |
| Direct-to-Consumer Channel Expansion | Subscription economics in California and Texas circumvent slotting fee battles with supermarket chains. |
| Exclusive Pouring Rights Negotiation | Heineken's European football venue placements normalize draft consumption beyond traditional retail occasions. |
| Regulatory Compliance Certification | FDA and BfR verification for vacuum distillation systems accelerates procurement cycles by four to six months. |
| Hybrid Fermentation System Deployment | AI-driven sensory profiling enables small-batch consistency at scale for limited-release positioning. |
Methodological Framework
Bottom-up foodservice channel modeling reconciled against top-down production capacity tracking forms the analytical core. Primary interviews with brewery R&D directors, stadium concessionaire procurement managers, specialty retail buyers, and sensory scientists combined with secondary validation from FDA filings, EU Regulation 1169/2011 compliance databases, BfR guidance documents, and FSSAI beverage standards. Nielsen retail audit data and customs records provided volume triangulation against bottom-up segment builds.
Input-output matrices mapped dealcoholization method selection against packaging format economics and channel margin structures across the projection horizon. Segmentation dimensions modeled include product type, sales channel, packaging configuration, and consumer motivation archetype. CAGRs derived from regression analysis against historical adoption curves in comparable beverage categories, with forecast inputs incorporating hop supply volatility indices and regulatory labeling cost assumptions.
Caveats apply where REACH substance restrictions on hop extraction solvents or post-Brexit customs documentation delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Ice Tea Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market