
 Gulf Cooperation Council (GCC) Bottled Water Market | 2026-2036
Gulf Cooperation Council (GCC) Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf Cooperation Council (GCC) Bottled Water Market Foresight
Gulf Standardization Organization (GSO) bottled water certification is reorganizing competitive access across the six member states. Masafi LLC leverages its UAE production base and long-standing retail shelf presence to sustain volume leadership in mineral water. Agthia Group PJSC anchors the Abu Dhabi market through captive distribution into government and institutional channels. Crystal Mineral Water & Refreshments LLC differentiates via specialized glass packaging for premium hospitality accounts.
Gulf Cooperation Council (GCC) bottled water comprises packaged drinking water sourced from underground springs, desalinated seawater, or municipal supplies, treated through reverse osmosis, ultraviolet sterilization, or ozonation to meet potable standards with total dissolved solids typically below 500 ppm for purified variants and 150-1500 ppm for mineral classifications. Its primary commercial purpose is delivering safe, transportable hydration in climates where ambient temperatures exceed 40°C for extended periods and piped water remains non-potable in many zones. Mineral water commands the dominant value share given consumer preference for taste profiles linked to natural source branding, while HoReCa distribution channels capture expanding margin pools as hotel construction accelerates across Riyadh and Doha. Plastic bottles retain volume dominance though regulatory pressure on single-use polymers is shifting procurement toward recyclable PET and alternative packaging substrates.
SFDA (Saudi Food and Drug Authority) and Emirates Authority for Standardization and Metrology (ESMA) enforce diverging label and quality protocols that raise compliance costs for cross-border suppliers. GSO harmonization efforts remain incomplete, forcing producers to maintain multiple product specifications. Stakeholders must monitor municipal water tariff reforms and plastic waste levies as these policy instruments reshape cost structures and channel economics faster than volume growth alone.
Market Dynamics
Gulf municipal authorities are tightening discharge rules for desalination byproducts under national environmental frameworks, forcing producers to reconfigure treatment infrastructure and source portfolios faster than volume expansion alone.
Growth Catalysts
- Desalination byproduct regulations:Saudi Arabia's tightened brine discharge standards under its National Environment Strategy are redirecting investment toward spring-sourced extraction and advanced filtration capacity.
- HoReCa channel expansion:Dubai's hotel construction pipeline and Riyadh's entertainment district developments are institutionalizing multi-year mineral water supply contracts with volume guarantees.
- Reverse osmosis efficiency gains:Energy recovery device improvements in UAE treatment plants are lowering unit production costs for purified variants competing against mineral water price premiums.
Market Restraints
- PET resin import dependency:GCC states lack indigenous polymer production, exposing bottlers to freight cost volatility and currency fluctuation against Asian supplier invoices.
- Source concentration in Hajar Mountains:Premium mineral water extraction licenses cluster in northern UAE and eastern Saudi Arabia, creating supply vulnerability to regional groundwater table depletion.
- GSO-SFDA protocol divergence:Incomplete Gulf Standardization Organization harmonization forces producers to maintain parallel label specifications and testing regimens for cross-border shipments.
Strategic Opportunities
- Oman and Kuwait underpenetration:These markets show lower bottled water per-capita consumption than UAE or Saudi Arabia, offering first-mover positioning in premium hospitality and institutional channels.
- Glass packaging regulatory tailwind:Dubai's single-use plastic reduction mandates for hotel F&B operations are creating preference shifts toward refillable glass formats for premium table service.
- Direct-to-hotel distribution platforms:Digital procurement portals connecting bottlers with procurement teams are compressing distributor margins and capturing data on consumption patterns.
Industry Challenges
- GSO certification timeline compression:New harmonized standards require simultaneous multi-market submission and extended laboratory validation, stretching quality assurance staffing.
- Legacy distributor integration:Established route-to-market relationships in Saudi Arabia's fragmented retail landscape resist disintermediation attempts by direct-ship models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf Cooperation Council (GCC) Bottled Water Market |
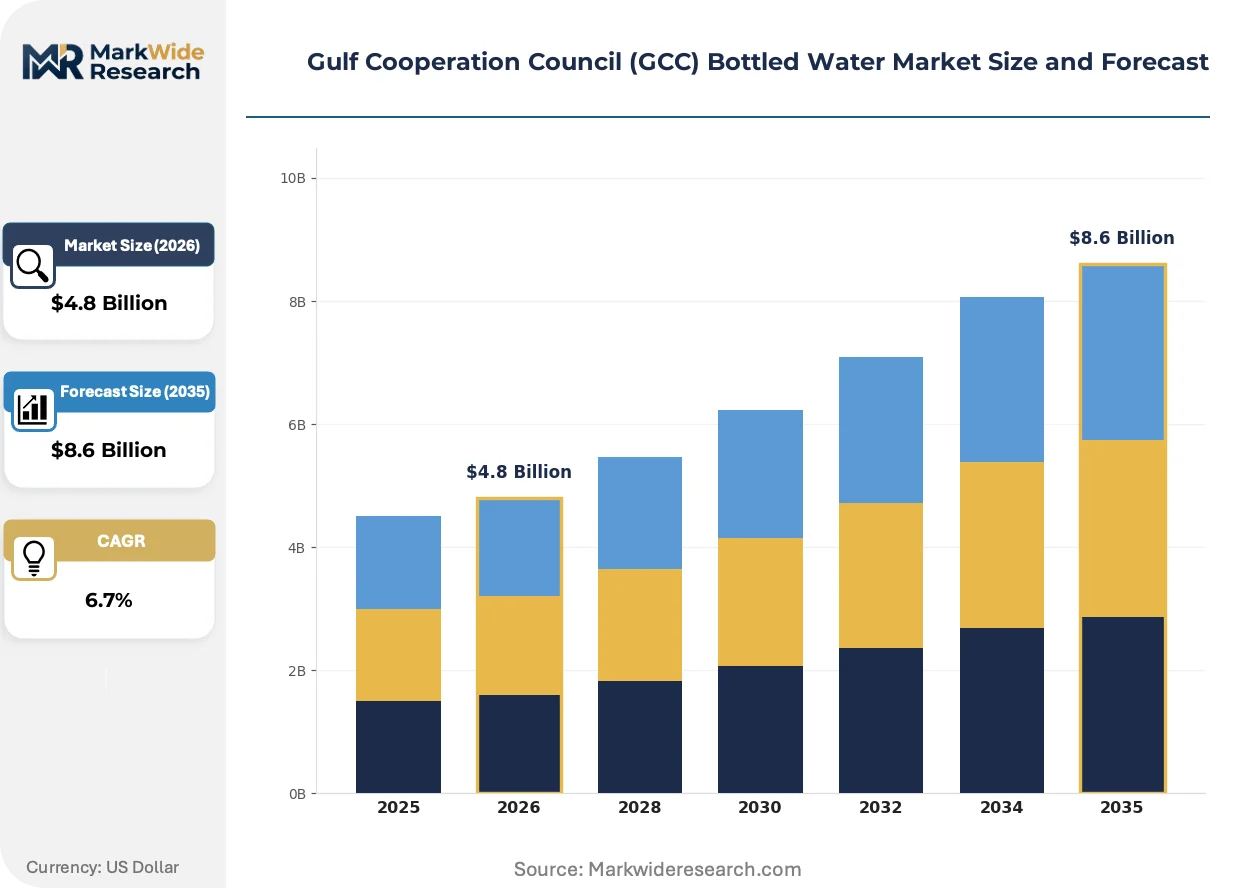
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Mineral Water, Purified Water, Sparkling Water Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Households, Offices, Restaurants, Gyms |
| Companies Covered | Masafi LLC, Crystal Mineral Water & Refreshments LLC, Nestle SA, Mai Dubai LLC, Al-Qassim Water, Danone SA, PepsiCo Inc, Al Jomaih Water and Beverages, Agthia Group PJSC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf Cooperation Council (GCC) Bottled Water Market Shifts & Advancements
Packaging material transitions and certification-driven procurement criteria are restructuring competitive advantage away from source branding alone toward demonstrable environmental compliance and supply chain transparency.
Ultraviolet-LED sterilization systems are supplanting traditional mercury-vapor UV units in treatment facilities. UAE-based producers are retrofitting existing reverse osmosis lines with UV-LED arrays to reduce energy consumption and eliminate mercury handling protocols. This technology shift is compressing operational cost differentials between large-scale desalination-derived production and smaller spring-sourced bottling operations.
SFDA and ESMA are enforcing diverging mineral content disclosure requirements that exceed baseline GSO standards. Saudi regulations mandate source aquifer geological documentation on labels, while UAE rules emphasize post-treatment mineral addition transparency. Premium hospitality buyers in Doha and Manama are now requiring dual-certification documentation to satisfy cross-border contract terms.
Hotel procurement teams are consolidating supplier relationships around multi-property framework agreements with sustainability audit requirements. Bulk volume contracts now specify recycled PET content percentages and carbon disclosure thresholds. This concentration pattern is most visible in Dubai's beachfront resort corridor, where three-property minimum commitments are displacing single-hotel spot purchasing.
Gulf Cooperation Council (GCC) Bottled Water Market Segmentation
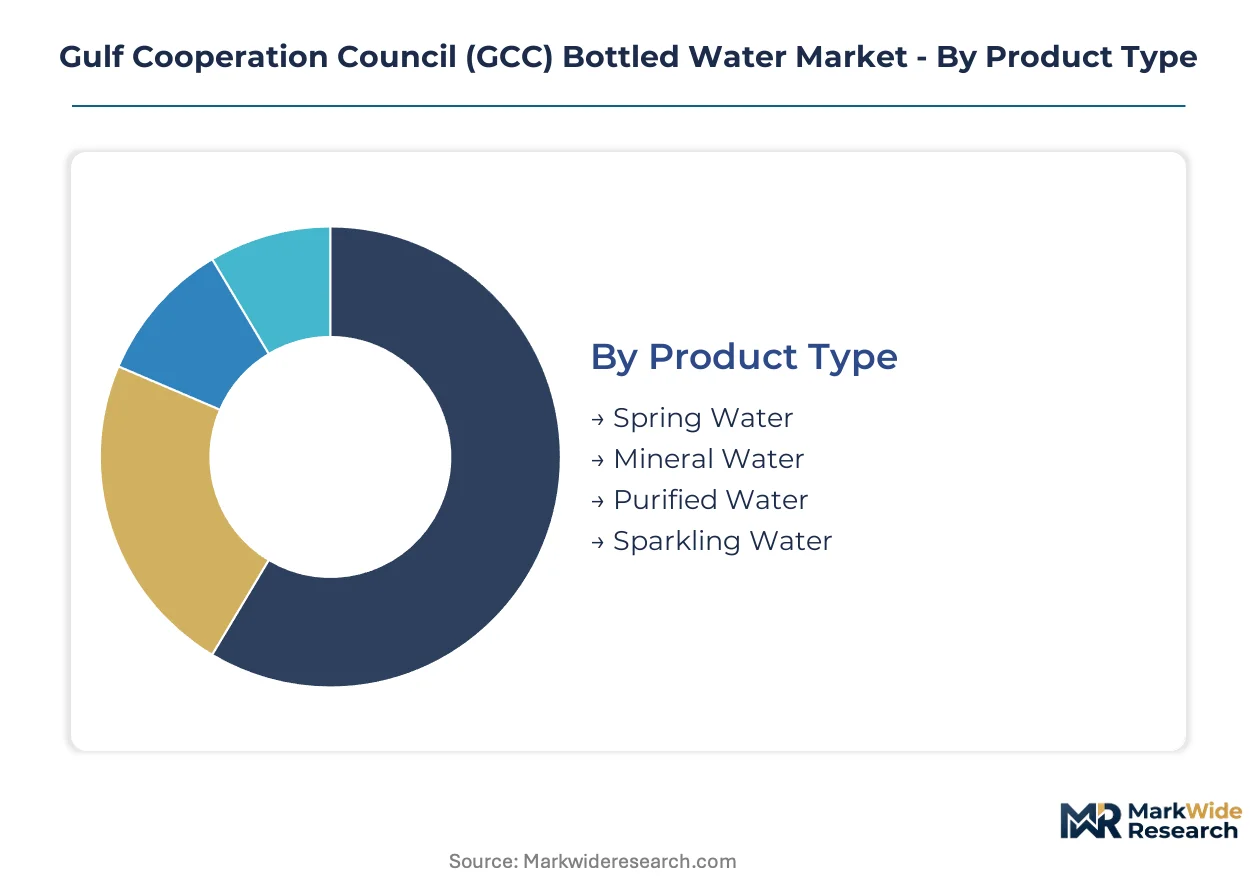
Segmentation in the GCC bottled water market reveals divergent growth vectors across product positioning and channel access. Procurement patterns in Saudi Arabia and the UAE favor premium mineral formats for hospitality contracts, while household consumption clusters around purified variants sourced from desalination infrastructure.
Product Type:
Domestic extraction dominates mineral and spring water production, concentrated in UAE's Hajar Mountains and Saudi Arabia's eastern aquifers. Purified and sparkling variants rely more heavily on desalination feedstock with cross-border distribution potential.
- Spring Water:Naturally sourced from protected underground aquifers with total dissolved solids between 150-500 ppm. Procurement teams at Dubai beachfront resorts specify spring water for premium table service, though extraction license scarcity in the Hajar Mountains constrains volume scaling.
- Mineral Water:Contains stable mineral content from geological formations, typically 150-1500 ppm TDS. Riyadh's entertainment district developments are institutionalizing multi-year supply contracts with volume guarantees, anchoring demand for branded mineral formats.
- Purified Water:Reverse osmosis-treated municipal or desalinated sources with post-treatment mineral adjustment. UAE treatment plants leverage energy recovery devices to compress production costs against mineral water premiums.
- Sparkling Water:Carbonated variants produced through injection of food-grade CO2 into purified or mineral bases. Dubai's hotel F&B operations are expanding sparkling SKUs for beverage menu differentiation.
Mineral water commands the established base. The steepest expansion runs through purified variants as reverse osmosis efficiency gains compress cost differentials.
Packaging Type:
Cost tiering separates single-use formats from reusable systems, with premium hospitality procurement driving glass adoption against retail-dominated plastic volumes.
- Plastic Bottles:Recyclable PET dominates volume across retail channels, though Dubai's single-use plastic reduction mandates for hotel F&B operations are shifting procurement specifications toward post-consumer recycled content thresholds.
- Glass Bottles:Refillable and single-serve formats command premium positioning in Doha and Manama hospitality corridors. Crystal Mineral Water & Refreshments LLC specializes in glass packaging for premium accounts, capitalizing on regulatory tailwinds.
- Tetra Packs:Aseptic carton formats for bulk institutional supply. Saudi government and institutional channels specify Tetra Pak for office and school catering contracts.
- Pouches:Flexible film formats for low-cost retail and event distribution. Convenience stores in Oman and Kuwait stock pouch formats for price-sensitive segments.
Plastic bottles retain volume leadership. Glass formats are gaining share fastest as sustainability audit requirements harden in hospitality procurement frameworks.
Distribution Channel:
Volume concentration favors retail infrastructure, while margin expansion concentrates in direct-to-institutional platforms that compress distributor layers.
- Supermarkets:Hypermarket and supermarket chains anchor household replenishment in Saudi Arabia's fragmented retail landscape. Masafi LLC leverages long-standing shelf presence to sustain volume leadership.
- Convenience Stores:High-frequency, small-format retail for immediate consumption. UAE petrol station retail and Saudi neighborhood grocery networks prioritize chilled purified SKUs.
- Online Retail:Digital platforms for bulk household subscription and corporate gifting. Direct-to-consumer models are emerging in Dubai's residential corridor for recurring delivery scheduling.
- HoReCa:Hotels, restaurants, and catering operations with framework agreement procurement. Agthia Group PJSC anchors Abu Dhabi institutional channels through captive distribution into government accounts.
Supermarkets and convenience stores represent the volume core. HoReCa channels are climbing the fastest as hotel construction pipelines in Riyadh and Doha institutionalize multi-year mineral water contracts.
End User:
Customer type segmentation maps directly to consumption occasion and price tolerance, with institutional buyers commanding volume guarantees unavailable to fragmented household demand.
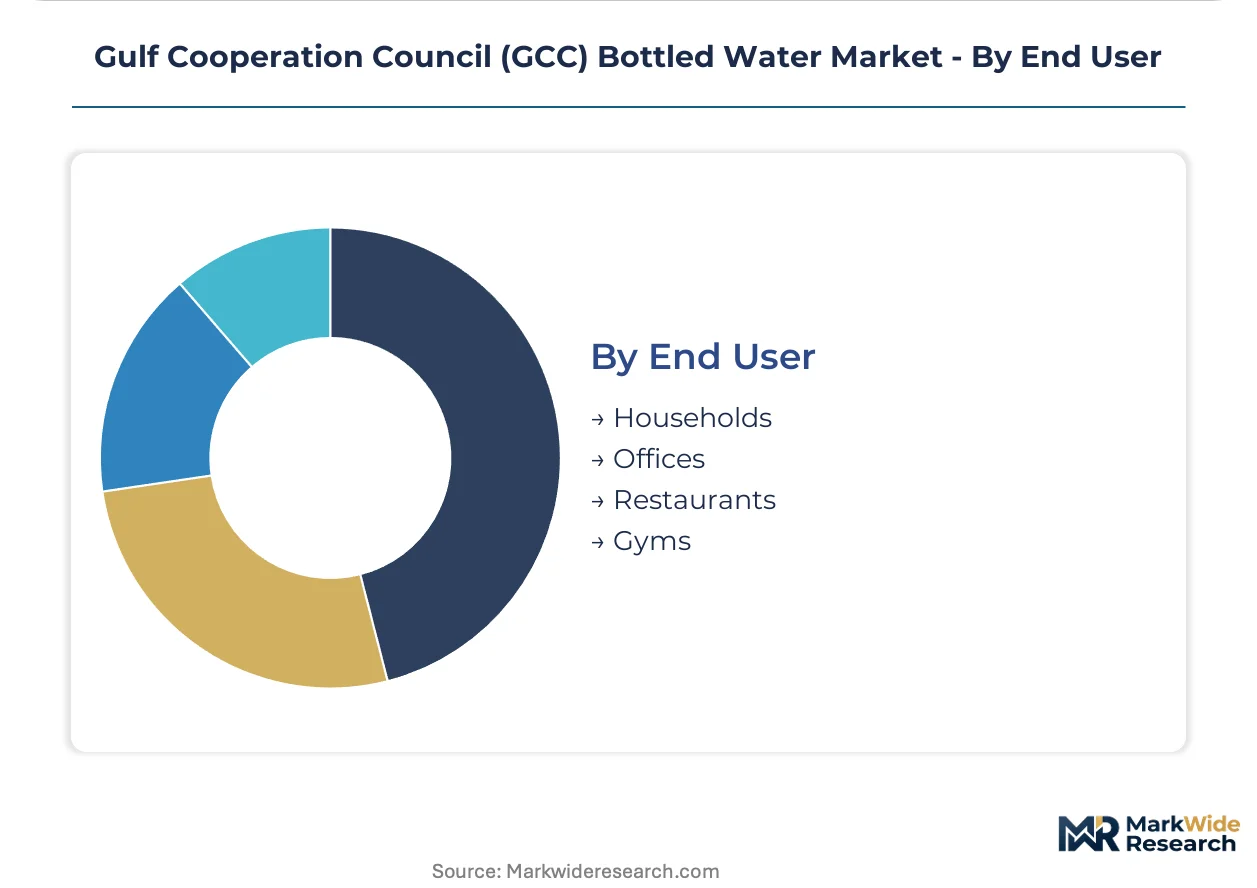
- Households:Residential consumption for daily hydration and meal accompaniment. Saudi and UAE households show per-capita consumption above Oman and Kuwait levels, driving regional volume concentration.
- Offices:Corporate catering and employee hydration programs. Dubai commercial real estate expansion is institutionalizing bulk dispenser contracts with sustainability disclosure requirements.
- Restaurants:Table service and kitchen preparation use. Premium hospitality buyers now require dual-certification documentation to satisfy cross-border contract terms between SFDA and ESMA jurisdictions.
- Gyms:Fitness center hydration and retail resale. Riyadh's entertainment district developments include wellness facility mineral water supply in master service agreements.
Households anchor the consumption base. Restaurant and hospitality procurement is expanding most quickly as framework agreements consolidate supplier relationships around multi-property commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA and ESMA regulatory divergence is fragmenting cross-border supply chains across the six member states. Bottlers must maintain parallel certification documentation and testing protocols to satisfy diverging mineral content disclosure mandates.
Saudi Arabia
Riyadh's entertainment district developments and NEOM construction are institutionalizing multi-year mineral water contracts with volume guarantees. SFDA mandates source aquifer geological documentation on labels, raising compliance costs for imported brands. The Eastern Province hosts concentrated extraction licenses around Al-Ahsa aquifers where groundwater depletion concerns are tightening extraction permits.
United Arab Emirates
Dubai's hotel construction pipeline and commercial real estate expansion are driving bulk procurement through direct-to-hotel distribution platforms. ESMA emphasizes post-treatment mineral addition transparency, diverging from Saudi protocols. Abu Dhabi's institutional channels anchor government and captive distribution networks for premium hospitality accounts.
Qatar
Doha's hospitality corridor is consolidating supplier relationships around multi-property framework agreements with sustainability audit requirements. The country's national standardization body enforces GSO baseline certification with additional local testing for mineral stability. Lusail City development is incorporating mineral water supply into master service agreements for wellness and entertainment facilities.
Kuwait
Lower per-capita bottled water consumption than UAE or Saudi Arabia offers first-mover positioning in premium hospitality channels. The national environmental authority is reviewing desalination byproduct discharge rules under regional harmonization pressure. Kuwait City's hotel F&B operations are beginning to specify recycled PET content thresholds in procurement frameworks.
Oman
Muscat's tourism development strategy is expanding institutional mineral water demand through resort and heritage site concessions. The Ministry of Commerce and Industry enforces GSO certification with extended laboratory validation timelines stretching quality assurance staffing. Salalah's hospitality corridor shows emerging demand for glass-packaged premium formats.
Gulf Cooperation Council (GCC) Bottled Water Market Competitive Landscape
Player mix skews toward integrated domestic bottlers with captive source access and multinational beverage conglomerates leveraging brand equity. Market structure concentrates around three tiers: established UAE-based mineral water specialists with Hajar Mountain extraction rights, Saudi institutional suppliers anchored in government channels, and global FMCG players importing purified variants. Competitive moves center on sustainability certification acquisition and direct distribution platform development to compress intermediary margins.
Among UAE-based specialists, Masafi LLC and Crystal Mineral Water & Refreshments LLC exemplify the source-access archetype, while Agthia Group PJSC represents the institutional-captive model through Abu Dhabi government channel penetration. Nestle SA and Danone SA occupy positions as multinational brand licensors. Mai Dubai LLC and Al-Qassim Water anchor the mid-market purified segment. PepsiCo Inc and Al Jomaih Water and Beverages exemplify diversified beverage portfolio strategies extending into hydration categories.
| Leading Market Players |
|---|
| Masafi LLC |
| Crystal Mineral Water & Refreshments LLC |
| Nestle SA |
| Mai Dubai LLC |
| Al-Qassim Water |
| Danone SA |
| PepsiCo Inc |
| Al Jomaih Water and Beverages |
| Agthia Group PJSC |
| Others |
Supply & Pricing Matrix
Reverse osmosis scale economies at UAE treatment plants compress production costs for purified variants, anchoring price floors that mineral water extraction operations in the Hajar Mountains cannot match without premium positioning. This scale asymmetry concentrates supply-side power among desalination-integrated bottlers while forcing spring-sourced competitors toward glass-packaged hospitality contracts.
Pricing Analysis
Certification level creates the primary spread between SFDA-grade mineral documentation and ESMA-compliant purified variants. Three-tier pricing structure across premium, standard, and economy levels segments by source branding, packaging substrate, and channel access. Cost compression in the purified tier stems from energy recovery device deployment at UAE desalination facilities. Household consumers in Oman and Kuwait show highest price sensitivity, while Dubai hotel procurement teams prioritize sustainability audit compliance over unit cost.
Supply Chain Analysis
Container availability on Asia-Gulf trade lanes governs PET resin inbound costs, exposing bottlers to freight volatility against Asian supplier invoices. Supply concentrates in Saudi Arabia's Eastern Province aquifers, UAE's Hajar Mountain extraction zones, and Oman's emerging tourism corridor. Raw material dependencies span imported polymer resin, food-grade CO2, and specialized glass packaging. Single-source vulnerability runs through Asian PET suppliers given absent indigenous polymer production. Distribution runs through fragmented Saudi retail networks and consolidated UAE direct-to-hotel platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
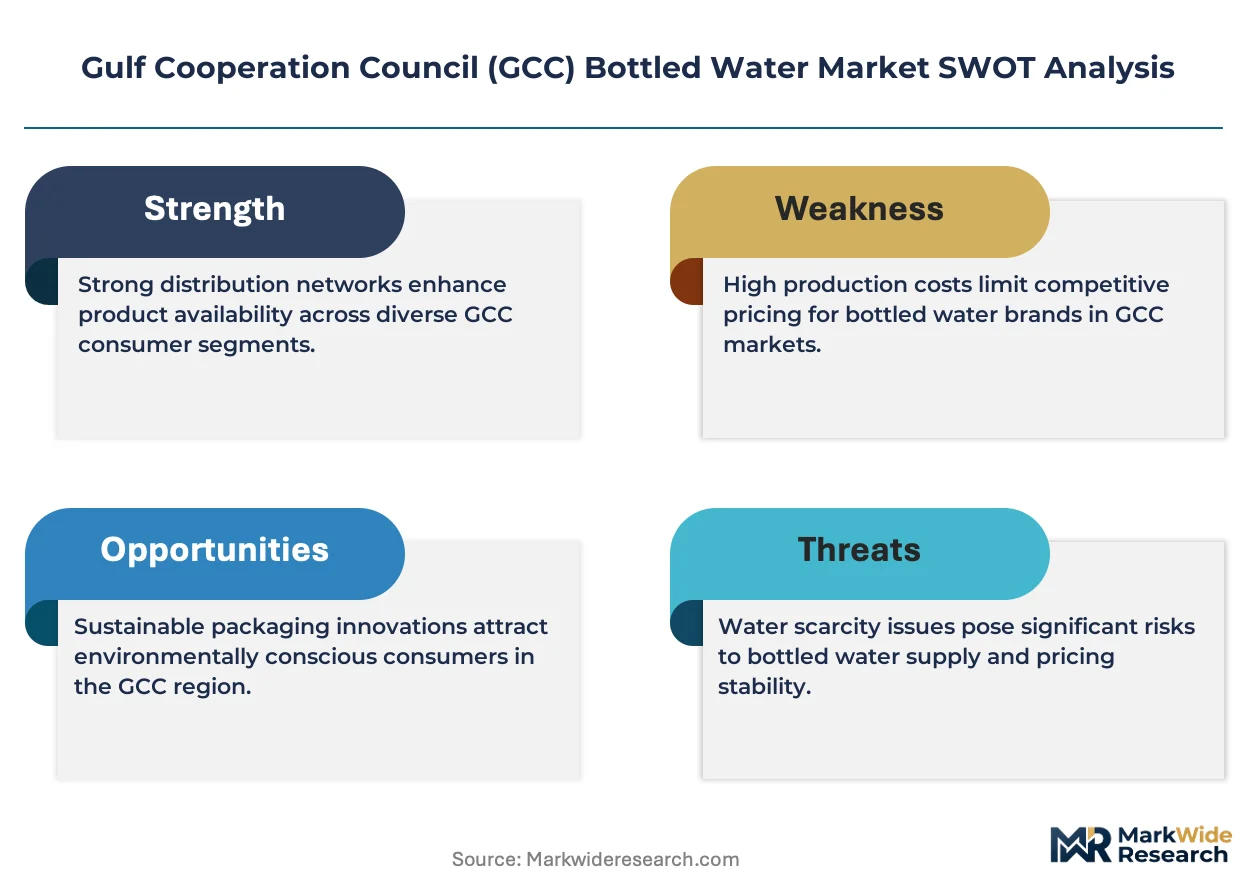
Incumbents must defend against point-of-use filtration systems and municipal piped water quality improvements that threaten core bottled volume in commercial real estate. Substitution risk intensifies as Dubai and Riyadh infrastructure investments reduce non-potable zone dependence.
For Market Incumbents: Fortify source-access moats through Hajar Mountain extraction license renewal and backward integration into desalination feedstock contracts. Secure multi-year hospitality framework agreements with volume guarantees before point-of-use filtration penetrates Dubai's hotel corridor. Certification investment in dual SFDA-ESMA documentation preserves cross-border shipment flexibility. For New Entrants and Emerging Players: Differentiate on sustainability transparency by capturing recycled PET content thresholds and carbon disclosure data that legacy distributors cannot aggregate. Target Oman's underpenetrated resort and heritage site concessions where Muscat's tourism development strategy institutionalizes mineral water demand. Direct-to-hotel digital procurement platforms offer disintermediation leverage against established route-to-market relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bottlers with UV-LED retrofit completion and glass packaging regulatory tailwinds over legacy mercury-vapor dependent operations. Long-term viability hinges on extraction license duration and municipal water tariff reform exposure. The signal to watch is GSO harmonization completion, which would compress compliance costs for multi-market operators and reshape acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Extraction License Renewal | Secures Hajar Mountain aquifer access against groundwater depletion tightening. |
| UV-LED Retrofit Completion | Eliminates mercury handling protocols and compresses operational cost differentials. |
| Dual Certification Investment | Enables cross-border hospitality contracts spanning SFDA and ESMA jurisdictions. |
| Direct-to-Hotel Platform Launch | Captures procurement data and compresses distributor margin layers. |
| Recycled PET Content Threshold | Satisfies Dubai single-use plastic reduction mandates for hotel F&B operations. |
Research Methodology
Operator-level perspectives from hospitality procurement managers, desalination plant engineers, retail category buyers, and regulatory compliance officers anchored the qualitative base. Primary interviews triangulated against customs records, GSO certification databases, municipal water tariff filings, and SEC disclosures from listed beverage conglomerates. Bottom-up volume modeling across extraction zones and top-down macro validation ensured convergence.
Sensitivity analysis tested mineral content disclosure divergence, polymer resin freight volatility, and hospitality construction pipeline delays across the analysis window. Segmentation dimensions included product type, packaging substrate, distribution channel, and end-user archetype. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections incorporated reverse osmosis efficiency curves and hotel room stock expansion.
The analysis sits within stated boundaries; outcomes outside GSO harmonization progress, groundwater extraction permit tightening, or PET resin supply stabilization would require recalibration. Forecasts reflect documented assumptions around municipal infrastructure investment and climate-driven consumption patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Flavored Water Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
China Energy- Drinks Market
Non-Alcoholic Beverages
GCC Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Iced Tea Market