
 Diet Soda Market | 2026-2036
Diet Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Diet Soda Market Analytics
Mexico's beverage manufacturing corridor is fragmenting as new low-calorie production lines compete for contract capacity. The Coca-Cola Company leverages its fountain distribution network to defend shelf presence in North American foodservice. PepsiCo anchors its position through direct-store-delivery infrastructure that reaches over 500,000 retail endpoints. Monster Beverage Corporation specializes in energy-positioned diet formulations that command premium placement in convenience channels.
Diet soda comprises carbonated soft drinks formulated with non-nutritive sweeteners such as aspartame, sucralose, or stevia derivatives, containing negligible caloric content per serving while maintaining flavor profiles comparable to full-sugar alternatives. The category serves consumers seeking reduced-calorie refreshment without sacrificing carbonation intensity or taste familiarity. Caffeinated variants dominate volume due to entrenched morning and afternoon consumption rituals, though caffeine-free offerings attract sensitivity-conscious demographics and evening consumption occasions. Sparkling formats capture the fastest growth trajectory as health-oriented consumers migrate from still beverages toward effervescent alternatives. Packaging type segmentation reveals cans gaining share in convenience and on-premise channels while multi-packs sustain household stock-up behavior in supermarket environments.
FDA guidance on added sugars disclosure and the EPA's packaging waste standards shape formulation and material choices across the industry. State-level sugar taxation proposals in California and New York create compliance complexity that favors national operators with regulatory affairs capabilities. The EU's F-Gas Regulation constrains carbonation equipment refrigerants, affecting production cost structures for European bottlers. Stakeholders must monitor sweetener safety studies and evolving municipal tax regimes to anticipate reformulation requirements and geographic demand shifts.
Market Dynamics
The FDA's updated nutrition labeling requirements and proliferating sugar-tax debates across multiple jurisdictions are compressing formulation cycles and forcing rapid sweetener diversification across the category.
Growth Catalysts
- Reformulation Incentives:State-level sugar taxation proposals in California and New York create immediate pull for zero-calorie alternatives as beverage makers pre-empt compliance costs.
- Health-Conscious Demographics:Millennials and Gen Z consumers in fitness and wellness applications normalize diet soda as a training-hydration staple rather than occasional treat.
- Carbonation Infrastructure:Expanded fountain distribution networks in North American foodservice channels embed low-calorie options into default beverage dispensers.
Market Restraints
- Sweetener Supply Concentration:Aspartame and sucralose production clusters in China and India create input vulnerability for Western bottlers facing geopolitical friction.
- Technical Limitation:Stevia derivatives retain bitter aftertaste profiles that limit complete sugar replacement in cola formulations without flavor masking investments.
- Regulatory Friction:The EU's F-Gas Regulation constrains carbonation equipment refrigerants, elevating European production cost structures relative to other regions.
Strategic Opportunities
- Underpenetrated Geography:Brazil's low-calorie beverage penetration trails the United States and Germany, presenting volume expansion potential as health positioning accelerates.
- Regulatory Tailwind:The EPA's packaging waste standards favor aluminum can formats that align with diet soda's convenience-channel strength.
- Channel Innovation:Direct-to-consumer subscription models for caffeine-free evening variants bypass traditional retail slotting constraints.
Industry Challenges
- Reformulation Talent Scarcity:Food scientists with non-nutritive sweetener stability expertise command premium compensation, constraining mid-tier brand innovation velocity.
- Certification Timeline Compression:Novel natural sweetener approvals through FDA GRAS pathways extend 18-24 months, lagging consumer preference shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diet Soda Market |
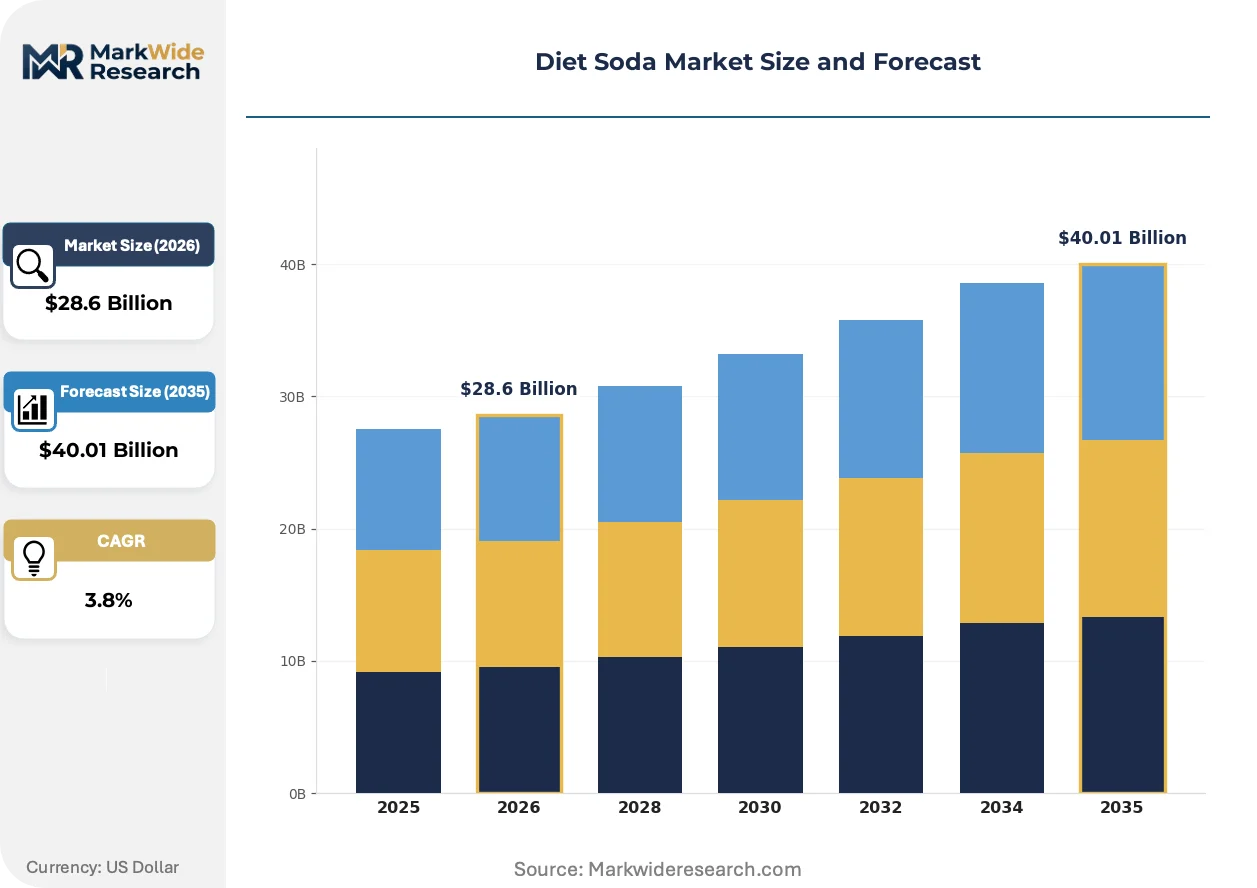
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeine-Free, Caffeinated, Sparkling, Non-Carbonated Flavor Profile: Citrus, Berry, Cola, Vanilla Packaging Type: Bottle, Can, Multi-Pack, Fountain Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops |
| Companies Covered | Nestle, Polar Beverages, The Coca-Cola Company, Refresco Group, Unilever, PepsiCo, Cott Corporation, Monster Beverage Corporation, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diet Soda Market Evolving Landscape
Digital formulation platforms and clean-label positioning are compressing product development timelines while regulatory disclosure mandates reshape competitive transparency across the category.
Artificial intelligence-driven flavor mapping is virtualizing traditional sensory panel workflows. Mid-tier beverage developers adopt machine-learning taste prediction to accelerate sweetener blending optimization. This compression of sensory validation cycles is virtualizing the historical advantage held by established brands with captive tasting facilities.
The EU's F-Gas Regulation mandates refrigerant phase-downs in carbonation equipment, forcing European bottlers toward ammonia-based or transcritical CO2 systems. Installation retrofits absorb capital that might otherwise flow to line expansion. German and French production facilities face the steepest compliance curves given their aging equipment bases.
Health-oriented consumers migrate from still beverages toward effervescent alternatives, elevating sparkling format preference above traditional cola consumption. Convenience channels capture this rotation through single-serve can placement at fitness centers and workplace micro-markets. United States metropolitan corridors exhibit the sharpest behavioral pivot, with afternoon consumption occasions shifting from coffee to caffeinated sparkling waters.
Diet Soda Market Segmentation
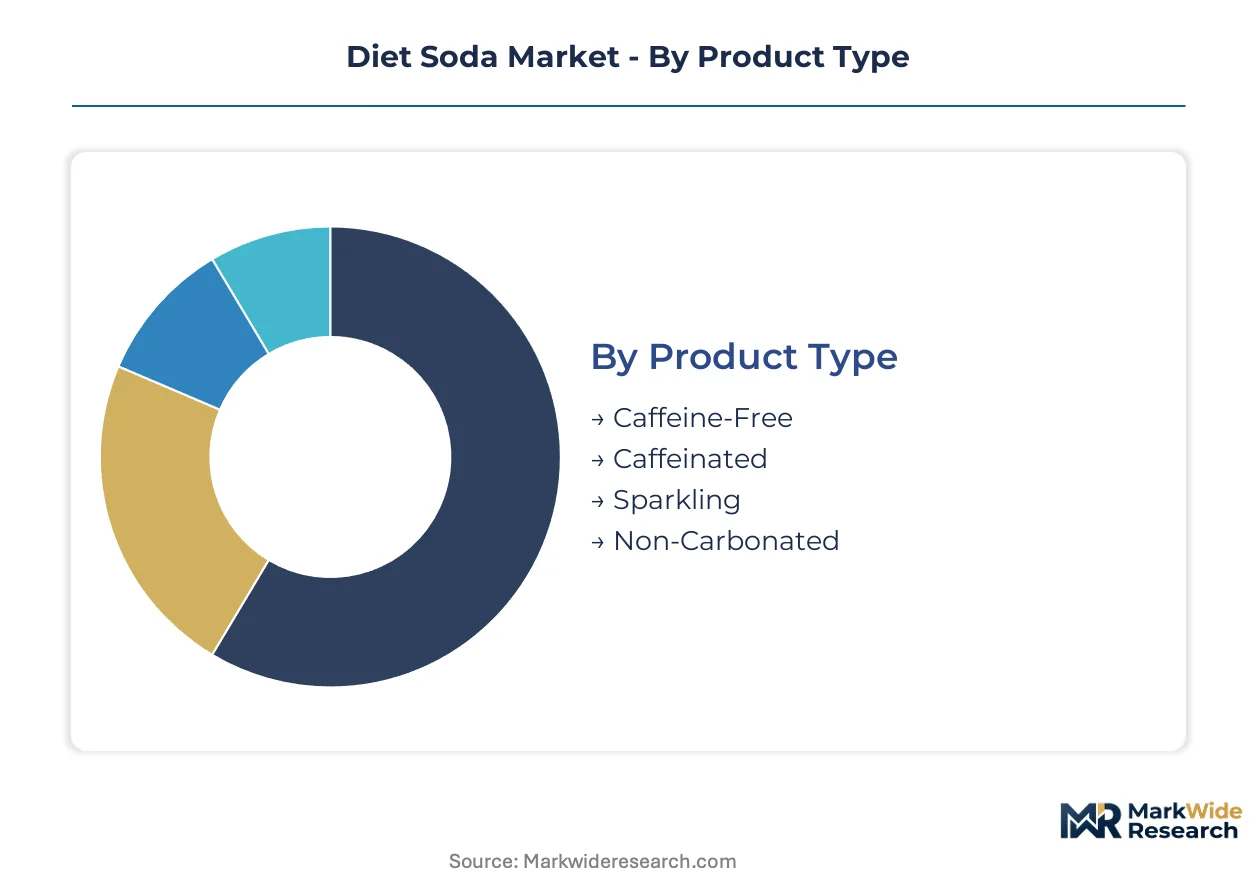
Segmentation in the diet soda category reveals distinct velocity patterns across consumption occasions and channel economics. Product turnover rates vary dramatically between ritual-driven daily purchases and episodic trial formats, reshaping inventory strategies for bottlers and retailers.
Product Type:
Caffeinated variants turn over fastest due to entrenched morning and afternoon consumption rituals, while caffeine-free and non-carbonated alternatives exhibit slower replenishment cycles tied to health-conscious planning behaviors.
- Caffeinated:Formulated with added caffeine to replicate the stimulant profile of traditional cola and coffee alternatives. Demand concentrates in United States metropolitan corridors where afternoon consumption occasions shift from coffee toward carbonated alternatives, driven by workplace micro-market penetration.
- Sparkling:Carbonated water base with non-nutritive sweeteners and natural or artificial flavoring, emphasizing effervescence over traditional cola taste profiles. United States health-oriented consumers migrate from still beverages toward this format, with fitness centers and convenience channels capturing the rotation through single-serve placement.
- Caffeine-Free:Zero-caffeine formulation targeting sensitivity-conscious demographics and evening consumption occasions. Evening consumption planning extends purchase cycles.
- Non-Carbonated:Still formulation with diet sweetener profiles, competing directly with flavored waters. Slower velocity reflects category-blurred positioning.
Caffeinated variants anchor the volume base while Sparkling gains share at the steepest rate.
Flavor Profile:
Cost tiers separate commodity cola formulations from premium-positioned fruit and vanilla variants, with ingredient sourcing economics driving margin stratification across the category.
- Cola:Caramel-colored, spice-and-citrus blended formulation replicating traditional Coca-Cola and Pepsi taste signatures. The benchmark flavor commands the largest production runs and lowest per-unit flavoring costs.
- Citrus:Lemon-lime, orange, and grapefruit-derived profiles targeting refreshment occasions. Brazil and Germany show concentration as consumers seek alternatives to cola heaviness.
- Berry:Strawberry, raspberry, and mixed berry formulations leveraging natural and artificial flavor compounds. Premium positioning in specialty channels elevates margin contribution.
- Vanilla:Creamy, dessert-oriented profile with vanilla extract or artificial vanillin. Limited edition and seasonal releases compress development timelines for novelty positioning.
Cola anchors the volume base while Citrus climbs the fastest as consumers diversify beyond traditional taste profiles.
Packaging Type:
Volume concentration separates household stock-up formats from impulse-driven single-serve economics, with channel placement dictating format prioritization for bottler capital allocation.
- Can:Aluminum single-serve container dominating convenience and on-premise channels. EPA packaging waste standards favor this format, aligning with diet soda's strength in grab-and-go occasions.
- Multi-Pack:Bundled can or bottle configurations sustaining supermarket and club-channel household replenishment. Stock-up behavior extends purchase cycles but locks in brand loyalty.
- Bottle:PET or glass container formats retaining preference in foodservice and sit-down consumption contexts. Higher per-unit cost constrains mass-market penetration.
- Fountain:Post-mix syrup dispensed through foodservice equipment, leveraging The Coca-Cola Company's network defense in North American foodservice. Capital-intensive equipment limits new entrant participation.
Can formats anchor the volume base while Multi-Pack expands most quickly as retailers optimize for household consolidation trends.
Distribution Channel:
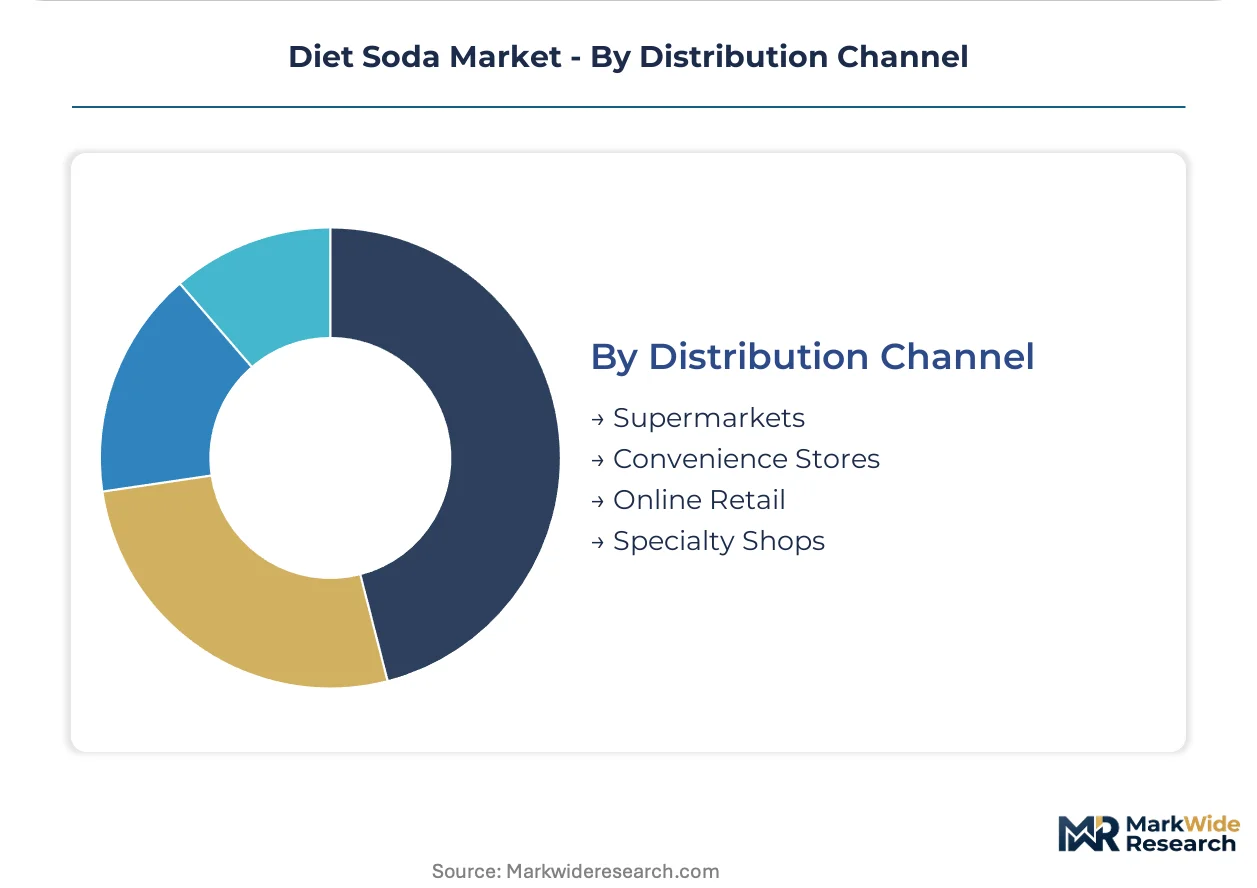
Customer type segmentation separates planned household purchasing from immediate consumption needs, with digital-native entrants disrupting traditional slotting-fee economics.
- Supermarkets:Full-assortment retail environment capturing planned purchase occasions and promotional-driven trial. PepsiCo's direct-store-delivery infrastructure reaches over 500,000 endpoints in this channel.
- Convenience Stores:Limited-assortment, high-velocity environment prioritizing single-serve cans and immediate consumption. Monster Beverage Corporation commands premium placement for energy-positioned diet formulations here.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment, enabling subscription models for caffeine-free evening variants that bypass traditional slotting constraints.
- Specialty Shops:Health-food and fitness-oriented retail emphasizing clean-label and natural sweetener positioning. Stevia-derivative formulations find disproportionate traction despite aftertaste limitations.
Supermarkets anchor the volume base while Online Retail gains share fastest as subscription mechanics reshape replenishment patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States consumers treat diet soda as a daily ritual replacement for coffee, while Brazilian and German purchasers view it as an occasional refreshment alternative to sugar-sweetened beverages.
United States
Millennial and Gen Z fitness enthusiasts normalize diet soda as training-hydration staples, driving afternoon consumption occasions away from coffee. FDA updated nutrition labeling requirements compress formulation cycles for domestic bottlers. Metropolitan corridors in California and New York exhibit the sharpest behavioral pivot toward caffeinated sparkling alternatives.
Brazil
Health-conscious urban consumers in São Paulo and Rio de Janeiro accelerate low-calorie beverage penetration from a trailing base. ANVISA regulatory frameworks govern non-nutritive sweetener approvals, creating compliance timelines that favor established multinational operators. The beverage manufacturing corridor fragments as new production lines compete for contract capacity.
Germany
EU F-Gas Regulation mandates refrigerant phase-downs in carbonation equipment, forcing bottlers toward ammonia-based systems. German production facilities face steep compliance curves given aging equipment bases. The country's central European logistics position supports distribution reach into neighboring low-calorie markets.
Mexico
Sugar-tax debates in multiple jurisdictions reshape formulation strategies for cross-border production. Mexico City's beverage manufacturing corridor fragments as new low-calorie production lines compete for contract capacity. The country's role as a North American production hub elevates regulatory scrutiny from both domestic and US trade authorities.
China
SAMR oversight of food additive safety creates extended approval pathways for novel natural sweeteners. Aspartame and sucralose production clusters concentrate input supply for Western bottlers facing geopolitical friction. Yangtze River Delta manufacturing bases supply global sweetener demand while domestic consumption of low-calorie carbonates remains nascent.
Diet Soda Market Competitive Landscape
Capability concentration sits with multinational beverage conglomerates possessing captive distribution infrastructure; scale advantage sits with diversified food and beverage groups leveraging cross-category procurement power. The market structure exhibits tiered consolidation around fountain network operators, direct-store-delivery specialists, and energy-positioned premium brands. Three archetypes dominate: infrastructure-heavy incumbents defending shelf presence through logistics density, contract manufacturers capturing overflow capacity, and niche specialists commanding convenience-channel premium placement. Competitive moves center on pre-emptive reformulation ahead of sugar-tax implementation and vertical integration into sweetener supply chains.
Among North American infrastructure-heavy incumbents, The Coca-Cola Company and PepsiCo exemplify the logistics-density archetype, with the former leveraging fountain distribution networks and the latter anchoring position through direct-store-delivery reach. Monster Beverage Corporation occupies the specialist tier, representing energy-positioned diet formulations that command premium placement in high-velocity convenience channels.
| Leading Market Players |
|---|
| Nestle |
| Polar Beverages |
| The Coca-Cola Company |
| Refresco Group |
| Unilever |
| PepsiCo |
| Cott Corporation |
| Monster Beverage Corporation |
| Keurig Dr Pepper |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta sweetener production clusters concentrate global aspartame and sucralose capacity, granting Chinese manufacturers outsized leverage over Western bottlers' input costs. This geographic concentration compresses margin flexibility for reformulation-heavy brands while amplifying pricing power for contract manufacturers with diversified sweetener sourcing.
Pricing Analysis
Price spreads between United States and German retail shelves widen during input cost spikes, with European bottlers absorbing steeper F-Gas compliance premiums. Three-tier pricing structure across premium natural-sweetener, standard aspartame-based, and economy private-label levels separates brand equity tiers. Pricing pressure stems from state-level sugar-tax proposals in California and New York, accelerating zero-calorie substitution economics. Price-sensitive private-label buyers in supermarket channels contrast with premium-insensitive fitness-center convenience purchasers.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for Western bottlers dependent on Yangtze River Delta sweetener clusters. Aspartame, sucralose, and stevia extract supply concentrates in China, India, and select Southeast Asian processing hubs. Single-source vulnerability concentrates in high-purity sucralose synthesis, where technical know-how limits qualified suppliers. Distribution runs through PepsiCo's direct-store-delivery infrastructure and Coca-Cola's fountain network, with online retail bypassing traditional slotting-fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fountain network interoperability and direct-store-delivery platform density are creating winner-take-most dynamics, with ecosystem lock-in accelerating as retailers consolidate replenishment partners.
For Market Incumbents: Build captive sweetener supply moats through backward integration into natural-sweetener extraction or long-term offtake agreements with Indian stevia processors. Pre-empt ANVISA and FDA reformulation timelines by accelerating GRAS-submission pipelines for novel sweeteners. Channel control through micro-market fountain placements defends against energy-positioned diet entrants. For New Entrants and Emerging Players: Pursue caffeine-free evening-variant subscriptions as a direct-to-consumer white space, bypassing PepsiCo and Coca-Cola shelf dominance. Brazil's trailing low-calorie penetration offers the most penetrable geography, with São Paulo health-conscious urbanites receptive to clean-label positioning. Specialty shop placement with stevia-forward formulations builds trial before supermarket slotting investment. For Investors and Strategic Acquirers: Long-term, this sits as a platform-economics play because fountain and DSD infrastructure creates compounding route-density advantages that software-enabled challengers cannot replicate. Acquisition targets should emphasize contract manufacturers with ANVISA or FDA pre-approved production lines and established natural-sweetener formulation capabilities. Monitor GRAS approval timelines for novel sweeteners as the signal for reformulation-cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses slotting-fee barriers for caffeine-free evening variants targeting wellness planners. |
| Natural Sweetener Backward Integration | Captures margin from stevia extraction and reduces dependency on Chinese aspartame clusters. |
| Fountain Network Expansion | Embeds default low-calorie placement in foodservice channels before sugar-tax implementation. |
| GRAS Pipeline Acceleration | Compresses 18-24 month novel sweetener approval timelines ahead of regulatory disclosure mandates. |
| Micro-Market Convenience Placement | Captures fitness-center afternoon consumption rotation from coffee toward caffeinated sparkling. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across beverage brand managers, category buyers at supermarket chains, fountain equipment technicians, and regulatory affairs specialists at multinational bottlers. Secondary validation drew from FDA GRAS notifications, ANVISA sweetener approvals, EPA packaging waste standards, and Nielsen retail audit data. Bottom-up volume builds by channel and format were triangulated against top-down category expenditure estimates.
Calibration against historical reformulation-cycle timing and sugar-tax implementation precedents anchored the projection framework. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel, with regional regulatory clusters as a cross-cutting variable. CAGRs were derived from trend-line extrapolation moderated by penetration ceiling analysis and per-capita consumption benchmarks. Sweetener cost trajectories and F-Gas compliance capital requirements fed industry-specific forecast adjustments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-label entrants or rapid GRAS approvals for breakthrough natural sweeteners would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market