
 Probiotic Soda Market | 2026-2036
Probiotic Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Soda Market Insights
Subscription-based replenishment services is expanding how probiotic soda reaches repeat buyers, converting single purchases into recurring revenue streams. OLIPOP leverages direct-to-consumer channels to sustain brand loyalty and capture first-party data. Poppi anchors its growth through retail placement in premium grocery chains. Health-Ade differentiates via kombucha-crossover expertise applied to soda formats.
Probiotic soda is a carbonated beverage containing live microbial cultures, typically at concentrations of one billion CFU per serving, manufactured through controlled fermentation or post-brew inoculation to deliver digestive health benefits in ready-to-drink formats. The canned segment dominates unit economics through aluminum recycling infrastructure and lower shipping weights, while fruity flavor profiles lead velocity in mainstream retail due to familiar taste mapping. Online retail channels represent the fastest-growing distribution pathway as cold-chain logistics mature for home delivery of live-culture products.
FDA oversight of live culture count claims and USDA organic certification requirements shape formulation decisions and label compliance costs for manufacturers entering the space. The EPA regulates wastewater discharge from fermentation facilities, adding environmental compliance layers to production scale-up. Stakeholders must monitor how evolving state-level sugar tax legislation intersects with probiotic health positioning to determine optimal product architecture and geographic rollout sequencing.
Market Dynamics
Cold-chain logistics maturation is compressing distribution lead times for live-culture beverages, enabling refrigerated probiotic sodas to reach retail shelves and direct-to-consumer doorsteps with viable colony counts intact. This infrastructure expansion is reshaping where manufacturers locate fermentation facilities and how they sequence geographic rollout.
Growth Catalysts
- USDA Organic Certification:Federal organic labeling requirements for processed foods create a premium tier that commands shelf price separation in mainstream grocery. Manufacturers reformulate around permitted sweeteners and fermentation inputs to qualify.
- Germany:The EU's largest beverage market demonstrates sustained per-capita consumption of functional fermented drinks, creating a demand template that export-oriented North American brands replicate in formulation and positioning.
- Post-brew inoculation:This manufacturing process allows precise CFU dosing at packaging rather than relying on fermentation variability, improving batch consistency and reducing spoilage rates in aluminum can formats.
Market Restraints
- Aluminum tariff volatility:Input cost swings for beverage-grade can sheet compress margin structures, particularly for mid-tier brands without long-term supply contracts or captive recycling streams.
- Live-culture stability:Temperature excursions above 8°C degrade viable probiotic counts, limiting distribution radius from production facilities and excluding ambient retail channels.
- EPA wastewater discharge:Fermentation facility scale-up triggers Clean Water Act permitting requirements that extend construction timelines and add environmental compliance overhead.
Strategic Opportunities
- Japan:METI's functional foods framework permits specific digestive health claims for verified probiotic strains, offering a regulatory pathway unavailable in US markets where FDA restricts disease-related assertions.
- Subscription replenishment:Direct-to-consumer auto-ship models convert trial purchases into predictable revenue while capturing consumption-velocity data for flavor development.
- Kombucha crossover expertise:Fermentation specialists with existing cold-chain relationships and live-culture handling capabilities can extend into soda formats with lower pH tolerance requirements.
Industry Challenges
- Microbiology talent scarcity:Commercial-scale probiotic strain selection and shelf-stability testing require specialized fermentation scientists, a skill set concentrated in dairy and pharmaceutical sectors.
- State sugar tax fragmentation:Beverage excise regimes in California, Colorado, and Philadelphia impose varying thresholds and rates, complicating national pricing architecture and label compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Soda Market |
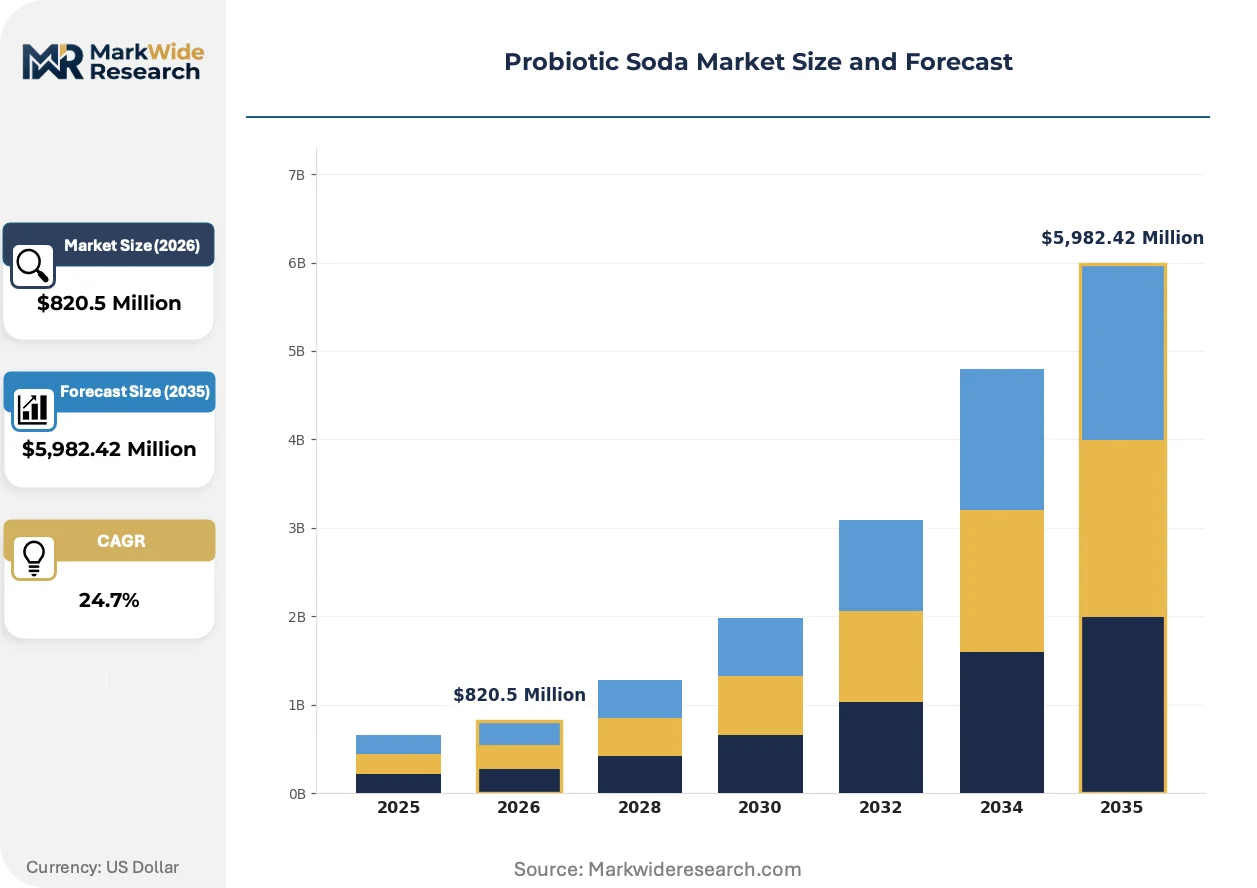
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $5,982.42 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Bottled, Draft, Powdered Flavor Profile: Fruity, Spicy, Herbal, Citrus End User: Health Conscious Consumers, Athletes, Gluten Intolerant Individuals, Beverage Enthusiasts Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | OLIPOP, Poppi, Health-Ade, Coca-Cola, PepsiCo, KeVita, Humm Kombucha, Culture Pop Soda, LIVE Soda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Soda Market Trends and Innovations
Refrigerated beverage infrastructure is expanding beyond traditional dairy channels, creating new points of distribution for live-culture products. Manufacturers are adapting formulation and packaging to exploit these emerging cold-chain pathways.
Encapsulation technology for probiotic strains is absorbing shelf-stability limitations that previously constrained distribution geography. Beverage manufacturers in the United States are licensing pharmaceutical-grade microencapsulation processes to extend viable CFU counts through ambient temperature excursions. This absorption of protection technology is compressing the capital requirements for regional production scale-up.
REACH chemical registration requirements in the European Union are tightening scrutiny of flavor compounds and processing aids used in fermented beverages. Manufacturers exporting to Germany and France must document substance safety profiles, adding formulation review cycles. The natural flavor segment faces the steepest compliance burden as botanical extracts fall under expanded hazard classification protocols.
Buyer concentration among premium grocery banners is compressing supplier negotiation leverage for emerging probiotic soda brands. Whole Foods Market and Sprouts Farmers Market collectively control refrigerated functional beverage placement in the United States, extracting slotting fees and promotional commitments. This channel consolidation is most visible in coastal metropolitan markets where independent natural retailers have exited.
Probiotic Soda Market Segmentation
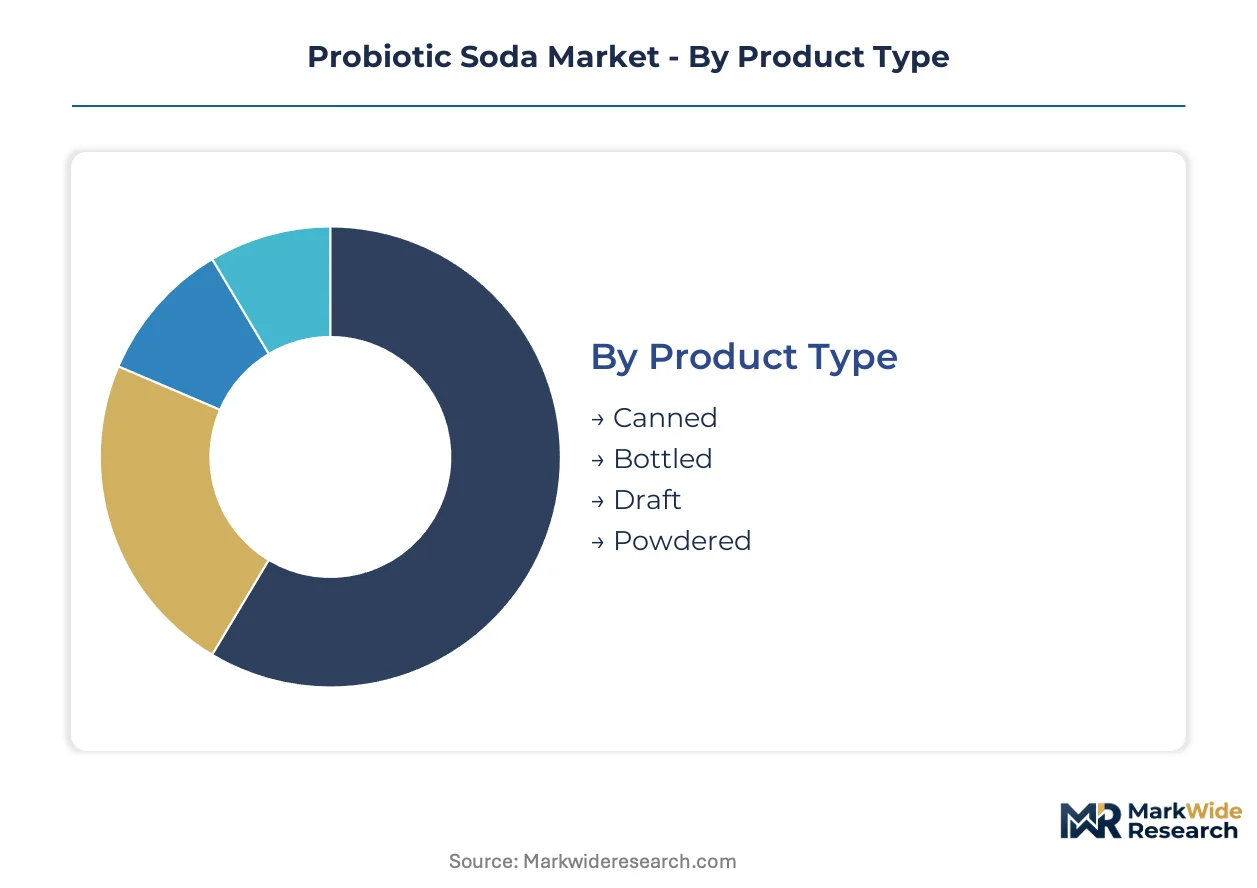
Probiotic soda manufacturers navigate four distinct segmentation dimensions that determine formulation priorities, cold-chain requirements, and channel economics. Each dimension carries implications for viable CFU preservation, flavor stability, and retail placement strategy.
Product Type:
Standalone formats dominate refrigerated distribution infrastructure, while embedded powder systems require consumer reconstitution and ambient shelf stability.
- Canned:Aluminum formats leverage established recycling infrastructure and reduced shipping weights. Demand concentrates in United States mass retail where refrigerated beverage sets accommodate live-culture requirements. Cold-chain maturation in Texas and Florida distribution hubs enables regional manufacturer scale-up.
- Bottled:Glass and PET containers support premium positioning through visual clarity and resealability. Health food stores in California and New York drive velocity for glass formats where deposit-return systems operate. UV-resistant amber glass commands price separation for light-sensitive probiotic strains.
- Draft:Keg-dispensed formats serve foodservice accounts and on-premise wellness venues with high-turnover consumption patterns.
- Powdered:Sachet and tub formats bypass cold-chain constraints entirely, targeting travel and workplace consumption occasions.
Volume placements concentrate in Canned; the faster expansion belongs to Powdered.
Flavor Profile:
Cost tier stratification separates commodity fruit blends from premium botanical extractions requiring REACH-compliant documentation for EU export.
- Fruity:Berry, tropical, and orchard fruit combinations deliver familiar taste mapping that reduces trial barriers. Supermarkets in Illinois and Ohio generate highest velocity for strawberry and mixed-berry variants. FDA natural flavor labeling requirements shape sweetener selection for these mainstream SKUs.
- Citrus:Lemon, lime, and grapefruit profiles align with sports hydration positioning and electrolyte fortification. Athletes in Arizona and Colorado drive repeat purchase rates for citrus-forward formulations with lower residual sugar.
- Spicy:Ginger, turmeric, and cayenne variants target digestive health positioning with functional ingredient density.
- Herbal:Botanical infusions face steepest EFSA novel food scrutiny when exported to Germany and France.
Mainstream penetration clusters in Fruity; Herbal claims the steepest expansion trajectory.
End User:
Application context determines CFU dosing levels, with therapeutic users requiring higher colony counts than casual wellness consumers.
- Health Conscious Consumers:Primary demand segment seeking digestive wellness and reduced-sugar alternatives to conventional soda. Subscription replenishment models in Washington and Oregon capture this cohort through direct-to-consumer auto-ship. USDA organic certification commands price premiums among this user base.
- Gluten Intolerant Individuals:Celiac and non-celiac gluten sensitive consumers require certified gluten-free fermentation inputs. Specialty shops in Massachusetts and Minnesota maintain dedicated shelf sets for third-party verified formats.
- Athletes:Performance-oriented users prioritize electrolyte synergy and rapid gastric emptying for training recovery.
- Beverage Enthusiasts:Flavor-driven explorers seeking novel fermentation profiles and limited releases.
Core volume resides with Health Conscious Consumers; Beverage Enthusiasts demonstrate the fastest share gain.
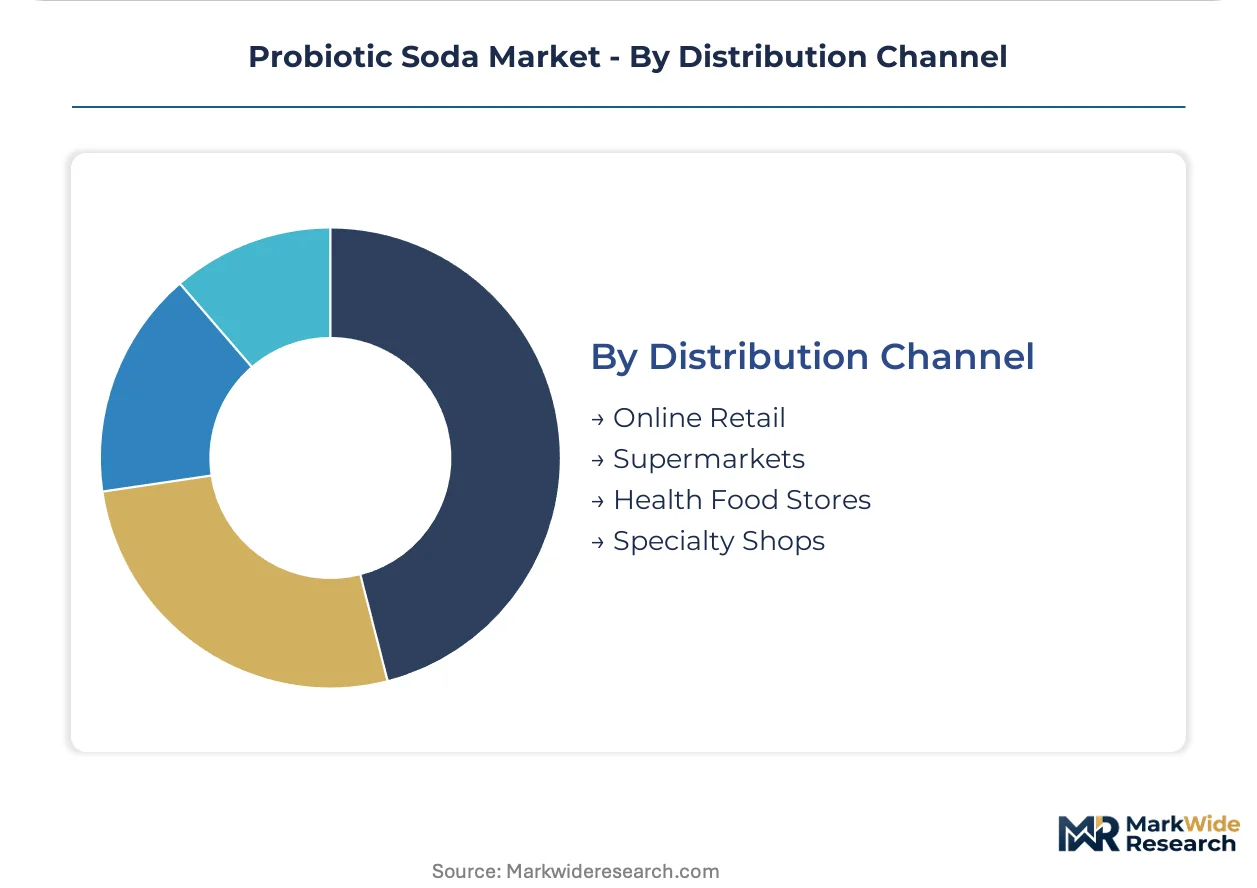
Distribution Channel:
Customer type fragmentation separates mass-market velocity from premium relationship-based retail requiring education-intensive sell-through.
- Online Retail:Direct-to-consumer and third-party marketplace channels represent the fastest-climbing pathway as cold-chain logistics mature for residential delivery. Amazon Fresh and Thrive Market operations in California and New York enable viable CFU preservation through last-mile refrigerated transport.
- Supermarkets:Kroger, Albertsons, and Publix banner placement demands slotting fee commitments and promotional velocity guarantees. Buyer concentration in this channel compresses supplier negotiation leverage for emerging brands.
- Health Food Stores:Independent and regional chains provide education-intensive environments for live-culture product trial.
- Specialty Shops:Fermentation-focused retailers and wellness boutiques support premium pricing for small-batch formats.
Transaction volume aggregates in Supermarkets; Online Retail posts the sharpest growth slope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors refrigerated beverage innovation through its concentration of cold-chain logistics startups and proximity to premium grocery headquarters. The metropolitan area hosts fermentation pilot facilities and direct-to-consumer fulfillment centers that supply probiotic sodas across the western United States.
United States
Health-conscious consumers in Washington and Oregon drive subscription replenishment adoption through direct-to-consumer auto-ship models. FDA labeling requirements for live culture counts reshape formulation standards nationwide. Texas and Florida distribution hubs enable regional manufacturer scale-up through maturing cold-chain infrastructure.
Germany
Sustained per-capita consumption of functional fermented drinks creates a demand template that export-oriented brands replicate. EFSA novel food scrutiny applies to botanical extracts used in herbal flavor variants. The Rhine-Ruhr metropolitan region concentrates beverage distribution infrastructure serving northern European markets.
Japan
METI's functional foods framework permits specific digestive health claims for verified probiotic strains unavailable in US markets. Tokyo and Osaka metropolitan areas host retail channels accustomed to premium-priced functional beverages. Regional manufacturers leverage existing kombucha expertise to extend into lower-pH soda formats.
United Kingdom
London's premium grocery concentration drives placement negotiations for refrigerated functional beverage sets. REACH chemical registration requirements tighten scrutiny of flavor compounds imported from North American suppliers. The Southeast England logistics corridor supports cold-chain distribution for live-culture products entering European markets.
Canada
Health Canada regulations govern probiotic health claims and strain-specific efficacy requirements for products sold domestically. Toronto and Vancouver metropolitan areas concentrate demand for organic-certified functional beverages. Provincial deposit-return systems in British Columbia and Ontario influence packaging format selection for glass and aluminum containers.
Probiotic Soda Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the probiotic soda landscape. The market structure fragments between fermentation specialists with captive cold-chain relationships and beverage conglomerates leveraging existing distribution scale. Three archetypes dominate: kombucha-crossover specialists, direct-to-consumer native brands, and diversified beverage multinationals. Competitive moves concentrate on retail slotting fee commitments and geographic expansion sequencing rather than manufacturing capacity races.
Within the direct-to-consumer native tier, OLIPOP and Poppi exemplify asset-light brand building through subscription replenishment and premium grocery placement respectively. Health-Ade occupies a position bridging kombucha heritage with soda format adaptation. These three companies anchor the emerging competitive structure as fermentation specialists and beverage conglomerates evaluate entry timing against cold-chain infrastructure maturation.
| Leading Market Players |
|---|
| OLIPOP |
| Poppi |
| Health-Ade |
| Coca-Cola |
| PepsiCo |
| KeVita |
| Humm Kombucha |
| Culture Pop Soda |
| LIVE Soda |
| Others |
Pricing and Supply Chain Analysis
Premium grocery banner concentration in coastal metropolitan markets compresses supplier negotiation leverage and enforces slotting-fee-driven pricing architectures for emerging probiotic soda brands. Whole Foods Market and Sprouts Farmers Market extract promotional commitments that reshape margin structures and force tiered positioning strategies.
Pricing Analysis
USDA organic certification anchors value-based pricing premiums that separate certified tiers from conventional formulations in refrigerated beverage sets. Price differentiation rests on live-culture count verification and cold-chain integrity guarantees rather than commodity input costs. Pricing pressure stems from aluminum tariff volatility compressing margin structures for mid-tier brands without captive recycling streams. Health-conscious consumers in Washington and Oregon demonstrate lowest price sensitivity, while mass-market trial buyers in Illinois and Ohio require promotional depth for conversion.
Supply Chain Analysis
Aluminum can recycling flows through established beverage-grade reclamation infrastructure in the United States, Germany, and Japan, enabling closed-loop material recovery for probiotic soda packaging. Raw material dependencies center on fermentation feedstocks, probiotic strain cultures, and natural flavor extracts. Supply chain risk concentrates in single-source vulnerability for pharmaceutical-grade microencapsulation technology licensed from pharmaceutical sectors. Distribution runs through maturing cold-chain logistics networks connecting Texas and Florida production hubs to premium grocery refrigerated sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around brands with captive cold-chain relationships and subscription replenishment infrastructure, as live-culture stability requirements and slotting fee burdens force undercapitalized entrants toward private-label servitude or exit.
For Market Incumbents: To counter aluminum tariff volatility and compressed margin structures, deepen backward integration into captive can recycling streams and secure long-term supply contracts for beverage-grade sheet. Reinforce channel control through exclusive refrigerated set placements in premium grocery banners, converting slotting fee investments into shelf-space moats against emerging competitors. For New Entrants and Emerging Players: Direct-to-consumer auto-ship models offer the most penetrable route for building first-party data and recurring revenue without slotting fee burdens. Target powdered format development for ambient distribution channels that bypass cold-chain infrastructure requirements. White-space opportunity concentrates in workplace and travel consumption occasions where reconstitution convenience outweighs ready-to-drink immediacy. For Investors and Strategic Acquirers: The window for entry favors kombucha-crossover specialists with existing fermentation expertise and live-culture handling capabilities. Long-term viability hinges on acquisition targets demonstrating viable CFU preservation through encapsulation technology or regional cold-chain density. Monitor EPA wastewater discharge permitting timelines as inflection indicators for production scale-up feasibility and facility location economics.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Subscription replenishment captures first-party data and converts trial to recurring revenue in Washington and Oregon. |
| USDA Organic Certification Investment | Federal labeling requirements enable price separation in Whole Foods Market and Sprouts Farmers Market refrigerated sets. |
| Encapsulation Technology Licensing | Pharmaceutical-grade microencapsulation extends viable CFU counts through ambient temperature excursions. |
| Cold-Chain Distribution Partnership | Amazon Fresh and Thrive Market refrigerated transport enables last-mile live-culture preservation in California and New York. |
| Powdered Format Development | Sachet and tub formats bypass cold-chain constraints entirely for travel and workplace consumption occasions. |
Research Methodology
Trade association filings, customs records, and Nielsen retail audit data formed the secondary backbone for volume and value estimation. Primary interviews with fermentation facility operators, premium grocery category buyers, cold-chain logistics providers, and probiotic strain suppliers validated secondary findings. Bottom-up and top-down triangulation reconciled production capacity estimates with point-of-sale velocity data across distribution channels.
Bottom-up modeling aggregated facility-level production capacity and capacity utilization rates across fermentation installations in Texas, Florida, and California. Segmentation dimensions included product format, flavor profile, end-user archetype, and distribution channel. CAGRs derived from trend extrapolation of live-culture beverage adoption rates and cold-chain infrastructure investment patterns. Forecast inputs incorporated FDA labeling requirement compliance costs and EPA wastewater discharge permitting timelines.
The model holds under continued cold-chain infrastructure maturation and stable aluminum input costs; deviation in tariff regimes or temperature excursion tolerance breakthroughs would shift geographic rollout sequencing and format mix. Practitioners should monitor encapsulation technology licensing agreements and state-level sugar tax legislation for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Non-Alcoholic Malt Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market