
 Global Nonalcoholic Beverage Market | 2026-2036
Global Nonalcoholic Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nonalcoholic Beverage Market Intelligence
The proliferation of functional beverages with enhanced nutritional profiles is redrawing the boundaries of traditional drink categories. PepsiCo, Inc. leverages its extensive distribution network to introduce new functional lines alongside its core carbonated drinks. Nestlé S.A. differentiates through its strong position in bottled water and health science-oriented drink formulations. Meanwhile, Danone S.A. specializes in dairy alternatives and probiotic-infused products, targeting specific consumer wellness needs.
Nonalcoholic beverages are commercially prepared liquids intended for human consumption that contain either zero alcohol or a legally defined trace amount, typically below 0.5% alcohol by volume. Production involves processes like pasteurization, carbonation, or aseptic filling to ensure shelf stability and safety. While carbonated drinks and bottled water form the market's volume base, functional beverages represent the fastest-growing product type. The ready-to-drink tea and dairy alternatives segments offer higher margin potential, driven by premium and natural ingredients.
Regulations such as the US FDA's standards for nutrient content claims and the EU's EFSA guidelines on health claims directly influence product formulation and marketing. In China, SAMR's enforcement of GB standards for food additives and labeling governs market access for all beverage categories. Navigating these divergent international labeling requirements for sugar, caffeine, and functional ingredients is a critical strategic decision for brand expansion.
Market Dynamics
The central dynamic shaping the nonalcoholic beverage market is the consumer-driven push for functional health benefits, which is fragmenting mass-market categories and creating premium niches. This force compels producers to balance scientific formulation with clean-label ingredient sourcing across their portfolios.
Growth Catalysts
- Sustainable Packaging Mandates:Regulations like the European Union's CSRD are accelerating the transition from traditional plastics to advanced cartons and recycled materials, appealing to environmentally conscious consumer segments.
- Demand for Functional Ingredients:A focus on wellness and preventative health, particularly among urban populations in China and India, fuels expansion for beverages enhanced with probiotics, vitamins, and botanicals.
- Advanced Processing Technology:Aseptic filling and high-pressure processing (HPP) technologies enable the production of premium, preservative-free beverages with extended shelf life, supporting the growth of natural juice and dairy alternative segments.
Market Restraints
- Input Cost Volatility:Fluctuation in global prices for key agricultural commodities, including sugar, coffee beans, and fruit concentrates, creates significant margin pressure and complicates long-term financial planning for manufacturers.
- Divergent Labeling Regulations:Navigating conflicting international rules, such as the US FDA's nutrient content standards versus the EU's EFSA health claim guidelines, creates compliance burdens and slows cross-border product rollouts.
- Cold Chain Infrastructure Gaps:The distribution of perishable products like cold-pressed juices and certain probiotic drinks depends on an unbroken, energy-intensive cold chain, limiting market access in regions with less developed logistics.
Strategic Opportunities
- Plant-Based Category Expansion:Significant opportunity exists in developing and marketing novel plant-based dairy alternatives beyond soy and almond, targeting consumers with specific dietary needs or taste preferences in North America and Europe.
- Direct-to-Consumer Personalization:The convergence of e-commerce platforms and data analytics allows for the creation of subscription services offering personalized nutritional beverage plans tailored to individual health goals and preferences.
- Untapped Food Service Channels:Expanding the availability of functional and premium nonalcoholic options within corporate cafeterias, healthcare facilities, and educational institutions opens a new, high-volume B2B revenue stream.
Industry Challenges
- Traceability of Niche Ingredients:Sourcing and verifying the authenticity and quality of specialized botanicals and functional additives from a fragmented global supplier base poses a significant supply chain management challenge.
- Health Claim Substantiation:The rigorous, time-consuming, and costly process of conducting clinical trials to substantiate health claims for functional beverages, as required by regulators like the EFSA, is a major barrier to innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nonalcoholic Beverage Market |
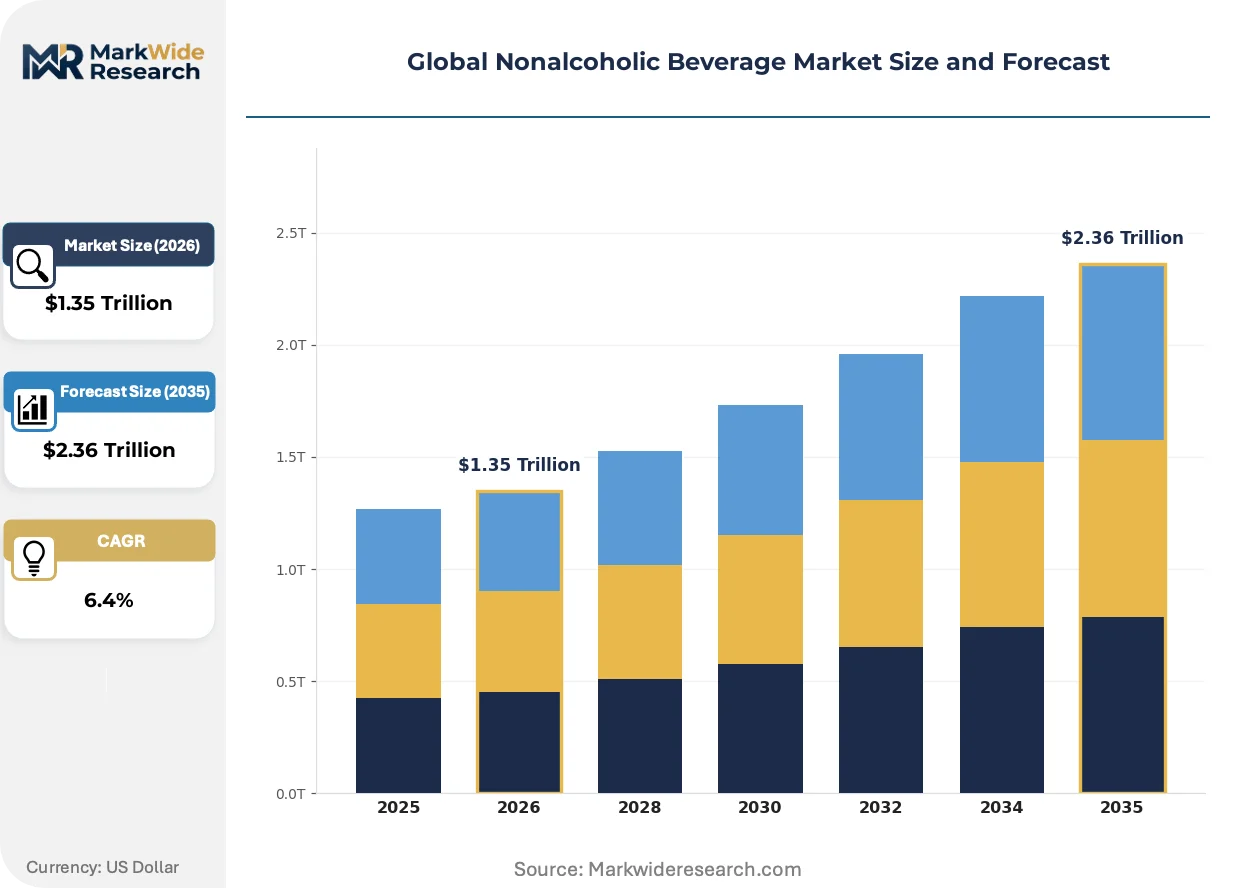
| Market Size in 2026 | $1.35 Trillion |
| Market Size in 2035 | $2.36 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated Drinks, Juice Drinks, Bottled Water, Functional Beverages, Ready-to-Drink Tea, Dairy Alternatives Packaging Type: Plastic Bottles, Glass Bottles, Aluminum Cans, Tetra Pak, Cartons, Pouches Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Foodservice Channels, Specialty Stores, Direct Sales Consumer Age Group: Children, Teenagers, Adults, Seniors, Young Professionals |
| Companies Covered | The Coca-Cola Company, PepsiCo, Inc., Nestlé S.A., Keurig Dr Pepper Inc., Red Bull GmbH, Danone S.A., Suntory Beverage & Food Ltd, Unilever, Asahi Group Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nonalcoholic Beverage Market Strategic Shifts & Innovations
The fusion of food science with digital technology is redefining the consumer experience. This convergence is moving the market from mass production toward personalized nutrition, forcing incumbents to innovate beyond simple flavor extensions and packaging updates.
Sensor-enabled smart cap technology provides consumers with real-time data on hydration levels and liquid freshness. Health-conscious individuals and athletic communities are the primary early adopters of these connected bottles. This technology is miniaturizing the feedback loop between consumption and personal health metrics, enabling immediate, data-driven beverage choices.
China's State Administration for Market Regulation (SAMR) is increasing enforcement of its GB standards governing sugar content and food additives. This regulatory pressure compels brands to reformulate legacy products, particularly in the carbonated soft drink and juice categories. The ready-to-drink tea segment is responding most rapidly, launching numerous "zero sugar" and "low sugar" variants using approved natural sweeteners.
A distinct behavioral shift from single, large-volume retail purchases to curated, subscription-based home delivery is underway. This direct-to-consumer (DTC) model is disrupting the traditional dominance of supermarkets for niche products like functional beverages and premium cold-pressed juices. The pattern is most pronounced in dense urban centers across the United States and Western Europe, where sophisticated logistics networks facilitate the model.
Global Nonalcoholic Beverage Market Segmentation
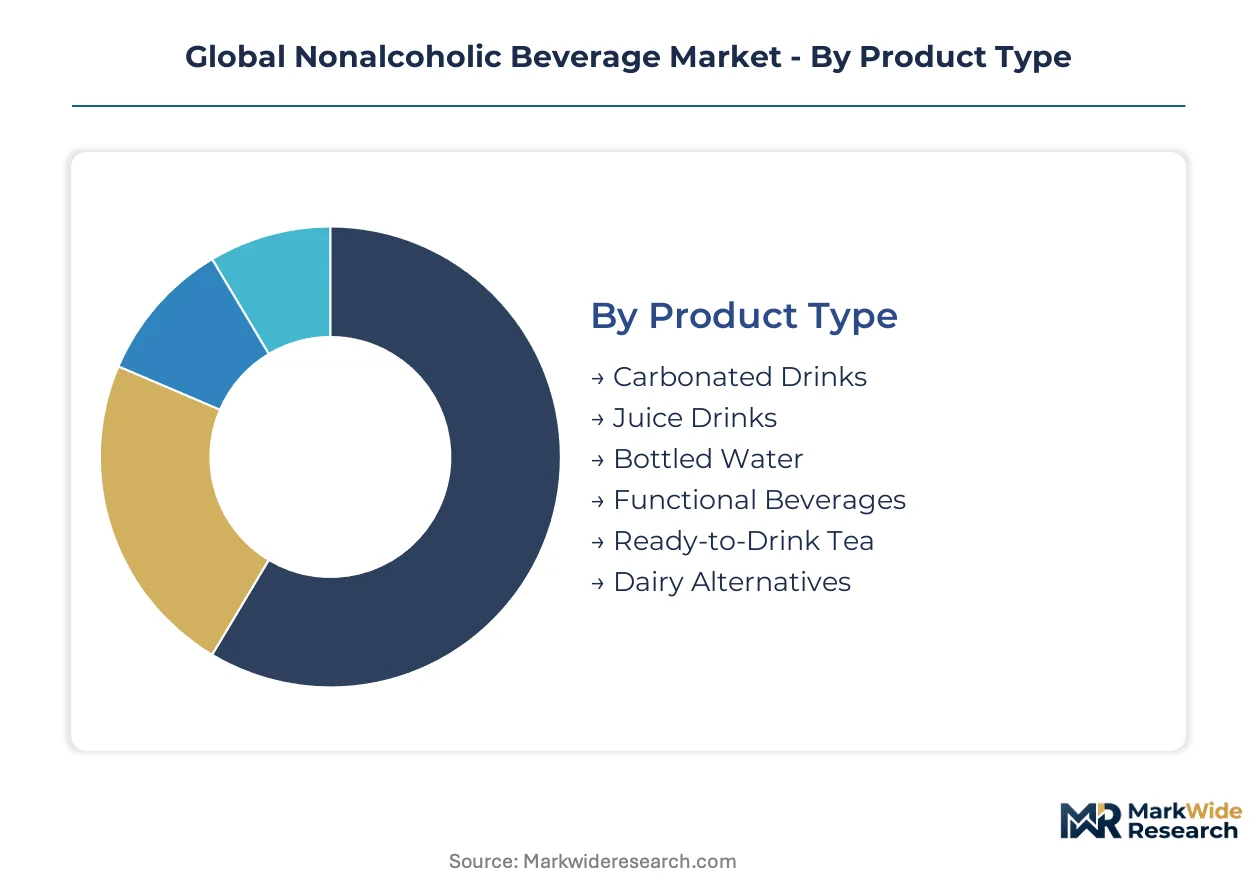
The global nonalcoholic beverage market exhibits diverse consumption patterns and product preferences across various demographic and geographic landscapes. Understanding these distinct segments allows producers to tailor product formulations, packaging, and distribution strategies effectively. This granular view reveals opportunities for targeted innovation and market penetration.
Product Type:
Certain nonalcoholic beverage product types demonstrate strong domestic market saturation, while others are experiencing significant export-driven expansion into new territories.
- Functional Beverages:These formulations incorporate specific ingredients like vitamins, minerals, probiotics, or botanicals to deliver perceived health benefits beyond basic nutrition. Demand is concentrating among health-conscious adults in major cities within China and India, driven by a preventative health focus.
- Dairy Alternatives:These plant-based beverages, derived from sources like almond, oat, or soy, offer lactose-free and vegan options. Consumption is expanding rapidly in North America and Western Europe, appealing to consumers with dietary restrictions and ethical preferences.
- Carbonated Drinks:These effervescent beverages, typically sweetened and flavored, form a foundational volume segment.
- Juice Drinks:Fruit-based liquid products, often with added sugars or water, cater to a broad consumer base.
- Bottled Water:Packaged drinking water, including still, sparkling, and flavored variants, provides essential hydration.
- Ready-to-Drink Tea:Pre-brewed and packaged tea products, available in various flavors and sweetness levels, offer convenience.
Carbonated Drinks command the established base. The steepest expansion runs through Functional Beverages.
Packaging Type:
Packaging types in the nonalcoholic beverage market often reflect a balance between material cost, consumer convenience, and environmental impact considerations.
- Plastic Bottles:These lightweight, shatter-resistant containers are widely used for mass-market beverages due to their cost-effectiveness and transport efficiency. Demand remains high for bottled water and carbonated soft drinks, despite growing environmental concerns.
- Cartons:Made from renewable paperboard, these aseptic packages extend shelf life without refrigeration for products like juice and dairy alternatives. Regulations like the EU's CSRD are accelerating their adoption for sustainable packaging solutions.
- Glass Bottles:Premium beverages and certain traditional products utilize glass for its inertness and perceived quality.
- Aluminum Cans:Recyclable and durable, aluminum cans are favored for carbonated drinks and ready-to-drink teas.
- Tetra Pak:Multi-layered aseptic packaging, often used for milk and juice, protects contents from light and oxygen.
- Pouches:Flexible, lightweight pouches offer convenience and reduced material use for children's drinks and on-the-go consumption.
Volume is dominated by Plastic Bottles, while Cartons are gaining traction due to sustainable packaging mandates.
Distribution Channel:
Distribution channels cater to distinct customer purchasing behaviors, ranging from routine grocery shopping to specialized or immediate consumption needs.
- Online Retail:This channel leverages e-commerce platforms for direct delivery, enabling personalized subscription services and wider product availability. The shift towards curated, subscription-based home delivery is most pronounced in dense urban centers across the United States and Western Europe.
- Foodservice Channels:This segment encompasses sales to corporate cafeterias, healthcare facilities, and educational institutions, offering a significant B2B revenue stream. Expanding premium nonalcoholic options in these settings represents a strategic opportunity for producers.
- Supermarkets & Hypermarkets:Large format retail stores serve as the primary channel for bulk and routine grocery purchases.
- Convenience Stores:These smaller outlets provide immediate consumption options and quick access for on-the-go purchases.
- Specialty Stores:Retailers focusing on organic, health, or gourmet products offer curated selections of niche beverages.
- Direct Sales:Manufacturers sell directly to consumers, often through company-owned stores or events, for exclusive products.
Traditional retail channels maintain significant reach, but Online Retail is experiencing rapid expansion driven by personalized delivery models.
Consumer Age Group:
Each consumer age group exhibits unique preferences and health requirements, influencing the specific nonalcoholic beverage formulations and marketing approaches.
- Adults:This broad demographic represents the largest consumer base, driving demand for both traditional and functional beverages. Their purchasing decisions are influenced by health trends, convenience, and brand loyalty across various product types.
- Young Professionals:This segment actively seeks out functional beverages and premium options, often prioritizing health and wellness benefits. They are early adopters of new technologies like smart cap hydration tracking and frequently utilize subscription delivery services for tailored nutrition.
- Children:This group primarily consumes juice drinks and flavored milk, with a focus on taste and parental approval.
- Teenagers:Energy drinks and carbonated soft drinks are popular among teenagers, often driven by social trends and taste.
- Seniors:Health-conscious seniors often prefer low-sugar options, fortified beverages, and easy-to-digest dairy alternatives.
While Adults represent the foundational consumer base, Young Professionals show the fastest growth in premium and functional categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global nonalcoholic beverage market exhibits varying export and import dynamics, with certain regions driving innovation while others represent significant consumption hubs. Trade flows are influenced by local ingredient availability and evolving consumer preferences. This market is shaped by diverse regulatory environments and logistical capabilities.
United States
Demand for personalized nutrition and plant-based dairy alternatives drives market expansion in the United States. The US FDA's standards for nutrient content claims directly influence product formulation and marketing strategies. Urban centers like New York City and Los Angeles actively adopt direct-to-consumer personalization models for beverage delivery.
China
China's market sees strong demand for functional beverages and premium juice drinks, fueled by a preventative health focus. SAMR's enforcement of GB standards for food additives and labeling governs market access. Major cities such as Shanghai and Beijing demonstrate significant consumption of health-conscious beverage options.
India
India's nonalcoholic beverage sector benefits from demand for functional ingredients and preventative health, particularly in urban areas. FSSAI guidelines influence product formulation and marketing approaches for new entrants. Urban populations in Mumbai and Delhi fuel expansion for enhanced and premium beverages.
Germany
Germany drives demand for sustainable packaging solutions and dairy alternatives, aligning with environmental consciousness. The EU's CSRD regulation accelerates the transition towards advanced cartons and recycled materials. Berlin's vibrant startup ecosystem fosters innovation in plant-based and health-science oriented beverage formulations.
Brazil
Brazil shows consistent demand for fruit-based juice drinks and convenience-focused bottled water across its large consumer base. ANVISA regulations govern food and beverage safety and labeling requirements within the country. Major metropolitan areas like São Paulo and Rio de Janeiro represent significant consumption centers for mass-market nonalcoholic categories.
Global Nonalcoholic Beverage Market Key Industry Players
Listed leaders compete with private specialists across innovation and distribution channels within the nonalcoholic beverage market. The industry structure features global conglomerates leveraging extensive networks alongside agile niche players focusing on specific dietary preferences. Strategic archetypes include mass-market volume producers, functional beverage innovators, and plant-based alternative providers. Companies pursue portfolio diversification, strategic partnerships, and targeted M&A to capture evolving consumer demand.
At the global scale, companies like PepsiCo, Inc. and Nestlé S.A. represent the diversified beverage giants, utilizing vast distribution networks to offer both traditional and health-focused lines. These publicly traded entities exemplify broad market coverage and brand strength across numerous product categories, from carbonated drinks to bottled water. Danone S.A., also a publicly listed entity, anchors the market's dairy alternative and probiotic-infused segments, demonstrating a distinct focus on specific consumer wellness needs and plant-based innovation.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo, Inc. |
| Nestlé S.A. |
| Keurig Dr Pepper Inc. |
| Red Bull GmbH |
| Danone S.A. |
| Suntory Beverage & Food Ltd |
| Unilever |
| Asahi Group Holdings, Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for key agricultural commodities like sugar and fruit concentrates secure consistent input access and stabilize cost visibility for large beverage producers. This contract-based approach helps mitigate volatility in raw material markets, enabling more predictable financial planning within the nonalcoholic beverage sector.
Pricing Analysis
Industrial OEM buyers anchor per-unit transactional pricing for bulk ingredients, while consumer retail pricing for nonalcoholic beverages often follows a tiered premium-mid-economy structure. Price differentiation stems from brand premium, organic certification levels, and geographic delivery costs, particularly for perishable goods. Pricing pressure stems from the rising prominence of private label brands and intense competition in the mass-market carbonated drinks segment. Mass-market consumers exhibit high price sensitivity, whereas functional beverage purchasers are less sensitive to higher price points.
Supply Chain Analysis
Just-in-time inventory strategies dominate for high-volume, shelf-stable nonalcoholic beverages, minimizing warehousing costs, while certain perishable functional drinks require strategic stockpiling at regional distribution hubs. Geographic supply concentration for key inputs includes Brazil for fruit concentrates and China for various packaging materials and specialized botanicals. Raw material dependencies center on sugar, fruit concentrates, and an expanding array of functional additives. Input cost volatility represents a significant structural risk for manufacturers. Distribution runs through a hybrid model, combining traditional supermarket channels with a rapidly expanding direct-to-consumer network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global nonalcoholic beverage market presents a significant fragmentation opportunity, driven by evolving consumer demand for personalized functional health benefits.
For Market Incumbents: Secure existing market share by accelerating portfolio diversification into functional and plant-based categories, countering regulatory pressure on sugar content from bodies like SAMR. Invest in sustainable packaging R&D, particularly advanced cartons, to meet EU CSRD mandates and appeal to environmentally conscious consumers. Leverage extensive distribution networks to introduce these new product lines, mitigating market share erosion from agile niche players.
For New Entrants and Emerging Players: Organic certification fast-tracks market entry for novel plant-based dairy alternatives, targeting health-conscious young professionals in dense urban centers across North America and Western Europe. Focus on developing proprietary formulations with clinically substantiated health claims, aligning with EFSA guidelines. A direct-to-consumer personalization model, leveraging e-commerce and data analytics, offers a scalable go-to-market angle for niche functional beverages.
For Investors and Strategic Acquirers: Specialized functional beverage developers with strong brand equity and proprietary formulations represent compelling acquisition targets over a five-to-ten-year horizon. These entities often possess unique intellectual property in botanicals or processing technologies. A signal to watch for investment attractiveness is successful clinical trial substantiation of health claims, indicating regulatory compliance and market differentiation. Focus on companies demonstrating strong growth in urban markets within China and India.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch new functional beverage lines | Diversifies product offerings to capture health-conscious consumer demand. |
| Invest in advanced carton packaging | Aligns with sustainable packaging mandates and environmental consumer preferences. |
| Expand into foodservice channels | Opens a new high-volume B2B revenue stream in corporate and institutional settings. |
| Develop novel plant-based dairy alternatives | Addresses specific dietary needs and ethical preferences in key global markets. |
| Conduct clinical trials for health claims | Provides regulatory substantiation and builds consumer trust for functional products. |
Research Approach
Findings reconcile primary fieldwork against secondary review of company annual reports, industry association publications, and regulatory filings from US FDA, EU EFSA, and China SAMR. Primary interviews involved R&D executives, marketing directors, supply chain managers, and retail buyers across key geographies. This approach facilitated bottom-up market sizing and top-down validation.
Market segmentation modeled across product type, packaging type, distribution channel, and consumer age group informed the quantitative framework over the projection horizon. Compound Annual Growth Rates were derived from historical data analysis, expert interviews, and a comprehensive assessment of market growth drivers. Key forecast inputs included consumer spending patterns and raw material price forecasts.
Underlying assumptions cover stable regulatory environments and consistent consumer health trends, with deviation risk concentrated in sudden shifts in commodity prices. New health-related regulations or major public health crises could significantly alter market dynamics. Revision becomes warranted when significant changes in global trade policies or major public health crises cross defined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Ice Tea Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Fruit-Infused Water Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Europe Sports Drink Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
US Non-Alcoholic Beverages Market