
 Cardamom Market | 2026-2036
Cardamom Market Size, Share, and Industry Trends Forecast 2026-2036
Cardamom Market Analysis
Multi-source procurement from smallholder cooperatives is hardening as the dominant sourcing pattern in cardamom. Olam Group Limited leverages its East African and South Indian estate networks to sustain year-round supply continuity. McCormick & Company, Inc. anchors North American retail shelf presence through proprietary grinding and volatile oil retention protocols. Frontier Cooperative differentiates via organic certification density and direct trade relationships with Idukki-based growers.
Cardamom comprises the dried fruit capsules of Elettaria cardamomum, valued for volatile oil content typically ranging from 2.5% to 8.0% by weight depending on curing method and storage conditions. The spice functions primarily as a flavoring agent, a carminative in traditional medicine systems, and an aromatic fixative in perfumery. Green cardamom commands premium positioning in food and beverage applications where whole-pod appearance and high cineole concentration justify price separation from black cardamom. Cardamom oil extraction is accelerating as cosmetics manufacturers seek natural fragrance compounds compliant with EU REACH registration thresholds. Ground cardamom occupies mature volume channels through supermarket and wholesale distribution, though margin compression intensifies against whole-pod specialty retail formats.
FSSAI in India enforces maximum residue limits and aflatoxin thresholds that determine export eligibility to EU markets governed by EFSA standards and REACH chemical safety protocols. FDA oversight in the United States shapes import inspection frequency and dietary supplement labeling requirements for cardamom-derived products. Stakeholders must monitor how dual carbon goals in India and EU Green Deal agricultural sourcing criteria will reshape curing energy inputs and smallholder compliance costs across origin markets.
Market Dynamics
FSSAI spice purity mandates and EU REACH chemical safety protocols are compressing export eligibility windows for Indian cardamom processors, forcing cooperative infrastructure upgrades across Kerala's Idukki district curing facilities.
Growth Catalysts
- Specialty beverage flavor layering:Premium tea blenders and craft coffee roasters are expanding whole-pod procurement for aromatic complexity in high-value SKUs.
- EUFood safety alignment:FSSAI maximum residue limit harmonization with EFSA aflatoxin thresholds is unlocking EU market access for compliant Indian exporters.
- Green curing method diffusion:Solar-assisted drying protocols in Idukki are reducing fossil fuel dependence while preserving volatile oil concentration above 6%.
Market Restraints
- Input cost volatility:Labor wages in Kerala's plantation belt fluctuate with seasonal migration patterns, squeezing processor margins during peak harvest windows.
- Supply concentration risk:Cooperative processing infrastructure dominance in Idukki creates single-point vulnerability to climate-induced yield shocks.
- Substitution pressure:Synthetic cineole and artificial cardamom flavoring compounds from flavor houses are penetrating economy-tier bakery and confectionery segments.
Strategic Opportunities
- Cosmetics natural fragrance pivot:EU REACH-compliant cardamom oil extraction is accelerating as perfumery houses seek botanical alternatives to synthetic fixatives.
- Direct trade channel expansion:Organic-certified Idukki growers are bypassing auction houses through blockchain-traceable contracts with North American retailers.
- PLI scheme alignment:India's production-linked incentive framework for food processing is subsidizing value-addition infrastructure for volatile oil distillation units.
Industry Challenges
- Certification timeline compression:Organic and Fairtrade audit backlogs in Kerala are delaying export readiness for smallholders seeking premium market access.
- Skill scarcity in quality grading:Expertise in cineole content assessment and visual pod grading is concentrating among aging cooperative inspectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardamom Market |
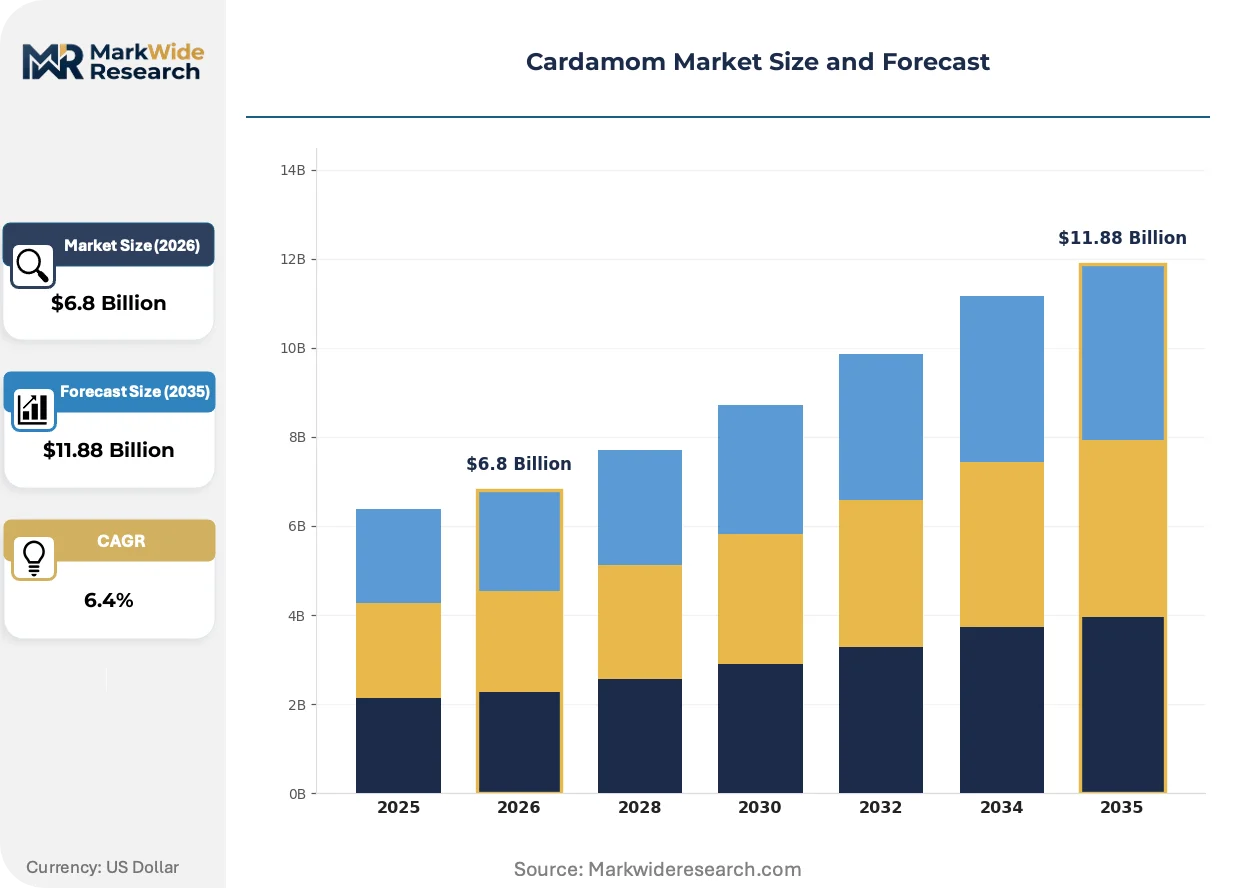
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Cardamom, Black Cardamom, Cardamom Oil, Ground Cardamom Application: Food & Beverage, Healthcare, Cosmetics, Flavoring End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Frontier Cooperative, Eastmade Spices & Herbs Private Limited, McCormick & Company, Inc., Vandanmedu Green Gold Cardamom Producer Company Limited, South Indian Green Cardamom Company Limited, Olam Group Limited, Mane Kancor Ingredients Private Limited, The Kerala Cardamom Processing and Marketing Co Ltd, DS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardamom Market Emerging Trajectories
Digital traceability infrastructure and renewable energy curing systems are displacing traditional auction-based sourcing and fossil-dependent drying methods across origin markets.
Blockchain-enabled provenance tracking is integrating with cooperative management software in Idukki's processing facilities. Specialty roasters and premium spice importers are adopting these systems to satisfy EU Green Deal agricultural sourcing criteria. This technology is integrating previously fragmented smallholder data into unified export compliance documentation, compressing customs clearance timelines for EU-bound shipments.
EU REACH registration thresholds for natural fragrance compounds are tightening disclosure requirements for cosmetics manufacturers. ECHA is mandating full supply chain substance registration for botanical extracts above specified volume thresholds. Fragrance houses sourcing cardamom oil are responding by demanding certified distillation records from Indian processors, shifting procurement criteria toward documented volatile oil retention protocols.
Buyer concentration among specialty beverage brands is consolidating procurement decisions into direct trade relationships with named estate cooperatives. Traditional auction houses in Kochi are losing volume share to pre-harvest contracting arrangements. This pattern is most visible in North American premium retail channels where single-origin storytelling commands shelf price separation from commodity-grade alternatives.
Cardamom Market Segmentation
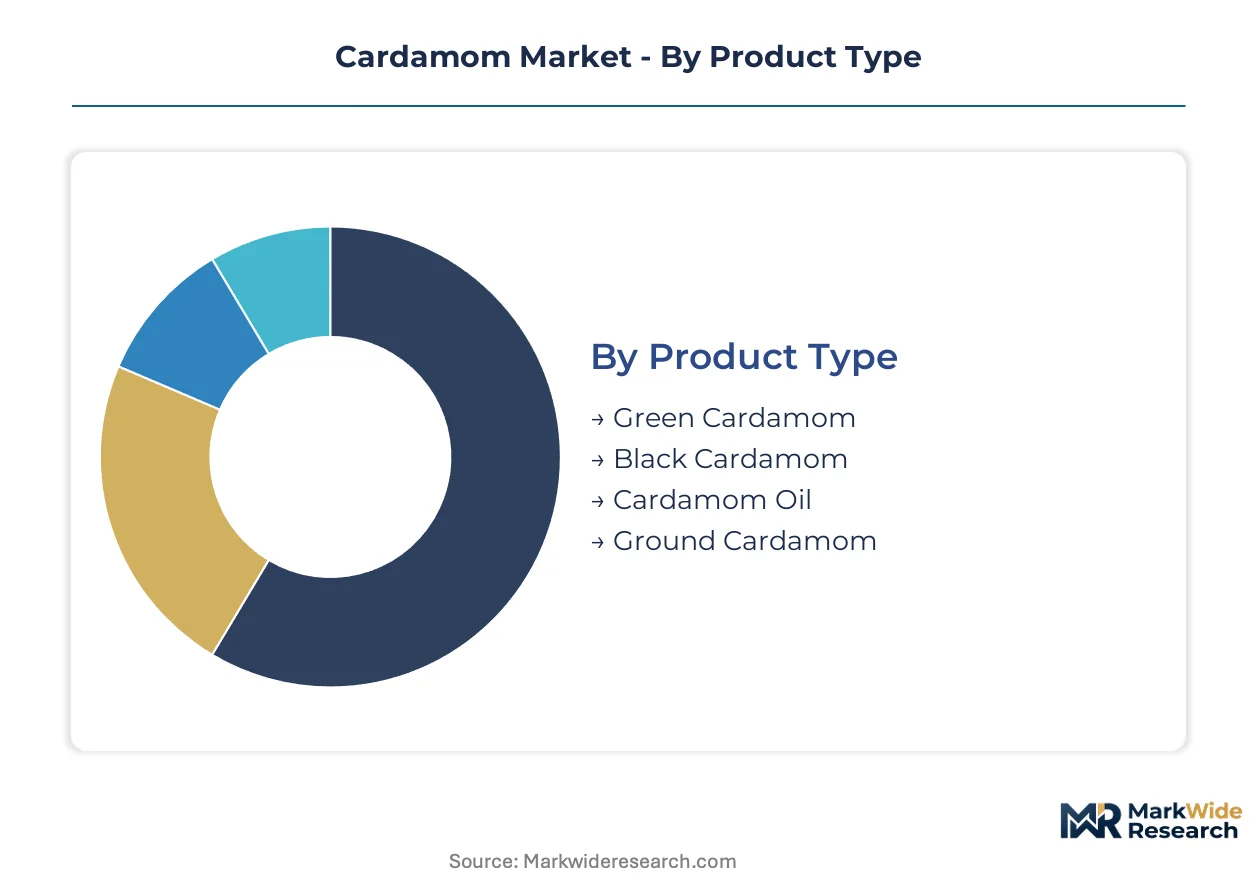
Cardamom procurement patterns diverge sharply across product formats and end-use specifications, with volatile oil content thresholds and appearance standards determining price realization. Application-driven segmentation reveals how pharmaceutical extractors, specialty beverage formulators, and fragrance houses impose incompatible purity and documentation requirements on common raw material origins.
Product Type:
Buyers select product formats based on end-use oil retention needs and visual presentation requirements, with whole-pod applications commanding strict cineole concentration minimums.
- Green Cardamom:Whole dried capsules of Elettaria cardamomum with volatile oil content typically exceeding 6% in premium grades. Kerala's Idukki district cooperative curing facilities supply specialty coffee roasters and premium tea blenders who specify whole-pod appearance and high cineole concentration for aromatic complexity in high-value SKUs.
- Black Cardamom:Larger capsules from Amomum subulatum with smoky flavor profiles from open-flame curing methods. North Indian and Nepalese processors supply this lower-priced format to economy-tier bakery and confectionery segments where synthetic cineole substitution pressure is most intense.
- Cardamom Oil:Steam-distilled volatile oil extracts standardized for 1,8-cineole content. EU REACH-compliant extraction is accelerating as perfumery houses seek botanical alternatives to synthetic fixatives.
- Ground Cardamom:Powdered form occupying mature volume channels through supermarket and wholesale distribution. Margin compression intensifies against whole-pod specialty retail formats as volatile oil degradation accelerates post-grinding.
Volume sits with Ground Cardamom; growth tilts toward Cardamom Oil.
Application:
Regulatory compliance burdens concentrate in pharmaceutical and cosmetic applications, where EU REACH and FSSAI mandates impose substance registration and residue documentation requirements absent from food-grade channels.
- Food & Beverage:Dominant consumption channel spanning bakery, confectionery, dairy, and beverage applications. Specialty coffee roasters and craft tea blenders are expanding whole-pod procurement for flavor layering in premium SKUs.
- Healthcare:Traditional medicine systems and modern pharmaceutical applications leveraging carminative properties. FSSAI maximum residue limit harmonization with EFSA aflatoxin thresholds is unlocking EU market access for compliant Indian extractors.
- Cosmetics:Natural fragrance and skincare applications requiring full supply chain substance registration. ECHA mandates are shifting procurement criteria toward documented volatile oil retention protocols from Indian processors.
- Flavoring:Industrial flavor house procurement for compound formulations. Synthetic cineole penetration is compressing natural cardamom share in economy-tier segments.
Food & Beverage holds the largest volume position; Cosmetics exhibits the steepest expansion trajectory.
End User:
Scale requirements and certification density separate institutional buyers from fragmented household demand, with pharmaceutical and cosmetic manufacturers imposing batch-traceability standards that exclude smallholder cooperatives lacking digital infrastructure.
- Food Manufacturers:Industrial-scale processors requiring consistent volatile oil specifications for standardized formulations. Procurement concentrates through pre-harvest contracting with named estate cooperatives, bypassing traditional auction houses.
- Pharmaceutical Companies:Extractors demanding certified distillation records and aflatoxin documentation. FSSAI enforcement of maximum residue limits determines export eligibility to EU markets governed by EFSA standards.
- Cosmetic Brands:Fragrance houses and natural skincare formulators seeking REACH-compliant botanical alternatives. Full supply chain substance registration requirements are compressing eligible supplier pools.
- Households:Fragmented retail demand served through supermarket and online channels. Price sensitivity in this segment sustains ground cardamom volume despite whole-pod premium positioning.
Food Manufacturers dominate procurement volume; Cosmetic Brands are gaining share fastest.
Distribution Channel:
Channel selection reflects buyer sophistication and documentation requirements, with blockchain-traceable direct trade eroding traditional auction-based volume flows.
- Online Retail:E-commerce platforms serving premium household and small-scale food service demand. Single-origin storytelling commands shelf price separation from commodity-grade alternatives.
- Supermarkets:Mass-market retail channels for ground cardamom and economy-tier whole pods. Private label penetration intensifies margin compression against branded specialty formats.
- Specialty Stores:Premium spice retailers and ethnic grocery channels. Organic-certified Idukki growers are bypassing auction houses through direct relationships with North American retailers.
- Wholesale:Bulk procurement channels for industrial food manufacturers and flavor houses. Traditional Kochi auction houses are losing volume share to pre-harvest contracting arrangements.
Wholesale channels handle the greatest volume; Specialty Stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in India's Kerala state, where Idukki district cooperative infrastructure processes the majority of global green cardamom exports. Specialty beverage brands in North America and fragrance houses in Europe are redirecting procurement toward named-origin contracts with these cooperatives.
India
Specialty coffee roasters and premium tea blenders are expanding direct procurement from Idukki district cooperatives for whole-pod aromatic complexity. FSSAI spice purity mandates are tightening traceability requirements across export supply chains, forcing curing facility upgrades. Kerala's Idukki district dominates global green cardamom grading through cooperative processing infrastructure.
United States
Craft coffee roasters and natural cosmetics brands are driving premium whole-pod demand through specialty retail channels. FDA import inspection frequency shapes entry timelines for cardamom-derived dietary supplements. McCormick & Company anchors North American retail shelf presence through proprietary grinding protocols.
Germany
Fragrance houses and natural skincare formulators are accelerating REACH-compliant cardamom oil procurement for botanical fixatives. ECHA substance registration mandates are compressing eligible supplier pools to documented Indian processors. Hamburg and Frankfurt trading houses are consolidating direct trade relationships with Kerala cooperatives.
United Arab Emirates
Re-export hubs in Dubai are channeling Indian cardamom toward Middle Eastern and North African spice markets. MOHAP food safety standards are aligning with EU aflatoxin thresholds for transshipment eligibility. Dubai's Jebel Ali Free Zone warehousing is enabling year-round supply continuity for Gulf Cooperation Council buyers.
Switzerland
Swissmedic oversight of botanical pharmaceutical ingredients is creating premium extraction demand for certified-distillation cardamom oil. Geneva-based fragrance houses are mandating full supply chain documentation for natural fragrance compounds. Basel pharmaceutical clusters are sourcing high-cineole extracts for carminative formulations.
Cardamom Market Vendor Landscape
Direct trade contracting dominates the current landscape as specialty buyers bypass traditional auction infrastructure. The vendor base fragments across estate networks, cooperative federations, and integrated spice houses, with consolidation pressure intensifying at the processing tier. Three archetypes occupy distinct positions: integrated agricultural conglomerates with multi-origin estate networks, cooperative federations anchored in Kerala's Idukki district, and North American retail-focused grinders with proprietary volatile oil retention protocols. Competitive moves center on backward integration into curing infrastructure and blockchain-traceable supply chain documentation.
Among integrated agricultural groups, Olam Group Limited exemplifies the multi-origin estate network archetype through its East African and South Indian operations. Frontier Cooperative occupies a position within the organic certification density tier, while McCormick & Company, Inc. anchors the North American retail grinding segment. These three entities represent the dominant competitive vectors: geographic diversification, certification density, and proprietary processing protocols.
| Leading Market Players |
|---|
| Frontier Cooperative |
| Eastmade Spices & Herbs Private Limited |
| McCormick & Company, Inc. |
| Vandanmedu Green Gold Cardamom Producer Company Limited |
| South Indian Green Cardamom Company Limited |
| Olam Group Limited |
| Mane Kancor Ingredients Private Limited |
| The Kerala Cardamom Processing and Marketing Co Ltd |
| DS Group |
| Others |
Supply Flow & Price Mechanics
Expertise in cineole content assessment and visual pod grading concentrates among aging cooperative inspectors across Kerala's Idukki district, with labor-cost differentials between these skilled graders and unskilled harvest workers driving spreads between premium whole-pod and economy-grade ground formats. This workforce scarcity compresses processor margins during peak harvest windows while amplifying price separation across certification tiers.
Pricing Analysis
Warranty-like service bundling separates premium from standard tiers, with organic-certified Idukki growers offering blockchain-traceable documentation and volatile oil retention guarantees that uncertified auction-house suppliers cannot match. Three-tier pricing structure across premium, standard, and economy levels reflects FSSAI compliance grade and cineole concentration thresholds. Cost compression in ground cardamom intensifies as private label penetration erodes branded specialty margins. Food manufacturers exhibit highest price sensitivity due to volume scale, while fragrance houses show lowest sensitivity given REACH compliance requirements.
Supply Chain Analysis
Workforce availability constraints in Kerala's plantation belt and Guatemala's emerging cultivation zones tether supply expansion to seasonal migration patterns. Raw material flows draw from smallholder cooperatives in Idukki, East African estate networks, and Nepalese black cardamom processors. Single-source vulnerability concentrates in Idukki's cooperative curing infrastructure, exposing global supply to climate-induced yield shocks. Distribution runs through direct trade contracts with North American specialty retailers, bypassing traditional Kochi auction houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with players pursuing upstream control over curing infrastructure to capture FSSAI compliance premiums and secure EU market access.
For Market Incumbents: Anchor market position through captive supply of Idukki cooperative curing capacity and proprietary volatile oil retention protocols. Synthetic cineole substitution pressure from flavor houses threatens economy-tier ground cardamom share; defend through certification investment in organic and Fairtrade tiers. Backward integration into solar-assisted drying infrastructure reduces fossil fuel cost exposure. For New Entrants and Emerging Players: Enter via cosmetics-grade cardamom oil extraction for EU REACH-compliant fragrance houses, where supplier pools remain thin and documentation requirements exclude traditional auction-sourced material. White-space targets include Swiss pharmaceutical extractors seeking Swissmedic-certified carminative formulations and North American direct-trade specialty retailers lacking Idukki-origin storytelling. Pursue blockchain-traceable pre-harvest contracting as primary go-to-market mechanism. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier cooperative federations possessing FSSAI-compliant curing infrastructure and latent organic certification capacity, given EU Green Deal agricultural sourcing criteria tightening disclosure requirements. Long-term viability hinges on climate adaptation investment and digital traceability deployment. Watch for FSSAI-EU MRL harmonization completion as inflection signal for export eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curing Infrastructure | FSSAI compliance mandates force processor ownership of Idukki cooperative drying facilities to secure export eligibility. |
| Blockchain Traceability Deployment | EU Green Deal sourcing criteria require unified smallholder data integration for customs clearance compression. |
| Organic Certification Investment | Fairtrade and organic audit density unlocks premium pricing separation from commodity auction channels. |
| Solar-Assisted Drying Transition | Dual carbon goals in India and EU subsidies reduce fossil fuel dependence while preserving volatile oil above 6%. |
| Direct Trade Channel Expansion | Pre-harvest contracting with named estate cooperatives displaces traditional Kochi auction volume. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews spanning cooperative federation managers, FSSAI compliance officers at export processors, specialty coffee roaster procurement leads, fragrance house sourcing directors, and Kerala plantation labor contractors. Spices Board of India production statistics, DGFT export registration databases, ECHA REACH substance filings, and EU import rejection records supplied validation benchmarks. Bottom-up smallholder yield estimates and top-down export value flows underwent iterative reconciliation.
Data-stream reconciliation across product format volumes, application-specific pricing spreads, and end-user procurement patterns shaped the analytical framework over the projection horizon. Segmentation dimensions encompassed product type, application, end-user scale tier, and distribution channel sophistication. CAGRs emerged from volatile oil content trend extrapolation and specialty beverage demand elasticity modeling. FSSAI-EU MRL harmonization timelines and PLI scheme subsidy trajectories informed scenario weightings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate-induced yield shocks in Idukki or synthetic cineole breakthroughs in economy-tier formulations. Forecasts reflect documented assumptions on cooperative infrastructure upgrade rates and migration pattern stability. Material deviation in FSSAI enforcement intensity or EU REACH threshold revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
South America Spice and Herb Extracts Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
Low Sodium Sea Salt Market