
 Energy Drinks Market | 2026-2036
Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Drinks Market Intelligence
The capability gap between global beverage giants with vast distribution networks and specialized energy drink brands is collapsing due to direct-to-consumer online channels. Red Bull sustains its premium market position through aggressive sports and lifestyle marketing. PepsiCo leverages its extensive retail footprint for brands like Rockstar. Meanwhile, Celsius Holdings differentiates by targeting the health and wellness segment with its fitness-focused formulations, gaining traction in gyms and specialty stores.
Energy drinks are defined as non-alcoholic beverages containing stimulant compounds, primarily caffeine, along with ingredients like taurine, B vitamins, and various sweeteners or herbal extracts. Their primary commercial purpose is to provide a temporary boost in mental alertness and physical stamina. While carbonated products remain the largest category, the sugar-free and organic segments represent the fastest-growing areas. Distribution through convenience stores and supermarkets still dominates, but online retail is creating new avenues for market entry.
The regulatory environment is shaped by health authorities focused on consumer safety. The U.S. FDA scrutinizes caffeine content and labeling, while the European Food Safety Authority (EFSA) provides guidance on safe consumption levels, influencing marketing claims. In countries like India, the FSSAI sets standards for ingredients and additives. Navigating these varied international regulations while appealing to evolving consumer preferences for healthier options remains the central strategic challenge for all market participants.
Market Dynamics
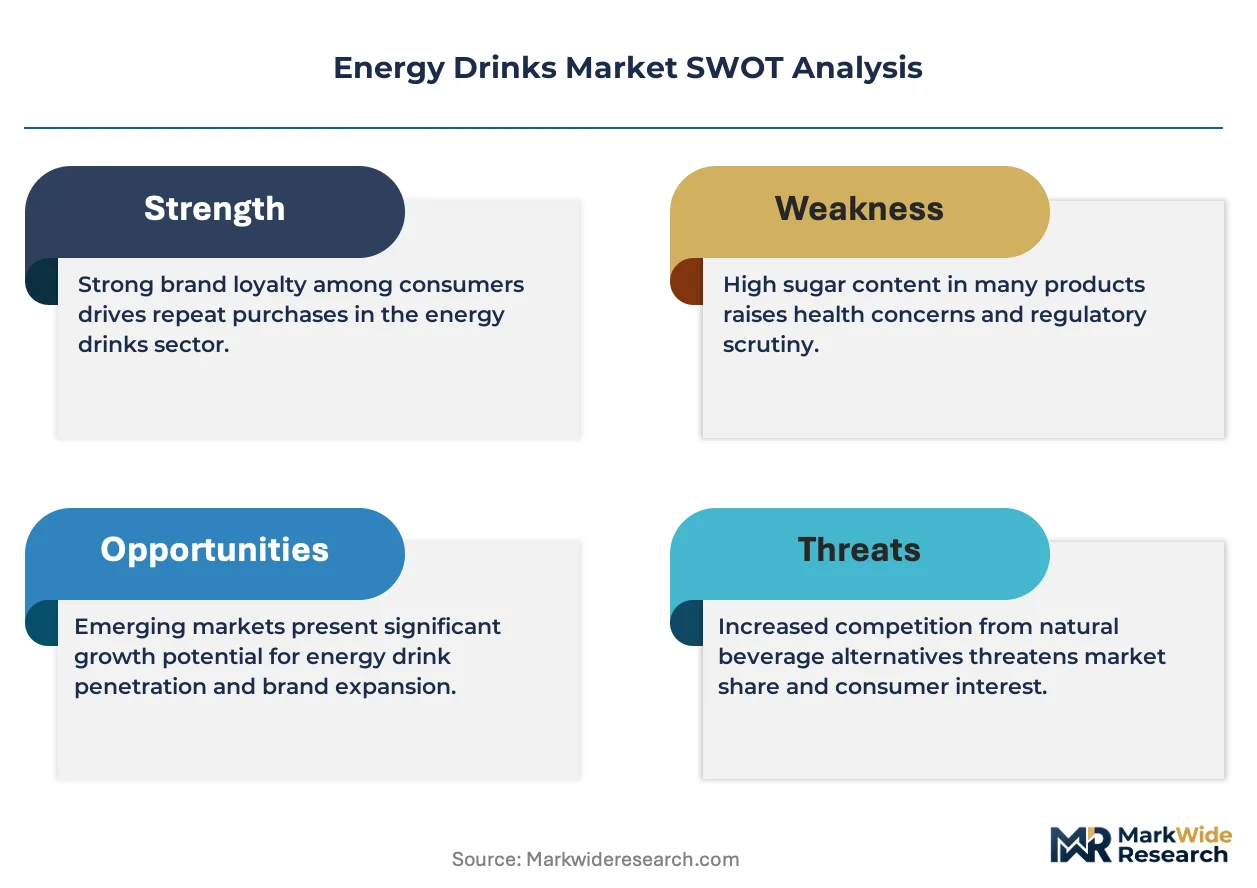
Regulatory pressure from health authorities like the FDA and EFSA is the central force shaping product formulation. This scrutiny over caffeine and sugar directly conflicts with consumer demand for potent performance effects, creating a fundamental strategic challenge.
Growth Catalysts
- Mainstream Fitness Culture:The expansion of gym memberships and participation in amateur sports provides a consistent demand base for beverages positioned for pre-workout energy and post-workout recovery.
- Emerging Market Penetration:Rising disposable incomes in countries such as Brazil and Vietnam create new consumer bases for aspirational lifestyle products, including energy drinks.
- Functional Ingredient Diversification:Integrating nootropics for cognitive enhancement and adaptogens for stress reduction broadens appeal beyond simple stimulation to holistic wellness.
Market Restraints
- Stringent Regulatory Scrutiny:Health warnings and marketing restrictions mandated by bodies like Health Canada and Europe's EFSA limit brand messaging and access to younger demographics.
- Input Price Volatility:Fluctuation in commodity prices for sugar, synthetic caffeine, and aluminum cans creates margin pressure and complicates long-term pricing strategies.
- Beverage Category Substitution:The proliferation of alternatives, including ready-to-drink coffees and electrolyte waters, presents a significant threat of consumer substitution.
Strategic Opportunities
- Targeted E-Sports Formulations:Developing products with nootropics for the cognitive demands of professional and amateur gamers represents a major white-space opportunity with a dedicated global audience.
- Product Format Innovation:Expansion into non-carbonated and powder formats can capture consumers who dislike carbonation or seek more portable and customizable energy solutions.
- Natural and Organic Ingredients:Leveraging plant-based caffeine and natural sweeteners can attract health-conscious consumers wary of synthetic additives.
Industry Challenges
- Global Regulatory Fragmentation:The operational burden of complying with disparate national standards for caffeine and labeling, from the US FDA to India's FSSAI, complicates global product rollouts.
- Formulation Stability:Ensuring the shelf-life stability and consistent sensory profile of products containing complex botanical extracts presents a significant technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Drinks Market |
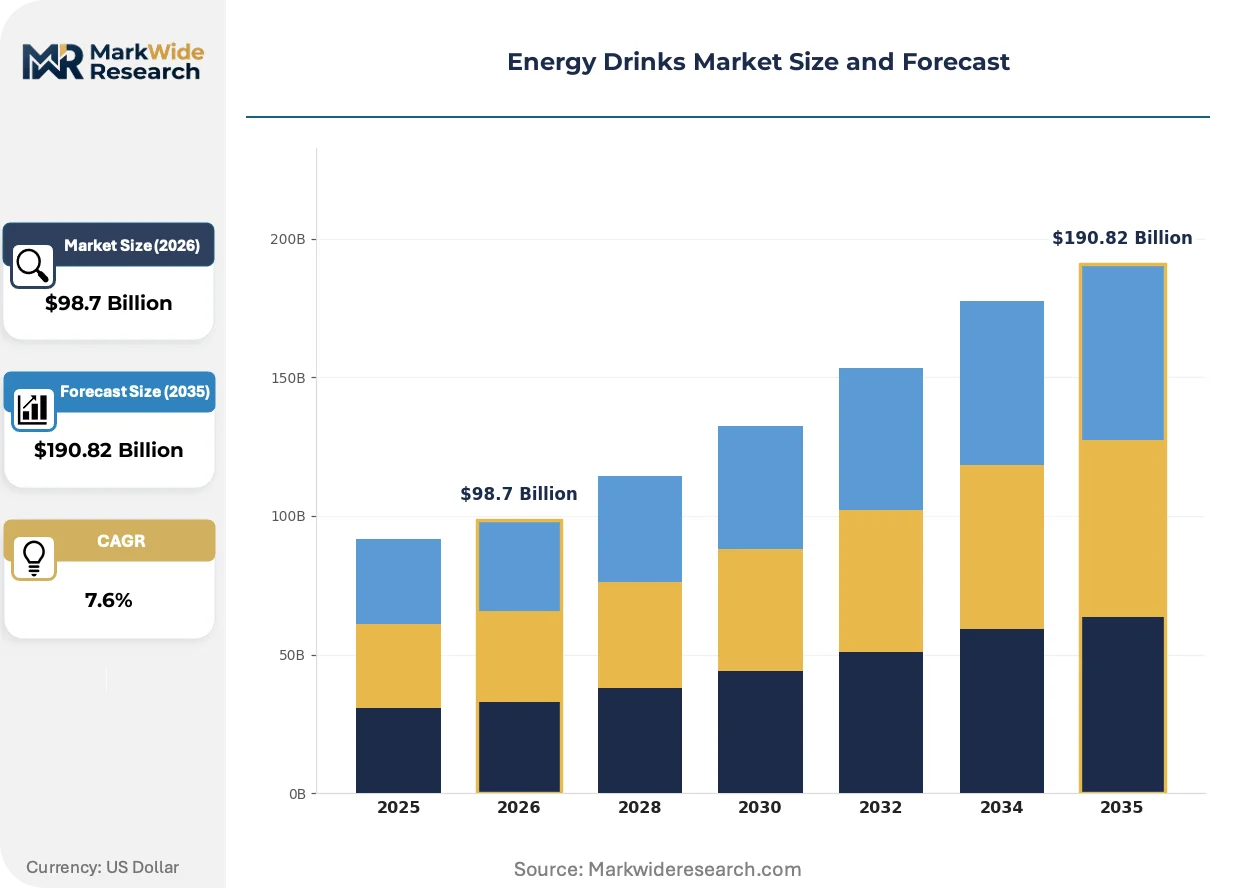
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $190.82 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Organic, Sugar-Free, Herbal Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Specialty Stores, Vending Machines Consumption Occasion: Pre-Workout, Post-Workout, Midday Boost, Social Events, Long-Distance Travel Customer Demographic: Teenagers, College Students, Young Professionals, Fitness Enthusiasts, Shift Workers |
| Companies Covered | PepsiCo, Eastroc Super Drink, Red Bull, Suntory Beverage & Food, National Beverage, Monster Beverage, Celsius Holdings, GURU Organic Energy, Rockstar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Drinks Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward sophisticated, multi-functional formulations beyond simple energy. This shift prompts innovations in ingredient science and creates new friction points with global health regulators.
Natural caffeine sources like green tea extract are combined with nootropics for energy without jitters. This approach is gaining favor among wellness-oriented consumers and professionals seeking cognitive enhancement. The adoption of these ingredient stacks is bifurcating the market, separating basic high-caffeine options from premium, brain-focused functional beverages.
Sugar taxation policies, such as the UK’s Soft Drinks Industry Levy, directly impact product economics. The primary consequence is a sector-wide push toward reformulation, replacing sugar with non-nutritive sweeteners to avoid penalties. This trend most heavily impacts the mass-market segment, accelerating the launch of zero-sugar and low-calorie variants.
Consumer purchasing is moving from impulse buys toward planned, bulk purchases via online channels. This behavior disrupts convenience stores and supermarkets, enabling brands to use direct-to-consumer (DTC) sales and subscription models. The shift is most advanced in the United States, where digital-first brands leverage social media to acquire customers directly.
Energy Drinks Market Segmentation
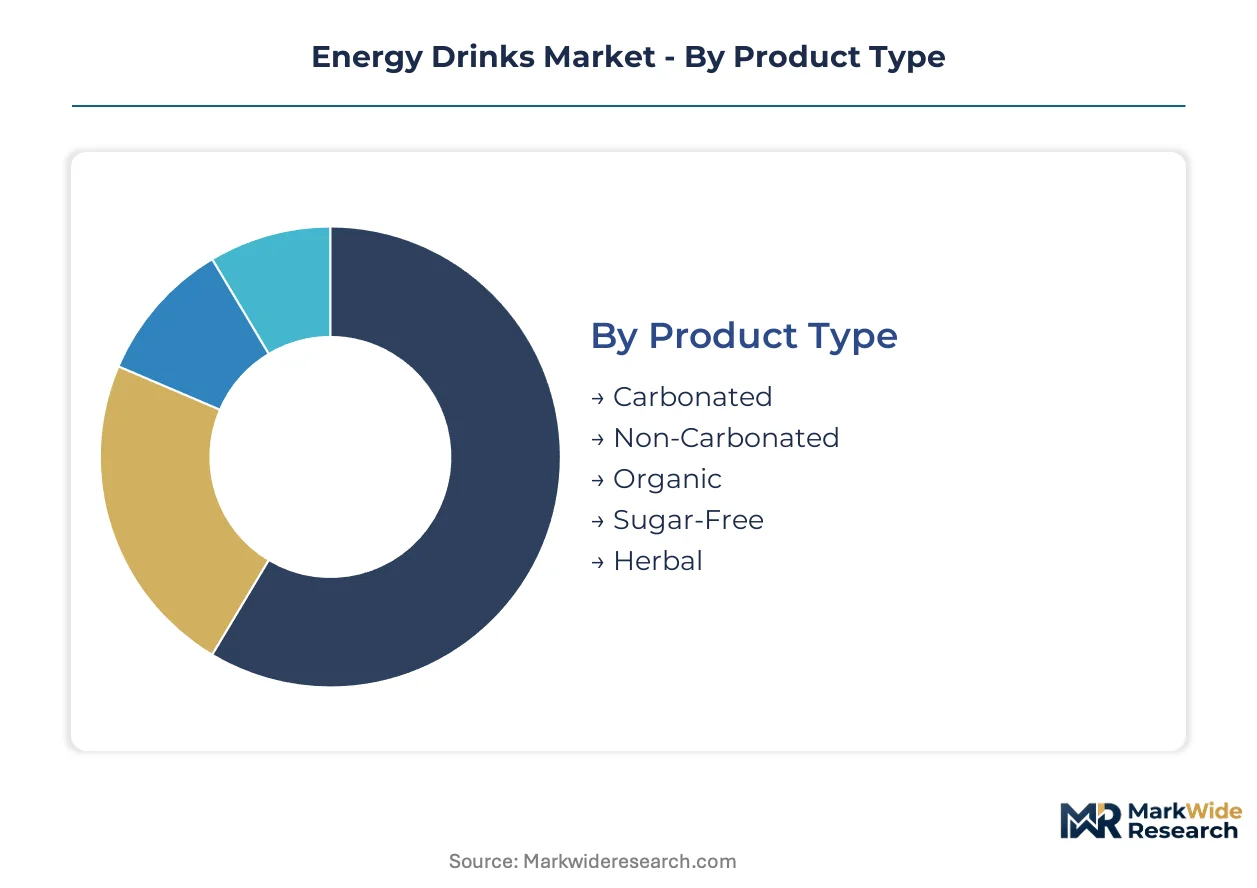
The energy drinks market segmentation provides a granular view of consumer preferences and operational strategies. Understanding these distinct segments allows market participants to tailor product development and distribution efforts. This detailed analysis highlights areas of established demand and emerging growth opportunities across various product types and consumer groups.
Product Type:
The product type segmentation reveals a dichotomy between domestically dominant formulations and those gaining traction in export markets.
- Carbonated:These beverages contain dissolved carbon dioxide, providing a fizzy texture. Demand concentrates in the United States, where traditional consumption patterns favor effervescent products for immediate stimulation.
- Sugar-Free:Formulations using non-nutritive sweeteners eliminate caloric content, catering to health-conscious consumers. This segment experiences growth in European markets, driven by sugar taxation and EFSA recommendations.
- Non-Carbonated:These flat beverages, including shots and liquid concentrates, appeal to consumers preferring a smoother texture.
- Organic:Products certified with organic ingredients, free from synthetic pesticides, target consumers seeking natural alternatives.
- Herbal:These drinks incorporate botanical extracts like ginseng or guarana for natural energy and functional benefits.
Carbonated commands the established base. The steepest expansion runs through Sugar-Free.
Distribution Channel:
Distribution channels are differentiating based on consumer purchasing habits, from impulse buys to planned bulk orders.
- Convenience Stores:These small retail outlets are primary points for impulse purchases of single-serve energy drinks. Demand remains high in urban centers across the United States due to high foot traffic.
- Online Retail:E-commerce platforms and direct-to-consumer websites facilitate planned, bulk purchases and subscription models. This channel expands rapidly in the United States, driven by digital-first brands.
- Supermarkets & Hypermarkets:Large format stores offer extensive selections and multi-pack options for weekly grocery shopping.
- Specialty Stores:Health food stores and gyms stock niche and premium energy drink formulations for targeted demographics.
- Vending Machines:Automated dispensers provide on-the-go access in workplaces and public transport hubs for immediate refreshment.
While Convenience Stores maintain a significant market presence, Online Retail is gaining share fastest through evolving consumer purchasing behaviors.
Consumption Occasion:
This segmentation highlights the specific functional needs driving energy drink consumption across various daily activities.
- Pre-Workout:Consumers use these drinks to enhance physical performance and focus before exercise or athletic activities. This occasion sees strong demand among fitness enthusiasts in Brazil.
- Midday Boost:These products provide a quick surge of energy to combat afternoon fatigue and maintain mental alertness. Young professionals globally frequently consume these for sustained productivity.
- Post-Workout:Formulations designed for recovery, often including electrolytes, assist muscle repair and rehydration after physical exertion.
- Social Events:Energy drinks are consumed as mixers or standalone beverages during gatherings and nightlife, often as an alternative to alcohol.
- Long-Distance Travel:Travelers use these beverages to maintain alertness and combat drowsiness during extended journeys.
Pre-Workout and Midday Boost occasions are driving the largest consumption volumes, reflecting both performance and daily energy needs.
Customer Demographic:
Customer demographics define varying levels of market penetration and specific product preferences within the energy drink sector.
- Fitness Enthusiasts:Individuals engaged in physical activity seek energy drinks for performance enhancement and recovery benefits. This demographic drives growth in the United States, influencing ingredient trends.
- Young Professionals:This group consumes energy drinks to maintain alertness and productivity during demanding work schedules. They represent a significant consumer base in developed economies, valuing premium formulations.
- Teenagers:Attracted by brand marketing and social trends, this demographic consumes energy drinks for recreational purposes.
- College Students:This group relies on energy drinks for sustained concentration during study sessions and to manage sleep patterns.
- Shift Workers:Individuals working irregular hours use energy drinks to combat fatigue and maintain wakefulness during night shifts.
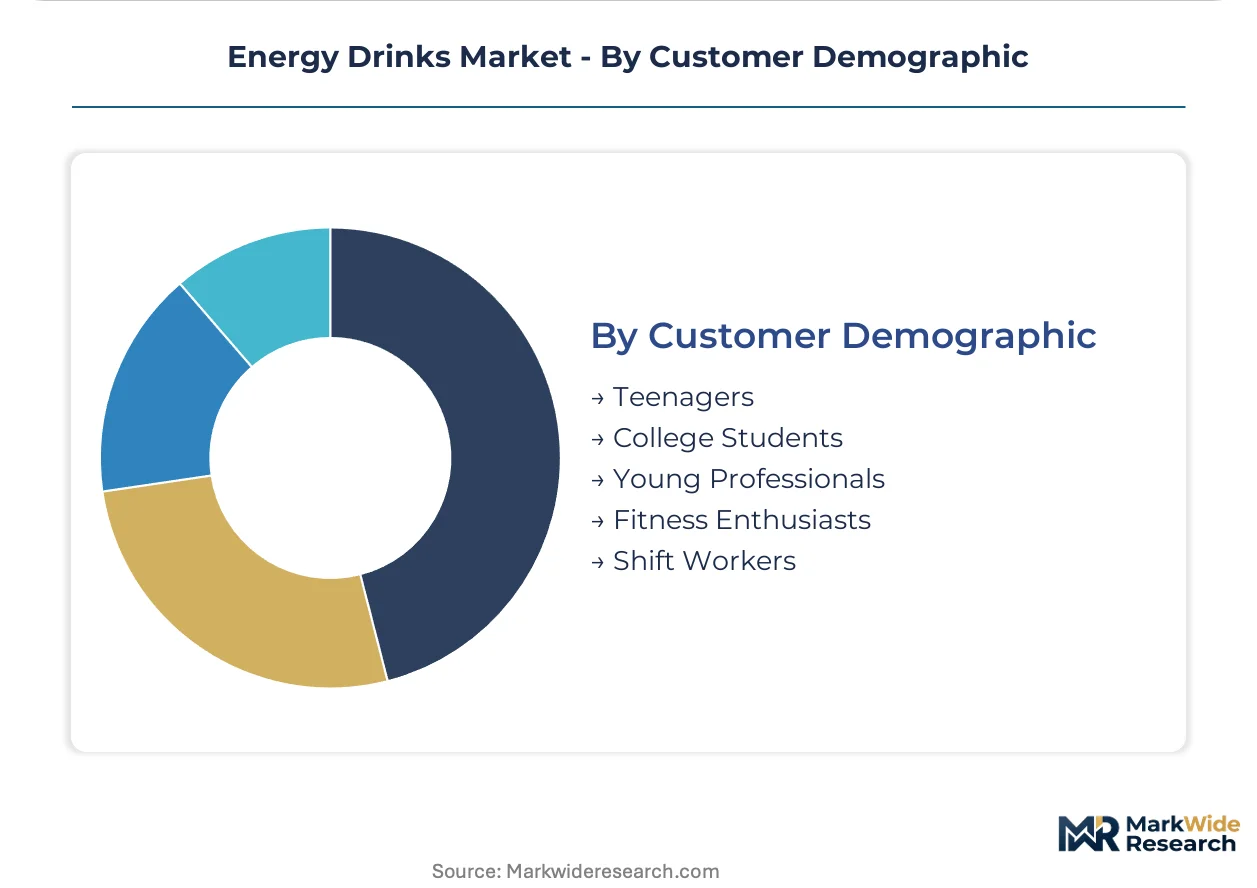
Fitness Enthusiasts and Young Professionals exhibit the most dynamic purchasing patterns, continuously influencing product innovation and market trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The energy drinks market exhibits a nuanced export-import balance, with certain nations driving significant consumption volumes while others emerge as key manufacturing hubs. Consumption patterns are heavily influenced by local cultural preferences and regulatory frameworks. This global dynamic shapes regional development and product availability.
United States
United States demand for energy drinks is concentrated among fitness enthusiasts seeking pre-workout performance enhancement. The U.S. FDA actively scrutinizes caffeine content and labeling, influencing product formulations. California's health-conscious culture fosters innovation, with new brands focusing on natural and organic ingredients gaining traction in urban centers.
Brazil
Brazil's energy drink consumption is driven by a mainstream fitness culture and rising disposable incomes. ANVISA, the national health surveillance agency, oversees ingredient safety and labeling requirements. São Paulo, a major economic center, exhibits strong demand for pre-workout beverages within its expanding gym and sports facilities.
India
India represents an emerging market for energy drinks, fueled by a growing young professional demographic seeking alertness. The FSSAI sets stringent standards for ingredients and additives, creating compliance challenges for manufacturers. Delhi-NCR, a major metropolitan region, shows substantial growth in energy drink sales, especially within its expanding urban consumer base.
United Kingdom
United Kingdom consumers show a strong preference for sugar-free energy drink options, influenced by health trends. The UK’s Soft Drinks Industry Levy has compelled widespread reformulation to reduce sugar content. London's urban professionals frequently consume energy drinks for midday boosts, driving sales in convenience stores across the city.
Germany
Germany's market for energy drinks is influenced by a strong health and wellness segment, valuing functional ingredients. The European Food Safety Authority (EFSA) guidance on safe consumption levels influences product marketing claims. Berlin, a vibrant urban center, shows increasing adoption of functional beverages with nootropics among its professional and student populations.
Energy Drinks Market Key Industry Players
Concentration sits with global beverage giants leveraging extensive distribution networks and robust marketing budgets. The market features a tiered structure, from established players with broad appeal to specialized brands targeting niche demographics. Strategic archetypes include mass-market volume drivers, premium lifestyle brands, and health-focused functional beverage producers. Dominant competitive moves involve continuous portfolio diversification and aggressive sports and lifestyle marketing campaigns.
Among global beverage giants, PepsiCo exemplifies the power of an extensive retail footprint, integrating brands like Rockstar into its vast distribution network to reach diverse consumer segments. Red Bull, a prominent European-based company, consistently occupies a premium market position through aggressive sports and lifestyle marketing initiatives that cultivate a distinct brand image. Celsius Holdings, a US-based firm, represents the health and wellness segment, differentiating its offerings with fitness-focused formulations that gain traction in gyms and specialty stores, appealing to a health-conscious demographic.
| Leading Market Players |
|---|
| PepsiCo |
| Eastroc Super Drink |
| Red Bull |
| Suntory Beverage & Food |
| National Beverage |
| Monster Beverage |
| Celsius Holdings |
| GURU Organic Energy |
| Rockstar |
| Others |
Cost & Logistics Intelligence
Large-scale production economies for essential inputs like aluminum cans and synthetic caffeine dictate significant supply concentration. This concentration directly influences pricing power and establishes effective price floors for mass-market energy drink formulations.
Pricing Analysis
Mass market retailers anchor the energy drink pricing structure, primarily operating on contract-based long-term offtake agreements. Premium-mid-economy pricing differentiation exists, driven by brand premium from extensive marketing and formulation complexity, such as nootropics. Pricing pressure stems from input price volatility for synthetic caffeine and aluminum cans. Mass market retailers exhibit high price sensitivity, whereas specialty stores serving fitness enthusiasts tolerate higher price points for niche products.
Supply Chain Analysis
Fluctuations in inbound logistics costs, particularly for container shipping from Asia, impact raw material procurement for energy drinks. Geographic supply concentration for key inputs centers on China for synthetic caffeine and Brazil for natural sweeteners, while the industry relies on critical raw materials like taurine, B vitamins, and aluminum for packaging. Commodity price volatility for these inputs represents a structural supply chain risk. Downstream distribution runs through convenience stores for impulse buys and online retail for bulk purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy drinks market presents a strategic landscape where regulatory navigation and advanced formulation science represent critical capability gaps. Brands must master ingredient sourcing and compliance to sustain growth.
For Market Incumbents: Shield existing market share by acquiring specialized functional beverage brands focused on nootropics or adaptogens. Deepen retail channel partnerships with supermarkets and convenience stores to counter beverage category substitution from ready-to-drink coffees. Invest in advanced regulatory compliance expertise to navigate disparate global standards from the FDA and EFSA, protecting product formulations.
For New Entrants and Emerging Players: Differentiate on ingredient innovation, targeting e-sports formulations with nootropics for cognitive enhancement. Explore powder formats for customizable and portable energy solutions, appealing to health-conscious consumers in the United States. Leverage direct-to-consumer online channels with subscription models to build brand loyalty and bypass traditional distribution gatekeepers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized functional beverage producers with proprietary blends and strong intellectual property in adaptogens and nootropics. The long-term viability remains strong for brands effectively navigating regulatory shifts and consumer health preferences. Target acquisition archetype includes niche brands with established health and wellness positioning. Growth in plant-based caffeine market share serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Portfolio Diversification | Expanding into non-carbonated and powder formats captures wider consumer preferences beyond traditional carbonated drinks. |
| Targeted E-Sports Marketing | Engaging the dedicated global gaming audience creates new demand for cognitive enhancement formulations. |
| Direct-to-Consumer Channel Expansion | Building online subscription models bypasses traditional retail, offering direct brand control and customer insights. |
| Natural Ingredient Sourcing | Leveraging plant-based caffeine and organic extracts attracts health-conscious consumers wary of synthetic additives. |
| Regulatory Compliance Specialization | Proactive adherence to FDA and EFSA guidelines ensures market access and builds consumer trust in product safety. |
Research Approach
A standing panel of R&D chemists, marketing directors, regulatory compliance officers, and retail buyers provided ongoing calibration to the analysis. This involved combining primary interviews with industry stakeholders and secondary validation from sources like FDA filings, EFSA reports, and company annual reports. Both bottom-up and top-down triangulation methods ensured data consistency across all segments.
Outputs underwent rigorous consistency checks against external benchmarks and published industry reports over the projection horizon. The analytical framework modeled segmentation by product type, distribution channel, consumption occasion, customer demographic, and regional regulatory frameworks. CAGRs derived from historical trends incorporated ingredient price forecasts and regulatory compliance costs.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory changes or sudden shifts in consumer health perceptions would require recalibration. Forecasts reflect assumptions regarding market dynamics and technological advancements across the analysis window. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Isotonic Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Ice Tea Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market