
 Global Mobile Phone Insurance Ecosystem Market | 2026-2036
Global Mobile Phone Insurance Ecosystem Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Phone Insurance Ecosystem Market Intelligence
Comprehensive accidental damage and screen replacement coverage is collapsing the traditional distinction between OEM-led warranties and third-party insurance products. Insurers like Asurion sustain deep partnerships with mobile carriers such as AT&T to offer point-of-sale policies. Meanwhile, device manufacturers like Apple Inc. leverage their powerful brand ecosystem through proprietary plans, creating a highly competitive environment for specialized insurance providers.
The mobile phone insurance ecosystem comprises a network of insurers, carriers, and service providers offering policies that cover device malfunction, damage, theft, or loss. These policies are often defined by specific claim triggers, such as screen cracks or liquid damage, and provide for repair or replacement. Within insurance plan types, accidental damage protection shows significant momentum over basic warranties. Distribution is increasingly dominated by mobile carrier stores and direct integration into e-commerce platforms at the point of device purchase.
Regulatory frameworks like the EU's General Data Protection Regulation (GDPR) and oversight from bodies such as the US Federal Trade Commission (FTC) govern data privacy and transparency in policy terms. These regulations directly shape how insurers handle customer data and communicate coverage limitations. The critical decision for market participants is how to structure partnerships between device OEMs, mobile carriers, and underwriters to secure customer loyalty.
Market Dynamics
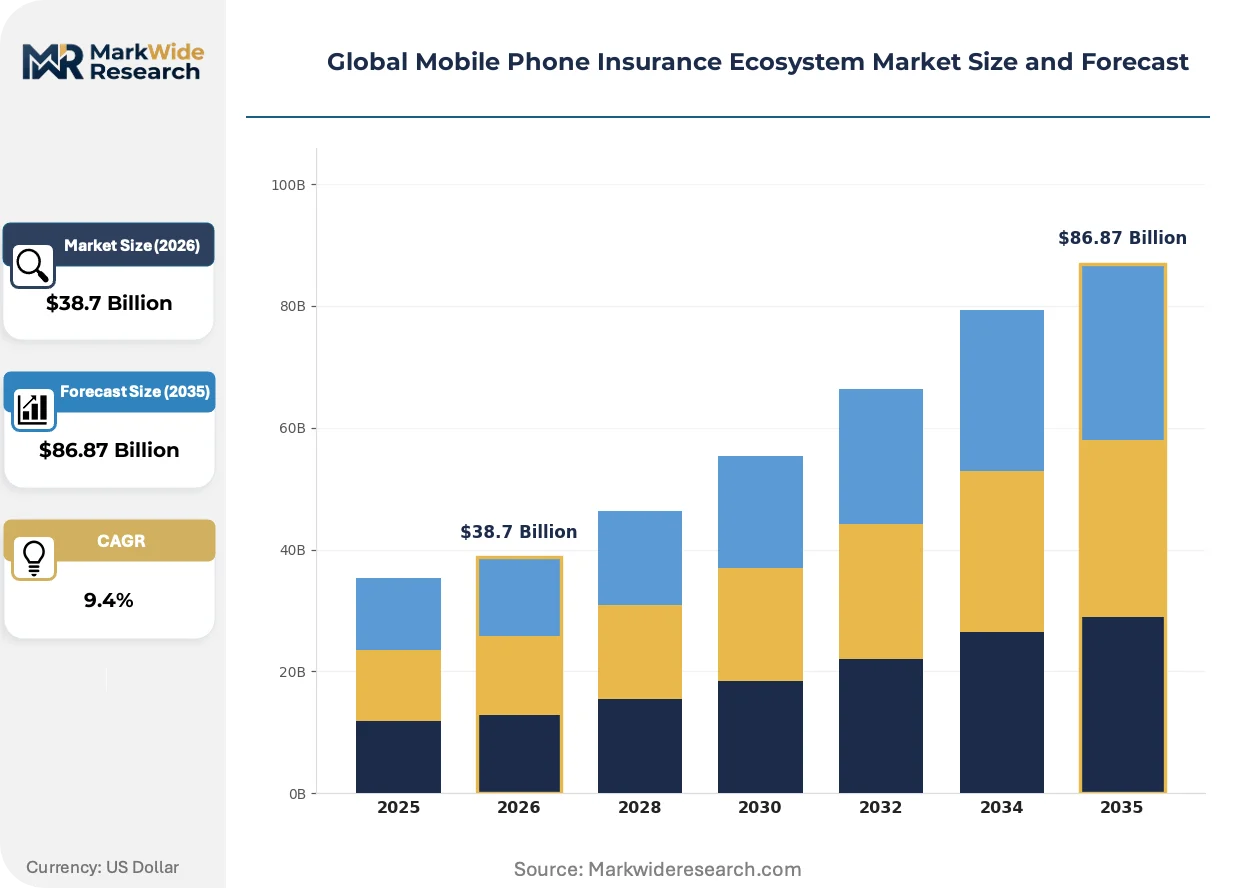
The convergence of OEM-led protection plans and third-party insurance products is the central force shaping the ecosystem. This blurs traditional market boundaries and intensifies competition for customer attachment at the point of device sale, forcing providers to differentiate on service and integration.
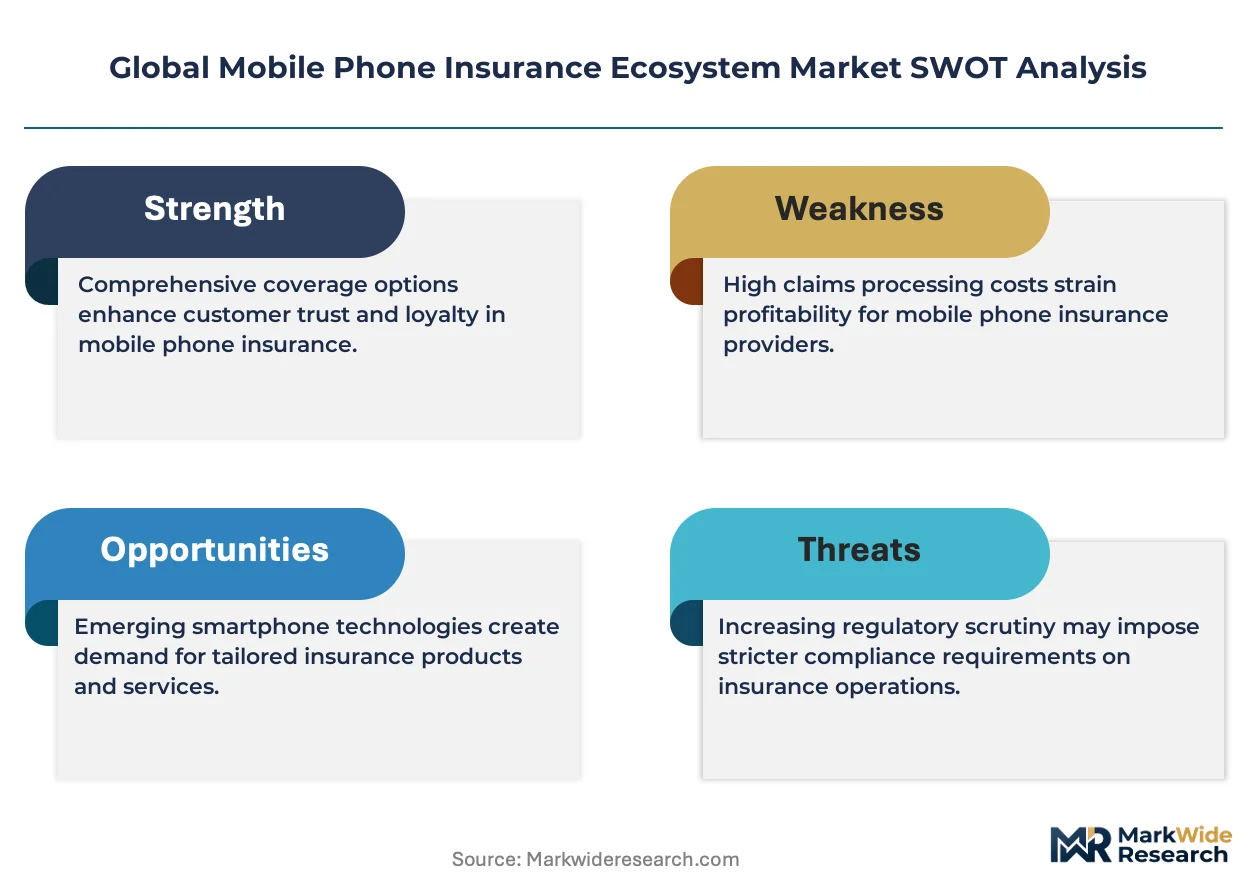
Growth Catalysts
- AI in Claims Processing:The integration of artificial intelligence for fraud detection and claims automation accelerates service delivery, improving operational efficiency and customer satisfaction for insurers.
- Corporate Demand Growth:Enterprises are increasingly purchasing bulk insurance policies to protect their large fleets of corporate-issued smartphones and tablets from accidental damage and loss.
- Premium Device Sales:High-volume sales of premium smartphones in markets like China, with higher device values and repair costs, directly stimulate consumer demand for comprehensive insurance coverage.
Market Restraints
- Regulatory Compliance Overhead:Adherence to data privacy regulations like the EU's General Data Protection Regulation (GDPR) increases operational costs and restricts the use of customer data for personalized underwriting.
- OEM Competition:Device manufacturers leverage powerful brand ecosystems and direct customer access to promote proprietary protection plans, creating a formidable competitive barrier for specialized insurance providers.
- Low Perceived Value:A segment of consumers remains skeptical of the need for phone insurance or finds policy terms confusing, resulting in low adoption rates outside of bundled carrier offerings.
Strategic Opportunities
- Specialized Device Coverage:Developing policies for emerging device form factors, such as foldable smartphones, presents an opportunity to address unique, high-cost repair scenarios not covered by standard plans.
- Embedded Insurance Channels:Integrating insurance offerings directly into e-commerce checkout flows and fintech applications opens new distribution channels beyond traditional mobile carrier stores and direct sales.
- Emerging Market Penetration:Targeting smartphone users in underinsured regions like Brazil and India offers significant growth potential as device ownership and digital service adoption expand rapidly.
Industry Challenges
- Sophisticated Fraud Detection:Insurers face the continuous challenge of identifying and preventing increasingly complex fraud schemes, especially related to claims of device theft or non-accidental damage.
- Partnership Complexity:Structuring and managing profitable partnerships between underwriters, mobile carriers, and authorized service centers requires navigating complex revenue-sharing agreements and service-level commitments.
- Systems Integration:Ensuring seamless data exchange between insurer platforms and the disparate IT systems of multiple device OEMs and retailers is a significant technical hurdle to scalable operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Phone Insurance Ecosystem Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Plan Type: Standard Coverage, Extended Warranty, Accidental Damage Protection, Theft Protection, Screen Replacement Distribution Channel: Direct Insurer Website, Mobile Carrier Stores, E-Commerce Platforms, Retail Electronics Stores, Third-Party Brokers Device Type: Smartphones, Feature Phones, Tablets, Wearable Devices, Portable Media Players Customer Segment: Individual Users, Small Businesses, Corporate Clients, Educational Institutions, Non-Profit Organizations |
| Companies Covered | Apple Inc., Asurion, Assurant, Inc., American International Group, Inc., Allianz, AmTrust International, AT&T, Brightstar Corp., Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Phone Insurance Ecosystem Market Strategic Shifts & Innovations
Technological integration is fundamentally changing service delivery expectations in the mobile insurance sector. The focus is shifting from passive risk coverage to proactive, digitally-enabled support that enhances the overall device ownership experience for customers and streamlines claims.
AI-powered visual diagnostics enable customers to self-assess device damage, such as screen cracks, using a smartphone camera. Insurtechs and third-party administrators are adopting this technology for instant, automated initial loss reporting. This automated triage capability is displacing traditional manual inspection processes, significantly reducing claim cycle times and administrative costs for common damage types.
Right-to-repair legislation in the European Union and several US states mandates that OEMs provide independent repair shops with access to parts, tools, and diagnostic information. This regulatory shift directly impacts the structure of authorized service networks and the economics of repairs. Insurers are consequently re-evaluating their repair partner strategies, especially for common out-of-warranty hardware fixes like screen replacements.
Consumers show a growing preference for subscription-based device protection bundles over standalone, one-time policies. This model, which combines insurance with services like technical support and cloud storage, disrupts the transactional sale at the point of purchase. The shift is most visible in developed markets like the United States and Germany, where carriers use such bundles to boost customer loyalty.
Global Mobile Phone Insurance Ecosystem Market Segmentation
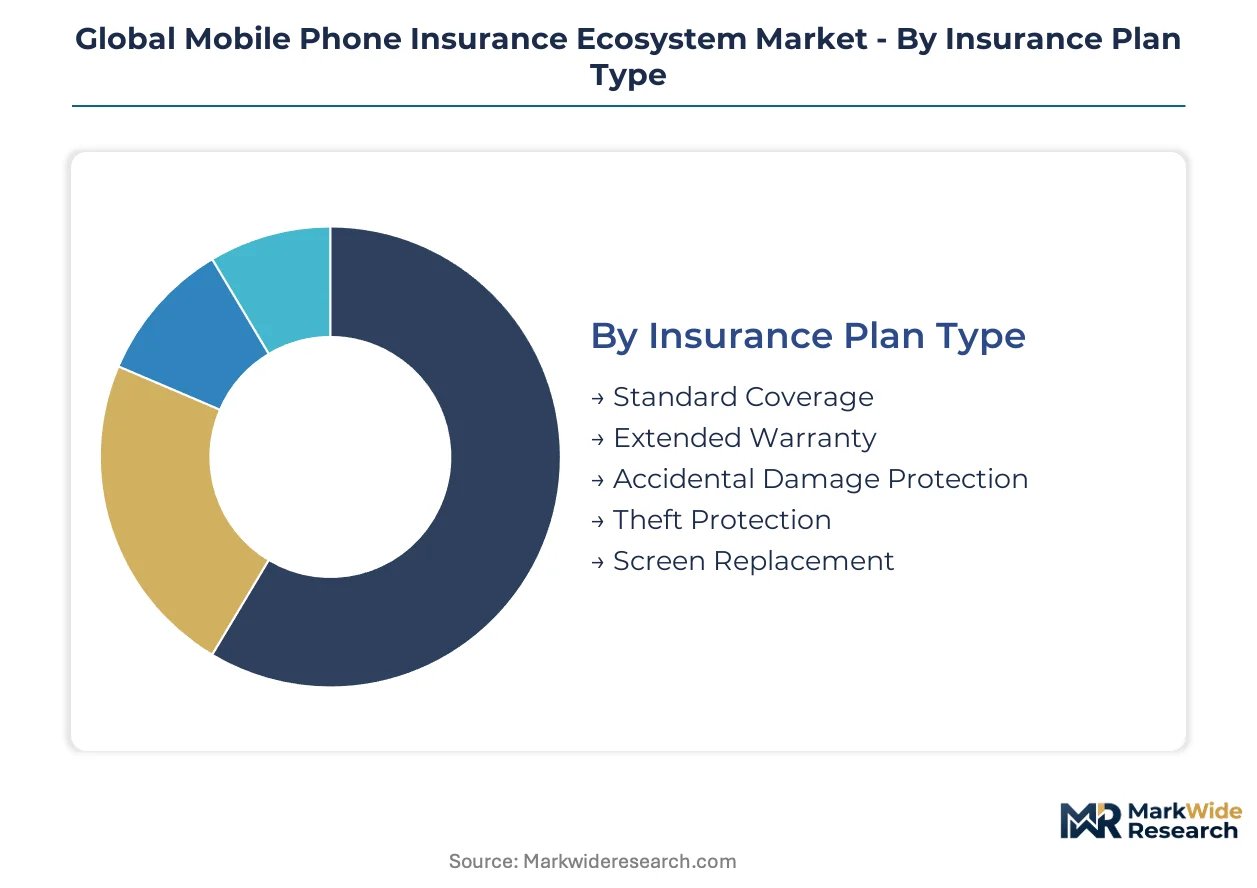
Understanding the diverse needs, distribution models, and device types is critical for market participants in the global mobile phone insurance ecosystem. Segmentation allows insurers to tailor policies and reach specific customer groups effectively, optimizing product development and sales strategies across various geographies.
Insurance Plan Type:
The uptake of specific insurance plan types varies significantly across different global regions, reflecting local consumer priorities and regulatory landscapes.
- Accidental Damage Protection:This coverage protects devices from physical damage resulting from unexpected incidents, such as drops or spills, beyond manufacturing defects. Demand concentrates heavily in markets with high premium smartphone penetration like China, where repair expenses for advanced displays are substantial.
- Screen Replacement:This specialized plan specifically covers the repair or replacement of a device's display panel, a frequent point of vulnerability. Consumer preference for this focused coverage is pronounced in developed economies, driven by the high cost of screen repairs for modern devices.
- Standard Coverage:Offers basic protection against manufacturing defects or limited accidental damage, often bundled with device purchases.
- Extended Warranty:Prolongs the original manufacturer's warranty period, covering mechanical or electrical failures post-initial warranty expiration.
- Theft Protection:Provides financial compensation or device replacement in cases where a mobile phone is stolen, a common concern for users.
Accidental Damage Protection holds the largest share; momentum sits with Screen Replacement due to its targeted value proposition.
Distribution Channel:
The efficiency and cost-effectiveness of various distribution channels heavily influence customer acquisition costs and policy pricing within the ecosystem.
- Mobile Carrier Stores:These physical retail locations of telecommunications providers offer insurance policies directly to customers at the point of device activation or upgrade. This channel thrives in markets like the United States, where carriers leverage bundled offerings to enhance customer loyalty and recurring revenue streams.
- E-Commerce Platforms:Online marketplaces and brand websites integrate insurance offerings directly into the digital checkout process for new device purchases. This digital distribution method is gaining significant traction in India, driven by increasing online shopping penetration and seamless purchase experiences.
- Direct Insurer Website:Allows consumers to purchase policies directly from insurance providers, offering transparency and customization options.
- Retail Electronics Stores:Brick-and-mortar outlets selling electronics often partner with insurers to offer protection plans alongside device sales.
- Third-Party Brokers:Independent agents or firms that facilitate the sale of insurance policies from multiple underwriters to consumers.
Mobile Carrier Stores remain critical for high-volume sales, while E-Commerce Platforms are seeing rapid expansion and reach.
Device Type:
The diverse usage patterns and inherent vulnerabilities of different device types dictate the specific insurance requirements and claim frequencies across the market.
- Smartphones:These advanced mobile devices offer extensive computing capabilities and connectivity, making them the primary focus for insurance providers. Demand for smartphone insurance is universally high, especially in developed markets where premium models represent a significant investment for consumers.
- Tablets:Larger portable computing devices, typically without cellular voice capabilities, are covered for damage, loss, or theft. Corporate clients show increased interest in tablet insurance to protect their mobile workforces and educational institutions for student devices.
- Feature Phones:Basic mobile phones with limited functionality, which typically require less comprehensive and lower-cost insurance options.
- Wearable Devices:Includes smartwatches and fitness trackers, increasingly covered for accidental damage given their active use.
- Portable Media Players:Devices primarily designed for audio and video playback, representing a smaller, niche segment for insurance.
The majority of revenue flows from Smartphones, with emerging growth in Wearable Devices as their adoption increases.
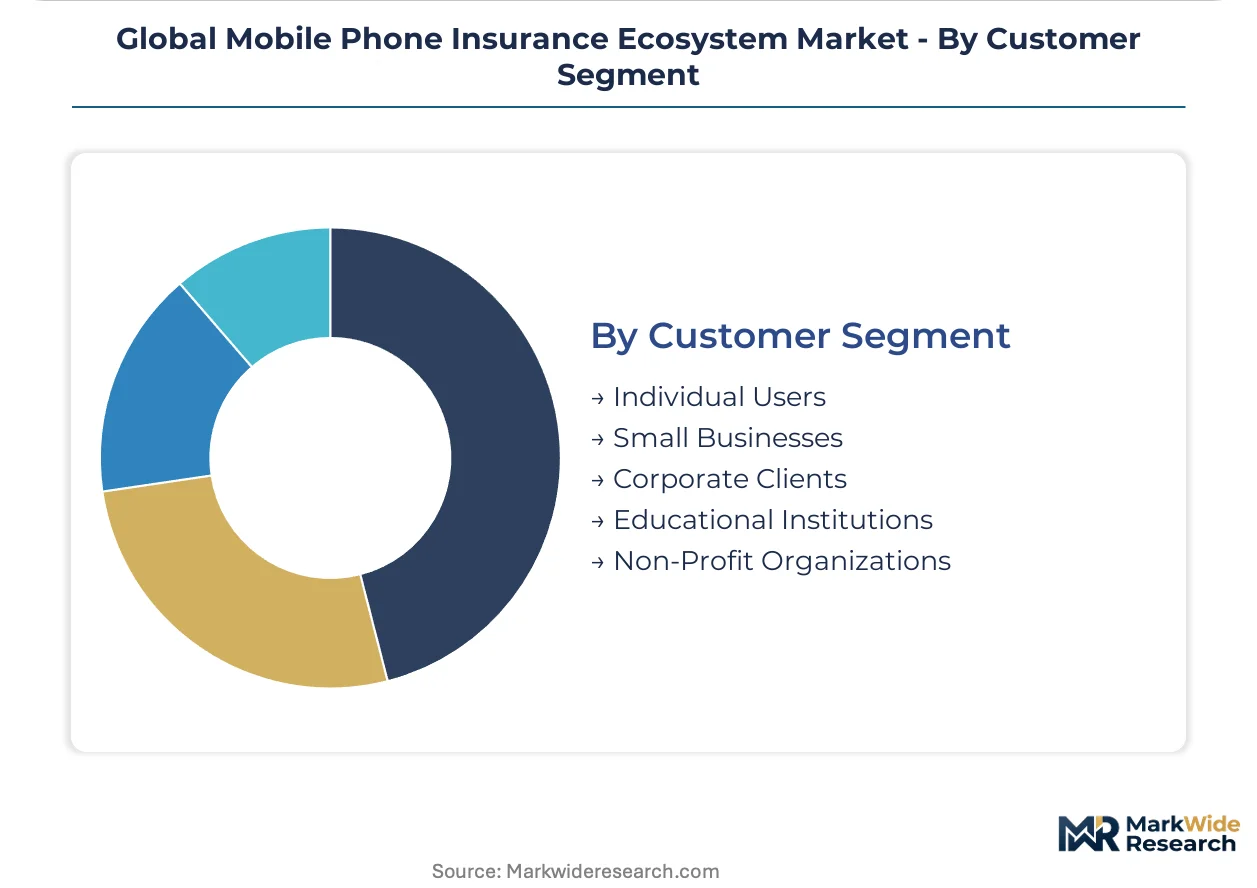
Customer Segment:
The purchasing volume and specific risk profiles of various customer segments significantly influence policy customization and pricing strategies for insurers.
- Individual Users:This segment comprises individual consumers purchasing insurance for their personally owned mobile phones and devices. High volume sales in this segment are observed globally, with particular concentration in markets like Germany where subscription bundles are popular.
- Corporate Clients:Enterprises acquire bulk insurance policies to protect their extensive fleets of company-issued smartphones and tablets. This segment shows significant growth in the US and Europe, driven by the need to safeguard valuable corporate assets and ensure business continuity.
- Small Businesses:Smaller enterprises requiring protection for a limited number of employee devices, often seeking scalable solutions.
- Educational Institutions:Schools and universities insuring devices provided to students or faculty, focusing on accidental damage and theft.
- Non-Profit Organizations:Organizations that insure their mobile devices, often seeking cost-effective solutions for their operational needs.
Individual Users dominate the market, but Corporate Clients are poised for significant expansion, driven by fleet protection needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for mobile phone insurance exhibits distinct patterns, with its evolution and adoption significantly influenced by regional factors. Regulatory frameworks and consumer behaviors shape policy uptake and distribution strategies. Demand for comprehensive device protection concentrates in markets with high premium smartphone penetration.
China
Strong consumer demand in China stems from high premium smartphone sales, where repair expenses for advanced displays are substantial. The Ministry of Industry and Information Technology (MIIT) oversees digital services, impacting insurance product development. Shenzhen's tech manufacturing hub sees continuous innovation in insurance offerings for new devices.
United States
Corporate clients drive significant demand in the United States, seeking to protect extensive fleets of company-issued devices. The Federal Trade Commission (FTC) issues guidelines influencing policy transparency and consumer protection. Atlanta, a major hub for insurance technology providers, fosters deep partnerships with leading mobile carriers.
Germany
Consumers in Germany increasingly prefer subscription-based device protection bundles, moving away from transactional standalone policies. The General Data Protection Regulation (GDPR) strongly influences how insurers handle customer data. Munich's established financial services sector develops innovative digital protection plans for the European market.
India
India presents significant growth potential, driven by rapid e-commerce penetration and expanding smartphone ownership. The Telecom Regulatory Authority of India (TRAI) impacts service offerings related to mobile devices and associated insurance. Bangalore's dynamic tech ecosystem fosters embedded insurance solutions within fintech applications.
Brazil
Expanding smartphone ownership in Brazil creates a substantial, yet underinsured, market for mobile device protection. ANVISA, the national health surveillance agency, also influences consumer protection aspects in various service sectors. São Paulo's bustling financial services hub explores new insurance distribution models to reach this emerging consumer base.
Global Mobile Phone Insurance Ecosystem Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global mobile phone insurance ecosystem. The market exhibits a tiered structure, with device manufacturers, dedicated insurance providers, and mobile carriers all competing for customer attachment. Key archetypes include integrated OEMs leveraging brand loyalty, specialized insurtechs focusing on digital efficiency, and carrier-backed entities offering bundled solutions. Dominant competitive moves involve strategic partnerships to expand distribution and vertical integration into repair service networks.
Among the established players, Asurion exemplifies a dedicated insurance provider, sustaining deep partnerships with mobile carriers to offer point-of-sale policies and extensive service networks. Apple Inc., a prominent device manufacturer, represents the OEM segment, leveraging its powerful brand ecosystem through proprietary protection plans and direct customer access. Global financial services giant Allianz, with its extensive insurance portfolio, occupies a position among traditional underwriters adapting to digital distribution channels and expanding into emerging markets.
| Leading Market Players |
|---|
| Apple Inc. |
| Asurion |
| Assurant, Inc. |
| American International Group, Inc. |
| Allianz |
| AmTrust International |
| AT&T |
| Brightstar Corp. |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements between mobile carriers and insurers are crucial for locking in stable policy pricing and ensuring consistent service network access.
Pricing Analysis
The EU's General Data Protection Regulation (GDPR) dictates the pricing tier structure by increasing operational costs related to data handling. Pricing stratifies across premium, standard, and economy tiers based on device value and coverage scope. Pricing softness reflects intense OEM competition, particularly for bundled offerings. Corporate clients demonstrate lower price sensitivity compared to individual users seeking basic plans.
Supply Chain Analysis
Just-in-time inventory practices for replacement parts characterize the mobile phone insurance supply chain, minimizing lead times for common repairs. This network draws heavily from component manufacturing hubs in China and South Korea, with service centers concentrated in the United States and Germany. Single-source vulnerability for proprietary OEM parts poses a structural risk. Distribution runs through mobile carrier stores and integrated e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile phone insurance market is experiencing early-cycle expansion, driven by the increasing penetration of premium smartphones globally.
For Market Incumbents: Shield existing customer bases by reinforcing point-of-sale partnerships with mobile carriers. Deepen integration with authorized repair networks to counter OEM competition. Invest in AI-powered fraud detection to mitigate rising claims complexity, securing profit margins against emerging insurtech threats. Introduce specialized coverage plans for new device form factors.
For New Entrants and Emerging Players: Under-served niche device segments, such as foldable smartphones, represent a significant service-layer gap for new entrants. Target underinsured regions like India and Brazil with embedded insurance solutions. A digital-first, direct-to-consumer approach integrated with fintech applications offers a penetrable go-to-market angle. Focus on transparent policy terms to build consumer trust.
For Investors and Strategic Acquirers: Capital is best deployed toward insurtechs specializing in AI-driven claims automation and fraud detection for long-term viability. Acquisition targets should possess strong data analytics capabilities and established partnerships with e-commerce platforms. The signal to watch is the increased regulatory alignment across major global regions, indicating market maturation and reduced operational fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI in Claims Processing | Streamlines operations and enhances fraud detection for insurers like Asurion. |
| Expand Embedded Insurance Channels | Opens new distribution avenues through e-commerce and fintech applications in India. |
| Develop Specialized Foldable Device Coverage | Addresses unique, high-cost repair scenarios for emerging device form factors. |
| Strengthen Mobile Carrier Partnerships | Secures point-of-sale distribution and customer loyalty for providers. |
| Penetrate Underinsured Emerging Markets | Captures significant growth potential in regions like Brazil and India. |
Research Approach
The analysis maps insurance plan types, distribution channels, device types, and customer segments, each validated through primary interviews with insurance underwriters and mobile carrier executives. This involved engaging device OEM product managers and e-commerce platform leads. Secondary research drew from regulatory filings (FTC, MIIT), industry association reports, financial news archives, and academic research, triangulated using both bottom-up and top-down approaches.
Outputs were cross-referenced against external benchmarks and industry reports to ensure consistency across the analysis window. The analytical framework modeled segmentation dimensions including insurance plan type, distribution channel, device type, customer segment, and regional market. Compound annual growth rates were derived from historical data analysis and projected market dynamics, with smartphone sales volumes and average repair costs serving as key inputs.
Underlying assumptions cover technological advancements and consumer behavior shifts, with deviation risk concentrated in evolving regulatory frameworks and OEM strategy shifts. New fraud detection methods also pose a potential impact. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Global AI in Auto-Insurance Market
Insurance
Aircraft Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
China Liability Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Spain Group Health Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Reinsurance Market
Insurance
Digital Monetary Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Car Insurance Market
Insurance
United States Dental Insurance Market
Insurance
Canada Health and Medical Insurance Market