
 Aircraft Insurance Market | 2026-2036
Aircraft Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Insurance Market Analysis
Usage-based coverage models are rebalancing how underwriters price risk across flight hours and operational profiles. Munich Re leverages its catastrophe modeling infrastructure to anchor capacity for wide-body hull exposures in volatile geographies. Allianz competes through integrated aviation teams that control both primary placement and reinsurance attachment points. American International Group specializes in war-risk and lessor contingent coverage, extending its footprint across leased commercial jet portfolios.
Aircraft insurance is a specialized risk-transfer instrument covering physical damage to airframes, engines, and avionics alongside third-party and passenger liability exposures; policies incorporate technical parameters including agreed-value hull limits, pilot certification minimums, and territory restrictions tied to ICAO Annex compliance. Its commercial purpose centers on enabling fleet financing, lessor returns, and operational continuity against total-loss events. Liability insurance commands the deepest premium pools given escalating jury awards in passenger injury litigation, while hull insurance maintains steadier loss ratios supported by salvage value recoveries. Per flight coverage is gaining traction among charter services and on-demand operators seeking variable cost structures against fixed annual premiums.
The FAA mandates minimum liability limits for commercial operators under Part 121, while EASA's risk-based oversight framework shapes European carrier retention and reinsurance purchasing. The EU AI Act introduces emerging compliance dimensions for autonomous flight systems that underwriters must incorporate into coverage exclusions and pricing models. Stakeholders should monitor how regulator divergence between Washington and Brussels fragments policy wording standardization and drives compliance cost inflation.
Market Dynamics
Usage-based coverage models are rebalancing risk pricing across flight hours and operational profiles, forcing underwriters to rebuild actuarial frameworks around real-time telemetry data rather than static annual premiums.
Growth Catalysts
- E-commerce logistics expansion:Cargo carriers are expanding coverage purchases as dedicated freighter fleets deepen their integration into express delivery networks.
- FAA drone integration mandates:Evolving airspace regulations are reshaping underwriting requirements for hybrid operations mixing crewed and uncrewed aircraft.
- Hull valuation inflation:Rising replacement costs for commercial jets are driving policy renewals at higher agreed-value limits across United States domestic fleets.
Market Restraints
- Reinsurance capacity concentration:Catastrophe-modeling infrastructure for wide-body exposures concentrates among a handful of Munich-based and Zurich-based carriers.
- Salvage value volatility:Aircraft part-out markets fluctuate with fleet retirement cycles, compressing recoveries on partial-loss hull claims.
- ICAO Annex compliance fragmentation:Divergent territorial restrictions between FAA Part 121 and EASA risk-based frameworks multiply policy wording complexity.
Strategic Opportunities
- Autonomous flight systems:The EU AI Act introduces emerging compliance dimensions that underwriters can incorporate into specialized coverage exclusions and pricing models.
- Per-flight charter coverage:On-demand operators seek variable cost structures, creating white space for micro-duration policies against fixed annual premiums.
- Lessor contingent products:Leased commercial jet portfolios require war-risk and contingent coverage extensions that primary carriers can anchor.
Industry Challenges
- Actuarial talent scarcity:Underwriters lack sufficient personnel trained in telemetry-based pricing models and real-time flight data interpretation.
- Legacy system integration:Incumbent policy administration platforms struggle to ingest streaming flight-hour data for dynamic premium adjustments.
- Cross-border claims adjudication:Jurisdiction shopping in passenger injury litigation complicates liability reserve calculations across multiple legal systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Insurance Market |
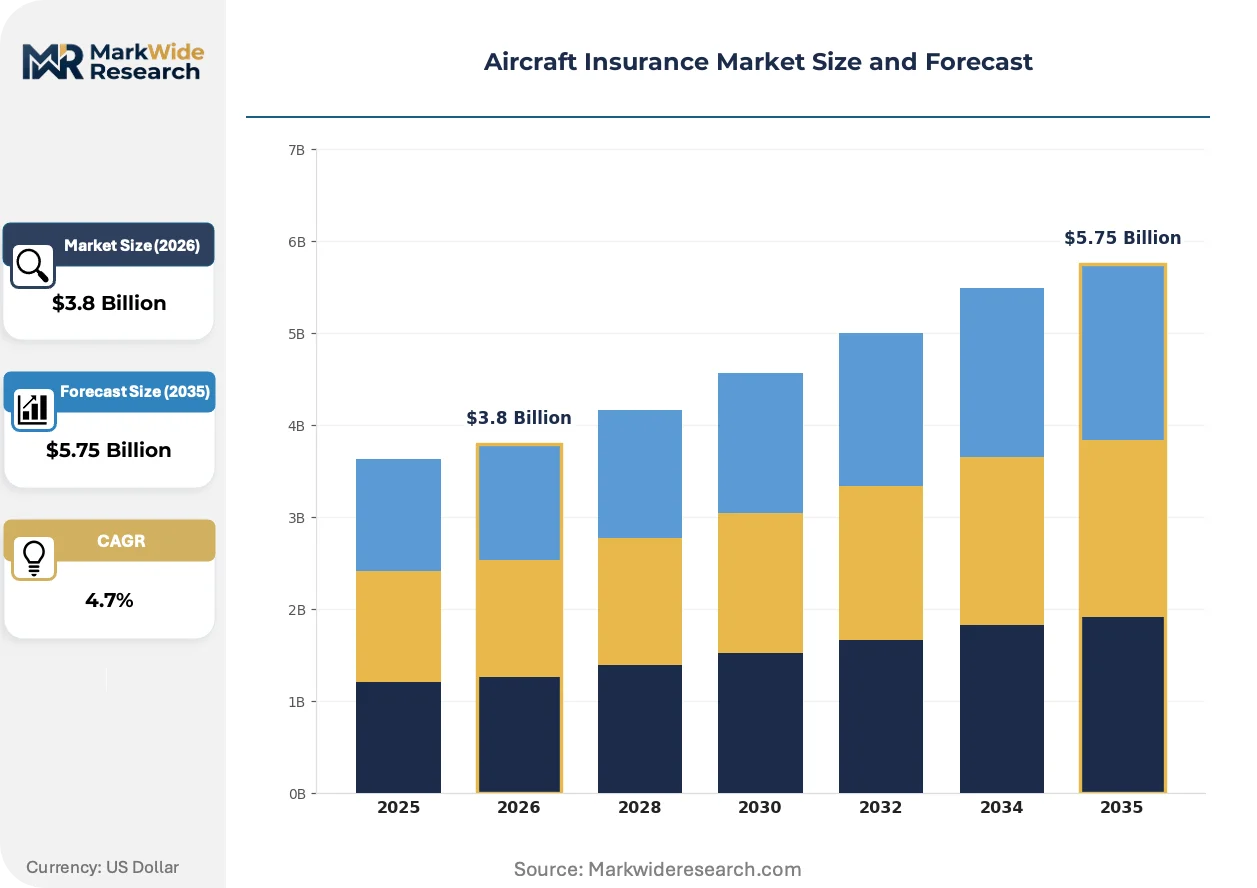
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Liability Insurance, Hull Insurance, Ground Risk Insurance, Passenger Insurance End User: Airlines, Cargo Carriers, Private Owners, Charter Services Coverage Type: Full Coverage, Third-Party Coverage, Limited Coverage, Per Flight Coverage Aircraft Type: Commercial Jets, Private Planes, Helicopters, Cargo Aircraft |
| Companies Covered | American International Group, Allianz, AXA, Chubb, Berkshire Hathaway, Munich Re, Willis Towers Watson, Marsh, Tokio Marine HCC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Insurance Market Emerging Trajectories
Telematics-enabled underwriting is collapsing the distinction between hull and liability pricing, while regulatory divergence between Washington and Brussels fragments standard policy wordings.
Parametric flight-data triggers are electrifying how underwriters structure coverage attachments. Sensors embedded in avionics systems stream engine performance metrics and flight-path deviations to carrier data lakes in real time. Cargo operators and fractional-ownership fleets are adopting these instruments fastest, seeking premium reductions for demonstrated risk-mitigation behaviors. This sensor infrastructure is electrifying competitive positioning among carriers that can price policies at the individual flight-segment level rather than annual fleet aggregates.
The EU AI Act is imposing algorithmic transparency requirements on autonomous flight system certifications. Underwriters must now model coverage exclusions around explainability mandates for machine-learning-driven navigation decisions. European carriers operating hybrid airspace routes face the steepest compliance cost inflation, with many restructuring reinsurance attachment points to isolate AI-related liability exposures in separate treaty layers.
Charter services are unbundling traditional annual policies into flight-hour blocks purchased through digital placement platforms. These transactional coverage models displace broker-mediated annual renewals for on-demand operators seeking working-capital flexibility. The shift is most visible in United States regional aviation markets, where fractional-ownership growth and air-taxi networks concentrate demand for just-in-time risk transfer instruments.
Aircraft Insurance Market Segmentation
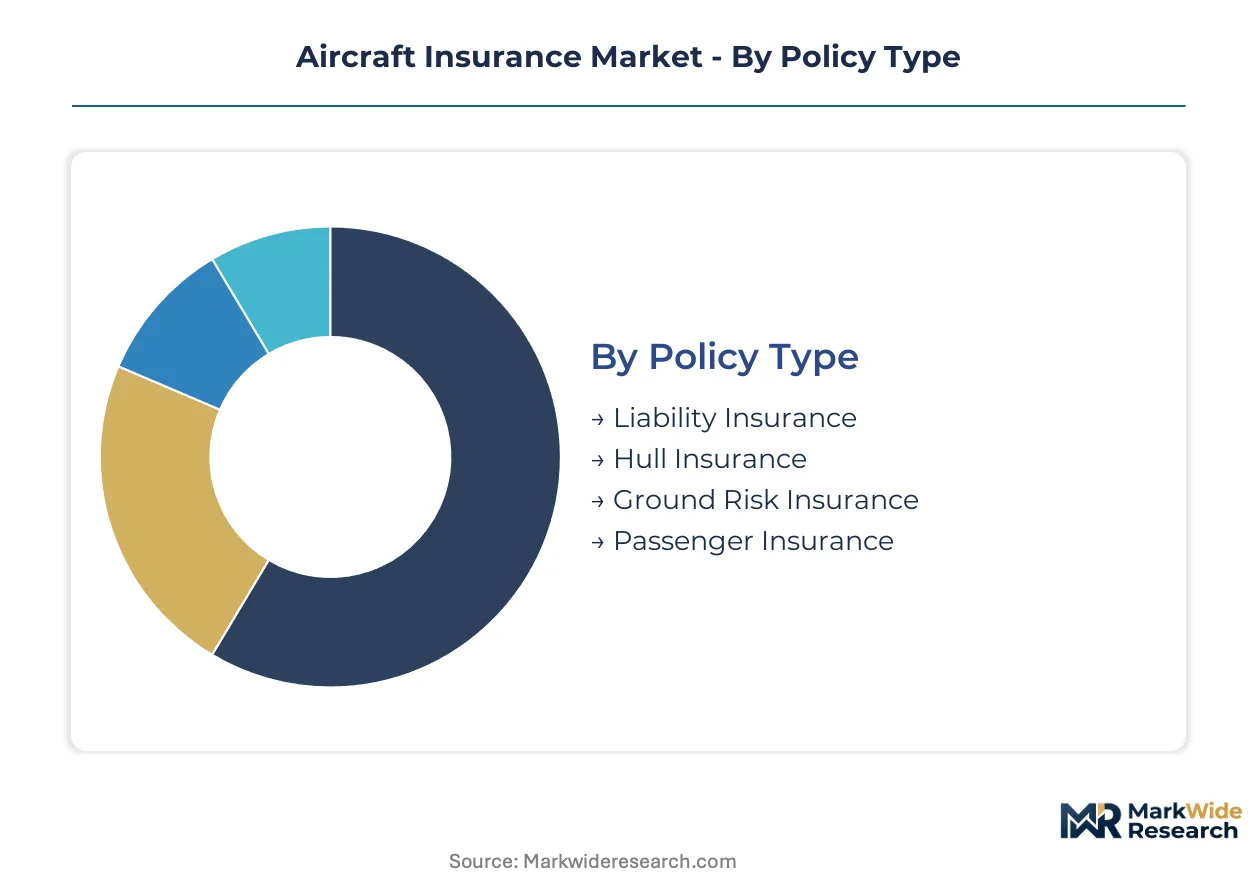
Segmentation in aircraft insurance reflects divergent risk profiles across operational models and asset classes. Underwriters price coverage using distinct actuarial frameworks for each axis, from hull valuation methodologies to liability exposure calculations.
Policy Type:
Liability limits and hull valuation specifications define how carriers structure capital reserves and reinsurance attachments.
- Liability Insurance:Covers third-party bodily injury and property damage alongside passenger claims. Demand concentrates among United States carriers facing escalating jury awards in personal injury litigation, where verdict inflation drives retention point adjustments.
- Hull Insurance:Protects physical damage to airframes, engines, and avionics through agreed-value or actual cash value structures. European operators under EASA oversight favor this coverage type as rising replacement costs for narrow-body fleets force policy limit recalibrations.
- Ground Risk Insurance:Addresses damage occurring while aircraft are stationary, including hangar fires and taxiing incidents. Private owners and fixed-base operators purchase this coverage most frequently.
- Passenger Insurance:Provides supplemental personal accident coverage beyond standard liability limits. Charter services bundle this into per-flight pricing models.
Liability Insurance leads on scale; Hull Insurance leads on momentum.
End User:
Customer procurement patterns vary sharply between scheduled service operators and on-demand aviation providers.
- Airlines:Scheduled carriers under Part 121 mandates purchase comprehensive annual policies with high attachment points. United States legacy carriers dominate premium volume through fleet-wide renewals covering hundreds of hulls.
- Cargo Carriers:Dedicated freighter operators structure coverage around route-specific risk profiles and night-flight exposure patterns. E-commerce logistics networks in Germany and the Netherlands are expanding coverage purchases fastest as express delivery volumes climb.
- Private Owners:Individual aircraft holders favor limited liability limits with high deductibles to manage fixed ownership costs.
- Charter Services:On-demand operators are adopting per-flight coverage blocks purchased through digital platforms rather than traditional annual renewals.
Airlines dominate absolute premium generation; Cargo Carriers are expanding most quickly.
Coverage Type:
Contract structures range from all-risk protection to transactional micro-duration instruments.
- Full Coverage:Comprehensive protection spanning hull physical damage, third-party liability, and passenger claims in unified policy wordings. Major airlines in France and the United Kingdom require this structure to satisfy lessor and financing covenants.
- Third-Party Coverage:Stripped-down liability protection excluding hull damage, purchased by operators with self-insured retention programs or captive arrangements.
- Limited Coverage:Named-peril policies covering specific risk categories such as war risk or terrorism exclusions. Operators flying conflict-adjacent routes in the Middle East layer this coverage atop primary policies.
- Per Flight Coverage:Transactional policies activated for individual flight segments through telemetry-triggered placement platforms. United States regional air-taxi networks and fractional ownership fleets are driving adoption of this variable-cost structure.
Full Coverage anchors the market; Per Flight Coverage is gaining share fastest.
Aircraft Type:
Hull valuation methodologies and loss ratio patterns diverge materially across platform categories.
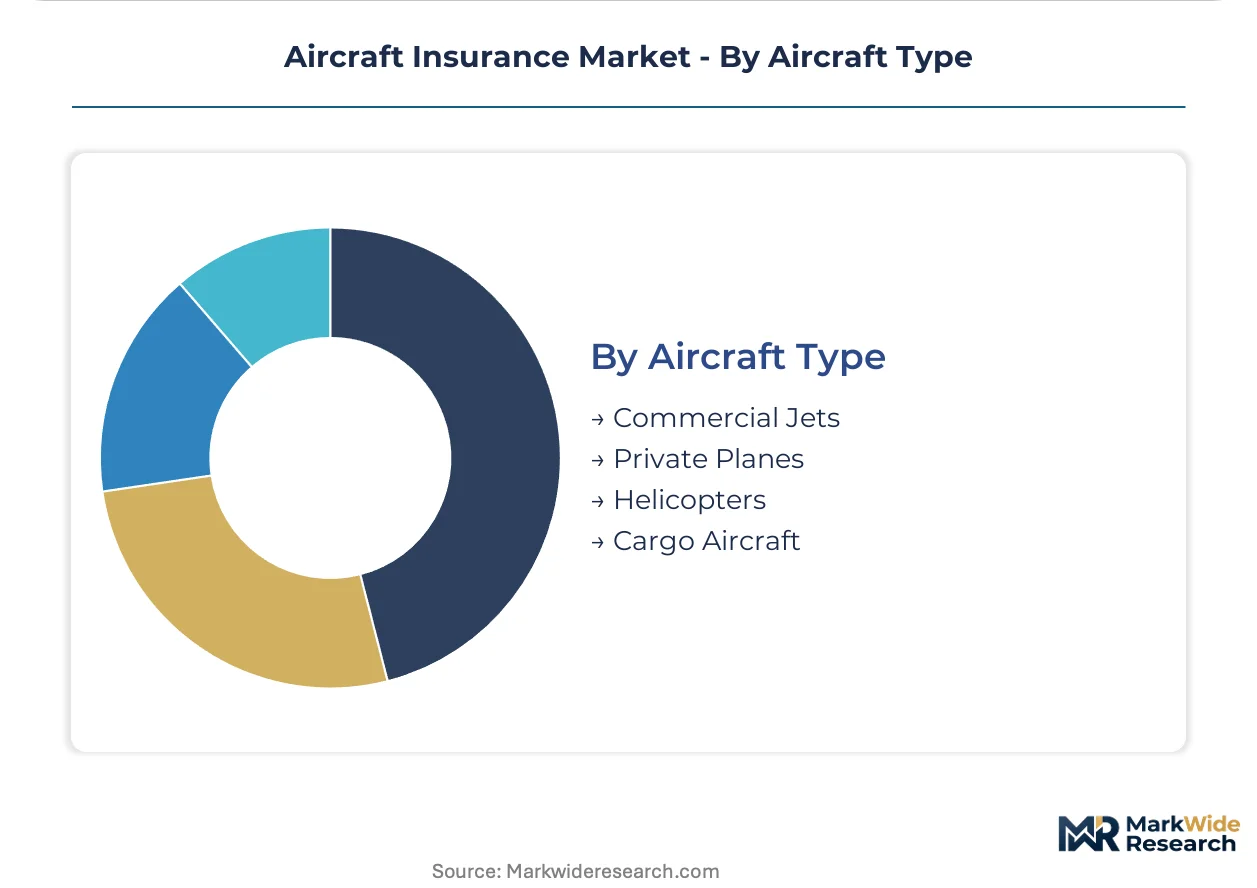
- Commercial Jets:Narrow-body and wide-body aircraft requiring agreed-value hull limits tied to manufacturer list prices. United States domestic carriers are renewing aging fleet policies amid rising valuations for Boeing and Airbus platforms.
- Private Planes:General aviation aircraft under 12,500 pounds with lower liability limits and simplified underwriting requirements. Owner-operators in Texas and Florida represent concentrated demand pockets.
- Helicopters:Rotorcraft with specialized coverage for wire-strike, rollover, and offshore operations. Gulf of Mexico energy transport and emergency medical services drive renewal activity.
- Cargo Aircraft:Dedicated freighter fleets including converted passenger jets and purpose-built haulers. German and Dutch express logistics operators are deepening coverage purchases as e-commerce fulfillment networks expand dedicated capacity.
Commercial Jets generate the deepest premium pools; Cargo Aircraft show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates deeper premium pools than Germany, yet Dutch cargo operators are expanding coverage purchases faster as e-commerce logistics networks multiply dedicated freighter capacity.
United States
Domestic carriers renew aging fleet policies as rising hull valuations for Boeing and Airbus platforms drive agreed-value limit recalibrations. The FAA mandates minimum liability thresholds under Part 121 for scheduled operators. Dallas-Fort Worth and Atlanta anchor the largest concentration of legacy carrier underwriting activity.
Germany
Express logistics operators in the Rhine-Ruhr corridor deepen coverage purchases for dedicated freighter fleets serving pan-European fulfillment networks. EASA's risk-based oversight framework shapes retention and reinsurance purchasing patterns. Frankfurt's insurance cluster hosts multiple aviation underwriting teams pricing narrow-body hull exposures.
Netherlands
Amsterdam-Schiphol cargo handlers expand per-flight coverage adoption as e-commerce volumes strain existing annual policy structures. The EU AI Act introduces compliance dimensions for autonomous flight systems that underwriters must incorporate into pricing models. Rotterdam's logistics hub concentrates demand for variable-cost micro-duration instruments.
United Kingdom
London's specialty insurance market retains dominance in war-risk and lessor contingent coverage placement for leased commercial jet portfolios. Lloyd's of London syndicates structure multi-layered treaties isolating terrorism and conflict-zone exposures. The capital's broker networks mediate cross-border placements for Middle East and African carrier risks.
Japan
Tokio Marine HCC and domestic carriers price hull coverage for narrow-body fleets serving regional routes across East Asian hubs. METI's aviation safety standards influence technical underwriting parameters for pilot certification minimums. Osaka-Kansai's maintenance clusters generate concentrated demand for ground-risk and taxiing incident coverage.
Aircraft Insurance Market Vendor Landscape
Top-tier vendors anchor global capacity for wide-body hull exposures, while regional specialists compete through per-flight and micro-duration product innovation. The market structures around three tiers: global reinsurers controlling catastrophe-modeling infrastructure, integrated primary carriers managing both placement and attachment points, and digital-native intermediaries unbundling traditional annual renewals. Strategic moves concentrate on telemetry-data partnerships and autonomous flight exclusion restructuring.
Within the integrated primary tier, Allianz and American International Group exemplify divergent specialization vectors. Allianz occupies a position emphasizing aviation team integration across primary placement and reinsurance attachment points. American International Group represents the war-risk and lessor contingent coverage archetype, anchoring capacity for leased commercial jet portfolios. Munich Re sits within the global reinsurance tier, leveraging catastrophe-modeling infrastructure to price volatile geography exposures.
| Leading Market Players |
|---|
| American International Group |
| Allianz |
| AXA |
| Chubb |
| Berkshire Hathaway |
| Munich Re |
| Willis Towers Watson |
| Marsh |
| Tokio Marine HCC |
| Others |
Supply Flow & Price Mechanics
Catastrophe-modeling capability divergence between Zurich-based reinsurers and regional primary carriers manifests in both premium rate structures and capital deployment patterns across hull exposure layers. Munich Re's proprietary risk engines command pricing power for wide-body fleets operating volatile geographies, while smaller underwriters compete through telemetry-enabled per-flight instruments that compress distribution costs.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for cargo hull coverage as e-commerce logistics operators expand dedicated freighter fleets. Three-tier pricing structure across premium catastrophe-modeled, standard actuarial-rated, and economy telemetry-based tiers differentiates carriers by data infrastructure depth. Cost compression in the standard tier is intensifying because salvage value volatility compresses partial-loss recoveries. Cargo carriers in the Rhine-Ruhr corridor show least price sensitivity given financing covenant requirements, while United States regional charter services demonstrate highest sensitivity as they migrate from annual to per-flight structures.
Supply Chain Analysis
Actuarial talent scarcity in London and Zurich constrains underwriting capacity expansion for hybrid airspace operations mixing crewed and uncrewed aircraft. Risk capital concentrates in Switzerland, Germany, and the United Kingdom, with Lloyd's of London syndicates anchoring war-risk placement. Raw material dependencies include aviation-specific reinsurance treaties, catastrophe-modeling software licenses, and telemetry sensor hardware. Single-source vulnerability runs through Munich Re's proprietary exposure engines. Distribution runs through broker-mediated annual renewals for legacy carriers and digital placement platforms for on-demand operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft insurance operates as a late-cycle quality story where hull valuation inflation and jury award escalation are concentrating demand toward carriers with integrated primary-reinsurance capabilities and catastrophe-modeling depth.
For Market Incumbents: Hedge telemetry-enabled entrants by acquiring flight-data analytics capabilities or partnering with avionics sensor providers before per-flight pricing commoditizes annual policy structures. Defend margin position through captive reinsurance vehicles that isolate AI-related liability exposures from traditional hull coverage, responding to EU AI Act compliance cost inflation. Prioritize certification investment in FAA Part 121 and EASA risk-based framework expertise to capture renewal activity from aging United States and European fleets. For New Entrants and Emerging Players: The premium-economy gap in per-flight coverage for fractional-ownership and air-taxi networks offers white-space entry with lower capital requirements than full annual policy capacity. Target United States regional aviation markets where Dallas-Fort Worth and Atlanta concentration creates broker inefficiency. Pursue digital-native go-to-market angles through telemetry-triggered placement platforms that unbundle traditional broker relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where actuarial talent scarcity and legacy system integration costs strand mid-tier carriers without proprietary data infrastructure. Long-term viability favors vertically integrated aviation teams controlling both primary placement and reinsurance attachment points. Acquisition target archetype: regional specialists with established cargo carrier relationships and nascent telemetry capabilities. The signal to watch is FAA drone integration mandate implementation pace, which could accelerate hybrid airspace coverage demand beyond current modeling capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Data Partnership | Avionics sensor integration enables per-flight pricing granularity against annual premium structures. |
| AI Liability Treaty Restructuring | EU AI Act compliance requires separate reinsurance layers for autonomous navigation exposure isolation. |
| Cargo Freighter Capacity Expansion | E-commerce logistics growth in Germany and Netherlands drives dedicated fleet coverage demand. |
| Legacy System Modernization | Real-time flight-hour data ingestion replaces static annual premium actuarial frameworks. |
| War-Risk Syndicate Participation | Lloyd's of London placement dominance in lessor contingent coverage anchors leased portfolio returns. |
Methodological Framework
Coverage spans the United States, Germany, the Netherlands, the United Kingdom, and Japan, with primary inputs from each region's aviation underwriting clusters. Primary interviews with aviation underwriters, reinsurance treaty brokers, cargo carrier risk managers, and regulatory compliance officers combined with secondary validation from FAA Part 121 filings, EASA oversight reports, EU AI Act documentation, and Lloyd's of London syndicate disclosures. Bottom-up premium volume estimates triangulated against top-down hull valuation and fleet deployment data.
Granularity-level modeling disaggregated the analysis window by policy type, end user, coverage structure, and aircraft platform category. Segmentation dimensions included liability versus hull exposure, scheduled airline versus cargo operator versus charter service procurement patterns, full coverage versus per-flight contract structures, and commercial jet versus cargo aircraft hull valuation methodologies. CAGRs derived from fitted trend analysis of premium volume against fleet expansion and valuation inflation trajectories. Forecast inputs incorporated FAA drone integration mandate timelines and EU AI Act implementation pacing.
Caveats apply where FAA regulatory divergence from EASA frameworks, salvage value volatility in aircraft part-out markets, or reinsurance capacity concentration among Zurich-based carriers could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Global Home Insurance Market
Insurance
EV Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
Europe Parametric Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
US Travel Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
United States Bancassurance Market
Insurance
Internet of Things Insurance Market
Insurance
China Online Insurance Market
Insurance
Art Insurance Market
Insurance
Title Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
China Property and Casualty Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Commercial Earthquake Insurance Market