
 North America Financial Advisory Services Market | 2026-2036
North America Financial Advisory Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Financial Advisory Services Market Outlook
The United States is reconfiguring its wealth management infrastructure as advisor headcount expands across Texas and Florida to capture migrating high net-worth households. Morgan Stanley Wealth Management leverages its integrated banking platform to sustain cross-selling momentum in ultra-high-net-worth segments. J.P. Morgan Wealth Management anchors its competitive position through proprietary alternative investment access. Edelman Financial Engines differentiates via scaled digital advice delivery hybridized with human planner touchpoints.
Financial advisory services encompass fee-based professional guidance on investment allocation, tax-efficient structuring, estate planning, and risk mitigation delivered through personalized client relationships governed by fiduciary or suitability standards. Practitioners deploy Monte Carlo simulation engines, liability-driven frameworks, and tax-loss harvesting algorithms to optimize after-tax, risk-adjusted portfolio outcomes across multi-generational wealth horizons. Wealth management commands the deepest margin pools due to recurring asset-based fees and sticky multi-service relationships, while investment advisory competes on scale and performance-based engagement models attract sophisticated institutional clients seeking aligned incentive structures. Tax consulting and risk management segments mature in regulatory complexity, creating specialist premium opportunities for firms with certified public accountant and chartered financial analyst depth.
SEC registration requirements, FINRA suitability rules, and state-level fiduciary standards collectively shape advisor compensation transparency and product recommendation accountability across the United States and Canada. The Department of Labor's evolving fiduciary definition and Canadian Securities Administrators' client-focused reforms pressure commission-based revenue models toward fee-only or fee-based structures. Stakeholders must monitor regulatory divergence between SEC best-interest regulation and emerging state fiduciary overlays to determine compliance architecture and service pricing recalibration.
Market Dynamics
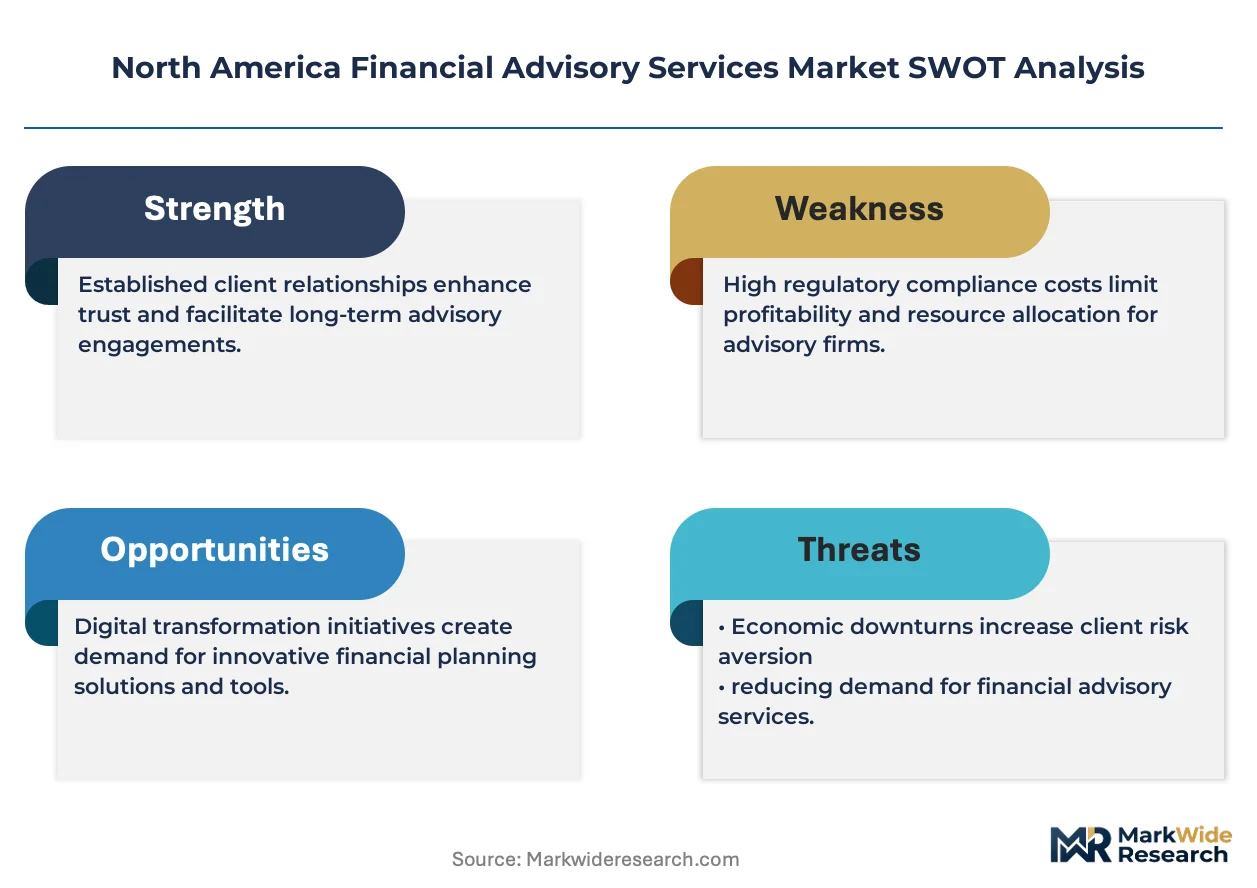
The North America Financial Advisory Services Market is reconfiguring around fiduciary standard harmonization as the SEC's best-interest rule and state-level fiduciary overlays create compliance complexity that favors scaled advisory platforms with dedicated regulatory infrastructure.
Growth Catalysts
- Technology Sector Liquidity Events:California and New York metro corridors generate recurring advisory demand from stock option exercises and venture capital distributions among newly liquid households.
- SEC Best-Interest Regulation:Enhanced disclosure requirements accelerate advisor migration toward fee-based compensation models that align client and practitioner incentives.
- Monte Carlo Simulation Engines:Liability-driven investment frameworks and tax-loss harvesting algorithms enable sophisticated after-tax optimization that attracts ultra-high-net-worth engagement.
Market Restraints
- Regulatory Divergence Friction:Competing fiduciary definitions between SEC federal standards and emerging state overlays in Massachusetts and Nevada create compliance architecture uncertainty.
- Talent Concentration Risk:Certified Financial Planner and Chartered Financial Analyst credential holders cluster disproportionately in coastal metropolitan advisory practices.
- Commission Model Compression:FINRA suitability rule evolution pressures traditional brokerage revenue structures toward lower-margin advisory relationships.
Strategic Opportunities
- Texas and Florida Household Migration:Advisor headcount expansion in Sun Belt states captures relocating high net-worth households seeking estate tax efficiency and lower cost structures.
- Hybrid Digital-Human Delivery:Scaled robo-advisory platforms augmented with certified planner touchpoints penetrate mass-affluent segments previously underserved by traditional wealth management.
- Canadian Securities Administrators Reform:Client-focused reforms create tailwind for fee-based advisory model adoption across Ontario and British Columbia wealth management practices.
Industry Challenges
- Multi-Jurisdictional Licensing Complexity:Advisors serving cross-border clients face fragmented registration requirements across SEC, FINRA, and Canadian provincial securities commissions.
- Legacy Technology Integration Friction:Established practices encounter operational disruption when migrating client data from proprietary CRM systems to open-architecture portfolio management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Financial Advisory Services Market |
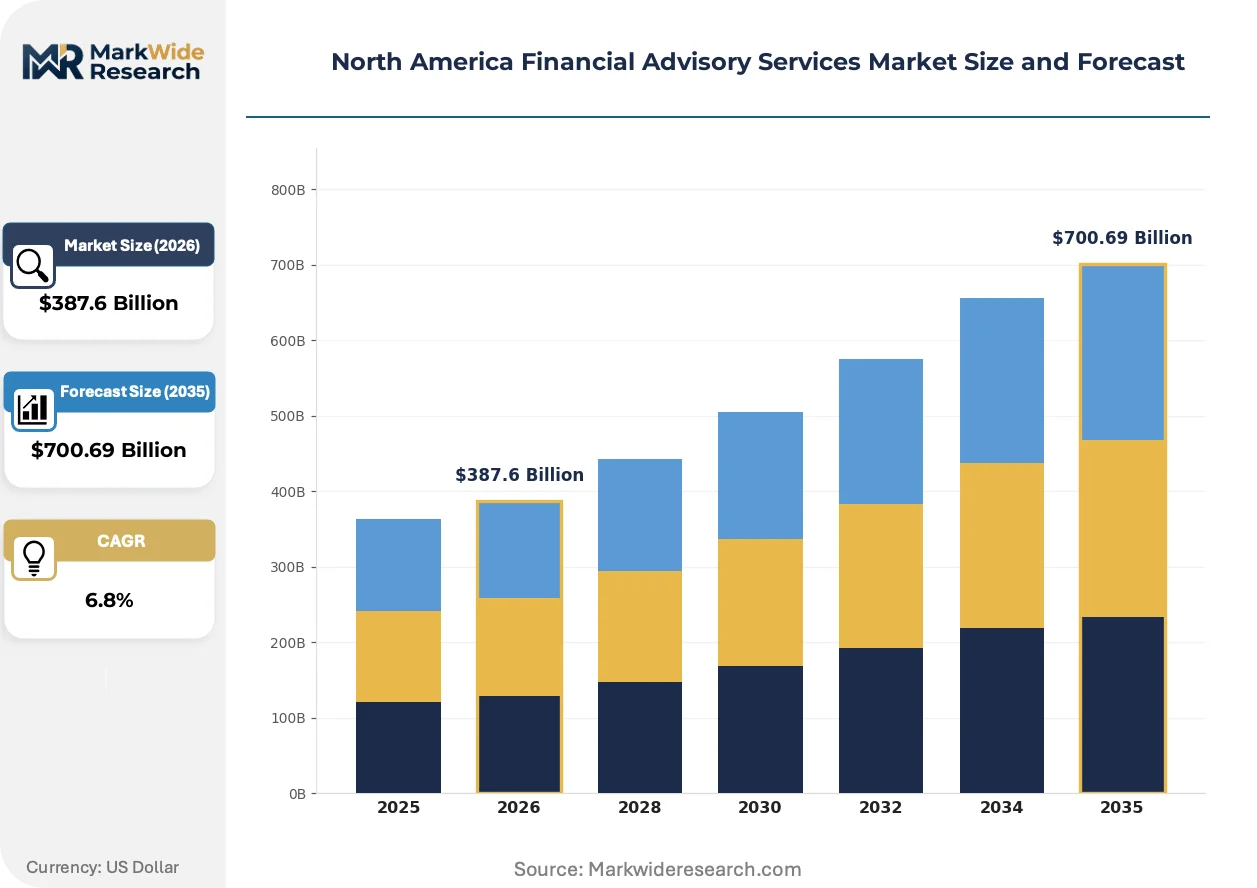
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Investment Advisory, Wealth Management, Tax Consulting, Risk Management Client Type: Individual Investors, Corporations, Institutions, High Net-Worth Individuals Engagement Model: Retainer-Based, Hourly Fee, Commission-Based, Performance-Based Industry Vertical: BFSI, Healthcare, Technology, Real Estate |
| Companies Covered | Aldrich Wealth, Morgan Stanley Wealth Management, Edelman Financial Engines, Nvest Financial, Presilium Private Wealth, CAPTRUST, J.P. Morgan Wealth Management, Genesis Wealth Management, Wealth Enhancement Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Financial Advisory Services Market Strategic Shifts
Advisory delivery models are fragmenting across human-digital hybrid architectures as client expectations for transparent fee structures and real-time portfolio visibility reshape service design.
Artificial intelligence-driven risk profiling engines are migrating from experimental deployment to core infrastructure across advisory platforms. Mid-sized registered investment advisors in Illinois and Pennsylvania are adopting these tools at accelerating pace. The technology is migrating from boutique implementation toward standardized client onboarding workflows that compress suitability documentation timelines.
The Department of Labor's evolving fiduciary definition continues reshaping compensation transparency mandates across retirement account advisory relationships. Product recommendation documentation requirements now extend to rollover guidance and annuity placement. Retirement-focused advisory practices in Arizona and Colorado are responding by restructuring revenue toward level-fee engagement models.
Family office demand is fragmenting traditional wealth management relationships as ultra-high-net-worth households establish dedicated investment staff. Multi-generational wealth transfer planning now requires coordinated estate attorney, tax specialist, and investment committee engagement. This behavioral shift is most visible in Connecticut and Washington state corridors where technology and aerospace liquidity has concentrated dynastic wealth.
North America Financial Advisory Services Market Segmentation
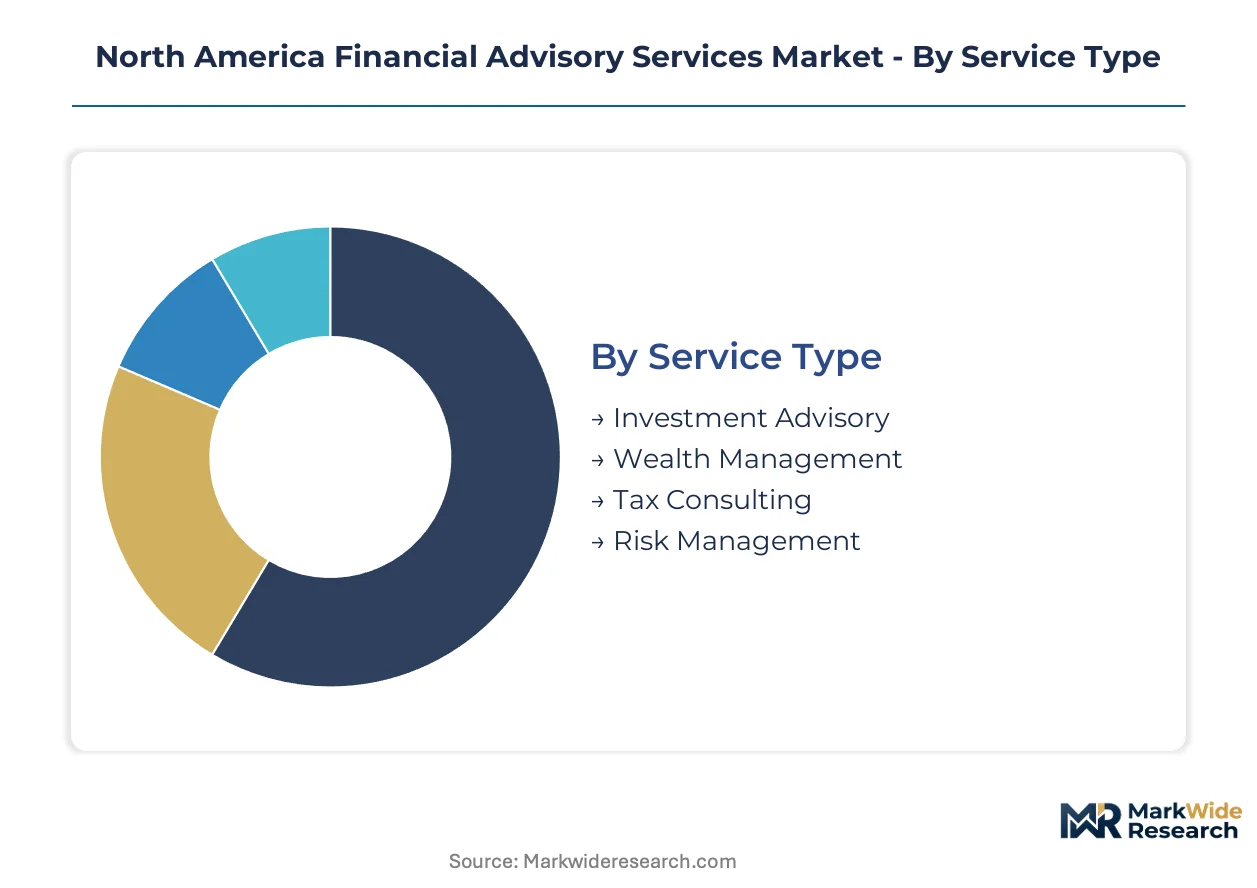
Service differentiation across the North America Financial Advisory Services Market determines pricing architecture, regulatory burden, and relationship durability. Segment boundaries are blurring as hybrid delivery models and cross-functional advisory teams reshape traditional category definitions.
Service Type:
After-sales-service intensity varies dramatically across advisory disciplines, with ongoing portfolio monitoring and tax-loss harvesting creating recurring touchpoint obligations that wealth management firms monetize through asset-based fee structures.
- Wealth Management:Holistic financial planning integrating investment allocation, estate structuring, and multi-generational wealth transfer. Demand concentrates among ultra-high-net-worth households in Connecticut and Washington state corridors where technology and aerospace liquidity events have concentrated dynastic wealth. Recurring asset-based fees and sticky multi-service relationships command the deepest margin pools in advisory services.
- Investment Advisory:Professional guidance on portfolio construction, asset allocation, and security selection governed by fiduciary or suitability standards. California and New York metro corridors generate sustained demand from stock option exercises and venture capital distributions among newly liquid technology sector households. Practitioners deploy Monte Carlo simulation engines and liability-driven frameworks to optimize risk-adjusted outcomes.
- Tax Consulting:Tax-efficient structuring, compliance navigation, and cross-border planning delivered by certified public accountant specialists. Regulatory complexity creates premium pricing opportunities for firms with deep technical credential depth.
- Risk Management:Insurance placement, liability mitigation, and enterprise risk assessment across personal and commercial exposures. Mature segment characteristics concentrate specialist expertise in established advisory practices.
By volume, investment advisory leads due to broader household penetration. By growth pace, wealth management is ahead as fiduciary standard harmonization drives consolidation toward comprehensive service models.
Client Type:
Cost tier segmentation separates mass-affluent digital advice users from relationship-intensive ultra-high-net-worth households requiring dedicated family office infrastructure.
- High Net-Worth Individuals:Households with substantial investable assets demanding coordinated estate, tax, and investment advisory across multi-generational horizons. Texas and Florida are capturing migrating households seeking estate tax efficiency and lower operational cost structures.
- Individual Investors:Mass-affluent and emerging wealthy households accessing advisory through hybrid digital-human platforms. Scaled robo-advisory penetration is expanding access to previously underserved segments.
- Corporations:Enterprise treasury management, executive compensation structuring, and pension advisory requiring specialized institutional expertise.
- Institutions:Endowments, foundations, and pension funds seeking performance-based engagement models with aligned incentive structures and alternative investment access.
By client count, individual investors dominate. By revenue per relationship, high net-worth individuals command premium positioning.
Engagement Model:
Margin structure varies sharply across compensation mechanisms, with fee-based models capturing regulatory tailwinds while commission-based revenue faces compression from evolving suitability standards.
- Retainer-Based:Fixed periodic fees for comprehensive advisory access regardless of transaction volume. Arizona and Colorado retirement-focused practices are restructuring toward level-fee engagement models in response to Department of Labor fiduciary definition evolution.
- Performance-Based:Compensation tied to investment outcomes or benchmark-relative returns. Sophisticated institutional clients seeking aligned incentive structures drive adoption in ultra-high-net-worth segments.
- Hourly Fee:Time-billed professional services for discrete planning engagements or project-based advisory.
- Commission-Based:Product placement compensation from third-party providers. FINRA suitability rule evolution and SEC best-interest regulation are accelerating migration away from this structure.
By advisor headcount, retainer-based relationships are expanding most quickly. By absolute revenue, performance-based engagements claim the steepest expansion trajectory among institutional mandates.
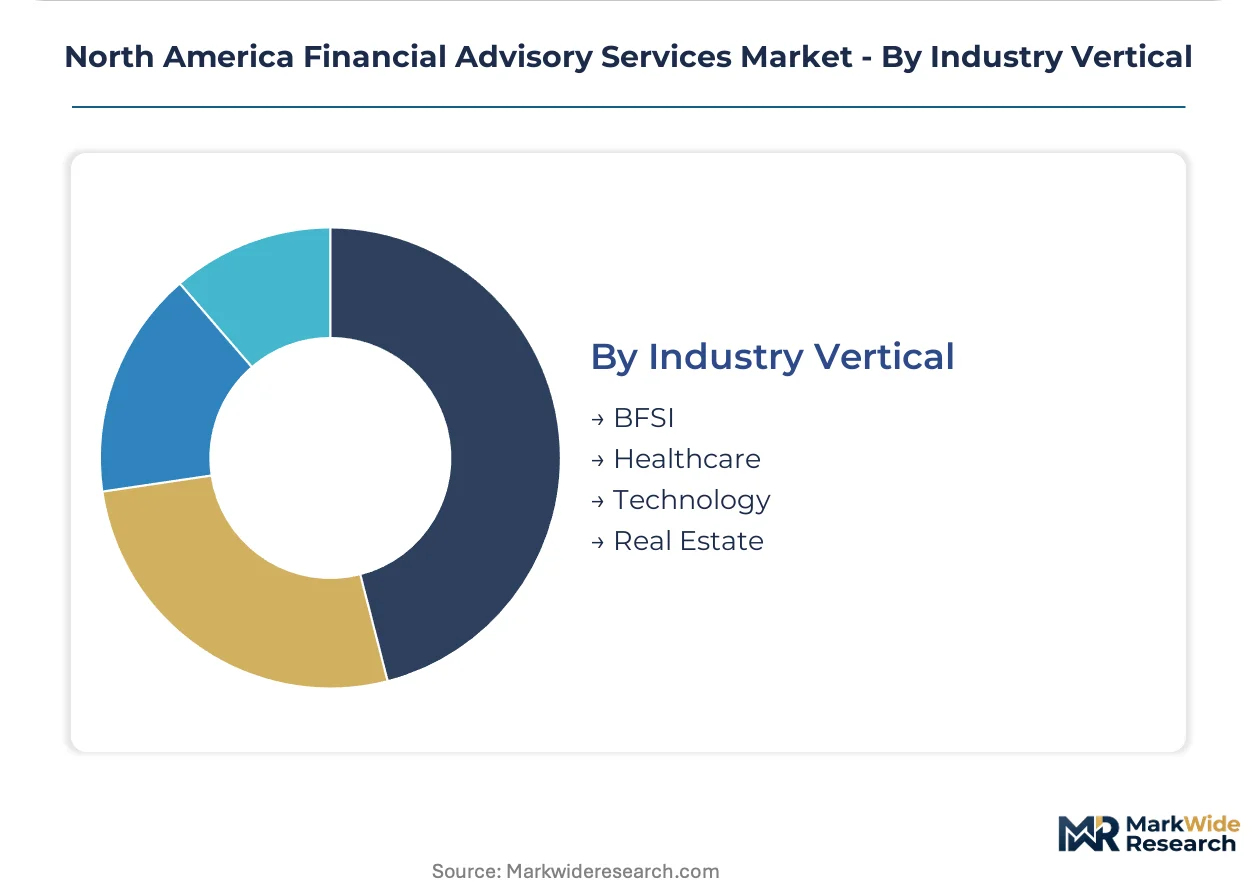
Industry Vertical:
Application-specific expertise requirements create specialist premium opportunities as regulatory complexity and compensation structure vary dramatically across end-use sectors.
- Technology:Equity compensation optimization, liquidity event planning, and venture-backed wealth structuring. California and New York metro corridors generate recurring advisory demand from stock option exercises and secondary share distributions.
- BFSI:Regulatory compliance advisory, executive compensation, and enterprise risk management for financial institutions. SEC disclosure requirements and fiduciary rule evolution reshape service delivery standards.
- Healthcare:Practice succession planning, regulatory compliance, and specialized compensation structures for medical professionals.
- Real Estate:1031 exchange navigation, opportunity zone structuring, and commercial property portfolio advisory.
By advisory revenue concentration, technology leads. By regulatory complexity expansion, BFSI is climbing the fastest as federal and state fiduciary overlays multiply compliance obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes financial advisory services through technology-driven liquidity event planning, while Canada emphasizes cross-border tax efficiency and Mexico's emerging affluent class accesses advisory through bank distribution partnerships.
United States
California and New York metro corridors generate sustained demand from technology sector stock option exercises and venture capital distributions. SEC best-interest regulation and evolving Department of Labor fiduciary definitions reshape advisor compensation transparency across retirement accounts. Texas and Florida advisor headcount expansion captures migrating high net-worth households seeking estate tax efficiency.
Canada
Ontario and British Columbia wealth management practices experience tailwinds from Canadian Securities Administrators client-focused reforms driving fee-based model adoption. Provincial securities commissions enforce registration requirements that pressure commission-based revenue structures toward advisory relationships. Toronto anchors institutional advisory demand while Vancouver channels Asia-Pacific cross-border wealth planning.
Mexico
Mexico City Metro and Nuevo León concentrate emerging affluent household demand for investment advisory through bank-affiliated distribution channels. The country's national securities regulator enforces disclosure standards that elevate transparency expectations for product recommendations. Bajío Region manufacturing wealth generates specialized estate planning and succession advisory needs.
North America Financial Advisory Services Market Competitive Environment
Capability concentration sits with boutique registered investment advisors possessing certified financial planner depth; scale advantage sits with integrated banking platforms with proprietary alternative investment access. The market structures around three tiers: wirehouse wealth management divisions, independent registered investment advisors, and hybrid digital-human platforms. Dominant competitive moves include advisor team recruitment from rival firms and technology platform licensing to compress client onboarding timelines.
Within the integrated banking tier, Morgan Stanley Wealth Management and J.P. Morgan Wealth Management exemplify scale-driven positioning through cross-selling momentum and captive alternative investment pipelines. Edelman Financial Engines occupies a position representing hybrid digital-human delivery archetypes. These three entities anchor competitive dynamics as fiduciary standard harmonization pressures compensation model evolution across the industry.
| Leading Market Players |
|---|
| Aldrich Wealth |
| Morgan Stanley Wealth Management |
| Edelman Financial Engines |
| Nvest Financial |
| Presilium Private Wealth |
| CAPTRUST |
| J.P. Morgan Wealth Management |
| Genesis Wealth Management |
| Wealth Enhancement Group |
| Others |
Value Chain & Pricing Dynamics
Regulatory divergence friction between SEC federal standards and emerging state fiduciary overlays determines both pricing tier spreads and supply chain shape across the North America Financial Advisory Services Market. Compliance architecture uncertainty compresses margins for boutique practices while scaled platforms capture premium pricing through dedicated regulatory infrastructure.
Pricing Analysis
Geographic price spreads separate coastal metropolitan advisory practices from Sun Belt expansion markets, with Connecticut and Washington state corridors commanding premium asset-based fee structures for multi-generational wealth transfer services. Three-tier pricing structure across comprehensive wealth management, investment advisory, and digital-hybrid platforms differentiates by credential depth and service bundling intensity. Pricing pressure stems from commission model compression as FINRA suitability rule evolution accelerates migration toward lower-margin fee-based relationships. Mass-affluent digital advice users exhibit highest price sensitivity, while ultra-high-net-worth households in dynastic wealth corridors demonstrate lowest sensitivity due to sticky multi-service relationship demands.
Supply Chain Analysis
Tariff exposure between United States and Canadian cross-border advisory relationships dominates supply chain risk for practices serving dual-jurisdiction clients. Human capital supply concentrates in California, New York, and Texas where certified financial planner and chartered financial analyst credential holders cluster disproportionately. Raw material dependencies rest on Monte Carlo simulation engine licensing, proprietary alternative investment access arrangements, and open-architecture portfolio management platform subscriptions. Single-source vulnerability sits with concentrated technology vendor relationships for client onboarding and portfolio rebalancing infrastructure. Distribution runs through wirehouse wealth management divisions, independent registered investment advisors, and hybrid digital-human platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward ultra-high-net-worth households establishing dedicated family office infrastructure, fragmenting traditional advisory relationships as dynastic wealth concentrates in technology and aerospace liquidity corridors.
For Market Incumbents: Insulate fee-based revenue streams by deepening certified financial planner density in Texas and Florida migration corridors where relocating households seek estate tax efficiency. Vertical integration into proprietary alternative investment access, as demonstrated by J.P. Morgan Wealth Management's captive pipeline strategy, defends margin position against commission model compression from evolving Department of Labor fiduciary definitions. For New Entrants and Emerging Players: Pursue mass-affluent segments in Illinois and Pennsylvania where mid-sized registered investment advisors are adopting artificial intelligence-driven risk profiling engines at accelerating pace. Artificial intelligence-augmented client onboarding workflows penetrate previously underserved households through scaled robo-advisory platforms hybridized with certified planner touchpoints. For Investors and Strategic Acquirers: The Department of Labor's evolving fiduciary definition reshapes the acquisition landscape by privileging advisory practices with pre-existing fee-based infrastructure over commission-dependent brokerage operations. Long-term viability favors registered investment advisors with demonstrated regulatory compliance architecture and sticky multi-generational client relationships. The signal to watch is advisor team recruitment velocity from wirehouse divisions toward independent platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Advisor Team Recruitment | Captures migrating high net-worth households seeking fiduciary-aligned engagement models. |
| Hybrid Digital-Human Platform Launch | Penetrates mass-affluent segments through artificial intelligence-augmented onboarding workflows. |
| Proprietary Alternative Investment Access | Differentiates ultra-high-net-worth positioning through captive private market pipelines. |
| Multi-Jurisdictional Licensing Expansion | Enables cross-border service delivery across SEC, FINRA, and Canadian provincial frameworks. |
| Regulatory Infrastructure Investment | Absorbs compliance complexity from competing fiduciary definitions between federal and state overlays. |
Study Parameters
Initial hypotheses were tested against primary input from wealth management executives, regulatory compliance officers, certified financial planners, and institutional investment consultants and refined through secondary validation. Primary fieldwork combined structured interviews with advisory practice principals and distribution channel partners across California, New York, Texas, and Florida corridors with bottom-up and top-down triangulation. Secondary sources encompassed SEC registration filings, FINRA regulatory notices, Canadian Securities Administrators policy bulletins, and provincial securities commission disclosure databases.
Demand-supply-balance framing anchored the forecast framework, modeling advisor headcount expansion against household migration patterns and liquidity event velocity across the analysis window. Segmentation dimensions spanned service type, client wealth tier, engagement model, and industry vertical with regional regulatory cluster overlays. CAGRs were derived through trend extrapolation validated against historical fee compression trajectories and fiduciary rule implementation timelines. Industry-specific inputs included Monte Carlo simulation engine adoption curves and artificial intelligence-driven risk profiling penetration rates.
Macroeconomic conditions sit as an overlay; deviation in technology sector valuation cycles, venture capital distribution velocity, or cross-border tax policy coordination would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization pace and advisor credential supply elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Healthcare Finance Solutions Market
Financial Services
Global Product Cost Management Market
Financial Services
BFSI A2P SMS Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
India Trade Finance Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
Direct Selling Market
Financial Services
Source to Pay Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Treasury Management Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
Commodity Services Market
Financial Services
Factoring Services Market
Financial Services
Pawn Shop Market
Financial Services
Cash Flow Market
Financial Services
Europe Financial Advisory Services Market