
 Digital Monetary Insurance Market | 2026-2036
Digital Monetary Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Monetary Insurance Market Insights
The capital-intensity divergence between cloud-native insurers and legacy carriers is rotating competitive advantage toward technology-first platforms. Chubb leverages its global commercial underwriting infrastructure to anchor institutional digital asset coverage. Lemonade Insurance Company sustains AI-driven policy automation that differentiates its cost structure against traditional actuarial models. Zhongan Insurance dominates embedded insurance distribution across Asia-Pacific e-commerce ecosystems, extending its reach through API-first partnerships with technology developers.
Digital monetary insurance encompasses risk-transfer instruments that protect holders of digitized value against unauthorized access, transactional failure, and smart-contract exploits, typically parameterized through real-time blockchain attestations and automated oracle feeds. Its primary commercial purpose is to reduce friction in digital commerce by substituting cryptographic certainty for institutional trust. Cyber Risk Coverage leads product-type revenue as ransomware attacks against DeFi protocols intensify, while Fraud Detection services within the service-type dimension command premium pricing due to machine-learning model scarcity. Digital Asset Protection is accelerating fastest among product categories as institutional custody solutions proliferate.
EU regulators including EBA and ESMA are tightening prudential standards for crypto-asset exposure, directly expanding mandatory coverage thresholds for payment processors and custodial wallet providers. The SEC and state-level insurance commissioners in the United States are constructing parallel disclosure regimes that shape product design and capital reserving requirements. Stakeholders must monitor how divergent supervisory approaches between jurisdictions affect policy portability and cross-border claims settlement architecture.
Market Dynamics
Automated underwriting platforms are compressing policy issuance cycles from weeks to minutes, fundamentally altering capital deployment velocity and carrier cost structures across the digital monetary insurance value chain.
Growth Catalysts
- EU AI Act compliance mandates:Payment processors and custodial wallet providers across the European Union face expanded mandatory coverage thresholds, directly accelerating platform adoption for automated risk assessment.
- Smart-contract oracle integration:Real-time blockchain attestations now enable parametric claim settlement, eliminating manual verification bottlenecks that previously constrained policy scalability.
- Germany:The country's specialized fintech insurance framework attracts institutional custody solutions seeking regulatory clarity for digital asset protection products.
Market Restraints
- Machine-learning model scarcity:Fraud detection services command premium pricing due to limited availability of trained actuarial models capable of assessing DeFi protocol risk.
- Legacy carrier infrastructure:Traditional insurers maintain capital reserves against outdated actuarial tables, creating cost disadvantages against cloud-native competitors.
- Cross-border claims settlement friction:Divergent supervisory approaches between the SEC and EU regulators complicate policy portability architecture.
Strategic Opportunities
- Singapore:The jurisdiction's fintech insurance framework remains underpenetrated by embedded distribution models, creating whitespace for API-first partnership structures.
- Convergence of AI-driven automation and blockchain attestation:Technology platforms that unify these capabilities can compress underwriting costs below traditional actuarial benchmarks.
- GDPR-aligned data governance:Regulatory tailwinds favor carriers demonstrating automated compliance for cross-border policyholder data management.
Industry Challenges
- Smart-contract exploit assessment:Talent scarcity in quantitative risk modeling for DeFi protocols limits carrier capacity to underwrite institutional digital asset portfolios.
- Oracle feed reliability certification:Third-party attestation standards remain fragmented, delaying parametric policy deployment timelines.
- Legacy system integration:Traditional carriers face execution friction connecting automated underwriting platforms to existing policy administration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Monetary Insurance Market |
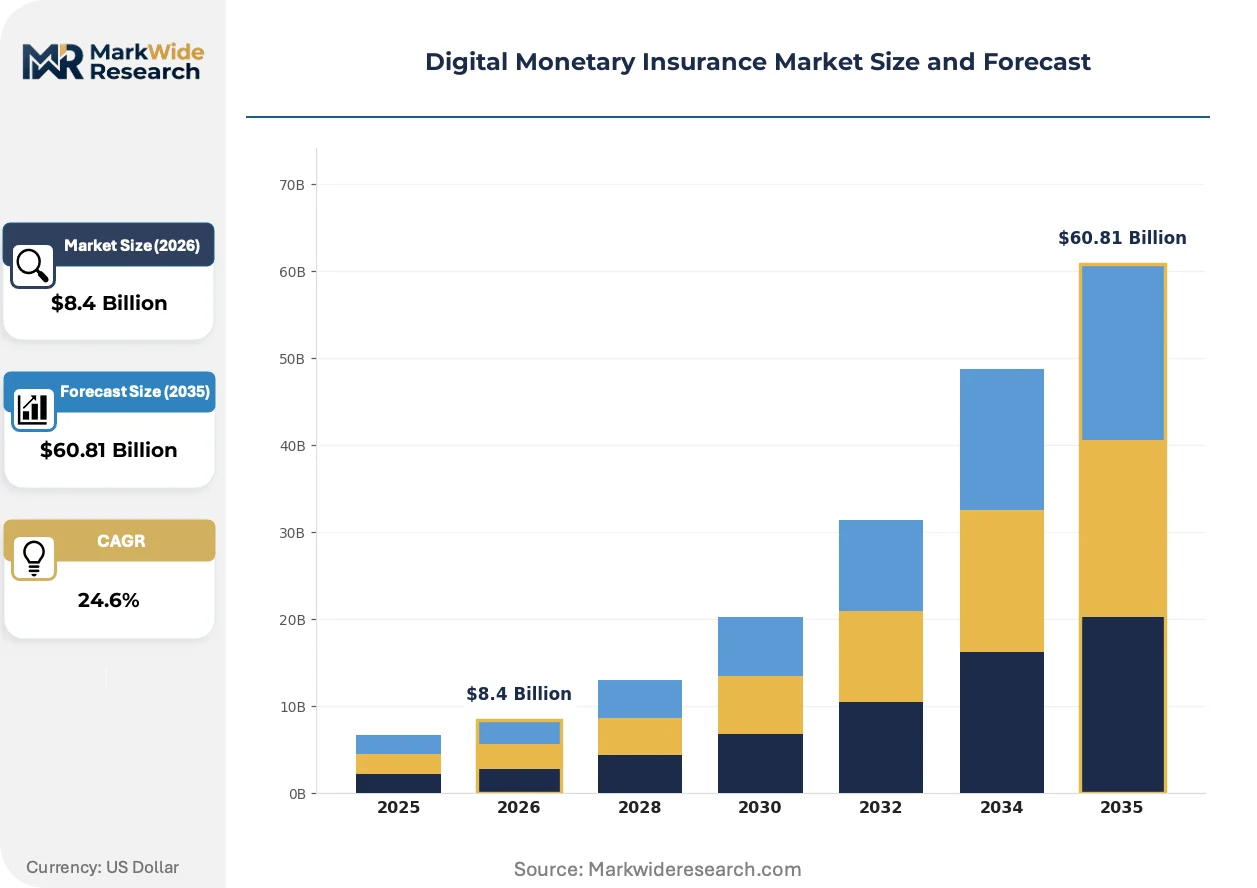
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyber Risk Coverage, Digital Asset Protection, Fraud Liability, Transaction Security, Identity Verification, Others Application: Cryptocurrency Wallets, Mobile Payment Platforms, Online Banking, E-Commerce Protection, Digital Identity Management, Peer-to-Peer Transfers Service Type: Risk Assessment, Claim Management, Policy Underwriting, Customer Support, Fraud Detection, Risk Mitigation End User: Financial Institutions, Payment Processors, E-Commerce Merchants, Digital Wallet Providers, Insurtech Firms, Technology Developers |
| Companies Covered | Chubb, Great American Insurance Group, Lemonade Insurance Company, Zhongan Insurance, DXC Technology Company, EIS Software Limited, Majesco, Salesforce, Guidewire Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Monetary Insurance Market Trends and Innovations
Parametric insurance architectures are replacing indemnity-based structures, enabling instantaneous claim settlement triggered by predefined blockchain events rather than subjective loss assessment.
Automated oracle feeds are displacing manual claims adjustment in digital asset coverage. Institutional custody providers now require real-time attestation of reserve adequacy. This compression of verification cycles is enabling carriers to price coverage at fractions of traditional cyber policy rates.
The EU AI Act establishes binding transparency requirements for algorithmic underwriting decisions. European carriers must document model training data and decision logic for regulatory examination. German and French regulators are constructing parallel technical standards that shape product design across the continental market.
Corporate treasury departments now procure digital asset coverage through embedded insurance APIs rather than standalone broker relationships. E-commerce platforms in Asia-Pacific integrate protection at transaction point-of-sale. Singapore and Hong Kong display the most advanced adoption of this distribution model among institutional buyers.
Digital Monetary Insurance Market Segmentation
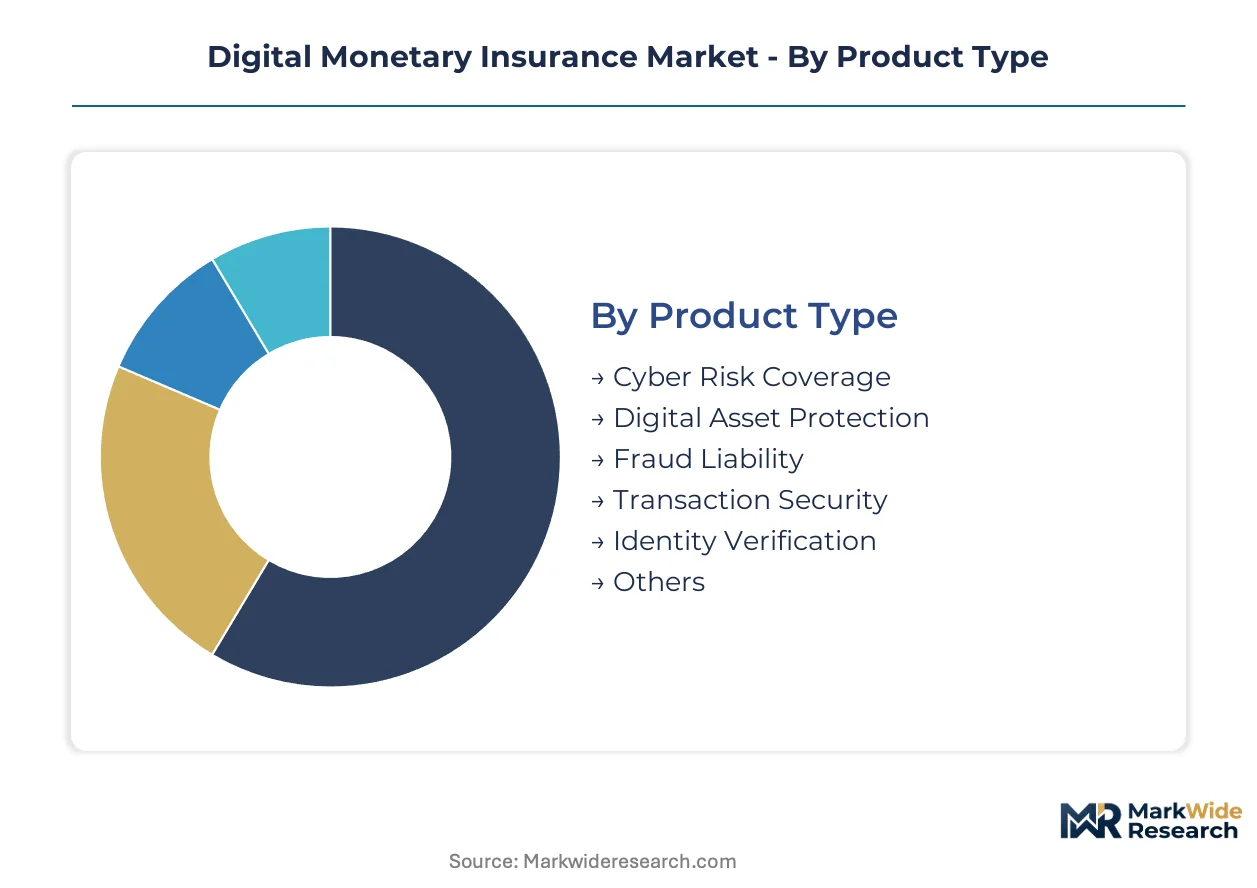
Segmentation in digital monetary insurance reveals how risk-transfer instruments align with distinct operational vulnerabilities across custody, transaction, and identity layers. Each dimension exposes different underwriting complexity, from parametric smart-contract triggers to behavioral biometric verification.
Product Type:
Geographic concentration varies sharply across product categories, with institutional custody solutions driving cross-border demand for Digital Asset Protection while Cyber Risk Coverage remains anchored in domestic regulatory frameworks.
- Cyber Risk Coverage:Parametric structures protect against protocol exploits and ransomware attacks through automated oracle feeds. Demand concentrates among DeFi platforms and institutional custodians in Germany and Singapore, constrained by talent scarcity in quantitative risk modeling.
- Digital Asset Protection:Coverage for unauthorized access and private key compromise utilizes real-time blockchain attestations for verification. Singapore's fintech insurance framework attracts the steepest carrier expansion as custody solutions proliferate.
- Fraud Liability:Transfer mechanisms for synthetic identity and social engineering losses.
- Transaction Security:Protection against settlement failures and double-spend attacks in high-velocity payment rails.
- Identity Verification:Coverage for biometric system breaches and credential stuffing campaigns.
- Others:Niche instruments including stablecoin depeg protection and cross-chain bridge failure.
Cyber Risk Coverage commands the established base. The steepest expansion runs through Digital Asset Protection.
Application:
Cost-tier stratification separates enterprise-grade custody solutions from retail-facing wallet protection, with premium pricing attaching to institutional mandates under EU AI Act compliance.
- Cryptocurrency Wallets:Hot and cold storage protection spans consumer mobile applications through institutional multi-signature architectures. Custodial providers in the United States face expanded mandatory coverage thresholds under SEC disclosure regimes.
- Mobile Payment Platforms:Real-time transaction insurance embedded at point-of-sale through API integration. Asia-Pacific e-commerce ecosystems display the most advanced adoption, led by Singapore and Hong Kong deployment models.
- Online Banking:Traditional financial institution coverage for digital channel vulnerabilities.
- E-Commerce Protection:Merchant-facing instruments against chargeback fraud and payment gateway failures.
- Digital Identity Management:Coverage for centralized and decentralized identity infrastructure breaches.
- Peer-to-Peer Transfers:Protection for informal payment networks and remittance corridors.
Cryptocurrency Wallets anchors current premium volume. Mobile Payment Platforms is gaining share fastest as embedded distribution models mature.
Service Type:
Margin concentration follows automation intensity, with Fraud Detection commanding premium pricing due to machine-learning model scarcity while Customer Support remains labor-intensive.
- Risk Assessment:Automated underwriting platforms compress evaluation cycles from weeks to minutes through algorithmic scoring. EU AI Act transparency mandates require documented model training data and decision logic for regulatory examination.
- Fraud Detection:Machine-learning systems identify anomalous transaction patterns and synthetic identity creation. Limited availability of trained actuarial models capable of assessing DeFi protocol risk sustains pricing premiums above traditional cyber benchmarks.
- Claim Management:Parametric settlement architectures triggered by predefined blockchain events.
- Policy Underwriting:Capital deployment and pricing functions increasingly automated.
- Customer Support:Human-assisted dispute resolution and coverage explanation.
- Risk Mitigation:Preventive services including security audits and protocol hardening.
Fraud Detection captures the highest margin pool. Risk Assessment is climbing the fastest as carriers automate core underwriting infrastructure.
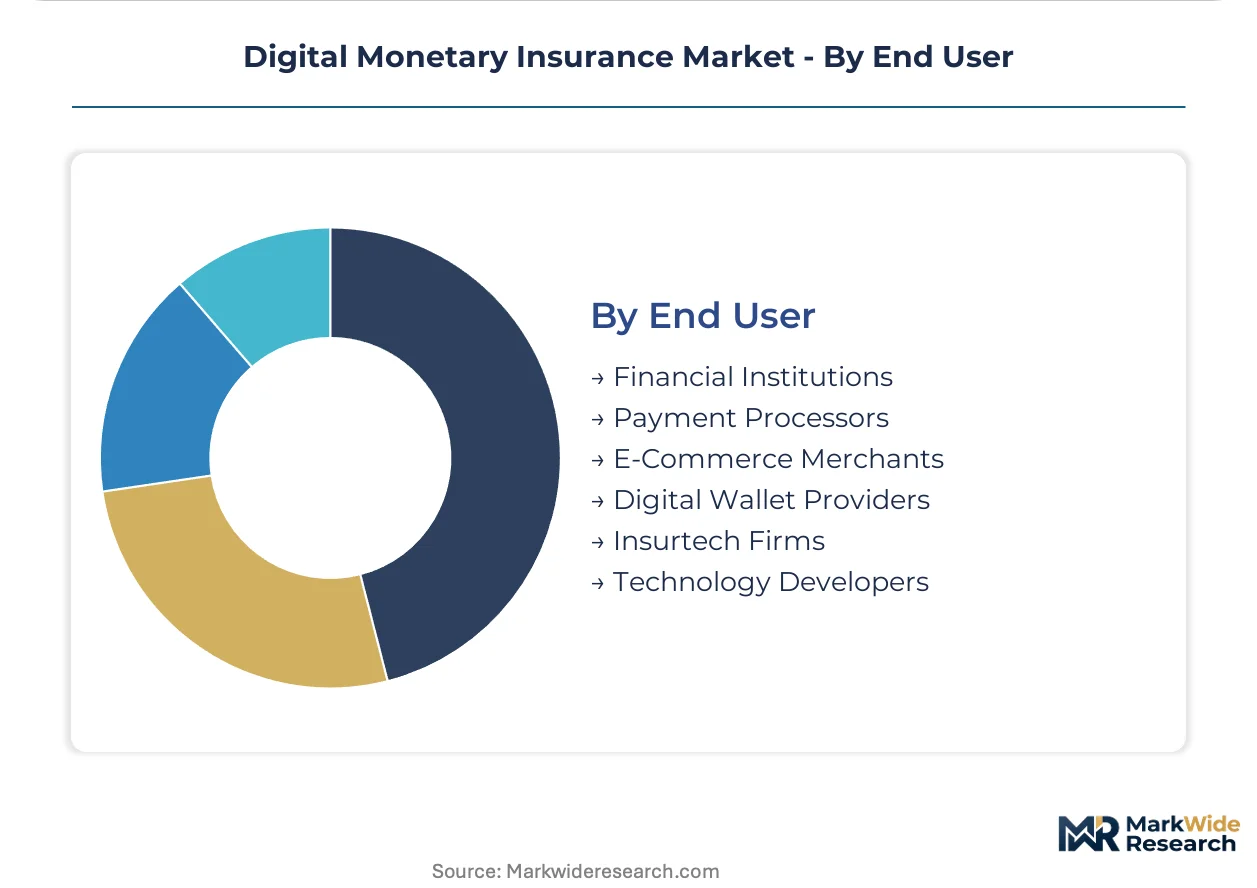
End User:
Supply concentration sits with technology-first platforms serving Payment Processors and Digital Wallet Providers, while legacy carriers retain Financial Institution relationships through existing commercial lines.
- Payment Processors:Mandated coverage for transaction failure and regulatory compliance across EU and US jurisdictions. EBA and ESMA prudential standards directly expand required protection thresholds for crypto-asset exposure.
- Digital Wallet Providers:Embedded insurance distribution through API-first partnerships. Zhongan Insurance's Asia-Pacific e-commerce ecosystem model demonstrates scalable architecture for this segment.
- Financial Institutions:Corporate treasury and institutional custody coverage.
- E-Commerce Merchants:Transaction-point protection against fraud and non-delivery.
- Insurtech Firms:Technology platforms requiring coverage for their own operational risk.
- Technology Developers:Smart-contract and protocol builders seeking liability transfer.
Payment Processors represents the deepest established demand. Digital Wallet Providers shows the steepest expansion trajectory as embedded distribution proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Singapore and Germany while the United States operates under heavier compliance cost burdens. Jurisdictions with specialized fintech insurance frameworks extract premium margins from institutional custody providers.
United States
SEC disclosure regimes and state-level insurance commissioners are expanding mandatory coverage thresholds for custodial wallet providers. The regulatory fragmentation between federal and state authorities complicates cross-border policy portability for carriers operating nationwide. New York and California host the densest clusters of insurtech startups building automated underwriting infrastructure for digital asset protection.
Germany
BaFin's prudential standards for crypto-asset exposure attract institutional custody solutions seeking regulatory clarity. The EU AI Act compliance mandates accelerate platform adoption for automated risk assessment across payment processors. Frankfurt anchors the continental market for parametric insurance architectures triggered by blockchain attestations.
Singapore
The Monetary Authority of Singapore's fintech insurance framework remains underpenetrated by embedded distribution models, creating whitespace for API-first partnerships. MAS regulatory sandboxes enable real-time testing of automated oracle feed integrations for claim settlement. The city-state's custody solution providers command premium pricing for digital asset protection products.
United Kingdom
FCA guidance on crypto-asset exposure shapes capital reserving requirements for carriers underwriting digital wallet protection. Post-Brexit divergence from EU AI Act standards creates compliance complexity for insurers operating across both markets. London's Lloyd's market infrastructure supports specialized coverage for DeFi protocol exploits and smart-contract failures.
Switzerland
FINMA's blockchain-friendly regulatory posture attracts carriers building parametric coverage for institutional digital asset portfolios. The country's private banking heritage translates into sophisticated demand for fraud detection services. Zug's Crypto Valley concentration hosts custody providers requiring real-time attestation of reserve adequacy.
Digital Monetary Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the digital monetary insurance value chain. Cloud-native platforms compress underwriting cycles through algorithmic automation while legacy carriers leverage existing commercial relationships and capital reserves. The market structure fragments across three strategic archetypes: global commercial underwriters with institutional infrastructure, AI-first insurtechs with automated cost structures, and embedded distribution specialists with API-first partnership models. Competitive moves concentrate on strategic partnerships with custody providers and technology licensing for oracle feed integration.
Among global commercial underwriters, Chubb anchors institutional digital asset coverage through its established underwriting infrastructure. Lemonade Insurance Company exemplifies the AI-driven automation archetype with differentiated cost structures against traditional actuarial models. Zhongan Insurance occupies the embedded distribution position, dominating API-first partnerships across Asia-Pacific e-commerce ecosystems.
| Leading Market Players |
|---|
| Chubb |
| Great American Insurance Group |
| Lemonade Insurance Company |
| Zhongan Insurance |
| DXC Technology Company |
| EIS Software Limited |
| Majesco |
| Salesforce |
| Guidewire Software |
| Others |
Pricing and Supply Chain Analysis
EU AI Act certification tiers gate both carrier qualification and price differentiation simultaneously, forcing technology-first platforms to document algorithmic decision logic while legacy insurers absorb compliance overhead into premium spreads.
Pricing Analysis
The customization-premium spread separates configured-to-order parametric policies from standard cyber coverage products. Subscription-tiered SaaS pricing dominates, with premium tiers attaching to real-time oracle feed integration and automated claim settlement. Price differentiation rests on certification grade and volume scale, with EU AI Act-compliant carriers commanding spreads above non-compliant competitors. Pricing pressure stems from cloud-native automation compressing underwriting costs, eroding legacy carrier margins. Payment processors show highest price sensitivity due to mandated coverage thresholds, while institutional custodians accept premium pricing for specialized digital asset protection.
Supply Chain Analysis
Germany, Singapore, and the United States anchor automated underwriting platform development and parametric insurance architecture. The supply chain draws from specialized machine-learning talent pools, blockchain oracle infrastructure providers, and regulatory compliance technology vendors. Single-source vulnerability concentrates in trained actuarial model scarcity for DeFi protocol risk assessment. Distribution runs through API-first embedded partnerships with custody providers and payment processors, displacing traditional broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
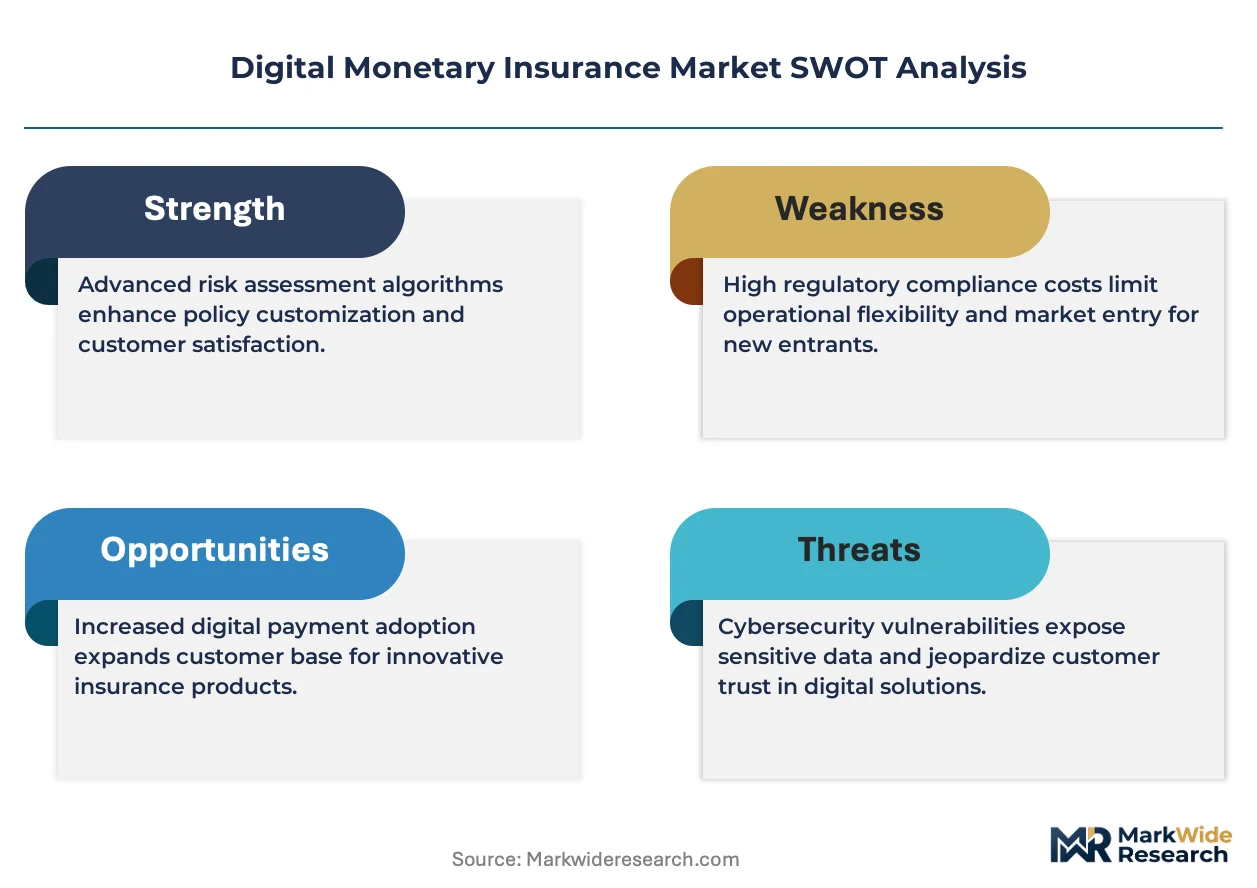
Market fragmentation creates opportunity as divergent regulatory frameworks between jurisdictions splinter demand into specialized niches requiring localized compliance architecture.
For Market Incumbents: Secure algorithmic underwriting talent pools against fintech poaching by acquiring specialized DeFi risk modeling teams. Lock in exclusive oracle feed partnerships with blockchain attestation providers to defend parametric settlement capabilities against emerging cloud-native competitors. Investment in EU AI Act documentation infrastructure protects premium positioning as transparency mandates tighten.
For New Entrants and Emerging Players: API-first distribution layers in Singapore's underpenetrated fintech insurance framework offer immediate whitespace, with MAS regulatory sandboxes enabling rapid testing of embedded coverage models. Target institutional custody providers seeking real-time reserve attestation as the most penetrable buyer segment, leveraging automated underwriting cost advantages against legacy carrier actuarial overhead.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native underwriting platforms as algorithmic automation displaces manual actuarial processes. Long-term viability favors technology-first carriers with demonstrated EU AI Act compliance infrastructure over legacy players burdened by outdated policy administration systems. Monitor oracle feed reliability certification standardization as the critical inflection signal for parametric policy scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Oracle Feed Partnership | Blockchain attestation integration enables parametric claim settlement compression below traditional cyber benchmarks. |
| EU AI Act Compliance Investment | Documented model transparency creates regulatory moat against non-compliant competitors in European markets. |
| Embedded API Distribution | Point-of-sale integration with custody providers displaces broker-dependent acquisition models. |
| DeFi Risk Modeling Acquisition | Quantitative talent scarcity makes specialized teams strategic differentiators for institutional coverage. |
| Regulatory Sandbox Engagement | Singapore MAS and German BaFin programs accelerate real-time testing of automated underwriting platforms. |
Research Methodology
Operator-level perspectives from chief underwriting officers, blockchain protocol risk managers, regulatory compliance leads at payment processors, and API integration specialists anchored the qualitative base. Primary interviews combined with secondary validation against SEC disclosure filings, EBA prudential standard updates, MAS fintech framework documentation, and automated underwriting platform technical specifications. Bottom-up carrier capacity modeling and top-down premium flow analysis provided triangulation across the analysis window.
Sensitivity analysis framed the quantitative approach across product type, service automation intensity, end-user regulatory mandate tier, and jurisdiction-specific compliance architecture. CAGRs derived from algorithmic scoring of carrier expansion trajectories, custody solution proliferation rates, and embedded distribution adoption curves. Oracle feed integration timelines and EU AI Act implementation phases served as industry-specific forecast inputs throughout the modeling period.
Underlying assumptions cover regulatory enforcement consistency, blockchain network reliability, and machine-learning model availability, with deviation risk concentrated in divergent supervisory approaches between SEC and EU frameworks. Recalibration cycles align with material shifts in prudential standard updates, smart-contract exploit frequency, and custody provider institutional adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Parametric Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Germany Reinsurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Jewelry Insurance Market
Insurance
Global Home Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Gap Insurance Market
Insurance
Cyber Insurance Market
Insurance
Auto Extended Warranty Market