
 India Health and Medical Insurance Market | 2026-2036
India Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Health and Medical Insurance Market Foresight
Comprehensive family floater coverage with sum insured above INR 10 lakh is unwinding the mass-market dominance of basic indemnity plans. Star Health and Allied Insurance Company Limited leverages its dedicated health insurance focus to sustain retail channel depth. HDFC ERGO General Insurance Company Limited anchors its position through bancassurance partnerships with HDFC Bank's branch network. Aditya Birla Health Insurance Company Limited differentiates via its health-first wellness-linked product architecture.
Health and medical insurance constitutes a risk-pooling financial contract where premiums are actuarially priced against morbidity tables, hospitalization cost indices, and network provider fee schedules to indemnify policyholders for curative and preventive healthcare expenditures. The mechanism transfers catastrophic out-of-pocket spending risk from individuals to pooled risk pools underwritten by licensed insurers. Family floater policies command the largest premium volume given their tax-advantaged positioning under Section 80D of the Income Tax Act and multi-life coverage efficiency. Online distribution channels represent the fastest-growing acquisition pathway as IRDAI's Bima Sugyaan portal and insurer proprietary apps reduce friction in quote-to-policy issuance. Inpatient care services absorb the dominant share of claims outflows, though preventive care riders are emerging as a margin-accretive attachment category.
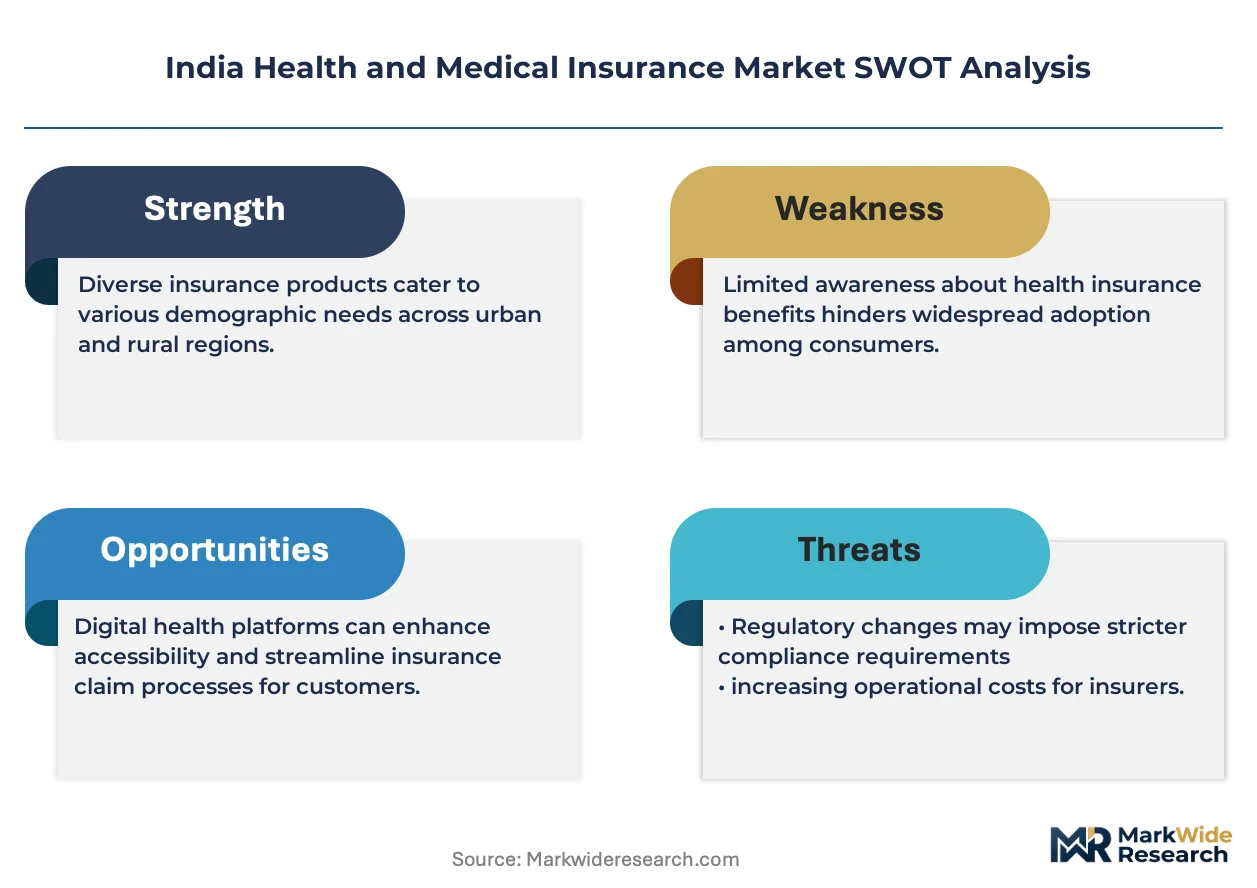
IRDAI mandates solvency margins, product filing approvals, and grievance redressal standards that constrain new entrant speed while protecting policyholder interests. BIS guidelines on health data interoperability and the Digital Information Security in Healthcare Act framework shape insurer IT infrastructure investments and data governance protocols. Stakeholders must monitor how IRDAI's proposed risk-based capital regime recalibrates pricing freedom and product innovation boundaries.
Market Dynamics
IRDAI's sandbox framework for digital-first health products is compressing product development cycles and enabling insurers to test parametric coverage models without full filing requirements. This regulatory flexibility is reshaping competitive positioning by rewarding technology infrastructure over traditional branch density.
Growth Catalysts
- Section 80D Tax Incentives:Annual deductions up to INR 75,000 for senior citizen premiums and INR 25,000 for self/family drive family floater adoption among salaried households in metro clusters.
- Hospital Network Density:Maharashtra, Karnataka, and Tamil Nadu concentrate tertiary care infrastructure that enables cashless claim settlement and reduces policy servicing friction.
- Telemedicine Integration:IRDAI-mandated coverage of virtual consultations post-pandemic is expanding outpatient rider attachment rates and improving risk pool diversification.
Market Restraints
- Adverse Selection Concentration:Urban professional segments with higher health awareness disproportionately purchase coverage, elevating morbidity assumptions in pricing models.
- Claims Cost Inflation:Medical procedure tariffs at corporate hospital chains in Delhi and Mumbai escalate faster than premium revision cycles, compressing combined ratios.
- Distribution Channel Friction:Agent commission caps under IRDAI guidelines limit incentive structures for rural penetration while digital literacy gaps persist in Tier-3 cities.
Strategic Opportunities
- Tier-2 and Tier-3 Expansion:Underpenetrated districts in Uttar Pradesh, Bihar, and Madhya Pradesh present whitespace for simplified indemnity products with lower sum insured thresholds.
- Wellness-Linked Architecture:Wearable integration and fitness score premium discounts align with IRDAI's preventive health promotion mandate while improving lapse ratios.
- Microinsurance Convergence:Integration with Jan Dhan-Aadhaar-Mobile infrastructure enables sachet-sized policies for informal sector workers excluded from employer-sponsored coverage.
Industry Challenges
- Actuarial Talent Scarcity:Specialized health insurance pricing expertise remains concentrated among a limited pool of professionals familiar with Indian morbidity tables.
- Legacy System Integration:Core policy administration platforms at established insurers require middleware layers to connect with IRDAI's Bima Sugyaan portal and real-time claim adjudication networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Health and Medical Insurance Market |
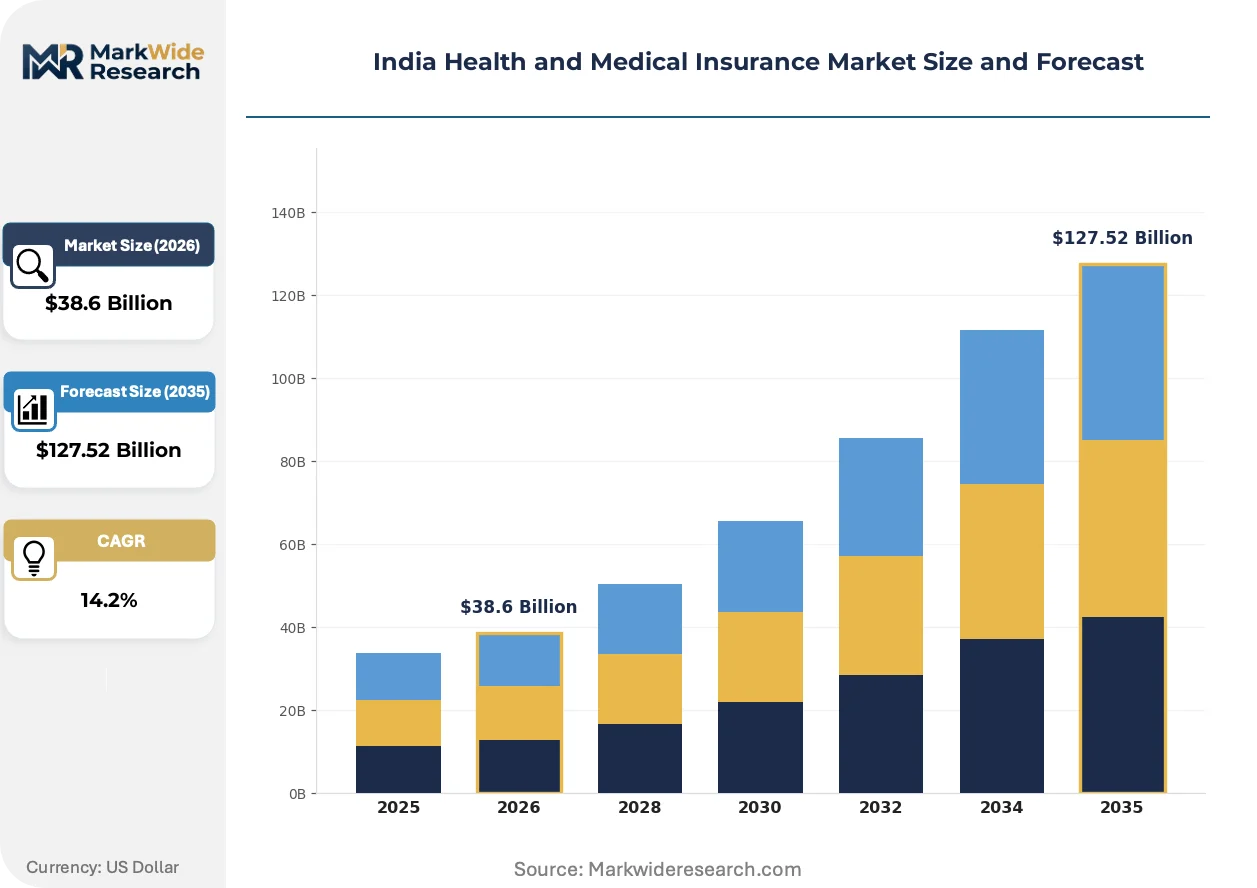
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family Floater, Top-Up, Critical Illness Service Type: Inpatient Care, Outpatient Care, Preventive Care, Maternity Coverage Distribution Channel: Online, Agent, Broker, Direct Sales Customer Segment: Urban Professionals, Senior Citizens, Small Business Owners, Rural Families |
| Companies Covered | HDFC ERGO General Insurance Company Limited, Aditya Birla Health Insurance Company Limited, Star Health and Allied Insurance Company Limited, Tata AIG General Insurance Company Limited, ManipalCigna Health Insurance Company Limited, Care Health Insurance Limited, ICICI Lombard General Insurance Company Limited, Bajaj Allianz General Insurance, Niva Bupa Health Insurance Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Health and Medical Insurance Market Shifts & Advancements
Digital distribution infrastructure and data-driven underwriting are displacing paper-based processes across the policy lifecycle. Insurers are investing in API-first architectures that embed insurance into healthcare provider workflows.
Artificial intelligence in claims adjudication is fragmenting traditional manual review processes. Machine learning models trained on hospital billing patterns now flag anomalies in real-time. Tier-1 insurers in Mumbai and Bangalore deploy these systems for pre-authorization decisions. The technology is compressing claim settlement timelines from weeks to hours while reducing operational expense ratios.
IRDAI's risk-based capital regime proposal is recalibrating product filing requirements. Insurers with advanced data governance frameworks gain faster approval timelines for innovative coverage structures. Digital-first insurers with cloud-native infrastructure are positioning to exploit this regulatory differentiation against legacy competitors with on-premise systems.
Employer-sponsored group coverage is displacing individual retail purchases as the dominant acquisition channel. Large IT services firms and manufacturing conglomerates in Hyderabad and Pune negotiate master policies covering extended families. This concentration is shifting pricing power toward corporate brokers and compressing retail agent commissions in saturated urban markets.
India Health and Medical Insurance Market Segmentation
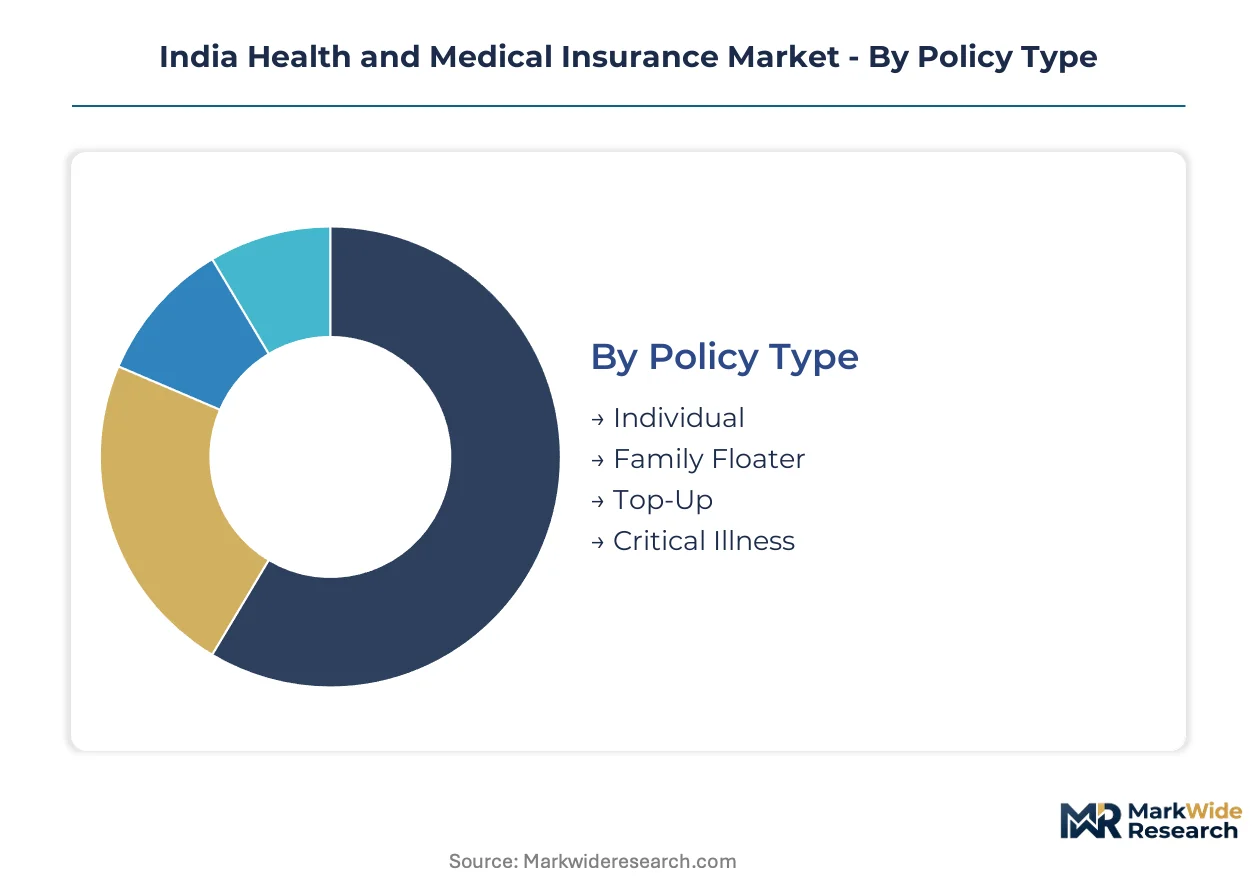
Segmentation reveals how premium pools concentrate across policy structures and service configurations in India's health insurance expansion. Distinct margin profiles emerge between indemnity-based products and wellness-linked preventive offerings.
Policy Type:
Margin pools concentrate in multi-life coverage structures that leverage tax efficiency and household risk pooling.
- Individual:Single-life indemnity contracts priced against personal morbidity profiles. Demand concentrates among unmarried urban professionals in Bangalore and Hyderabad seeking portable coverage independent of employer plans. Premiums scale with age-banded pricing and pre-existing condition loading.
- Family Floater:Multi-life umbrella policies covering spouse, children, and parents under unified sum insured. Maharashtra and Karnataka households drive volume given dual-income salary structures and Section 80D optimization. This segment captures the largest premium share through tax-advantaged positioning.
- Top-Up:Superimposed coverage activating beyond base policy thresholds. Corporate employees in Delhi-NCR attach these to employer-sponsored group schemes for enhanced catastrophic protection.
- Critical Illness:Lump-sum payout contracts triggered by defined diagnosis events. Tamil Nadu's aging demographic clusters generate concentrated uptake for cancer and cardiac coverage riders.
Family Floater holds installed capacity. Critical Illness is rotating up the share rankings.
Service Type:
Cost tier differentiation separates basic hospitalization coverage from value-added preventive and outpatient attachments.
- Inpatient Care:Hospitalization indemnity covering room charges, surgical procedures, and ICU stays. Claims outflows dominate here as corporate hospital chains in Mumbai and Delhi escalate procedure tariffs faster than premium revision cycles.
- Outpatient Care:Ambulatory consultation and diagnostic coverage traditionally excluded from base policies. IRDAI-mandated telemedicine inclusion post-pandemic is expanding attachment rates among tech-savvy urban subscribers.
- Preventive Care:Wellness screening, vaccination, and health check-up benefits. Aditya Birla Health and other innovators bundle fitness tracking discounts to improve lapse ratios and risk pool quality.
- Maternity Coverage:Prenatal, delivery, and newborn care benefits with defined waiting periods. Young professional couples in Pune and Chennai drive selective attachment to family floater base policies.
Inpatient Care anchors premium volume. Preventive Care is expanding most quickly as insurers differentiate through wellness-linked architectures.
Distribution Channel:
Volume concentration is shifting from commission-driven intermediation toward direct digital acquisition.
- Online:Proprietary insurer apps and aggregator platforms enabling quote-to-issuance in minutes. IRDAI's Bima Sugyaan portal reduces friction for digitally literate urban professionals across Tier-1 cities.
- Agent:Individual representatives earning capped commissions under IRDAI guidelines. Persistency challenges emerge as incentive structures constrain rural penetration in Uttar Pradesh and Bihar.
- Broker:Corporate intermediaries negotiating master policies for employer groups. IT services firms in Hyderabad and manufacturing conglomerates in Pune consolidate purchasing power through this channel.
- Direct Sales:Insurer-employed outreach teams targeting specific demographic clusters. Star Health deploys dedicated feet-on-street for senior citizen engagement in Kerala and Tamil Nadu.
Agent networks retain policy servicing infrastructure. Online is climbing the fastest as sandbox regulations compress digital product development cycles.
Customer Segment:
Application context determines product complexity and sum insured thresholds across demographic clusters.
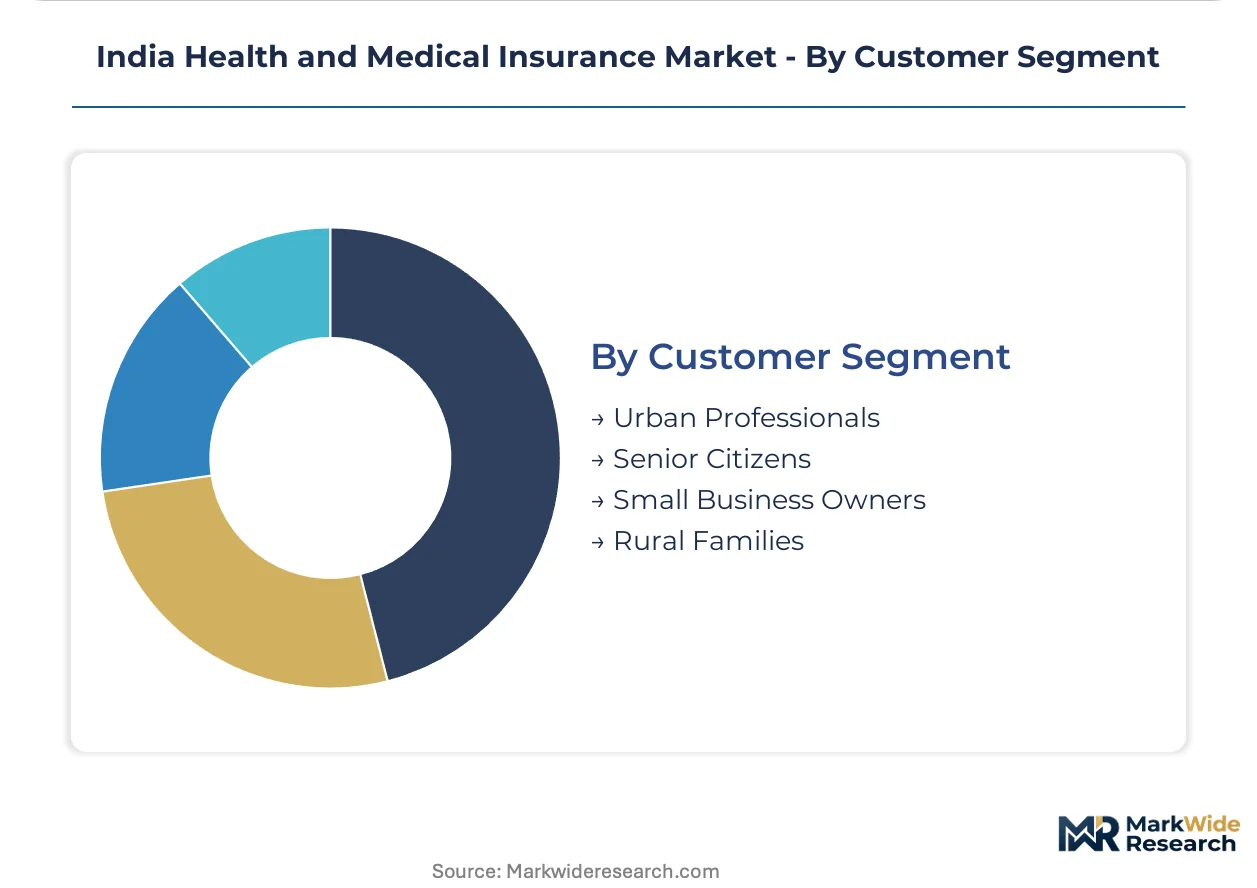
- Urban Professionals:Salaried households in metro clusters seeking comprehensive family floater coverage above INR 10 lakh. Section 80D awareness and employer coverage gaps drive autonomous purchasing decisions.
- Senior Citizens:Post-retirement individuals facing age-banded premium escalation and co-payment requirements. Coimbatore and Kochi concentration reflects South India's nuclear family transition and elderly independent living patterns.
- Small Business Owners:Informal sector entrepreneurs excluded from employer-sponsored pools. Microinsurance convergence with Jan Dhan-Aadhaar-Mobile infrastructure enables sachet-sized policy access.
- Rural Families:Agricultural and informal labor households in Madhya Pradesh and Rajasthan with limited health literacy and cash flow seasonality. Simplified indemnity products with lower sum insured thresholds address underpenetration.
Urban Professionals command premium pricing power. Rural Families represent the steepest expansion trajectory as distribution infrastructure penetrates Tier-3 districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's health insurance value flows from metropolitan centers to emerging Tier-2 and Tier-3 consumption clusters, with regulatory sandboxes accelerating product diffusion beyond traditional distribution strongholds.
Maharashtra
Mumbai and Pune anchor the highest premium density in India, driven by dual-income professional households optimizing Section 80D tax deductions. IRDAI's sandbox regulations enable faster product approvals for digital-first insurers testing parametric coverage models in this corridor. The Mumbai-Pune belt concentrates bancassurance partnerships and corporate group policy negotiations with IT services firms.
Karnataka
Bangalore's technology workforce generates concentrated demand for portable individual policies independent of employer-sponsored coverage. The state's high digital literacy supports rapid adoption of insurer proprietary apps and the Bima Sugyaan portal for quote-to-issuance. Apollo Hospitals and Manipal Health Enterprises anchor cashless network density in Bangalore and Mysore clusters.
Tamil Nadu
Chennai and Coimbatore exhibit elevated critical illness rider attachment rates tied to aging demographic transitions and nuclear family structures. IRDAI-mandated telemedicine coverage post-pandemic expanded outpatient benefit penetration among urban subscribers. Star Health deploys dedicated direct sales teams for senior citizen engagement across Kerala-adjacent districts.
Telangana
Hyderabad's pharmaceutical and IT services conglomerates negotiate master group policies covering extended families, shifting pricing power toward corporate brokers. The state's emerging hospital network infrastructure supports cashless claim settlement expansion into Tier-2 districts. Niva Bupa and Care Health Insurance target this corridor for employer-sponsored coverage consolidation.
Delhi-NCR
The National Capital Region absorbs the steepest medical procedure tariff inflation at corporate hospital chains, compressing insurer combined ratios and accelerating top-up policy attachment. IRDAI's proposed risk-based capital regime recalibrates pricing freedom for insurers with advanced data governance frameworks. Gurugram and Noida clusters concentrate third-party administrator operations and real-time claim adjudication technology deployment.
India Health and Medical Insurance Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel depth and technology infrastructure investment. The market exhibits tiered concentration with dedicated health insurers, diversified general insurers, and bancassurance-anchored players occupying distinct strategic positions. Three archetypes dominate: retail channel specialists leveraging feet-on-street density, digital-first entrants exploiting sandbox regulatory flexibility, and bank-backed platforms deploying branch network access. Competitive intensity centers on M&A consolidation for hospital network control and API-first technology partnerships embedding insurance into provider workflows.
Within the dedicated health insurer tier, Star Health and Allied Insurance Company Limited exemplifies retail channel specialization with focused disease-specific product architecture, while Aditya Birla Health Insurance Company Limited represents wellness-linked differentiation through fitness score premium discount models. Among diversified general insurers with bank distribution advantages, HDFC ERGO General Insurance Company Limited anchors bancassurance positioning through HDFC Bank branch network integration.
| Leading Market Players |
|---|
| HDFC ERGO General Insurance Company Limited |
| Aditya Birla Health Insurance Company Limited |
| Star Health and Allied Insurance Company Limited |
| Tata AIG General Insurance Company Limited |
| ManipalCigna Health Insurance Company Limited |
| Care Health Insurance Limited |
| ICICI Lombard General Insurance Company Limited |
| Bajaj Allianz General Insurance |
| Niva Bupa Health Insurance Company Limited |
| Others |
Supply & Pricing Matrix
Digital-first product architectures are displacing paper-based policy administration systems across Tier-1 cities, simultaneously compressing development cost structures and redrawing competitive geography toward cloud-native insurers with lower fixed-cost bases.
Pricing Analysis
Legacy indemnity products versus wellness-linked next-generation offerings versus sandbox-enabled parametric models create a three-tier pricing structure across premium, standard, and economy levels. Premium differentiation hinges on sum insured thresholds above INR 10 lakh and fitness-score-linked discounts from wearable integration. Cost compression in standard tiers is intensifying because medical procedure tariffs at corporate hospital chains escalate faster than premium revision cycles. Small business owners in informal sectors exhibit highest price sensitivity, while dual-income urban professional households in Maharashtra and Karnataka show lowest sensitivity due to Section 80D tax optimization.
Supply Chain Analysis
India anchors policy administration infrastructure and actuarial talent pools, while Ireland and Singapore host reinsurance capacity and catastrophe modeling capabilities. Core inputs draw from hospital network density in Tamil Nadu and Karnataka, telemedicine platform providers in Bangalore, and third-party administrator services in Delhi-NCR. Single-source vulnerability concentrates in legacy core policy administration platforms requiring middleware layers for IRDAI portal integration. Distribution runs through proprietary insurer apps, bancassurance branch networks, and corporate broker intermediation for employer-sponsored master policies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IRDAI's sandbox framework for digital-first health products creates a high-growth disruption window, compressing product development cycles from months to weeks while rewarding technology infrastructure over traditional branch density.
For Market Incumbents: Fortify retail channel depth through dedicated feet-on-street deployment for senior citizen engagement in Kerala and Tamil Nadu, while accelerating API-first architectures to embed insurance into hospital provider workflows. Threats from digital-first entrants with cloud-native infrastructure demand middleware elimination and direct Bima Sugyaan portal connectivity.
For New Entrants and Emerging Players: Lead with simplified indemnity products targeting underpenetrated Tier-2 and Tier-3 districts in Uttar Pradesh, Bihar, and Madhya Pradesh where agent commission caps constrain incumbent rural penetration. Jan Dhan-Aadhaar-Mobile infrastructure enables sachet-sized microinsurance access for informal sector workers excluded from employer-sponsored coverage.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital-first insurers possessing sandbox regulatory approvals and wellness-linked product architectures. Long-term viability centers on preventive care rider attachment rates and lapse ratio improvement through fitness-score premium discounts. Watch IRDAI's risk-based capital regime proposal as the inflection signal for pricing freedom recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Deployment | Embeds insurance into Apollo Hospitals and Manipal Health Enterprises workflows for real-time pre-authorization. |
| Wellness-Linked Product Launch | Aditya Birla Health's fitness-score premium discounts improve lapse ratios and risk pool quality metrics. |
| Tier-2/Tier-3 Geographic Expansion | Star Health's dedicated direct sales teams penetrate whitespace districts in Madhya Pradesh and Rajasthan. |
| Reinsurance Capacity Diversification | Singapore and Ireland catastrophe modeling capabilities reduce concentration in domestic risk pools. |
| Telemedicine Platform Integration | IRDAI-mandated virtual consultation coverage expands outpatient rider attachment among Bangalore subscribers. |
Research Methodology
Operator-level perspectives from actuarial pricing directors, hospital network contracting managers, IRDAI regulatory affairs leads, and corporate broker intermediaries anchored the qualitative base. Primary interviews combined with secondary validation from IRDAI product filing databases, Bima Sugyaan portal statistics, hospital procurement records, and Income Tax Department Section 80D utilization data. Bottom-up policy volume triangulation against top-down premium pool estimates established segmentation integrity.
Sensitivity analysis across multiple scenario assumptions tested forecast robustness over the projection horizon. Segmentation dimensions modeled include policy type, service configuration, distribution channel, and customer demographic cluster. CAGRs derived from actuarial morbidity table projections, hospital cost inflation indices, and digital adoption curve parameters. Key inputs encompass network provider fee schedule escalations and telemedicine penetration rates.
Forecasts assume regulatory continuity in IRDAI sandbox frameworks and risk-based capital regime proposals; material policy shifts would require re-modeling. Specific risks include adverse selection concentration in urban professional segments and claims cost inflation at corporate hospital chains. Recalibration cycles align with material shifts in IRDAI filing requirements and hospital network density expansion patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
General Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Small Business Insurance Market
Insurance
Gap Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
United States Bancassurance Market
Insurance
Marine Cargo Insurance Market
Insurance
United States Commercial Insurance Market
Insurance
Saudi Arabia Travel Insurance Market