
 Data Analytics in Insurance Market | 2026-2036
Data Analytics in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Data Analytics in Insurance Market Insights
Real-time streaming analytics is redrawing competitive boundaries across property and casualty lines. Oracle leverages embedded machine learning within policy administration systems to differentiate its platform for mid-market carriers. Microsoft anchors cloud infrastructure demand through Azure Synapse integrations with actuarial workflows. IBM Corporation sustains consulting-heavy deployments that extend legacy mainframe data into modern analytics pipelines.
Data analytics in insurance encompasses the systematic extraction, transformation, and modeling of structured and unstructured data to generate actionable intelligence for risk selection, pricing, and loss reserving, typically operating across terabyte-scale policy and claims repositories with sub-second query latency for operational decisions. Predictive analytics dominates solution-type revenue as carriers retrofit legacy rating engines with gradient-boosted models for personal auto and homeowners segments. Cloud-based deployment is capturing the fastest expansion as regulated entities resolve data residency concerns through sovereign cloud configurations from hyperscalers. Claims analysis within the application dimension commands premium pricing due to the measurable return on investment from automated fraud detection and reserve adequacy improvements.
FDA guidelines on software-as-medical-device intersect with health insurance analytics where wellness program incentives touch diagnostic thresholds, while the EU AI Act imposes conformity assessments on automated underwriting algorithms deployed by carriers writing cross-border European risks. State insurance commissioners in the United States are scrutinizing proxy discrimination in pricing models, creating compliance-driven refresh cycles for rating engine software. Stakeholders must weigh the capital efficiency of cloud migration against the operational risk of multi-tenant data architectures before committing to platform consolidation roadmaps.
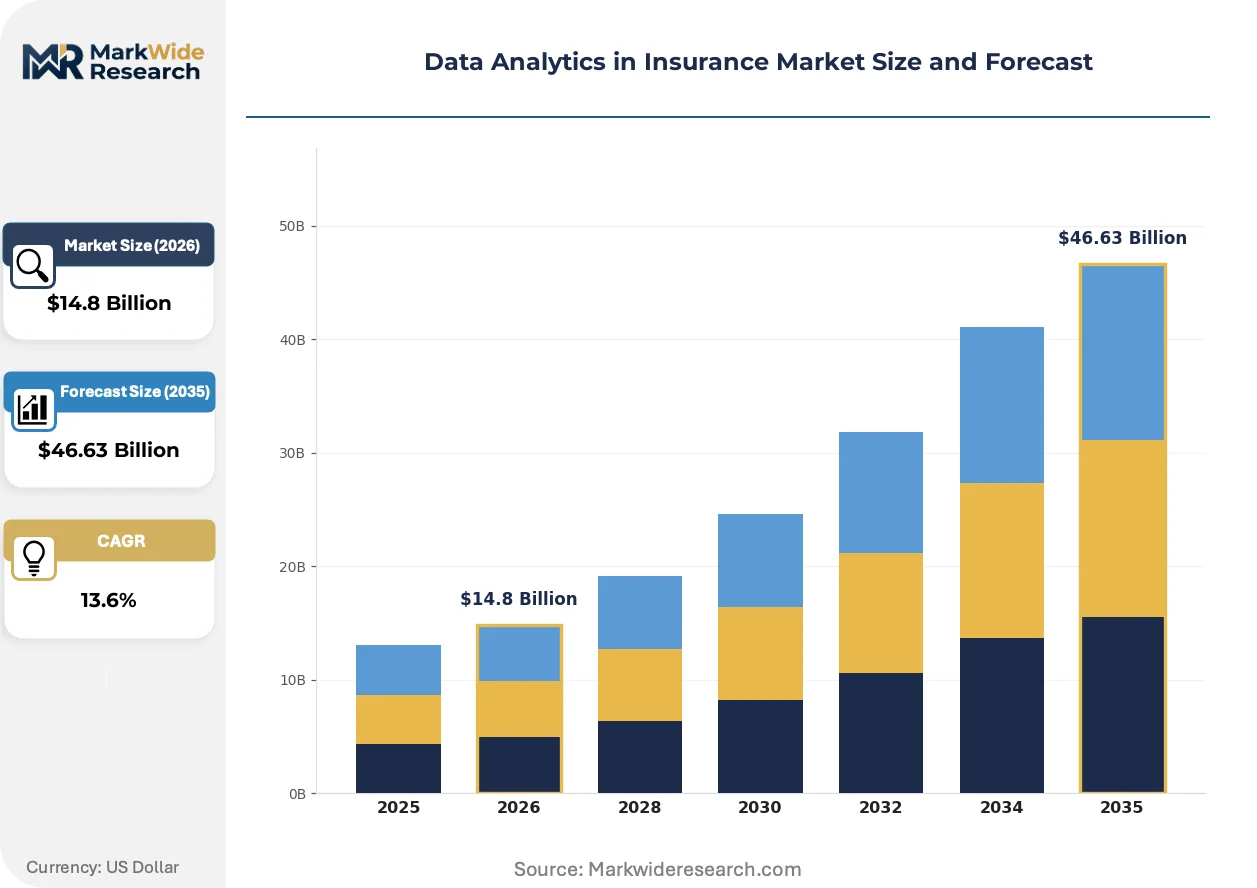
Market Dynamics
Predictive modeling architectures are forcing carriers to rebuild data infrastructure around real-time inference pipelines rather than batch-processed actuarial tables. Property and casualty insurers face compressed deployment timelines as cloud-native competitors demonstrate sub-second pricing capabilities.
Growth Catalysts
- EU AI Act Conformity Requirements:Automated underwriting algorithms deployed across European Union member states must pass standardized risk assessments, creating mandatory refresh cycles for rating engine software.
- Gradient-Boosted Machine Learning:Personal auto and homeowners segments are retrofitting legacy rating engines with ensemble methods that improve loss ratio predictability.
- United States Data Lake Consolidation:Large carriers operating multiple lines of business are unifying terabyte-scale policy and claims repositories into single analytics platforms.
Market Restraints
- Mainframe Integration Costs:Legacy policy administration systems built on COBOL architectures require expensive middleware layers to feed modern analytics pipelines.
- Data Residency Compliance:Regulated entities in Germany, France, and Switzerland must maintain sovereign cloud configurations that fragment infrastructure economics.
- Actuarial Talent Scarcity:The intersection of traditional reserving expertise and machine learning engineering remains undersupplied relative to carrier demand.
Strategic Opportunities
- India Stack Integration:Unified Payments Interface and Aadhaar-linked data streams enable parametric insurance products with minimal friction.
- Embedded Distribution Partnerships:Automotive OEMs and IoT device manufacturers are becoming direct channels for usage-based coverage.
- Wellness Incentive Convergence:FDA software-as-medical-device guidelines intersect with health insurance analytics where diagnostic thresholds trigger premium adjustments.
Industry Challenges
- Proxy Discrimination Audits:State insurance commissioners in California, New York, and Texas are retroactively testing pricing models for prohibited variable correlations.
- Multi-Tenant Security Architecture:Cloud migration roadmaps must weigh capital efficiency against operational risk of shared infrastructure for regulated data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Analytics in Insurance Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Analytics, Risk Management, Fraud Detection, Customer Segmentation, Claims Analysis Application: Underwriting, Policy Management, Customer Acquisition, Claims Processing, Regulatory Compliance Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Insurance Carriers, Brokers, Actuarial Firms, Reinsurance Companies |
| Companies Covered | Salesforce, Microsoft, Google, Oracle, SAP, IBM Corporation, SAS Institute Inc., Snowflake, Guidewire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Analytics in Insurance Market Trends and Innovations
Real-time streaming architectures are compressing the latency window between data ingestion and underwriting decision from hours to milliseconds. This shift is redrawing competitive boundaries across property and casualty lines.
Embedded machine learning within policy administration systems is displacing standalone analytics platforms. Mid-market carriers are adopting these integrated suites to avoid separate data engineering teams. The structural consequence is collapsing vendor consolidation timelines as carriers prefer single-source accountability over best-of-breed assembly.
The EU AI Act imposes conformity assessments on automated underwriting algorithms deployed by carriers writing cross-border European risks. Risk-based classification systems now mandate documentation trails for high-risk insurance decisions. French and German regulators are coordinating enforcement mechanisms that affect Lloyd's syndicates and Bermuda reinsurers equally.
Carrier procurement patterns favor outcome-based pricing for fraud detection vendors rather than per-seat software licenses. Claims departments in the United States are unbundling detection modules from core policy systems. This shift is most visible among regional mutual insurers seeking measurable ROI on reserve adequacy improvements.
Data Analytics in Insurance Market Segmentation
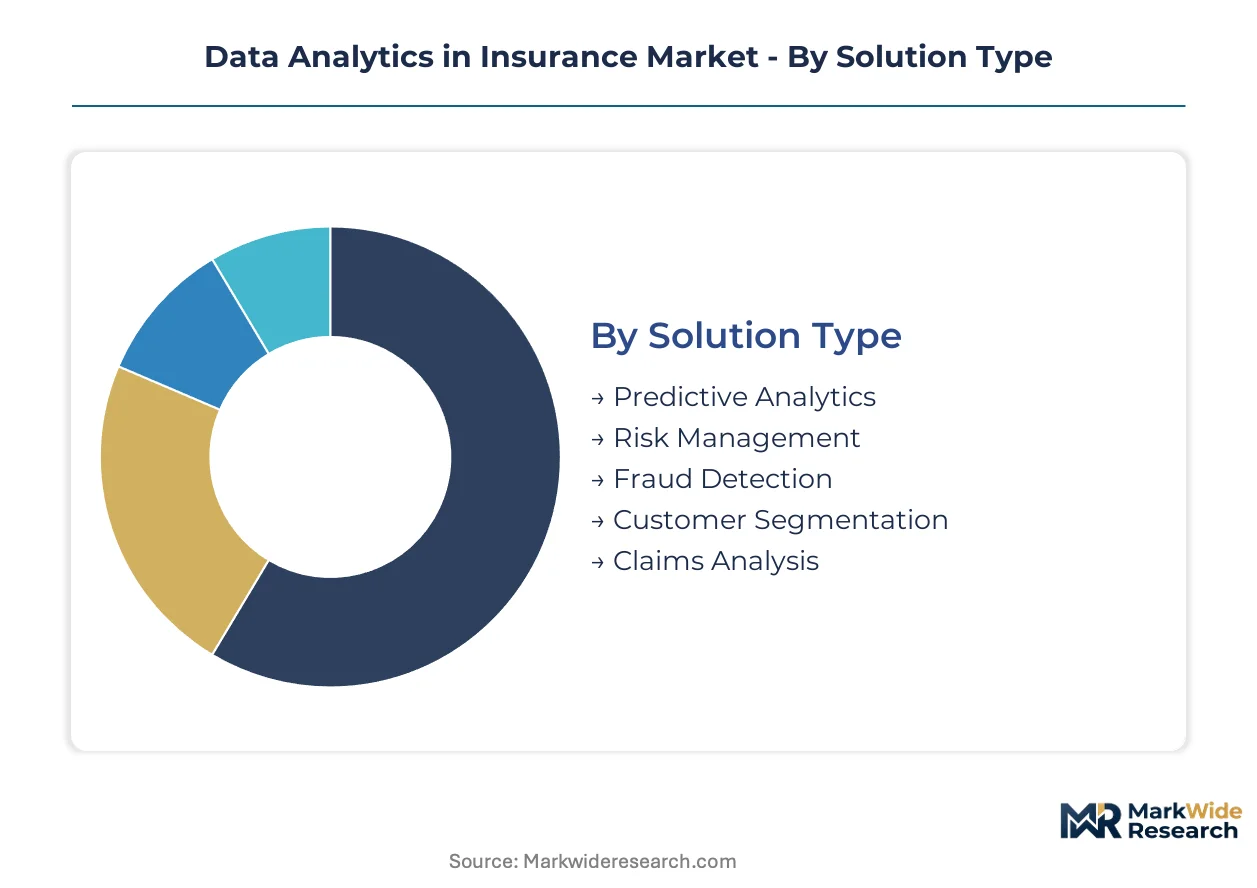
Segmentation in insurance analytics reveals how technology investments flow through distinct operational channels. Carriers allocate budgets differently across underwriting automation, claims optimization, and regulatory infrastructure, creating divergent vendor strategies for each pathway.
Solution Type:
Predictive analytics and fraud detection solutions move through direct enterprise sales channels, while customer segmentation tools increasingly route through embedded partnerships with policy administration platforms.
- Predictive Analytics:Gradient-boosted and ensemble methods retrofit legacy rating engines for personal auto and homeowners lines. United States carriers concentrate demand here as competitive pressure forces sub-second pricing capabilities.
- Fraud Detection:Real-time anomaly detection architectures analyze claim patterns against behavioral baselines. Procurement is shifting toward outcome-based pricing tied to measurable reserve adequacy improvements rather than per-seat licenses.
- Risk Management:Portfolio-level catastrophe modeling and concentration analysis for reinsurance ceding decisions.
- Customer Segmentation:Lifetime value scoring and churn prediction for retention marketing automation.
- Claims Analysis:Automated reserve setting and litigation propensity scoring for casualty lines.
Predictive analytics dominates installed base. Fraud detection is where expansion concentrates.
Application:
Cost tier stratification separates mission-critical underwriting systems from administrative policy tools, with claims processing occupying the premium investment band due to direct loss ratio impact.
- Claims Processing:Automated triage, fraud flagging, and reserve adequacy workflows compress settlement cycles. United States property and casualty carriers drive volume here as state commissioners mandate faster resolution timelines.
- Underwriting:Real-time risk scoring and automated decision engines for standard personal lines. EU AI Act conformity requirements are forcing algorithmic documentation investments for cross-border European risks.
- Policy Management:Endorsement processing and renewal pricing optimization.
- Customer Acquisition:Lead scoring and embedded distribution analytics.
- Regulatory Compliance:Proxy discrimination testing and algorithmic audit trails.
Claims processing commands premium pricing. Underwriting is climbing the fastest as carriers retrofit legacy engines.
Deployment Model:
Volume concentration favors cloud-native architectures, though data residency constraints fragment infrastructure economics across regulated jurisdictions.
- Cloud-Based:Hyperscaler platforms with sovereign configurations for German, French, and Swiss data localization mandates. Large United States carriers consolidate terabyte-scale repositories here, resolving prior residency objections through dedicated tenant options.
- Hybrid:Sensitive reserving data remains on-premises while customer-facing analytics shift to cloud. Mid-market carriers prefer this pathway to balance capital efficiency against operational risk exposure.
- On-Premises:Legacy mainframe-integrated installations for COBOL-dependent policy systems.
- Edge Computing:Telematics and IoT sensor processing for usage-based auto products.
Cloud-based deployments hold majority share. Hybrid architectures are gaining share fastest among regional mutual insurers.
End User:
Customer type maturity separates digitally native carriers from intermediaries, with actuarial firms occupying a consulting-heavy niche resistant to platform consolidation.
- Insurance Carriers:Full-stack implementations spanning underwriting through claims. United States large carriers drive platform consolidation across multiple lines of business, unifying previously siloed data lakes.
- Brokers:Comparative rating and placement analytics for commercial lines. Embedded distribution partnerships with automotive OEMs are creating direct channel competition.
- Actuarial Firms:Reserving and capital modeling services with legacy mainframe integration requirements.
- Reinsurance Companies:Catastrophe bond pricing and retrocession analytics.
Insurance carriers dominate vendor revenue. Brokers are expanding most quickly as embedded distribution reshapes channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net data analytics service flows favor the United States as a net exporter of insurance technology platforms, while Germany and Switzerland import specialized actuarial analytics capabilities. The United Kingdom maintains bilateral technology trade with Lloyd's syndicates sourcing cloud infrastructure from US hyperscalers. Asia-Pacific markets exhibit mixed patterns: India exports data engineering talent while Japan imports predictive modeling platforms.
United States
Large property and casualty carriers drive terabyte-scale data lake consolidation across multiple lines of business. State insurance commissioners in California, New York, and Texas enforce proxy discrimination audits that mandate rating engine refreshes. The Hartford and Boston insurance corridors concentrate vendor development for real-time claims analytics.
Germany
Munich Re and Allianz anchor demand for catastrophe modeling and portfolio concentration analytics. The country's national data protection regulator enforces sovereign cloud mandates that fragment infrastructure economics for cross-border carriers. The Frankfurt Rhine-Main metropolitan region hosts compliance-focused algorithmic audit consultancies serving EU-wide risks.
United Kingdom
Lloyd's syndicates and London market insurers generate specialized demand for reinsurance ceding analytics and retrocession modeling. The Prudential Regulation Authority coordinates with EU AI Act implementation for algorithms processing European risks. The City of London cluster sustains boutique actuarial firms integrating legacy mainframe data into modern pipelines.
India
Domestic insurers leverage Aadhaar-linked identity verification and UPI payment rails for parametric product distribution. The central bank's data localization guidelines shape cloud deployment decisions for foreign carriers operating locally. Bangalore and Hyderabad technology corridors supply data engineering talent to global insurance platforms.
Switzerland
Zurich-based reinsurers and private banks demand high-precision reserving analytics for alternative risk transfer structures. Swissmedic and FINMA coordinate on wellness program incentives that intersect with diagnostic thresholds. The Zurich-Geneva axis concentrates specialized vendors serving cross-border European and Middle Eastern risks.
Data Analytics in Insurance Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and embedded analytics dimensions. Hyperscaler platforms capture majority share in data lake consolidation, while vertical specialists retain pockets in fraud detection and actuarial consulting. Two archetypes dominate: cloud-native platform providers with sovereign configuration capabilities, and legacy systems integrators bridging mainframe-to-modern pipelines. Competitive moves concentrate on strategic partnerships with automotive OEMs for embedded distribution, and outcome-based pricing models for fraud detection modules.
Within the cloud platform tier, Microsoft, Oracle, and Salesforce represent the primary anchors for carrier procurement decisions. Microsoft exemplifies the hyperscaler archetype through Azure Synapse integrations with actuarial workflows. Oracle occupies a position as the embedded machine learning specialist within policy administration suites for mid-market carriers. Salesforce sits within the customer-facing analytics segment, anchoring distribution and retention marketing automation for personal lines insurers.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft |
| Oracle |
| SAP |
| IBM Corporation |
| SAS Institute Inc. |
| Snowflake |
| Guidewire |
| Others |
Pricing and Supply Chain Analysis
Outcome-based pricing contracts for fraud detection modules lock in multi-year vendor relationships while capping carrier expenditure to measurable reserve adequacy improvements. This structure concentrates procurement power among large United States property and casualty carriers who can demonstrate actuarial ROI, forcing mid-market mutual insurers toward subscription-tier SaaS alternatives with lower upfront commitment.
Pricing Analysis
Industrial OEM buyers anchor subscription-tier pricing for embedded analytics suites within policy administration systems. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler cloud configurations from mid-market SaaS bundles and on-premises legacy integrations. Price differentiation rests on data sovereignty certification level and volume-scale commitment duration. Cost compression in the standard tier is intensifying because Oracle and Microsoft are bundling machine learning modules into base platform licenses. Regional mutual insurers exhibit highest price sensitivity due to constrained IT budgets, while Lloyd's syndicates and Bermuda reinsurers prioritize compliance-grade documentation over unit cost.
Supply Chain Analysis
Just-in-time provisioning of cloud compute resources dominates infrastructure procurement, though carriers maintaining German or Swiss data residency mandates maintain strategic stockpiles of sovereign-configured server capacity. Geographic supply concentration centers on the United States for hyperscaler platform development, India for data engineering talent pipelines, and Ireland for EU-facing cloud infrastructure. Raw material dependencies include specialized GPUs for model training, encrypted storage arrays for claims repositories, and low-latency networking hardware for real-time underwriting. Single-source vulnerability persists in sovereign cloud configurations where only Microsoft and Oracle currently meet German BSI certification requirements. Distribution runs through direct enterprise sales teams for large carriers and embedded partnerships with Guidewire-type policy platforms for mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large United States carriers consolidating terabyte-scale data lakes, fragmenting vendor pricing leverage across smaller mutual insurers and regional brokers who lack comparable procurement scale.
For Market Incumbents: Consolidate platform offerings around embedded machine learning within policy administration suites to counter standalone analytics vendors. Deepen backward integration into sovereign cloud infrastructure for German and Swiss data residency compliance. Priority defensive move: acquire boutique actuarial consultancies bridging COBOL mainframe data into modern pipelines before cloud-native competitors capture this integration layer. For New Entrants and Emerging Players: Mid-market carrier demand for outcome-based fraud detection pricing represents an under-served service-layer gap where incumbents still rely on per-seat licensing. Target regional mutual insurers in the United States seeking measurable ROI on reserve adequacy without dedicated data engineering teams. Go-to-market angle: pre-integrated modules with Guidewire or Duck Creek policy platforms that collapse deployment timelines. For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with EU AI Act conformity assessment capabilities and Lloyd's market relationships. Long-term viability across the analysis window favors vendors combining algorithmic audit documentation with sovereign cloud deployment options. Signal to watch: carrier procurement shifts from best-of-breed assembly toward single-source platform accountability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded machine learning within policy administration collapses separate analytics vendor relationships for mid-market carriers. |
| Strategic Partnership | Automotive OEM alliances create direct distribution channels for usage-based auto products bypassing traditional broker networks. |
| Acquisition of Specialist Firm | COBOL-to-modern pipeline consultancies command scarcity premiums as mainframe integration talent remains undersupplied. |
| Geographic Expansion | Sovereign cloud configurations in Germany and Switzerland resolve data residency barriers for cross-border European risks. |
| Product Launch | Real-time streaming analytics architectures compress underwriting decision latency from hours to milliseconds in personal auto lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs and secondary validation protocols. Carrier chief data officers, actuarial firm partners, cloud platform solution architects, and state insurance commissioner technical staff provided operational perspective. Secondary sources included SEC 10-K filings from listed insurers, EU AI Act implementation guidance from national regulators, and hyperscaler sovereign cloud certification disclosures. Bottom-up sizing of vendor revenue streams was triangulated against top-down carrier IT budget allocations.
Across the analysis window, the forecasting framework modeled solution type, deployment model, application dimension, and end-user category segmentation. CAGRs were derived from trend extrapolation of carrier platform consolidation timelines and regulatory-driven refresh cycles. Industry-specific inputs included EU AI Act conformity assessment schedules and United States state commissioner proxy discrimination audit frequencies.
Forecasts assume regulatory continuity in EU AI Act implementation and United States state insurance oversight; material policy shifts would require re-modeling. Revision becomes warranted when sovereign cloud certification requirements expand beyond current German BSI and French ANSSI frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Liability Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Travel Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Embedded Insurance Market
Insurance
Online Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Financial Guarantee Market
Insurance
North America Liability Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
Specialty Insurance Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
India Property & Casualty Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Japan Parametric Insurance Market