
 Mobile Phone Insurance Market | 2026-2036
Mobile Phone Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Phone Insurance Market Outlook
GDPR data-handling mandates for device repair records is repositioning the cost-of-entry calculus for insurers operating across European markets. Allianz SE leverages its pan-European claims infrastructure to sustain compliance advantages in cross-border mobile coverage. Asurion anchors its competitive position through direct carrier integrations with Verizon and T-Mobile in the United States.
Mobile phone insurance constitutes a risk-transfer mechanism covering physical damage, theft, loss, and malfunction of portable cellular devices, typically underwritten through parametric pricing models tied to device replacement cost algorithms and historical claims frequency data. The product's primary commercial purpose is to reduce consumer replacement expenditure volatility while generating recurring premium revenue for underwriters and distribution partners. Accidental Damage coverage dominates premium volumes due to high-frequency screen breakage claims, while Theft protection commands elevated margins in urban corridors with elevated loss rates. Comprehensive policies distributed through Telecom Providers capture the largest addressable base, though Online Retailers represent the fastest-growing channel as e-commerce handset sales accelerate.
The EU Green Deal's right-to-repair provisions and the FCC's equipment authorization rules in the United States are reshaping claims fulfillment protocols, mandating refurbished component usage and certified repair network participation. India's BIS quality standards and the PLI scheme for domestic electronics manufacturing are conditioning insurer partnerships with local assembly operations. Stakeholders must monitor regulatory divergence between refurbishment mandates and OEM warranty restrictions as policy terms evolve.
Market Dynamics
Enterprise fleet mandates for employee-issued devices are restructuring premium distribution economics, forcing insurers to develop parametric pricing algorithms calibrated to corporate device refresh cycles rather than individual consumer behavior patterns.
Growth Catalysts
- Telecom Bundling Proliferation:Carrier-embedded insurance products in India are collapsing customer acquisition costs through TRAI-mandated transparency in tariff disclosures. Premium uptake accelerates where smartphone financing and coverage activate simultaneously.
- EU AI Act Compliance Infrastructure:Automated claims adjudication systems trained on device damage classification models require algorithmic audit trails. Insurers investing in explainable AI frameworks capture underwriting efficiency gains.
- Screen Durability Stagnation:Foldable display adoption outpaces Gorilla Glass Victus protection improvements. Accidental damage claim frequency rises with form-factor complexity, expanding addressable premium pools.
Market Restraints
- OEM Warranty Encroachment:AppleCare+ and Samsung Care+ vertical integration captures 40-60% of attachable premium within their device ecosystems. Third-party underwriters face exclusion from first-party distribution channels.
- Refurbishment Supply Concentration:Certified pre-owned component networks cluster in Shenzhen and Ho Chi Minh City logistics corridors. Cross-border parts authentication delays extend claims settlement timelines.
- Right-to-Repair Regulatory Friction:EU Green Deal mandates for repairability scoring conflict with OEM software lockout practices. Insurers must maintain dual fulfillment protocols for refurbished and new-component claims.
Strategic Opportunities
- Microinsurance Penetration in Sub-Saharan Africa:M-Pesa-integrated premium collection models enable sub-dollar daily coverage for entry-level smartphones. Regulatory sandboxes in Kenya and Nigeria permit parametric weather-damage riders.
- Cyber-Physical Convergence Products:eSIM-enabled remote device locking is converging with ransomware coverage extensions. Policies covering both hardware theft and data extortion command triple-digit basis-point premium multiples.
- India PLI Scheme Partnerships:Domestic assembly operations under the Production Linked Incentive framework require localized insurer relationships for factory-to-consumer warranty bridges.
Industry Challenges
- Fraud Detection Talent Scarcity:Computer vision specialists capable of training synthetic damage image classifiers command compensation premiums exceeding actuarial department budgets.
- GDPR Repair Record Architecture:Device diagnostic data retention for claims evidence must reconcile with CNIL-mandated erasure timelines. Database partitioning investments strain mid-tier carrier technology budgets.
- Legacy Policy Administration Migration:Mainframe-based rating engines from the 2000s resist API integration with real-time device telemetry feeds. Parallel system operation duplicates operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Phone Insurance Market |
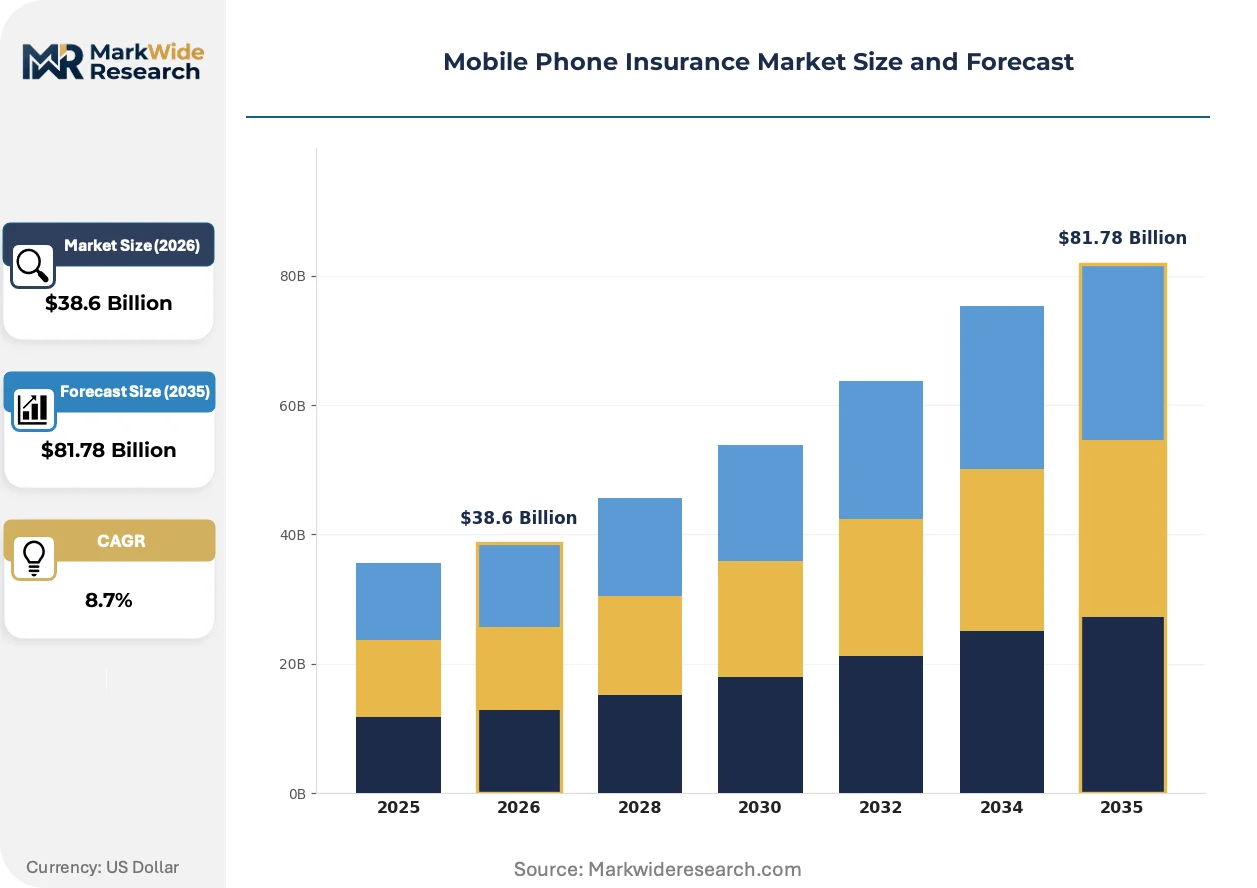
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accidental Damage, Liquid Damage, Theft, Lost Device Coverage Type: Comprehensive, Basic, Extended Warranty, Add-on Distribution Channel: Online Retailers, Telecom Providers, Insurance Brokers, Direct Sales Customer Type: Individual Consumers, Small Businesses, Corporations, Educational Institutions |
| Companies Covered | Allianz SE, AXA Group, Asurion, Chubb, AT&T Inc., Assurant, Inc., Apple Inc., AmTrust Financial, American International Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Phone Insurance Market Strategic Shifts
Telematics-enabled condition monitoring is displacing static risk pools with dynamic premium adjustment models calibrated to actual device handling patterns rather than demographic proxies.
Blockchain-verified device provenance systems are converging with parametric smart contracts. High-value handset insurers in the United Arab Emirates and Singapore deploy immutable ownership records to eliminate duplicate-claim fraud. Settlement automation compresses indemnity cycles from weeks to hours.
The EU Digital Product Passport requirements under the Ecodesign for Sustainable Products Regulation mandate component-level traceability for all electronics sold in member states. Insurers must integrate passport data APIs into claims validation workflows. Repair network certification costs rise as passport compliance becomes a coverage condition.
Corporate procurement departments are unbundling device insurance from hardware leasing agreements. Fortune 500 technology buyers in the United States negotiate standalone coverage through brokerage channels rather than OEM-captive programs. This disintermediation pressures carrier commission structures and accelerates price transparency platforms.
Mobile Phone Insurance Market Segmentation
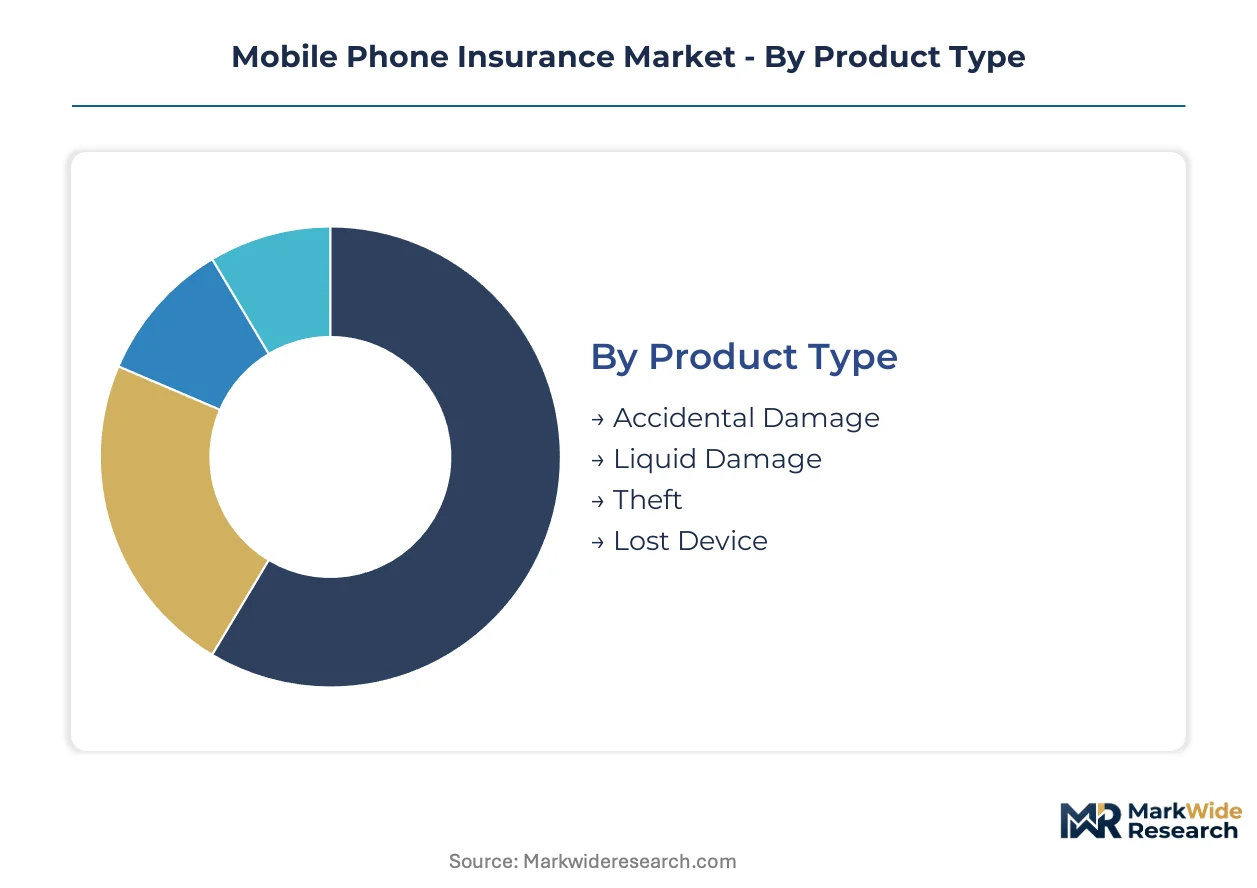
Mobile phone insurance segments diverge sharply in claims infrastructure requirements and customer lifetime value. Underwriters must calibrate pricing algorithms, fulfillment networks, and fraud detection systems to each segment's distinct risk profile and distribution economics.
Product Type:
Capital intensity escalates with claims frequency and forensic complexity, driving divergent investment in repair networks and adjudication systems.
- Accidental Damage:Screen fracture, impact damage, and port failure claims dominate policy utilization. High-frequency claims necessitate dense certified repair networks; premium volumes concentrate in urban India and United States coastal corridors where device replacement costs peak.
- Liquid Damage:Corrosion assessment and component-level diagnostics require specialized lab infrastructure. Demand clusters in humid subtropical markets—Southeast Asia, Gulf Coast United States—where moisture exposure rates exceed temperate benchmarks.
- Theft:Loss verification protocols and law enforcement coordination elevate operational overhead. Urban corridors with elevated street crime rates generate disproportionate claim volumes.
- Lost Device:Geolocation dependency and remote wipe capabilities define coverage scope. Corporate fleet policies drive attachment rates above consumer retail channels.
Accidental Damage absorbs the bulk of installed capacity; Liquid Damage is expanding most quickly.
Coverage Type:
Margin structure varies by claims aggregation method and policy duration, separating recurring revenue models from single-premium transactions.
- Comprehensive:Bundled physical damage, theft, and malfunction protection commands premium multiples over single-peril alternatives. Carrier-embedded distribution through Verizon and Bharti Airtel maximizes attach rates at point of sale.
- Basic:Limited peril coverage—typically screen-only or mechanical failure—targets price-sensitive segments. Direct-to-consumer digital channels in Germany and United Kingdom sustain thin-margin volume.
- Extended Warranty:Manufacturer-backed programs overlap with OEM service contracts, compressing third-party underwriter margins. AppleCare+ and Samsung Care+ vertical control limits addressable market.
- Add-on:Modular peril riders attach to base policies or credit card benefits. Flexibility attracts gig economy workers and seasonal device users.
Comprehensive coverage generates the majority of premium income; Add-on products are climbing the fastest.
Distribution Channel:
Customer acquisition cost spreads separate embedded distribution from brokerage-dependent models by an order of magnitude.
- Telecom Providers:Point-of-sale integration with device financing collapses friction. TRAI-mandated tariff transparency in India and FCC disclosure rules in the United States standardize presentation.
- Online Retailers:E-commerce handset sales—Amazon, Flipkart, JD.com—accelerate coverage attachment through one-click enrollment. Fulfillment speed expectations compress policy issuance windows.
- Insurance Brokers:Corporate procurement and high-net-worth individual placement sustain commission-based intermediation. Fortune 500 technology buyers leverage brokerage for standalone coverage unbundled from OEM programs.
- Direct Sales:Insurer-owned digital platforms and call centers target policy renewals and cross-sell. Retention economics favor established players with claims history data advantages.
Telecom Providers command the dominant share of premium flow; Online Retailers are gaining share fastest.
Customer Type:
Policy administration complexity scales with fleet size and procurement centralization, restructuring back-end platform requirements.
- Corporations:Enterprise mobility management integration demands API connectivity with MDM platforms. Parametric pricing calibrated to refresh cycles—24 to 36 months—replaces individual risk rating.
- Individual Consumers:Mass-market retail distribution through carrier stores and electronics retailers. Churn sensitivity requires frictionless claims experience to sustain renewal rates.
- Small Businesses:Owner-operated firms with 5-50 devices occupy a service gap between consumer and enterprise tiers. Broker channel specialization addresses underserved configuration needs.
- Educational Institutions:K-12 one-to-one device programs and university procurement generate seasonal enrollment spikes. Bulk policy negotiation and student data privacy compliance—GDPR in Europe, FERPA in the United States—elevate contracting complexity.
Individual Consumers represent the largest addressable base; Corporations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Shenzhen anchor mobile insurance underwriting concentration. TRAI-mandated tariff bundling and PLI scheme manufacturing incentives reshape premium distribution economics. EU Green Deal repairability mandates and FCC equipment rules create divergent compliance corridors.
United States
Verizon and T-Mobile carrier-embedded insurance drives premium volumes through point-of-sale activation. FCC equipment authorization rules mandate certified repair network participation for claims fulfillment. Dallas and Atlanta logistics clusters host dense third-party administrator operations serving southeastern device markets.
India
Bharti Airtel and Reliance Jio telecom bundling collapses customer acquisition costs through simultaneous smartphone financing activation. BIS quality standards and PLI scheme incentives condition insurer partnerships with domestic assembly operations. Mumbai and Bangalore financial centers concentrate underwriter regional headquarters and claims processing infrastructure.
Germany
GDPR repair record retention mandates elevate database partitioning investments for device diagnostic evidence. EU AI Act algorithmic audit requirements reshape automated claims adjudication system deployment. Frankfurt insurance hub hosts pan-European policy administration platforms serving cross-border coverage mandates.
United Kingdom
Direct-to-consumer digital channels sustain thin-margin basic coverage distribution to price-sensitive segments. CNIL-equivalent ICO data handling rules govern device repair record architecture for claims evidence. London brokerage corridor specializes in Fortune 500 standalone coverage unbundled from OEM-captive programs.
China
MIIT equipment certification standards and dual carbon goals condition refurbishment supply chain protocols for claims fulfillment. Shenzhen and Ho Chi Minh City logistics corridors concentrate certified pre-owned component networks. Shanghai fintech clusters develop blockchain-verified device provenance systems for parametric smart contract deployment.
Mobile Phone Insurance Market Competitive Environment
United States underwriters anchor one tier; European diversified insurers hold compliance-driven positioning. The vendor base separates into carrier-captive programs, pan-European diversified underwriters, and independent third-party administrators. Three archetypes dominate: telecom-embedded distributors, OEM-vertical warranty captives, and independent risk-bearing specialists. M&A activity concentrates on MDM platform integration capabilities; geographic expansion targets India PLI scheme partnerships.
Within the pan-European diversified tier, Allianz SE exemplifies compliance infrastructure scale, while AXA Group occupies a comparable cross-border position. Asurion anchors the carrier-embedded archetype through direct Verizon and T-Mobile integrations. These three entities represent distinct competitive positioning vectors: regulatory compliance depth, distribution channel control, and claims fulfillment density.
| Leading Market Players |
|---|
| Allianz SE |
| AXA Group |
| Asurion |
| Chubb |
| AT&T Inc. |
| Assurant, Inc. |
| Apple Inc. |
| AmTrust Financial |
| American International Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
Refurbished OLED panel spot prices in Shenzhen logistics corridors cascade through claims fulfillment economics, compressing indemnity reserves for screen-damage policies while elevating premiums for same-day replacement guarantees in urban India and United States coastal markets.
Pricing Analysis
Expedited component sourcing commands premium multiples over standard fulfillment timelines, with same-day screen replacement policies in Mumbai and Dallas carrying surcharge structures that reflect certified repair network density. Pricing stratifies across premium, standard, and economy tiers based on OEM-authorized part certification and remote diagnostic capability integration. Cost compression in basic coverage segments is intensifying because direct-to-consumer digital channels in Germany and the United Kingdom strip away carrier commission layers. Small business owners exhibit the highest price sensitivity, while Fortune 500 procurement departments prioritize SLA guarantees over premium outlays.
Supply Chain Analysis
Certified pre-owned component networks rest on Shenzhen, Ho Chi Minh City, and Dubai logistics corridors for screen assemblies and logic board refurbishment. Critical inputs include Gorilla Glass Victus substrates, foldable display hinge mechanisms, and eSIM controller chips. Single-source vulnerability concentrates in Shenzhen's specialized refurbishment zones, where MIIT equipment certification standards and customs inspection protocols create settlement delays. Distribution feeds from certified repair depots through telecom provider service centers and third-party administrator field operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile phone insurance has become a vertical-integration race, with carrier-captive programs and OEM warranty captives tightening control over device lifecycle touchpoints from activation through refurbishment.
For Market Incumbents: To counter AppleCare+ and Samsung Care+ distribution lockouts, third-party underwriters must deepen carrier API integrations for real-time claims adjudication and establish captive refurbishment partnerships in India PLI scheme zones. Allianz SE's pan-European compliance infrastructure offers a template for sustaining cross-border coverage advantages as EU AI Act audit requirements harden. For New Entrants and Emerging Players: TRAI-mandated tariff transparency in India opens a window for microinsurance specialists to attach sub-dollar daily coverage to M-Pesa-integrated premium collection models in Kenya and Nigeria. Sub-Saharan Africa's regulatory sandboxes permit parametric weather-damage riders that bypass legacy claims infrastructure. Direct e-commerce enrollment through Flipkart and JD.com storefronts collapses acquisition friction for online retailer channel penetration. For Investors and Strategic Acquirers: Distressed-cycle entries favor MDM platform specialists with enterprise fleet management APIs in the United States and Germany. Long-term viability hinges on algorithmic claims adjudication capabilities that compress settlement cycles from weeks to hours. Watch for FCC equipment authorization rule expansions that mandate certified repair network participation as a coverage condition, signaling consolidation pressure on independent third-party administrators.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Framework Deployment | EU AI Act algorithmic audit requirements favor insurers with transparent damage classification models. |
| PLI Scheme Partnership Formation | Domestic assembly operations in India require localized insurer relationships for factory-to-consumer warranty bridges. |
| Blockchain Provenance Integration | Immutable ownership records in UAE and Singapore eliminate duplicate-claim fraud in high-value handset coverage. |
| MDM Platform Acquisition | Enterprise mobility management API connectivity enables parametric pricing calibrated to corporate refresh cycles. |
| Digital Product Passport API Integration | Ecodesign for Sustainable Products Regulation mandates component-level traceability for claims validation workflows. |
Study Parameters
Independent corroboration across claims executives at third-party administrators, procurement directors at Fortune 500 technology buyers, and regulatory affairs leads at pan-European underwriters underwrites the qualitative findings. Secondary validation draws from FCC equipment authorization filings, TRAI tariff disclosure records, EU Digital Product Passport technical specifications, and SEC 10-K insurance segment disclosures. Bottom-up policy volume estimates triangulate against top-down premium pool calculations derived from carrier-embedded distribution data.
Rate-of-change decomposition across the analysis window segments growth by product type, coverage tier, distribution channel, and customer archetype. CAGRs emerge from fitted trend lines applied to historical claims frequency data and replacement cost algorithms. Modeling incorporates smartphone financing penetration rates, foldable display adoption curves, and right-to-repair regulatory implementation timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for foldable display durability improvements would alter the outlook. Forecasts reflect assumptions regarding EU Green Deal repairability mandate enforcement intensity and OEM software lockout persistence. A small set of triggers—FCC equipment rule expansions, India PLI scheme incentive adjustments, and GDPR repair record retention requirement clarifications—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Africa Insurance Market
Insurance
Digital Transformation in Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Cyber Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
China Group Health Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Gap Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
Crime Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Global Livestock Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market