
 Germany Health and Medical Insurance Market | 2026-2036
Germany Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Health and Medical Insurance Market Foresight
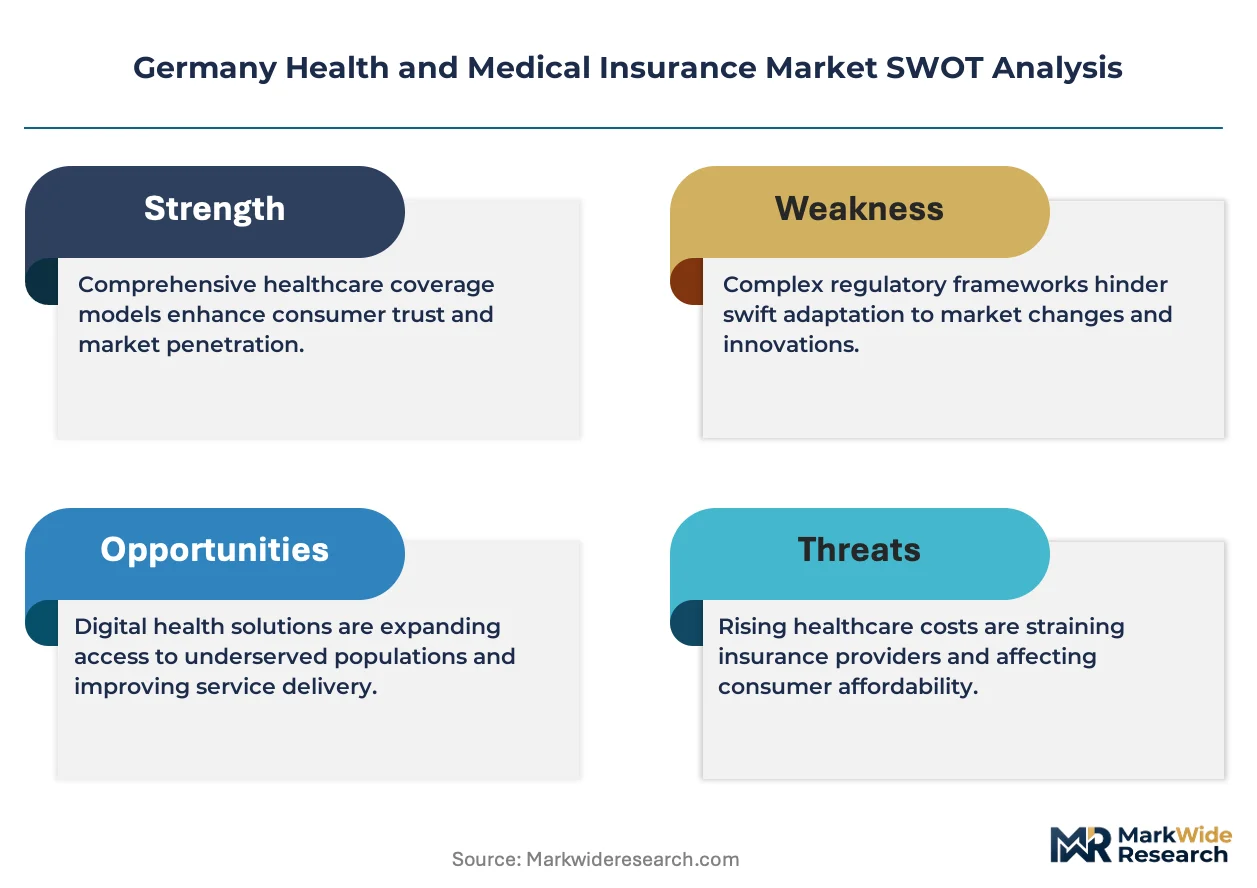
Comprehensive coverage tiers is rotating toward broader outpatient and preventive benefits as statutory insurers face cost pressures. Techniker Krankenkasse leverages its digital health services platform to retain younger enrollees. BARMER anchors its position through dense branch networks in eastern German states. Allianz Private Krankenversicherung differentiates via tailored products for high-income professionals seeking elective care access.
Germany health and medical insurance constitutes risk-pooling financial instruments covering diagnosis, treatment, and rehabilitation costs within a dual public-private framework characterized by income-proportional statutory contributions and risk-rated private premiums. The system operates through standardized benefit catalogs mandated by the Social Code Book V, ensuring minimum coverage depth across acute, chronic, and long-term conditions. Public health insurance dominates enrollment volume due to compulsory membership thresholds, while private health insurance captures higher-margin segments among affluent earners and civil servants. Supplemental insurance is expanding fastest as statutory benefit restrictions on dental and vision care deepen out-of-pocket exposure for mainstream households.
Bundesamt für Justiz enforces insurance contract transparency rules under the German Insurance Supervision Act, while BaFin monitors solvency adequacy across risk-bearing entities. The Hospital Reform introduces activity-based pricing transitions that will reshape insurer-provider negotiations and premium setting. Stakeholders must track how regional hospital consolidation affects network adequacy clauses and subscriber choice rights.
Market Dynamics
The 2023 Hospital Reform (Krankenhausreform) is restructuring insurer-provider reimbursement mechanics, forcing statutory funds to renegotiate activity-based pricing while private carriers recalibrate risk pools around elective care access.
Growth Catalysts
- Aging demographics in North Rhine-Westphalia:Population above 65 years concentrates in urban corridors, expanding chronic disease coverage demand and sustaining premium volume expansion for long-term care riders.
- Social Code Book V benefit standardization:Mandatory minimum coverage depth across acute and chronic conditions reduces consumer switching friction and stabilizes enrollment retention for statutory insurers.
- Digital health platform adoption:Telemedicine infrastructure and app-based claims processing reduce administrative cost ratios while attracting younger enrollees seeking convenience-driven service models.
Market Restraints
- Pharmaceutical input cost volatility:Biologic and specialty drug price inflation compresses statutory fund reserves, forcing supplementary premium adjustments that erode household purchasing power for supplemental coverage.
- East-west provider network asymmetry:Hospital consolidation in eastern German states reduces subscriber choice rights and tightens network adequacy clauses, limiting competitive differentiation among regional carriers.
- BaFin solvency adequacy requirements:Risk-based capital buffers for private health insurers restrict product innovation velocity and delay entry into preventive benefit categories.
Strategic Opportunities
- Bavaria employer density expansion:Manufacturing and technology sector concentration in Munich-Stuttgart corridors creates captive group coverage pools for tailored occupational health products.
- Preventive benefit regulatory tailwind:Federal Ministry of Health pilot programs for digital prevention apps open reimbursement pathways for insurers integrating behavioral health monitoring.
- Out-of-pocket dental-vision convergence:Statutory benefit restrictions deepen household exposure, creating white space for modular supplemental products with tiered activation thresholds.
Industry Challenges
- Legacy IT system integration:Statutory funds face multi-year migration timelines to interface with hospital electronic health record systems, delaying real-time claims adjudication.
- Actuarial talent scarcity:Risk modeling expertise for dual public-private framework products concentrates among retiring specialists, constraining private carrier expansion into hybrid coverage designs.
- Interoperability certification delays:Bundesamt für Justiz transparency rule implementations stall product launch calendars as compliance documentation requirements expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Health and Medical Insurance Market |
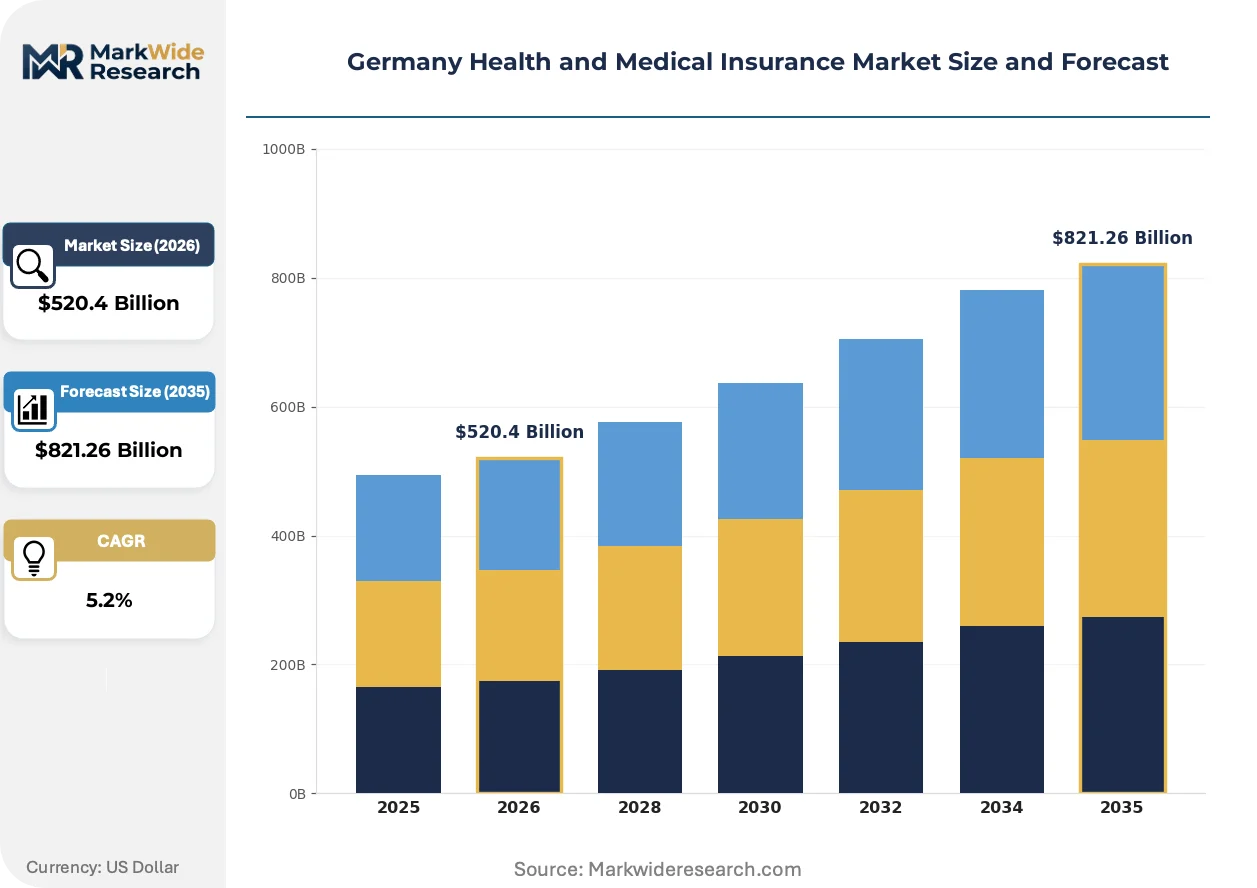
| Market Size in 2026 | $520.4 Billion |
| Market Size in 2035 | $821.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Private Health Insurance, Public Health Insurance, Supplemental Insurance, Dental Insurance, Long-Term Care Insurance Coverage Type: Inpatient, Outpatient, Maternity Care, Prescription Drugs, Preventive Care Customer Type: Individual, Family, Freelancers, Small Business Employees, Senior Citizens Distribution Channel: Brokers, Direct Sales, Online Platforms, Banks, Insurance Agents |
| Companies Covered | Techniker Krankenkasse (TK), AOK – Die Gesundheitskasse, BARMER, DAK-Gesundheit, Debeka Krankenversicherung, Allianz Private Krankenversicherung, DKV Deutsche Krankenversicherung, SIGNAL IDUNA Krankenversicherung, AXA Krankenversicherung, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Health and Medical Insurance Market Shifts & Advancements
Digital infrastructure investments are compressing traditional administrative cost structures while regulatory pressure on hospital pricing transparency accelerates data-sharing requirements across the dual insurance framework.
Artificial intelligence-powered claims triage is decomposing manual processing workflows across statutory funds. Techniker Krankenkasse and BARMER deploy machine learning for fraud detection and pre-authorization screening. This technology is decomposing legacy back-office staffing models and shifting cost structures toward cloud-native platforms.
BaFin's enhanced solvency reporting under the German Insurance Supervision Act tightens capital reserve disclosures for private health carriers. Insurers must now submit granular risk-pool segmentation data quarterly. High-income professional segments face extended underwriting scrutiny as regulators stress-test elective care exposure.
Subscription-based preventive service bundles are displacing traditional fee-for-service supplemental models. Younger enrollees in Berlin and Hamburg favor flat-rate wellness packages covering telemedicine, mental health, and fitness tracking. This behavioral pivot concentrates in metropolitan employer pools where HR departments negotiate group-rated lifestyle benefits.
Germany Health and Medical Insurance Market Segmentation
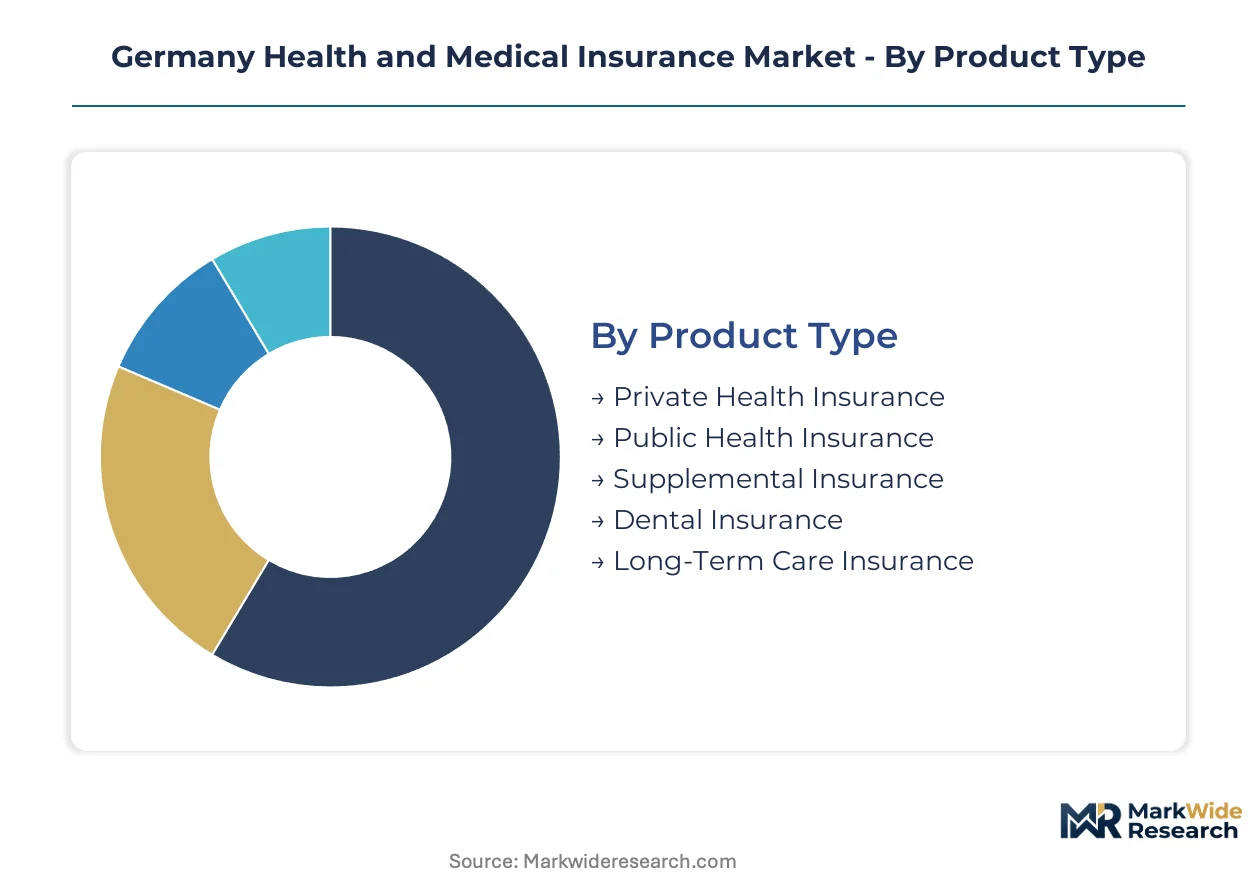
Segmentation in Germany's dual insurance framework exposes where statutory mandates end and voluntary premium opportunities begin. Distinct product architectures, coverage depths, and distribution economics create divergent margin profiles across each dimension.
Product Type:
Margin pools concentrate in elective coverage layers where statutory benefit restrictions force household out-of-pocket spending.
- Private Health Insurance:Risk-rated premiums tied to individual health status and age brackets. High-income professionals in Bavaria and civil servants sustain this segment through demand for single-occupancy hospital rooms and direct specialist access.
- Public Health Insurance:Income-proportional contributions capped at statutory thresholds. North Rhine-Westphalia's aging industrial workforce anchors enrollment volume, though contribution rate pressures compress per-member margins.
- Supplemental Insurance:Modular add-ons covering dental, vision, and alternative medicine gaps. Berlin and Hamburg employers increasingly bundle these as group-rated lifestyle benefits for younger talent retention.
- Dental Insurance:Standalone policies addressing statutory reimbursement ceilings on crowns, implants, and orthodontics. Households in eastern states face deeper exposure due to historical provider network gaps.
- Long-Term Care Insurance:Mandatory since 1995, with private top-up options for care level upgrades. Pflegeversicherung integration with acute coverage creates cross-selling pathways for statutory funds.
The dominant share belongs to Public Health Insurance, while Supplemental Insurance is closing the gap fastest.
Coverage Type:
Revenue concentration tracks the 2023 Hospital Reform's shift toward activity-based pricing and outpatient migration incentives.
- Inpatient:Acute hospital stays including surgery and intensive care. Consolidation in eastern German hospital networks tightens insurer negotiation leverage on per-case rates.
- Outpatient:Physician consultations, diagnostic testing, and day-case procedures. Techniker Krankenkasse's telemedicine platform redirects routine demand from physical clinics.
- Maternity Care:Prenatal through postnatal services including midwife coverage. Employer pools in Munich-Stuttgart corridors drive group-rated family plan attachments.
- Prescription Drugs:Pharmacy reimbursement subject to reference pricing and generic substitution rules. Biologic inflation strains statutory fund reserves.
- Preventive Care:Screenings, vaccinations, and digital health apps. Federal Ministry of Health pilot programs open new reimbursement pathways for behavioral monitoring integration.
Outpatient services command expanding share as inpatient volumes plateau, with Preventive Care expanding most quickly.
Customer Type:
Acquisition economics vary sharply by employment status and household composition.
- Individual:Single-policy holders selecting coverage based on income thresholds and health preferences. Self-employed professionals in Hamburg and Frankfurt drive private insurance uptake.
- Family:Multi-member policies with dependent coverage through primary earner contributions. Statutory family insurance cap rules create switching friction.
- Freelancers:Mandatory self-purchased coverage without employer subsidy. 2023 reform documentation requirements increased administrative burden for this segment.
- Small Business Employees:Group-rated schemes for firms below statutory insurance obligation thresholds. Bavarian manufacturing clusters favor tailored occupational health products.
- Senior Citizens:Age-bracketed premiums with chronic condition prevalence. North Rhine-Westphalia's urban corridors concentrate long-term care rider demand.
Individual policies generate highest per-customer lifetime value, while Freelancers are gaining share fastest.
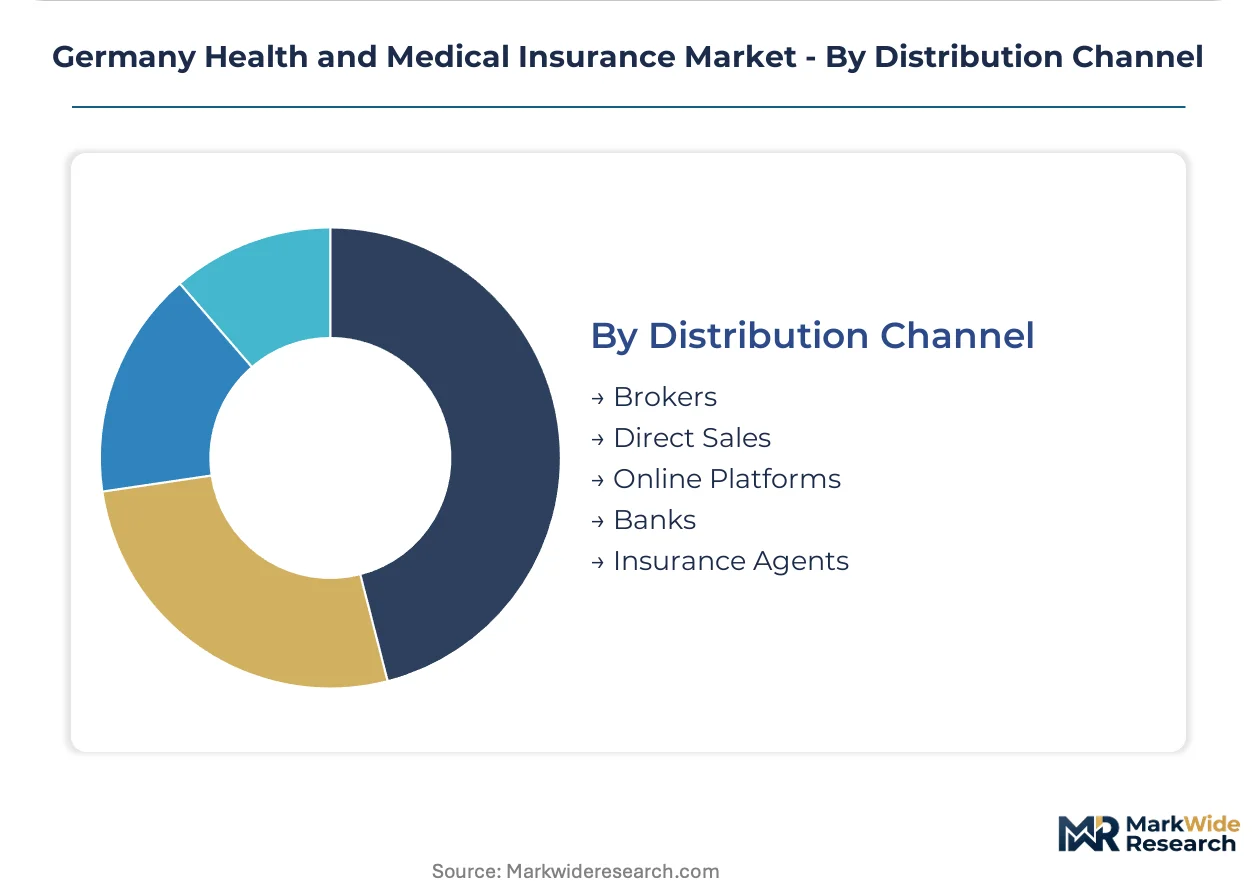
Distribution Channel:
Cost-to-acquire spreads determine profitability across advice-intensive versus self-service pathways.
- Brokers:Independent intermediaries comparing across statutory and private carriers. Complex product comparisons sustain commission structures for high-net-worth segments.
- Direct Sales:Carrier-employed advisors with exclusive product portfolios. BARMER's dense eastern German branch network leverages this model.
- Online Platforms:Digital comparison engines and direct-to-consumer enrollment. Younger enrollees in Berlin favor app-based policy management.
- Banks:Bancassurance partnerships bundling coverage with mortgage and investment products. Allianz Private Krankenversicherung utilizes this for affluent professional targeting.
- Insurance Agents:Tied representatives with single-carrier contracts. Rural penetration relies on this channel where digital literacy gaps persist.
Brokers retain dominant placement volume, though Online Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's health insurance sector generates substantial domestic premium volume with limited cross-border outflow, as statutory membership rules and residency requirements anchor coverage within federal boundaries. The market's internal dynamics reflect pronounced east-west and north-south disparities in provider density, demographic aging velocity, and employer concentration.
North Rhine-Westphalia
Industrial belt demographics concentrate Germany's highest 65-plus population share, expanding chronic disease coverage demand and long-term care rider attachment rates. The state's Hospital Reform implementation tightens activity-based pricing negotiations between statutory funds and consolidated provider networks. Düsseldorf and Cologne anchor employer density that sustains group-rated family plan enrollment.
Bavaria
Munich-Stuttgart manufacturing and technology corridors generate captive occupational health pools with above-median income profiles favoring private insurance uptake. BaFin solvency monitoring applies uniform capital reserve standards across Munich-based carrier headquarters. Nuremberg and Augsburg clusters exhibit fastest supplemental insurance growth among younger household segments.
Baden-Württemberg
Automotive supplier density creates mid-sized employer pools below statutory insurance obligation thresholds, expanding tailored group coverage schemes. The state's digital health infrastructure investments accelerate telemedicine platform adoption among statutory fund enrollees. Stuttgart and Mannheim concentrate broker-mediated private insurance placement for high-income professionals.
Berlin-Brandenburg
Freelancer and self-employed professional concentration exceeds national averages, driving individual policy acquisition outside employer-subsidized channels. Federal Ministry of Health pilot programs for digital prevention apps open reimbursement pathways for insurers integrating behavioral health monitoring. Berlin's platform-native younger enrollees favor app-based policy management over branch network access.
Hamburg
Port and logistics sector employment sustains group-rated schemes with elevated occupational health risk profiles requiring specialized coverage modules. The city's banking and maritime insurance heritage supports bancassurance distribution partnerships bundling health coverage with investment products. Hamburg's dense digital infrastructure enables fastest online platform enrollment growth among northern metropolitan regions.
Germany Health and Medical Insurance Market Competitive Landscape
Concentration sits with statutory funds commanding enrollment volume through compulsory membership thresholds, while private carriers capture premium margin in risk-rated segments. The dual framework produces a tiered structure: dominant public health insurers with standardized benefit catalogs, specialized private carriers with elective care access positioning, and modular supplemental specialists exploiting statutory coverage gaps. Strategic moves center on digital platform investments compressing administrative cost ratios and regional hospital network consolidation tightening insurer-provider negotiation leverage.
Among Germany-based statutory funds, Techniker Krankenkasse exemplifies digital-first service delivery through its telemedicine infrastructure, while BARMER represents branch network density advantages in eastern states. Within private risk-rated tiers, Allianz Private Krankenversicherung occupies a position targeting affluent professionals through bancassurance distribution. These three anchors illustrate divergent competitive archetypes: platform-native efficiency, physical proximity retention, and premium segment specialization.
| Leading Market Players |
|---|
| Techniker Krankenkasse (TK) |
| AOK – Die Gesundheitskasse |
| BARMER |
| DAK-Gesundheit |
| Debeka Krankenversicherung |
| Allianz Private Krankenversicherung |
| DKV Deutsche Krankenversicherung |
| SIGNAL IDUNA Krankenversicherung |
| AXA Krankenversicherung |
| Others |
Supply & Pricing Matrix
Digital claims processing substitution for manual adjudication workflows simultaneously reshapes supply geography toward cloud-native platform providers and compresses pricing economics across statutory fund administrative cost structures. This displacement concentrates vendor procurement power with AWS, Microsoft Azure, and domestic German cloud operators while forcing traditional IT service margins downward through automation-driven efficiency benchmarks.
Pricing Analysis
High-income professionals anchor risk-rated premium structures across private health insurance tiers. Pricing stratifies across elective access, single-occupancy guarantees, and direct specialist consultation tiers, with brand premium and geographic delivery cost as primary differentiation drivers. Cost compression in statutory fund supplementary premiums is intensifying because biologic drug inflation erodes household purchasing power for supplemental coverage. Freelancers and self-employed professionals exhibit highest price sensitivity due to mandatory self-purchased coverage without employer subsidy, while civil servants show least sensitivity given statutory contribution exemptions.
Supply Chain Analysis
Germany and Switzerland anchor core insurance administration infrastructure, with Ireland and Luxembourg hosting secondary data processing centers for EU regulatory compliance. Cloud-native platform dependencies rest on hyperscaler compute capacity, specialized health data interoperability middleware, and legacy mainframe migration services. Single-source vulnerability concentrates in electronic health record system vendors serving hospital network consolidation zones. Distribution runs through statutory fund branch networks, broker intermediaries, and direct digital channels with divergent cost-to-acquire profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hospital Reform's activity-based pricing transition constitutes a structural inflection compressing legacy cost structures while rewarding platform-native operational models. This regulatory disruption creates asymmetric opportunity windows across incumbent defense, entrant positioning, and capital deployment strategies.
For Market Incumbents: Consolidate regional hospital network partnerships in eastern German states where provider consolidation tightens subscriber choice rights and strengthens negotiation leverage on per-case rates. Deepen cloud-native platform integration to compress administrative cost ratios below legacy IT-dependent competitors, using Techniker Krankenkasse's telemedicine infrastructure as the operational benchmark. Counter emerging digital-first statutory funds by accelerating real-time claims adjudication capabilities that reduce member friction in routine service interactions. For New Entrants and Emerging Players: BaFin solvency certification fast-tracks for captive reinsurance structures enable entry into private health insurance risk-pool segments without full capital reserve burdens. Target Berlin-Brandenburg freelancer concentration with modular supplemental products bundling telemedicine, mental health, and dental-vision gaps into subscription-based wellness packages. Deploy direct-to-consumer app enrollment bypassing broker commission structures to capture price-sensitive self-employed professionals outside employer-subsidized channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional statutory funds in eastern German states facing multi-year IT modernization timelines. Five-to-ten year viability hinges on successful legacy system migration to cloud-native platforms enabling real-time hospital EHR integration. Monitor Bundesamt für Justiz interoperability certification delays as the signal indicating which carriers face product launch calendar compression versus regulatory clearance acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Cloud-native claims processing reduces administrative cost ratios while attracting younger enrollees seeking app-based service models. |
| Hospital Network Partnership | Activity-based pricing negotiations with consolidated eastern German providers tighten network adequacy clauses and subscriber retention. |
| Supplemental Product Modularization | Tiered dental-vision bundles address statutory benefit gaps deepening household out-of-pocket exposure in metropolitan employer pools. |
| Preventive Service Subscription | Federal Ministry of Health pilot programs for digital prevention apps open reimbursement pathways for behavioral health monitoring integration. |
| Broker Channel Optimization | Independent intermediary relationships sustain complex product comparison economics for high-net-worth private insurance segments. |
Research Methodology
The analysis maps statutory fund operations, private risk-rated tiers, and supplemental insurance modules, each validated through health insurance fund executives, hospital procurement administrators, broker network heads, and regulatory compliance officers. Primary interview insights combine with Social Code Book V regulatory filings, BaFin solvency disclosure databases, Bundesamt für Justiz transparency rule implementations, and federal health ministry pilot program documentation. Bottom-up enrollment volume modeling and top-down premium revenue aggregation ensure cross-validation across the dual public-private framework.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type architecture, coverage depth tier, customer employment status, and distribution channel cost structure. CAGRs derive from enrollment trend extrapolation, premium rate adjustment schedules, and demographic aging velocity in North Rhine-Westphalia and Bavaria corridors. Hospital Reform implementation timelines and biologic drug price inflation curves feed directly into statutory fund reserve pressure modeling.
Decision-makers should treat outputs as directional under stable regulatory implementation assumptions; material deviation in Hospital Reform negotiation outcomes or BaFin solvency requirement adjustments would warrant model refresh. Specific risk factors include pharmaceutical input cost volatility, east-west provider network asymmetry acceleration, and legacy IT migration timeline slippage. Recalibration cycles align with material shifts in federal health ministry pilot program expansions and regional hospital consolidation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Gap Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
Cannabis Crop Insurance Market
Insurance
Global Home Insurance Market
Insurance
GCC Health Insurance Market
Insurance
EV Insurance Market
Insurance
Crime Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Commercial Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
Global Vehicle Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Umbrella Insurance Market