
 Europe Travel Insurance Market | 2026-2036
Europe Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Travel Insurance Market Intelligence
The gap between premium concierge policies and stripped-down commodity coverage is pivoting wider as insurers chase diverging traveler risk profiles. Allianz leverages its pan-European assistance network to dominate high-touch medical evacuation products. AXA competes through embedded distribution partnerships with major airline and hospitality platforms. Heymondo differentiates via app-native claims processing that reduces friction for digital-native travelers.
Europe travel insurance constitutes a risk-transfer contract underwritten to indemnify policyholders against financial losses arising from trip interruption, medical emergencies abroad, or baggage incidents during cross-border movement within or originating from European countries; policies typically specify per-claim limits, deductible tiers, and territorial scope clauses that define covered geographies and eligible medical providers. Single-trip coverage retains the largest premium pool among policy types due to its attachment to episodic leisure bookings, while annual multi-trip products are expanding fastest as remote workers blend business and leisure mobility. Medical expenses coverage commands the deepest margins within coverage types because of escalating healthcare costs in non-EU destinations and the complexity of repatriation logistics.
EU regulatory frameworks including the Insurance Distribution Directive and EIOPA conduct standards shape product transparency and commission disclosure requirements across member states, while national regulators such as BaFin in Germany and the UK's FCA enforce solvency and consumer protection rules that directly affect policy wording and pricing freedom. EIOPA's ongoing review of travel insurance as a priority sector for conduct risk assessment is tightening claims-handling standards and complaint resolution timelines. Stakeholders must monitor how the EU's proposed expansion of passenger rights legislation intersects with cancellation coverage to avoid overlapping obligations or coverage gaps.
Market Dynamics
The EU's Digital Operational Resilience Act is forcing insurers to rearchitect policy administration systems and claims infrastructure, compressing the gap between legacy carriers and insurtech challengers while elevating compliance costs across the distribution chain.
Growth Catalysts
- Multi-trip policy uptake:Remote workers blending business and leisure mobility across Germany, France, and Spain are accelerating annual coverage adoption beyond traditional single-trip episodic purchases.
- EIOPA conduct standards:Tightened claims-handling timelines and complaint resolution mandates are professionalizing the sector and reducing policyholder churn through improved service quality.
- Medical evacuation complexity:Escalating healthcare costs in non-EU destinations are deepening margins for repatriation coverage, incentivizing product innovation in high-touch assistance services.
Market Restraints
- Commission disclosure requirements:The Insurance Distribution Directive's transparency mandates are compressing distributor margins and forcing price recalibration across comparison platforms.
- Healthcare cost volatility:Unpredictable medical inflation in Turkey and North African destinations is creating underwriting uncertainty and reserve adequacy pressures.
- Regulatory fragmentation:Divergent national implementations of EU directives by BaFin, FCA, and French Prudential Supervision Authority create compliance duplication costs for cross-border distributors.
Strategic Opportunities
- Embedded distribution partnerships:Airlines, hospitality platforms, and booking engines in Spain and Italy present untapped attach-rate potential for point-of-sale coverage integration.
- App-native claims processing:Mobile-first settlement workflows targeting digital-native travelers offer friction reduction that legacy carrier portals cannot match.
- Passenger rights convergence:The EU's proposed expansion of cancellation compensation mandates creates white space for complementary gap coverage products.
Industry Challenges
- Legacy system integration:Incumbent insurers face protracted IT modernization cycles to meet DORA's operational resilience deadlines without disrupting policy servicing.
- Actuarial talent scarcity:Shortages of professionals skilled in cross-border healthcare cost modeling and repatriation logistics are constraining product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Travel Insurance Market |
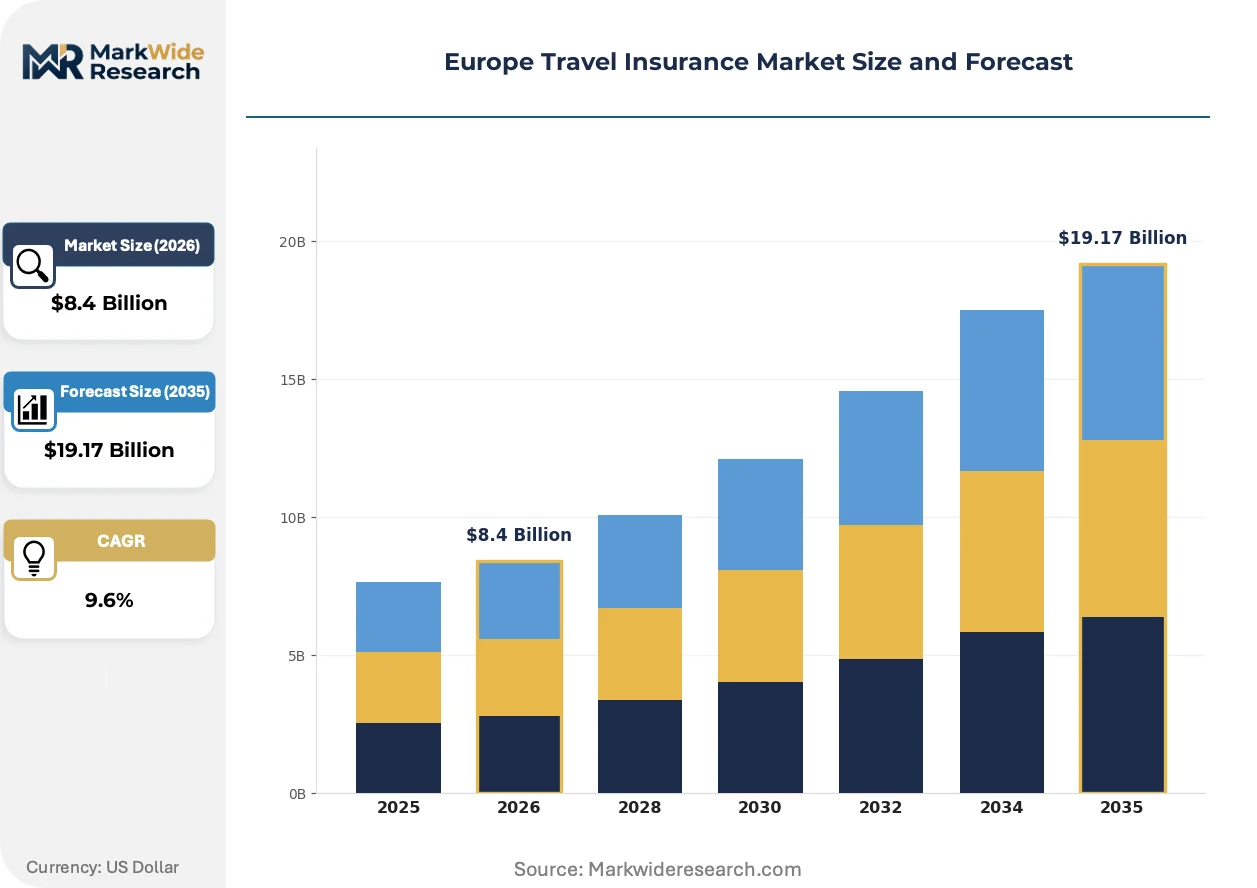
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Single Trip, Multi-Trip, Annual, Backpacker Coverage Type: Medical Expenses, Trip Cancellation, Lost Baggage, Personal Liability Customer Segment: Business Travelers, Leisure Travelers, Students, Families Distribution Channel: Online, Offline, Travel Agents, Insurance Brokers |
| Companies Covered | Trawick International, Travelex Insurance Services, Allianz, IMG, Berkshire Hathaway Travel Protection, AXA, Seven Corners, WorldTrips, Heymondo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Travel Insurance Market Strategic Shifts & Innovations
Digital infrastructure and regulatory pressure are compressing traditional policy lifecycles while fragmenting distribution channels across embedded, direct, and platform models. Carriers must now architect for real-time data exchange and automated decisioning.
Parametric trip interruption coverage is converging with flight-tracking APIs and weather data feeds to enable instant, no-documentation payouts. Low-cost carriers and online travel agencies in Central and Eastern Europe are piloting these products at check-out. This automation is compressing claims cycles from weeks to minutes and eliminating manual adjuster review for standardized events.
The EU's Digital Operational Resilience Act mandates granular operational risk reporting and third-party vendor oversight for insurers. Implementation requires mapping of critical IT service dependencies and stress-testing of business continuity protocols. Mid-sized carriers in Portugal and Greece face disproportionate compliance burdens relative to their technology budgets.
Leisure travelers are unbundling coverage components rather than purchasing comprehensive packages, selecting medical-only or cancellation-only products through comparison aggregators. This granularity is pressuring actuarial cross-subsidies that historically balanced portfolio risk. The shift is most pronounced in Nordic markets where digital literacy and price transparency expectations run highest.
Europe Travel Insurance Market Segmentation
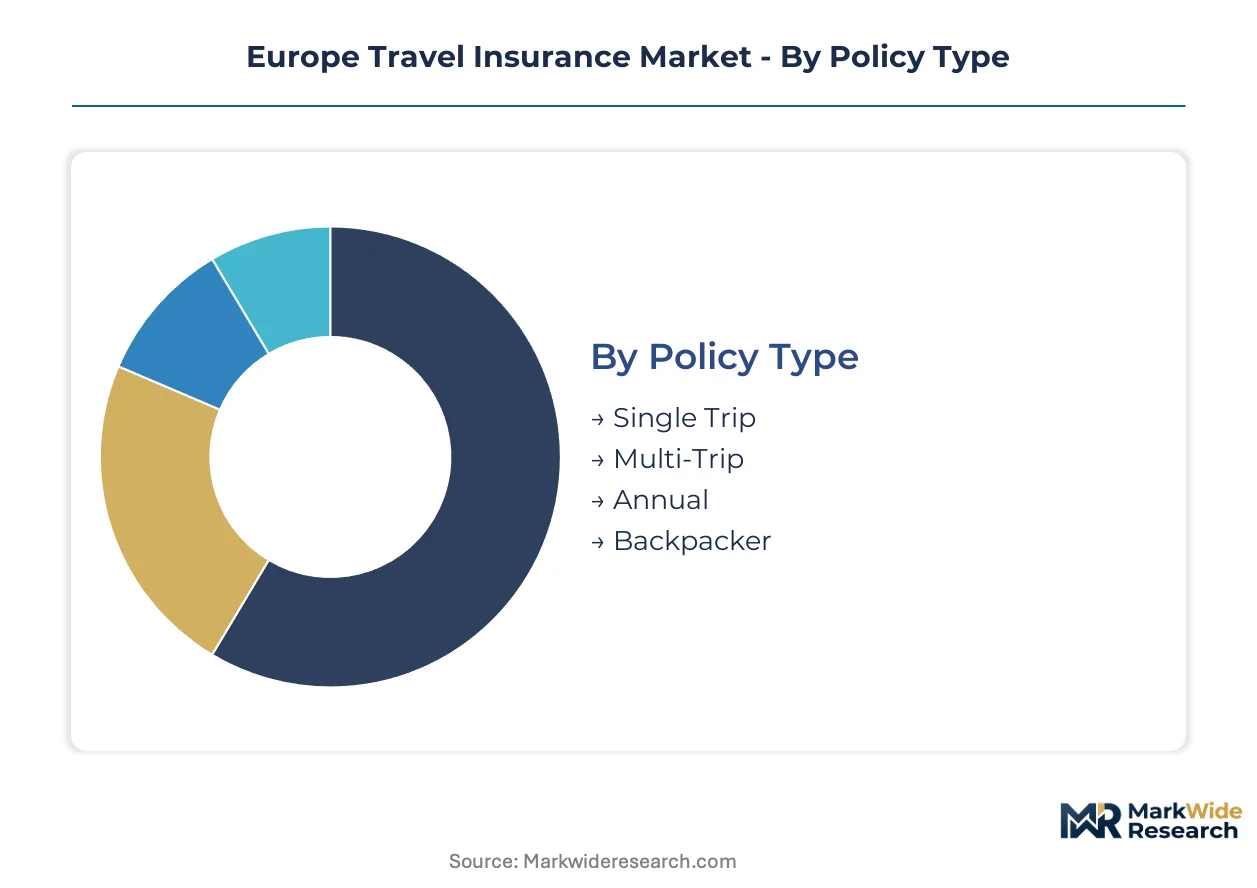
Travel insurance segmentation in Europe reflects divergent risk appetites and booking behaviors across policy structures, coverage scopes, and distribution touchpoints. Insurers must architect products that align with episodic leisure purchases, recurring business mobility, and embedded point-of-sale opportunities.
Policy Type:
Supply concentration in policy administration systems favors carriers with scalable underwriting platforms that can toggle between episodic and recurring coverage without manual intervention.
- Single Trip:Episodic coverage attached to discrete leisure bookings dominates premium volume across Mediterranean package holiday markets. German and French travelers booking summer beach destinations in Spain and Greece drive consistent attachment rates through online travel agencies.
- Multi-Trip:Annual coverage spanning unlimited journeys within a fixed period captures remote workers blending business and leisure mobility across borders. AXA and Allianz compete aggressively for this segment through corporate affinity partnerships and direct digital distribution.
- Annual:Calendar-year policies with territorial scope clauses appeal to frequent cross-border commuters and second-home owners with predictable travel patterns.
- Backpacker:Extended-duration coverage with adventure activity riders targets gap-year travelers and digital nomads on extended European circuits.
Single Trip absorbs the bulk of installed capacity; Multi-Trip is expanding most quickly.
Coverage Type:
Cost tier differentiation separates basic commodity coverage from premium assistance products, with repatriation complexity driving margin stratification.
- Medical Expenses:Coverage for emergency treatment and hospitalization abroad commands the deepest margins due to healthcare cost volatility in non-EU destinations and repatriation logistics complexity. Turkish and North African medical inflation creates underwriting uncertainty that favors carriers with strong assistance networks.
- Trip Cancellation:Protection against prepaid travel investment loss concentrates demand around peak booking windows and regulatory uncertainty. The EU's proposed passenger rights expansion threatens to overlap with private coverage, creating product design challenges.
- Lost Baggage:Coverage for personal effects and delayed luggage has compressed toward commodity pricing as airline liability frameworks mature and tracking technology reduces claim frequency.
- Personal Liability:Protection against third-party injury or property damage claims attracts niche demand from adventure travelers and winter sports enthusiasts in Alpine markets.
Medical Expenses commands the highest margin pool; Trip Cancellation faces the steepest regulatory headwinds.
Customer Segment:
Application-driven segmentation aligns product architecture with trip purpose, duration, and risk tolerance rather than demographic profiling alone.
- Business Travelers:Corporate account coverage with concierge assistance and 24-hour hotline access concentrates in financial services and consulting sectors. German multinational employers drive volume through mandatory travel risk management policies.
- Leisure Travelers:Episodic purchasers booking through comparison aggregators and airline check-out flows represent the largest addressable population. Nordic markets show highest digital literacy and unbundling tendency.
- Students:Exchange program coverage with extended medical and liability protection aligns with university partnerships and visa requirements.
- Families:Multi-generational policies with child-inclusive pricing and cancellation flexibility target school holiday booking patterns.
Leisure Travelers anchor volume generation; Business Travelers sustain margin extraction.
Distribution Channel:
Volume concentration in digital platforms is displacing traditional broker networks, with embedded partnerships at booking touchpoints capturing highest attachment rates.
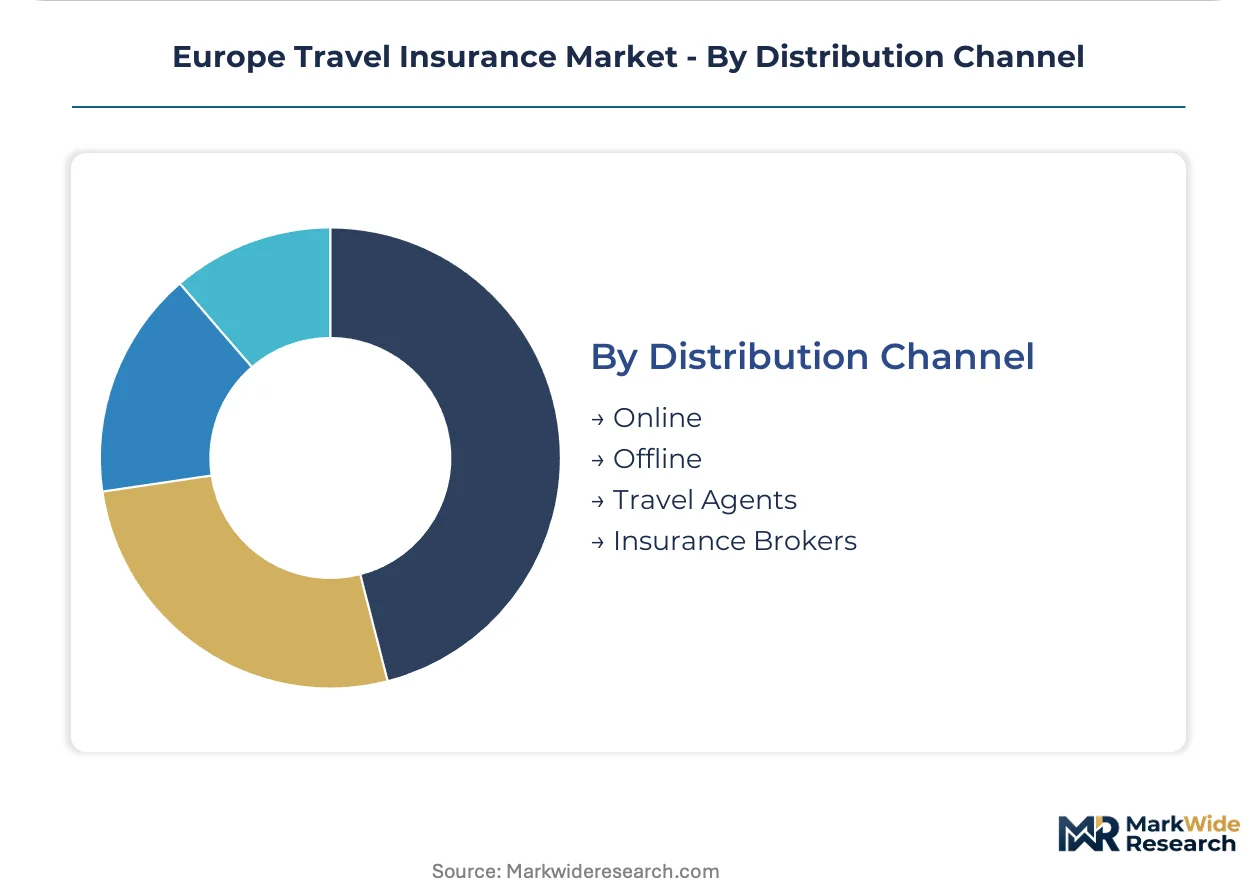
- Online:Direct-to-consumer platforms and comparison aggregators dominate policy origination for price-sensitive segments. Heymondo's app-native claims processing exemplifies friction reduction that legacy portals cannot match.
- Offline:Branch-based distribution retains relevance for complex family policies and high-net-worth segments seeking personalized advice.
- Travel Agents:Point-of-sale attachment at booking completion captures impulse purchases with minimal shopping behavior.
- Insurance Brokers:Independent intermediaries serve corporate accounts and specialty risks requiring tailored coverage design.
Online channels capture the steepest volume trajectory; Travel Agents sustain highest conversion efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European travel insurance underwriting capacity, hosting major carrier headquarters and pan-European assistance networks that service cross-border mobility across the continent.
Germany
Corporate travel risk mandates from multinational employers drive business coverage volume through mandatory policies. BaFin enforces solvency and consumer protection standards that constrain pricing freedom and policy wording. Frankfurt's financial services cluster concentrates corporate account management and affinity partnership structuring.
France
Leisure travelers booking Mediterranean package holidays sustain single-trip premium pools through online travel agency channels. The French Prudential Supervision Authority implements EU Insurance Distribution Directive requirements with strict commission disclosure enforcement. Paris houses embedded distribution partnerships with major airline and hospitality platforms.
Spain
Beach destination bookings from northern European source markets generate consistent attachment rates for episodic coverage products. National travel health mandates tighten product standards and documentation requirements for inbound visitors. Barcelona and Madrid host insurtech challengers piloting parametric trip interruption products with flight-tracking API integration.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for cross-border coverage spanning EU and non-EU destinations. The FCA maintains conduct standards and complaint resolution timelines that shape claims-handling infrastructure. London's Lloyd's market specialty underwriters focus on high-net-worth segments and adventure activity riders.
Italy
Cultural tourism and extended-stay second-home owners drive annual multi-trip policy adoption with territorial scope clauses. National implementations of EIOPA conduct standards professionalize claims processing and reduce policyholder churn. Milan's corporate travel management companies consolidate SME account coverage through digital distribution platforms.
Europe Travel Insurance Market Key Industry Players
Premium-margin players sit above commodity-margin players across assistance network depth and claims automation sophistication. The market structures around three tiers: integrated pan-European carriers with captive assistance infrastructure, digital-native challengers with app-native processing workflows, and niche specialists targeting adventure or extended-duration segments. Strategic moves concentrate on embedded distribution partnerships with booking platforms and parametric product development using real-time data feeds.
Within the integrated carrier tier, Allianz and AXA represent archetypal positions—Allianz through pan-European medical evacuation networks, AXA through hospitality and airline platform embedding. Heymondo occupies the digital-native challenger position, exemplifying friction-reduction through mobile-first claims architecture. These three anchors illustrate the competitive divergence between high-touch assistance depth and automated settlement velocity.
| Leading Market Players |
|---|
| Trawick International |
| Travelex Insurance Services |
| Allianz |
| IMG |
| Berkshire Hathaway Travel Protection |
| AXA |
| Seven Corners |
| WorldTrips |
| Heymondo |
| Others |
Cost & Logistics Intelligence
Repatriation logistics costs cascade through premium tiers as carriers with captive assistance networks in Germany and France command price premiums over distributors sourcing evacuation services from third-party providers. Medical inflation in Turkish and North African destinations feeds directly into actuarial reserve calculations, compressing margins for carriers without vertical control over assistance infrastructure.
Pricing Analysis
Outcome-based pricing anchored to successful medical evacuation completion dominates the premium tier, separating Allianz's pan-European network from commodity distributors. Price differentiation rests on assistance network depth and claims automation sophistication, with digital-native carriers extracting efficiency premiums. Pricing pressure intensifies in the single-trip segment as comparison aggregators compress distributor commissions under Insurance Distribution Directive transparency mandates. Leisure travelers booking through online platforms exhibit highest price sensitivity; corporate accounts with mandatory travel risk policies show lowest.
Supply Chain Analysis
Freight and logistics costs for medical equipment and pharmaceuticals destined to assistance stations concentrate supply chain investment in Germany, France, and Spain. Raw material dependencies include aviation fuel contracts, specialized medical supplies, and multilingual call center labor pools. Single-source vulnerability in air ambulance networks creates concentration risk during peak summer demand periods. Distribution runs through embedded airline partnerships, direct digital platforms, and broker networks serving corporate accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe travel insurance market functions as a cost-of-compliance arena where DORA's operational resilience mandates erect capital barriers that favor established carriers with legacy IT modernization budgets over undercapitalized challengers.
For Market Incumbents: Anticipate margin compression in the single-trip commodity tier as Heymondo's app-native processing workflows attract digital-native travelers away from legacy portals. Prioritize backward integration into captive assistance networks across Mediterranean destinations to defend repatriation margin pools. Accelerate IT modernization cycles to meet DORA's stress-testing deadlines without disrupting policy servicing continuity.
For New Entrants and Emerging Players: Enter via parametric trip interruption products piloted with low-cost carriers in Central and Eastern Europe, where flight-tracking API integration faces lowest incumbent saturation. Target the backpacker and digital nomad segments with extended-duration coverage that traditional carriers price inefficiently. Deploy mobile-first claims architecture as the primary go-to-market wedge against legacy portal friction.
For Investors and Strategic Acquirers: EIOPA's elevation of travel insurance to priority conduct risk assessment status is the leading indicator that regulatory compliance capabilities will determine acquisition premiums across the sector. Frame long-term viability around carriers with demonstrated claims-handling automation and cross-border license portability. Monitor BaFin and FCA enforcement patterns as the signal for which national implementations create compliance moats versus duplication costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Flight-tracking API integration enables instant payouts without documentation friction. |
| Embedded Distribution Partnership | Airline checkout flows capture impulse purchases with minimal shopping behavior. |
| Assistance Network Expansion | Captive medical evacuation infrastructure in Turkey and North Africa defends margin pools. |
| Claims Automation Investment | Mobile-first settlement workflows reduce policyholder churn through service quality. |
| DORA Compliance Modernization | Operational resilience stress-testing meets regulatory deadlines without service disruption. |
Research Approach
Independent corroboration across primary interviews with travel insurance product managers, airline partnership directors, and EIOPA regulatory affairs specialists, combined with secondary validation of BaFin enforcement disclosures, FCA complaint resolution data, and embedded distribution contract filings, underwrites the qualitative findings. Bottom-up policy origination data from online travel agencies triangulates against top-down carrier premium volume disclosures to anchor market sizing.
Rate-of-change decomposition across policy type, coverage scope, distribution channel, and territorial risk clustering structures the analytical framework throughout the projection horizon. CAGRs derive from segmented demand elasticity modeling and medical cost inflation assumptions. Forecast inputs incorporate remote worker mobility patterns and EU passenger rights legislative progression.
Forecast precision tightens around the base case; tail outcomes carry wider variance under healthcare cost volatility in non-EU destinations and divergent national DORA implementation schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Auto Extended Warranty Market
Insurance
France Car Insurance Market
Insurance
Financial Protection Market
Insurance
Property and Casualty Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Europe Car Insurance Market
Insurance
Europe Health Insurance Market
Insurance
Property Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Internet of Things Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Europe Road Assistance Insurance Market