
 Global AI in Auto-Insurance Market | 2026-2036
Global AI in Auto-Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI in Auto-Insurance Market Foresight
Modular policy bundling is broadening buyer choice across the Global AI in Auto-Insurance Market as carriers unbundle traditional comprehensive coverage into discrete, AI-priced micro-products. Progressive Corporation leverages telematics data streams to sustain usage-based pricing leadership, while CCC Information Services Inc. anchors the claims automation segment with computer vision damage assessment. Shift Technology competes on fraud detection specialization, extending its position across European and North American carrier networks.
AI in auto-insurance encompasses algorithmic systems that ingest vehicle sensor data, driver behavior signals, and historical loss records to automate underwriting, claims adjudication, and risk pricing with millisecond-level decision latency. These systems process structured and unstructured data through machine learning pipelines to reduce loss ratios and accelerate settlement cycles. Claims Processing applications dominate current deployment value as carriers automate first-notice-of-loss workflows, while Computer Vision technology captures the fastest expansion as image-based damage estimation replaces physical adjuster inspections. Cloud-Based deployment models concentrate margin pools through API-embedded distribution partnerships with automotive OEMs and mobility platforms.
The EU AI Act classifies certain automated insurance decisions as high-risk systems, mandating human oversight and algorithmic transparency standards that reshape product development requirements for carriers operating across Europe. The National Association of Insurance Commissioners in the United States coordinates state-level guidance on AI governance, while China's SAMR enforces algorithmic recommendation provisions affecting personalized premium calculations. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether to build compliant architectures centrally or maintain region-specific technology stacks.
Market Dynamics
Telematics-enabled usage-based insurance is compressing traditional annual policy cycles into real-time risk pricing, forcing carriers to rebuild actuarial models around streaming vehicle data rather than static demographic proxies.
Growth Catalysts
- Fleet Telematics Mandates:Commercial vehicle operators in Germany and the United States face insurance cost pressures that telematics-based policies directly address. Fleet managers accelerate adoption to capture per-mile premium reductions.
- EU AI Act Compliance Infrastructure:European carriers invest in explainable AI pipelines to meet algorithmic transparency requirements for automated claims decisions. This regulatory pull creates vendor demand for audit-ready machine learning systems.
- Computer Vision Damage Assessment:Image-based estimation technology eliminates physical adjuster dispatch for minor collisions. Property and casualty carriers deploy these systems to compress settlement cycles from weeks to hours.
Market Restraints
- Sensor Data Fragmentation:Vehicle OEMs lock telematics streams behind proprietary APIs, forcing insurers into bilateral data-licensing negotiations with each manufacturer. This concentration raises integration costs and slows policy rollout.
- Cloud Compute Cost Volatility:Real-time risk scoring demands continuous GPU inference, exposing carriers to hyperscaler pricing swings. Mid-tier insurers face margin pressure from unpredictable infrastructure spend.
- Algorithmic Bias Liability:US state regulators under NAIC guidance scrutinize proxy discrimination in AI-driven pricing models. Legal exposure from disparate impact claims constrains deployment velocity for predictive underwriting systems.
Strategic Opportunities
- Embedded Insurance Distribution:Automotive OEMs and mobility platforms integrate micro-policies at point-of-sale. Tesla and Rivian demonstrate captive insurance attach rates above 30 percent in select US states.
- Connected Vehicle Penetration in China:MIIT mandates drive 5G-V2X deployment across domestic passenger fleets. Foreign carriers partnering with domestic platforms gain access to the world's largest telematics data reservoir.
- Fraud Detection Convergence:Natural language processing of repair shop invoices converges with anomaly detection in claims patterns. European networks deploy unified pipelines that cross-reference unstructured text with structured loss histories.
Industry Challenges
- Actuarial Talent Scarcity:Traditional pricing specialists lack fluency in machine learning pipelines. Carriers compete for hybrid data scientists who bridge statistical rigor with production engineering.
- Legacy Core System Integration:Decades-old policy administration platforms resist API-native connectivity. Insurers face multi-year transformation timelines to embed AI decision engines without operational disruption.
- Cross-Border Model Validation:Training data from US driving patterns degrades when deployed in European traffic contexts. Carriers must rebuild or retrain models for each regulatory jurisdiction, fragmenting development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI in Auto-Insurance Market |
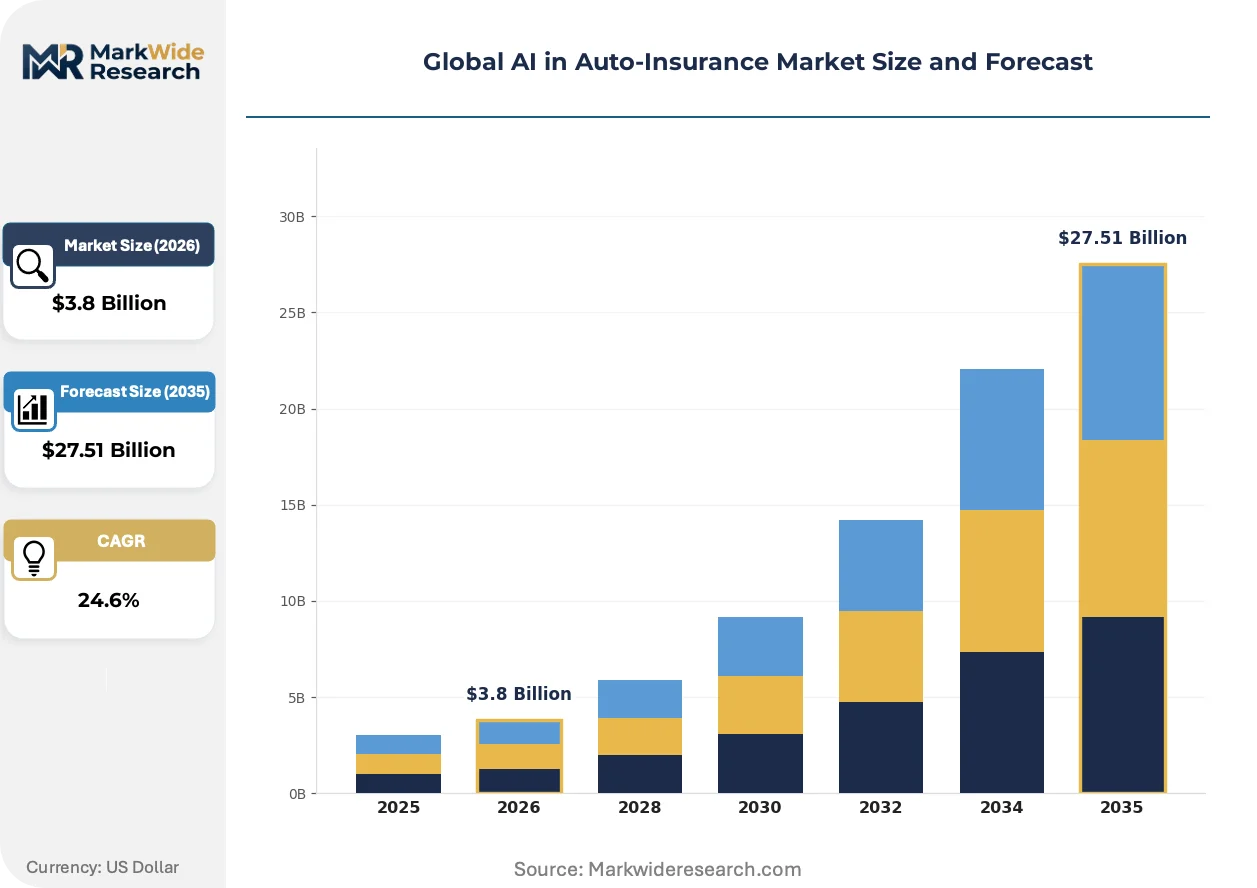
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Claims Processing, Risk Assessment, Customer Profiling, Behavior Analytics, Pricing Optimization Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotic Process Automation, Predictive Analytics, Speech Recognition End User: Insurance Carriers, Claims Adjusters, Underwriting Firms, Risk Management Consultants, Policy Administrators, Actuarial Teams Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing, SaaS, Private Cloud |
| Companies Covered | Progressive Corporation, GEICO, CCC Information Services Inc., Microsoft Corporation, Claim Genius Inc., Nauto Inc., Shift Technology, Liberty Mutual Insurance, Ant Financial Services Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI in Auto-Insurance Market Shifts & Advancements
Algorithmic decision systems are displacing human judgment across the insurance value chain, from risk selection through claims resolution, while regulatory frameworks race to impose accountability guardrails on opaque machine learning models.
Edge computing architectures are converging with in-vehicle inference chips to enable millisecond-level risk scoring without cloud round-trips. Tier-1 automotive suppliers embed neural accelerators into telematics control units. This distributed intelligence is converging with carrier pricing engines to support dynamic premium adjustments triggered by detected driving events.
The EU AI Act establishes conformity assessment requirements for high-risk automated insurance decisions, mandating human oversight interfaces and algorithmic transparency documentation. European carriers restructure product development workflows to embed compliance checkpoints before model deployment. Claims automation vendors serving France, Germany, and Italy face accelerated demand for audit trail functionality.
Fleet procurement teams now specify API-accessible insurance pricing as a standard procurement criterion in RFPs for vehicle leasing contracts. Traditional broker channels lose share to direct platform integrations between fleet operators and algorithmic underwriters. This specification-driven sourcing is most visible in the United States, where large commercial fleets negotiate bundled telematics and insurance contracts with unified data governance terms.
Global AI in Auto-Insurance Market Segmentation
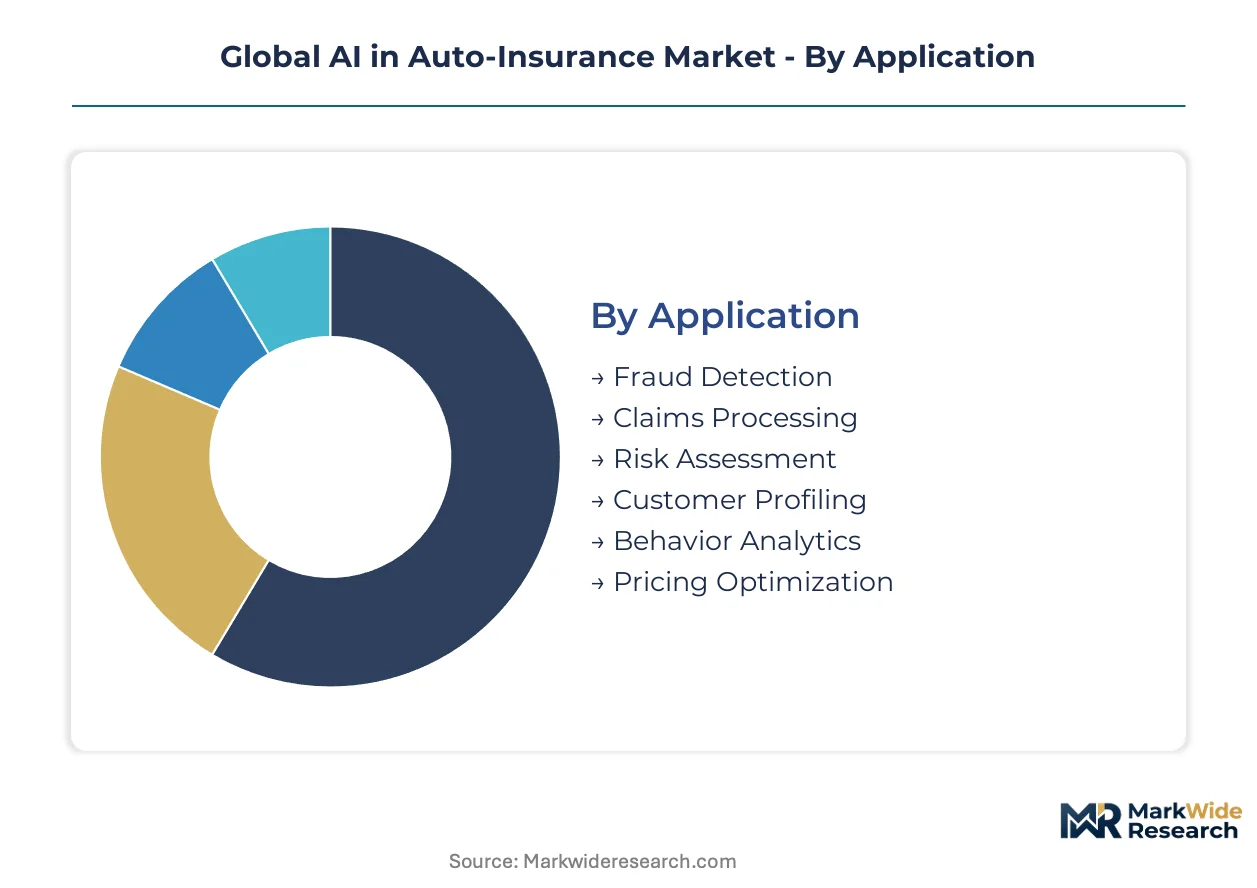
Segmentation reveals how AI value pools concentrate across distinct technical architectures and operational workflows in auto-insurance. Carriers allocate capital differently across these axes based on regulatory exposure, data sovereignty requirements, and legacy system constraints.
Application:
Technology deployment varies sharply by functional domain, with carriers prioritizing automation where loss ratios compress fastest and customer friction creates retention risk.
- Claims Processing:First-notice-of-loss automation ingests unstructured accident reports, damage imagery, and repair estimates through machine learning pipelines. Carriers in Germany and the United States deploy these systems to compress settlement cycles from weeks to hours, directly addressing customer churn drivers.
- Fraud Detection:Anomaly detection algorithms cross-reference historical loss patterns against real-time claim features to flag synthetic accidents and inflated repair invoices. European networks lead deployment as the EU AI Act mandates audit trails for automated suspicion triggers.
- Risk Assessment:Predictive models score driver propensity using telematics streams and behavioral signals rather than static demographic proxies.
- Customer Profiling:Segmentation engines cluster policyholders by lifetime value and cross-sell propensity to optimize retention spend.
- Behavior Analytics:Real-time driving event detection enables dynamic premium adjustments and coaching interventions.
- Pricing Optimization:Reinforcement learning algorithms test thousands of rate combinations against elasticity models to maximize portfolio yield.
Claims Processing leads on scale; Fraud Detection leads on momentum.
Technology:
Capability maturity determines where carriers can automate versus augment human decision-making across the insurance value chain.
- Computer Vision:Convolutional neural networks assess vehicle damage severity from smartphone-captured imagery, eliminating physical adjuster dispatch for minor collisions. Property and casualty carriers in China deploy these systems at scale as MIIT-mandated connected vehicle penetration generates training data reservoirs.
- Machine Learning:Supervised learning pipelines power predictive underwriting and dynamic pricing models using structured historical loss records. Cloud-native carriers leverage these systems to refresh risk scores with sub-hour latency against traditional annual policy cycles.
- Natural Language Processing:Text extraction from police reports and repair invoices accelerates claim documentation workflows.
- Robotic Process Automation:Scripted bots handle repetitive data entry between legacy policy administration systems and modern AI engines.
- Predictive Analytics:Statistical forecasting models project loss reserves and catastrophe exposure for regulatory capital requirements.
- Speech Recognition:Voice interfaces enable hands-free claim reporting and policy inquiries through mobile applications.
Machine Learning dominates current infrastructure spend; Computer Vision exhibits the steepest expansion trajectory.
End User:
Organizational role shapes procurement authority and technical sophistication requirements for AI vendor selection.
- Insurance Carriers:Full-stack carriers deploy end-to-end AI platforms spanning underwriting through claims, with capital budgets reflecting multi-year transformation timelines. Tier-1 operators in the United States maintain dedicated data science organizations exceeding 500 personnel.
- Claims Adjusters:Independent adjusting firms license computer vision tools to compete with carrier-owned automation, preserving relevance in complex liability disputes.
- Underwriting Firms:Managing general agencies algorithmically price specialty commercial auto risks beyond standard carrier appetite.
- Risk Management Consultants:Advisory practices resell AI-enabled fleet safety assessments to corporate clients.
- Policy Administrators:Third-party administrators automate endorsement processing and billing reconciliation.
- Actuarial Teams:Pricing specialists validate machine learning model outputs against regulatory filing requirements.
Insurance Carriers command the largest procurement volumes; Claims Adjusters face the most urgent competitive displacement pressure.
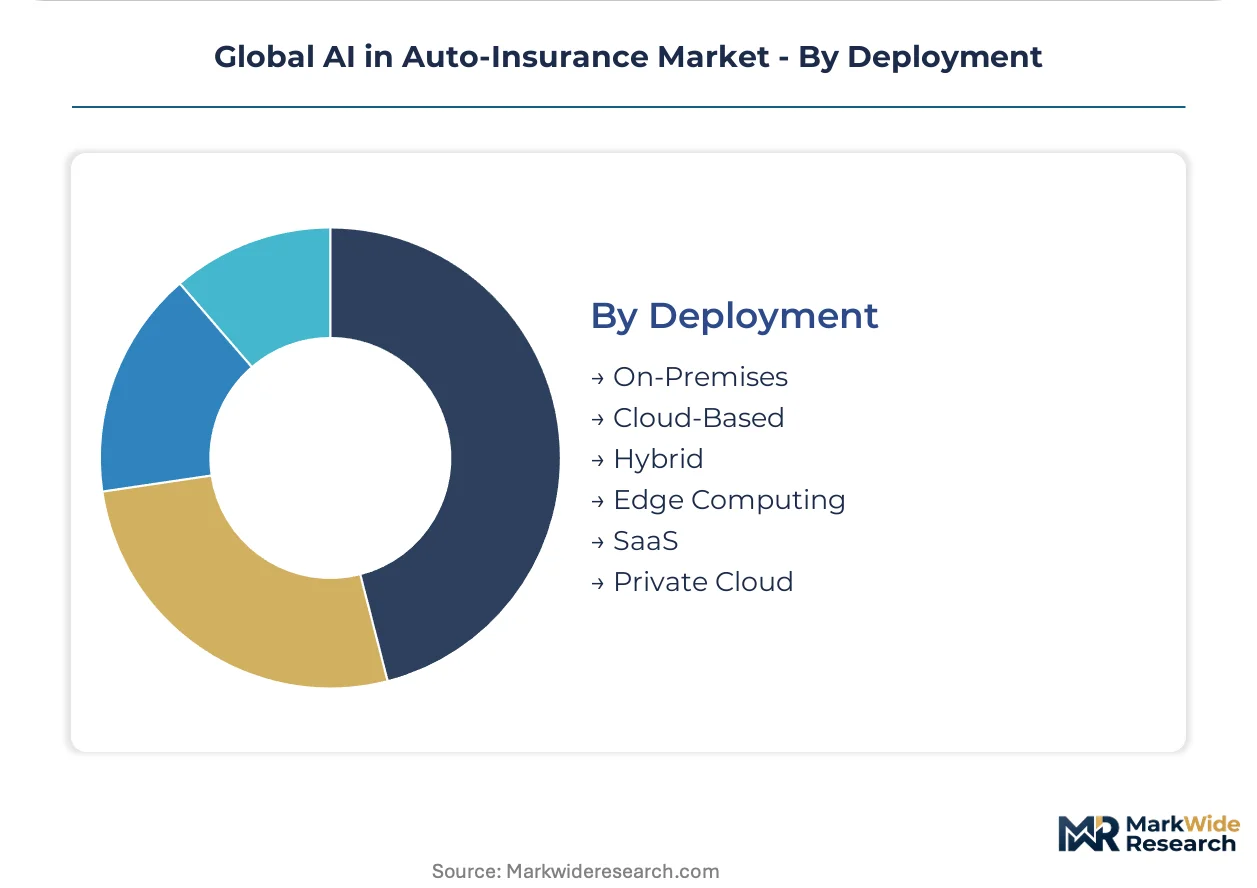
Deployment:
Infrastructure architecture trade-offs reflect data sovereignty mandates, latency requirements, and hyperscaler dependency risk tolerance.
- Cloud-Based:API-embedded distribution partnerships with automotive OEMs and mobility platforms concentrate margin pools through scalable inference infrastructure. Mid-tier insurers face margin pressure from unpredictable GPU pricing swings at hyperscalers.
- Edge Computing:In-vehicle neural accelerators enable millisecond-level risk scoring without cloud round-trips, supporting dynamic premium adjustments triggered by detected driving events. Tier-1 automotive suppliers embed these capabilities into telematics control units.
- On-Premises:Legacy carriers maintain captive data centers for core policy administration systems resistant to cloud migration.
- Hybrid:Split architectures route sensitive customer data through private infrastructure while leveraging public cloud for model training.
- SaaS:Pre-configured AI modules reduce time-to-value for carriers lacking internal data science capabilities.
- Private Cloud:Dedicated tenant environments address EU GDPR and AI Act data localization requirements.
Cloud-Based deployments capture the broadest carrier adoption; Edge Computing is gaining share fastest as connected vehicle penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AI-enabled auto-insurance first scaled in the United States through telematics pioneers, then diffused to Germany and China as connected vehicle mandates and digital infrastructure matured. Regulatory divergence now shapes regional deployment architectures.
United States
Commercial fleet operators in Texas and California drive telematics adoption to capture usage-based premium reductions. The NAIC coordinates state-level AI governance guidance, with California's Department of Insurance enforcing stringent algorithmic transparency rules. Progressive Corporation anchors the usage-based insurance segment from its Cleveland headquarters, processing streaming vehicle data for real-time risk scoring.
Germany
Fleet managers across Bavaria and North Rhine-Westphalia specify API-accessible insurance pricing in vehicle leasing RFPs. The EU AI Act mandates human oversight for automated claims decisions, forcing Munich-based carriers to rebuild explainable AI pipelines. Stuttgart's automotive cluster generates telematics data streams that feed algorithmic underwriting models for commercial vehicle portfolios.
China
MIIT-mandated 5G-V2X deployment across the Yangtze River Delta creates the world's largest connected vehicle data reservoir. SAMR enforces algorithmic recommendation provisions affecting personalized premium calculations. Shanghai-based insurtech platforms partner with foreign carriers to access telematics streams from domestic OEMs.
United Kingdom
London's commercial insurance market experiments with parametric auto policies triggered by telematics events. The Financial Conduct Authority scrutinizes proxy discrimination in AI-driven pricing models. Manchester's emerging insurtech cluster develops fraud detection pipelines that cross-reference unstructured repair invoices with historical loss patterns.
Japan
Tokyo-based non-life insurers deploy computer vision damage assessment to compress settlement cycles for minor collisions. METI guidelines encourage data sharing between automotive OEMs and carriers while preserving consumer privacy. Toyota City's manufacturing ecosystem supplies neural accelerators for edge-computing telematics control units.
Global AI in Auto-Insurance Market Competitive Landscape
The competitive structure tilts toward technology vendors with specialized AI capabilities rather than traditional carriers with balance-sheet scale. Tier-1 automotive suppliers and cloud hyperscalers occupy adjacent positions, creating a three-layer ecosystem of core insurers, AI-native vendors, and infrastructure providers. Strategic moves concentrate on API-embedded distribution partnerships and regulatory compliance infrastructure rather than horizontal consolidation.
Within the specialized AI vendor tier, CCC Information Services Inc. and Shift Technology exemplify contrasting geographic and functional positioning. Progressive Corporation anchors the carrier-owned technology segment, demonstrating captive telematics integration. Microsoft Corporation supplies cloud infrastructure and machine learning platforms that underpin competitor offerings across multiple jurisdictions.
| Leading Market Players |
|---|
| Progressive Corporation |
| GEICO |
| CCC Information Services Inc. |
| Microsoft Corporation |
| Claim Genius Inc. |
| Nauto Inc. |
| Shift Technology |
| Liberty Mutual Insurance |
| Ant Financial Services Group |
| Others |
Supply & Pricing Matrix
Fleet operators and commercial vehicle managers concentrate procurement authority for AI-enabled auto-insurance platforms, driving subscription-tiered SaaS pricing models that scale with connected vehicle counts and data ingestion volumes. This buyer archetype negotiates enterprise contracts with API-embedded pricing structures that bundle telematics hardware, cloud inference credits, and compliance documentation into unified rate cards.
Pricing Analysis
Subscription-tiered SaaS pricing with usage-based overage tiers dominates carrier procurement, separating premium enterprise deployments with dedicated model training environments from standard multi-tenant configurations and economy self-service modules with pre-trained inference endpoints. Price differentiation rests on data sovereignty certification levels—EU AI Act-compliant audit trails command premiums against standard GDPR-aligned deployments—and customization depth for legacy core system integration. Pricing pressure stems from hyperscaler GPU cost volatility compressing margins for mid-tier insurers running continuous inference workloads. Fleet procurement teams exhibit highest price sensitivity, while captive insurance arms of automotive OEMs prioritize integration speed over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from European and North American carriers mandate qualified secondary vendors for critical AI inference infrastructure, forcing procurement teams to maintain active relationships with multiple cloud hyperscalers and edge computing silicon providers. Supply concentrates in the United States for cloud-native model training platforms, Taiwan and South Korea for neural accelerator chips embedded in telematics control units, and Germany for automotive-grade edge computing hardware. The value chain draws from NVIDIA GPU clusters, ARM-based inference accelerators, and proprietary vehicle sensor streams locked behind OEM API gateways. Single-source vulnerability runs through Tier-1 automotive suppliers controlling telematics control unit firmware. Distribution runs through direct platform integrations between carriers and automotive OEMs, bypassing traditional broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global AI in Auto-Insurance Market functions as a stable compounder anchored by regulatory mandates for algorithmic accountability that perpetually refresh vendor demand for compliance-ready infrastructure. Connected vehicle penetration curves and telematics data generation create self-reinforcing growth mechanics across the analysis window.
For Market Incumbents: Deploy explainable AI pipeline investments to neutralize regulatory fragmentation risk across EU AI Act, NAIC state-level guidance, and SAMR algorithmic recommendation provisions. Carriers must consolidate data science talent through targeted acquisition of hybrid actuarial-machine learning teams, while embedding API-native connectivity layers into legacy policy administration systems to defend against cloud-native insurtech displacement. Captive telematics integration with automotive OEMs represents the critical defensive moat. For New Entrants and Emerging Players: API-embedded distribution partnerships with mid-size commercial fleet operators in Germany and the United States offer the most penetrable entry vector, as these buyers specify algorithmic pricing in leasing RFPs but lack internal data science capabilities to build proprietary systems. White-space targets include fraud detection specialization for European carrier networks facing EU AI Act audit trail mandates, and edge computing inference modules for Chinese connected vehicle fleets under MIIT 5G-V2X deployment timelines. Go-to-market positioning should emphasize rapid deployment against legacy core system constraints. For Investors and Strategic Acquirers: Automotive OEMs with captive insurance ambitions represent the most active acquirer category in this space, seeking vertical integration into telematics-enabled risk pricing. The acquisition target archetype centers on specialized AI vendors with regulatory compliance infrastructure—particularly EU AI Act conformity assessment capabilities—and established API distribution partnerships with carrier networks. Long-term viability over the five-to-ten year horizon depends on sustained connected vehicle penetration and regulatory pull for algorithmic accountability. The signal to watch is fleet procurement specification of unified telematics-insurance contracts as standard RFP criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Infrastructure Buildout | EU AI Act mandates reshape product development workflows for automated claims decisions. |
| API-Embedded Distribution Partnership | Tesla and Rivian demonstrate captive insurance attach rates above 30 percent in select US states. |
| Edge Computing Inference Deployment | Tier-1 automotive suppliers embed neural accelerators into telematics control units for millisecond risk scoring. |
| Hybrid Data Science Talent Acquisition | Carriers compete for specialists bridging statistical rigor with production engineering pipelines. |
| Legacy Core System API Integration | Decades-old policy administration platforms resist connectivity without multi-year transformation timelines. |
Research Methodology
Bottom-up fleet operator and commercial vehicle manager modeling reconciled against top-down AI vendor revenue tracking forms the analytical core. Primary interviews with insurance carrier CTOs, fleet procurement directors, regulatory affairs leads at NAIC-coordinated state departments, and AI vendor solution architects combined with secondary validation against SEC 10-K filings, EU AI Act implementation guidance, MIIT 5G-V2X deployment disclosures, and hyperscaler capex segment reporting. Triangulation across these sources anchors market size estimates.
Historical trendline analysis of telematics-enabled policy adoption, claims automation deployment velocity, and regulatory compliance infrastructure investment established baseline growth patterns. The forecast framework models segmentation across application type, technology maturity tier, deployment architecture, and end-user organizational role, with CAGRs derived from elasticity analysis against connected vehicle penetration curves and algorithmic accountability mandate timelines. Edge computing inference cost trajectories and cloud GPU pricing volatility constitute key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for federated learning architectures that reduce cloud dependency would alter the outlook. Forecasts reflect assumptions regarding EU AI Act enforcement intensity, NAIC state-level harmonization progress, and MIIT data localization requirements. Deviation in regulatory implementation timelines or hyperscaler pricing structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific Insurance Aggregators Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
Japan Bancassurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Property Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
UK Dental Insurance Market
Insurance
UK Travel Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
Specialty Insurance Market
Insurance
Business Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Critical Illness Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Asia-Pacific Surety Market