
 Europe Fintech Cloud Market | 2026-2036
Europe Fintech Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fintech Cloud Market Analytics
Modular service unbundling is decoupling core banking functions from monolithic platforms, letting buyers assemble specialized components. Microsoft Azure leverages its sovereign cloud certifications to anchor public-sector fintech workloads across France and Germany. OVHcloud competes on data residency guarantees, while Mambu specializes in composable lending engines that extend core banking flexibility.
Europe fintech cloud denotes the delivery of financial technology infrastructure, software, and data services through distributed computing architectures with sub-100ms latency thresholds and ISO 27001-certified security protocols, enabling real-time transaction processing and regulatory-compliant data sovereignty. Payment processing dominates service-type revenue pools due to perpetual transaction volume expansion, yet compliance solutions command premium pricing as DORA and GDPR mandates intensify audit frequency. Hybrid cloud deployment is growing fastest among investment firms seeking to segregate client portfolio data from analytics workloads.
EMA guidelines on cloud outsourcing, the EU AI Act's risk-classification system for algorithmic credit decisions, and DORA's operational resilience testing standards collectively elevate barrier-to-entry for non-compliant providers. National regulators in Germany and France now mandate incident reporting thresholds that force smaller fintechs toward certified cloud partners. Stakeholders must weigh sovereign-cloud premiums against the operational agility of multi-cloud orchestration as regulatory fragmentation deepens.
Market Dynamics
Modular unbundling of core banking functions is fragmenting technology procurement across European financial institutions, forcing infrastructure buyers to assemble distributed service stacks rather than rely on single-vendor platforms.
Growth Catalysts
- DORA operational resilience testing:The EU Digital Operational Resilience Act mandates third-party risk management for cloud service providers, creating mandatory upgrade cycles across German and French banking infrastructure.
- Neobank transaction volume expansion:Digital-native retail banks in the United Kingdom and Spain are scaling payment processing workloads that exceed legacy on-premise capacity limits.
- Banking-as-a-Service API proliferation:Embedded finance integrations are pulling specialized lending engines and compliance modules into non-banking platforms across Nordic markets.
Market Restraints
- Sovereign cloud premium pricing:Data residency certifications from French and German national cloud providers impose 25-40% cost premiums over standard hyperscale offerings.
- Technical debt in legacy core systems:Cobol-based mainframe architectures at established continental banks resist API-native refactoring without multi-year migration timelines.
- Regulatory fragmentation across member states:Divergent national implementations of EBA cloud outsourcing guidelines create compliance complexity for cross-border service deployment.
Strategic Opportunities
- Underpenetrated Eastern European markets:Polish and Romanian banking sectors show cloud infrastructure penetration gaps of 40-60 percentage points versus Western European benchmarks.
- AI Act algorithmic credit scoring compliance:High-risk system classification requirements are generating demand for explainable AI audit trails and bias-testing infrastructure.
- Edge computing and 5G convergence:Sub-10 millisecond latency requirements for real-time fraud detection are pulling compute resources toward telco edge locations in urban financial centers.
Industry Challenges
- Certified cloud architect scarcity:ISO 27001 and DORA-specific audit competencies remain concentrated among a limited pool of consultants in London, Frankfurt, and Paris.
- Hybrid orchestration complexity:Investment firms operating multi-cloud environments face integration friction between on-premise portfolio data and public analytics workloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fintech Cloud Market |
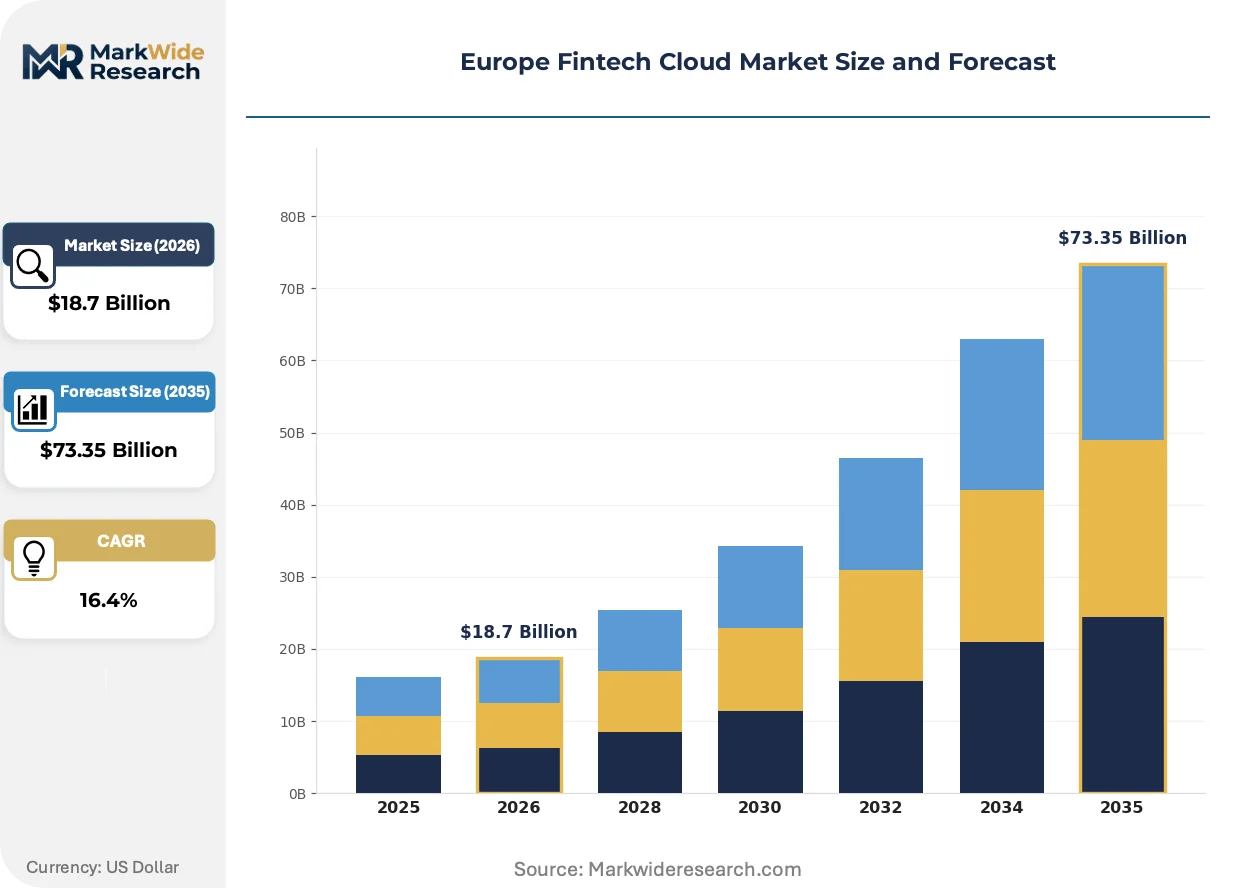
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Risk Management, Compliance Solutions, Wealth Management End User: Banks, Insurance Providers, Investment Firms, Credit Unions Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution: Blockchain Solutions, Digital Wallets, Automated Trading, Fraud Detection |
| Companies Covered | Adyen, OVHcloud, Microsoft Azure, Revolut, IONOS Cloud, Klarna, Mambu, Mollie, Hetzner, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fintech Cloud Market Evolving Landscape
Real-time transaction processing requirements are compressing infrastructure refresh cycles across European financial services, pulling capital toward low-latency distributed architectures and automated compliance tooling.
Composable banking platforms built on containerized microservices are consolidating vendor relationships across tier-two institutions. German regional banks and Dutch cooperative lenders are migrating from monolithic core systems to API-first architectures that permit selective component replacement. This consolidation is compressing implementation timelines from 36-month transformation programs to 12-month modular deployments.
EMA guidelines on cloud outsourcing have hardened audit requirements for algorithmic decision systems used in credit underwriting. The framework mandates documented human oversight mechanisms and stress-testing protocols for machine learning models. French and Italian retail banks are responding by segregating model development environments from production inference infrastructure.
Subscription-based infrastructure procurement is displacing capital-intensive perpetual licensing among asset managers and insurance carriers. Annual recurring payment models for compliance-as-a-service modules are gaining traction in Benelux markets where regulatory update frequency exceeds internal IT capacity. This shift is most visible among mid-size pension funds outsourcing GDPR data lineage tracking to specialized cloud providers.
Europe Fintech Cloud Market Segmentation
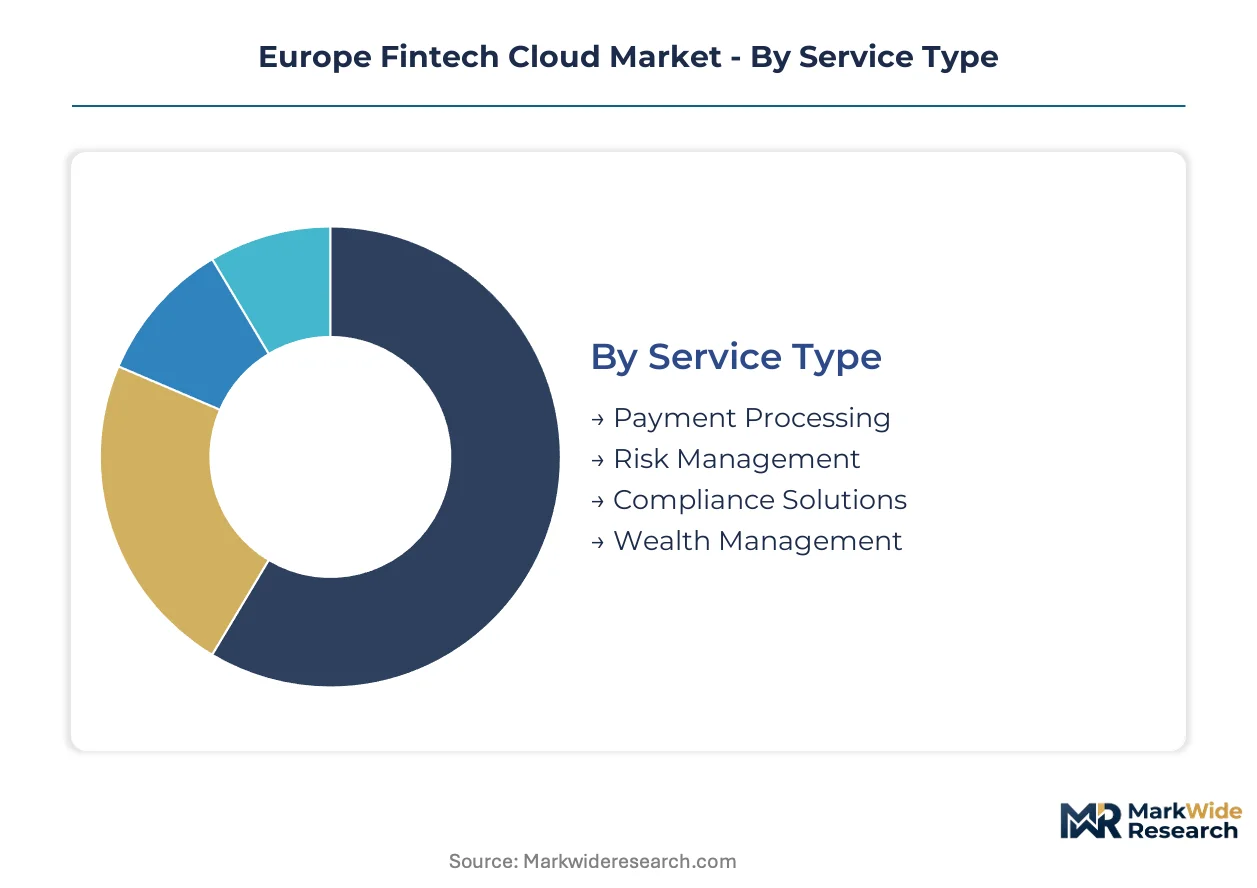
Segmentation in the Europe fintech cloud market reveals how regulatory pressure and workload specialization are fragmenting procurement patterns. Buyers now assemble distributed technology stacks rather than purchasing monolithic platforms, with deployment choices and service types diverging sharply across German, French, and UK financial centers.
Service Type:
Buyers in this category differentiate by transaction volume intensity versus audit frequency requirements.
- Payment Processing:Real-time transaction clearing infrastructure with sub-100ms latency thresholds handles perpetual volume expansion from neobank and embedded finance platforms. UK and Spanish digital-native banks are scaling workloads that exceed legacy on-premise capacity, forcing cloud migration decisions.
- Compliance Solutions:Automated audit trails and regulatory reporting modules command premium pricing as DORA operational resilience testing and GDPR data lineage mandates intensify. French and German national regulators now mandate incident reporting thresholds that push smaller fintechs toward certified cloud partners.
- Risk Management:Credit scoring and portfolio stress-testing platforms with explainable AI capabilities.
- Wealth Management:Robo-advisory and client portfolio analytics for asset managers and private banks.
Payment processing leads volumes today; compliance solutions are gaining share fastest.
End User:
Customer type in this category maps to legacy technical debt versus cloud-native starting position.
- Banks:Tier-one institutions and neobanks split sharply—established German and French lenders battle COBOL mainframe constraints while UK digital challengers scale serverless architectures from inception. Neobank transaction volume expansion is pulling specialized infrastructure investment toward London and Berlin.
- Investment Firms:Asset managers and hedge funds operating hybrid environments to segregate sensitive client portfolio data from public-cloud analytics workloads. EMA guidelines on cloud outsourcing have hardened audit requirements for algorithmic decision systems.
- Insurance Providers:Life and property carriers migrating actuarial modeling to elastic compute.
- Credit Unions:Member-owned cooperative lenders in Benelux and Nordic markets adopting subscription-based compliance modules.
Banks dominate current procurement; investment firms show the steepest expansion trajectory.
Deployment:
Infrastructure choice here hinges on data sovereignty premiums versus multi-cloud agility trade-offs.
- Hybrid Cloud:Segregation architecture splitting sensitive client data on-premise while pushing analytics to public resources. Investment firms across Frankfurt and Paris are adopting this model fastest to satisfy portfolio confidentiality requirements without sacrificing computational scale.
- Public Cloud:Hyperscale resources from providers with sovereign certifications anchoring French and German public-sector fintech workloads.
- Private Cloud:Single-tenant dedicated infrastructure for tier-one banks with strict data residency mandates.
- Multi-Cloud:Orchestrated workloads across competing providers to avoid vendor lock-in and optimize cost.
Hybrid cloud leads deployment volumes today; multi-cloud configurations are climbing the fastest.
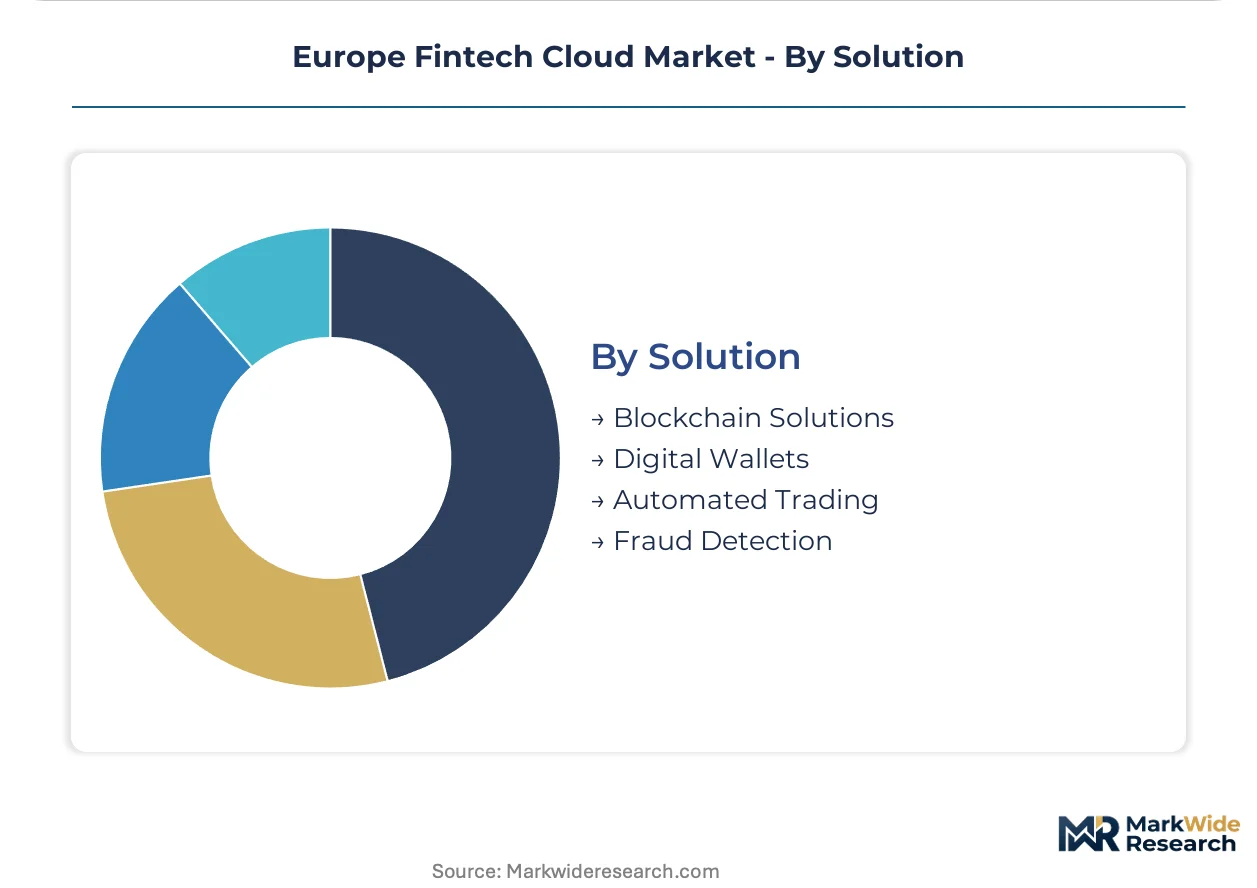
Solution:
Technology maturity and regulatory clarity differentiate buyer priorities in this category.
- Fraud Detection:Real-time transaction monitoring with machine learning pattern recognition and sub-10 millisecond latency requirements. Edge computing convergence with 5G infrastructure is pulling compute resources toward telco locations in urban financial centers like London and Frankfurt.
- Digital Wallets:Embedded payment credentials and tokenized credential management for retail and B2B platforms. Banking-as-a-Service API proliferation across Nordic markets is pulling specialized modules into non-banking platforms.
- Blockchain Solutions:Distributed ledger infrastructure for settlement and trade finance applications.
- Automated Trading:Algorithmic execution platforms with co-located exchange connectivity.
Fraud detection leads solution adoption today; digital wallets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European fintech cloud infrastructure traces its modern lineage to London's post-2008 regulatory sandbox experiments and Frankfurt's subsequent push for euro-denominated payment sovereignty. These twin foundations created divergent national pathways now hardening into distinct compliance architectures.
United Kingdom
Neobank transaction volumes from Revolut and Monzo are straining legacy clearing infrastructure, forcing cloud migration at sub-100ms latency thresholds. The Financial Conduct Authority's operational resilience rules mandate maximum tolerable downtime for critical services. London's Square Mile concentrates embedded finance API development, with Banking-as-a-Service platforms pulling specialized modules into retail and B2B stacks.
Germany
COBOL mainframe constraints at Sparkassen and Volksbanken are driving composable core banking replacements toward API-first architectures. BaFin's DORA implementation mandates third-party risk management with incident reporting thresholds that push smaller fintechs toward certified cloud partners. Frankfurt's financial district anchors sovereign cloud demand, with data residency premiums of 25-40% over standard hyperscale offerings.
France
CNIL-enforced GDPR data lineage requirements are intensifying audit frequency for algorithmic credit decisions under the EU AI Act. ANSM-aligned cloud outsourcing guidelines mandate documented human oversight for machine learning models in production. Paris-La Défense clusters insurance carriers migrating actuarial modeling to elastic compute with segregated development environments.
Netherlands
Subscription-based compliance-as-a-service modules are displacing capital-intensive perpetual licensing among mid-size pension funds. DNB's operational resilience supervision aligns with EBA cloud outsourcing guidelines while permitting multi-cloud orchestration for cost optimization. Amsterdam's Zuidas district concentrates investment firms operating hybrid environments to split sensitive portfolio data from public-cloud analytics.
Spain
Digital-native retail banks are scaling payment processing workloads that exceed on-premise capacity limits established during the cajas consolidation era. Banco de España's fintech licensing framework requires cloud service providers to maintain EU-established entities with local technical support. Barcelona's 22@ district hosts fraud detection specialists leveraging edge computing convergence with 5G infrastructure for sub-10 millisecond latency.
Europe Fintech Cloud Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and sovereign data residency guarantees. The vendor base stratifies into three tiers: hyperscale platforms with public-sector anchoring capabilities, national cloud providers competing on data localization, and specialized composable banking engines. Consolidation pressure concentrates among tier-two institutions seeking modular replacements for monolithic core systems. Dominant competitive moves include strategic partnerships with telcos for edge computing deployment and portfolio diversification into compliance-as-a-service modules.
Within the sovereign-cloud tier, OVHcloud and IONOS Cloud exemplify European providers competing on data residency guarantees against hyperscale alternatives. Microsoft Azure occupies a position anchoring public-sector fintech workloads through certified national cloud deployments. Among composable banking specialists, Mambu represents the API-first architecture approach consolidating vendor relationships across regional banks.
| Leading Market Players |
|---|
| Adyen |
| OVHcloud |
| Microsoft Azure |
| Revolut |
| IONOS Cloud |
| Klarna |
| Mambu |
| Mollie |
| Hetzner |
| Others |
Value Network & Pricing Analysis
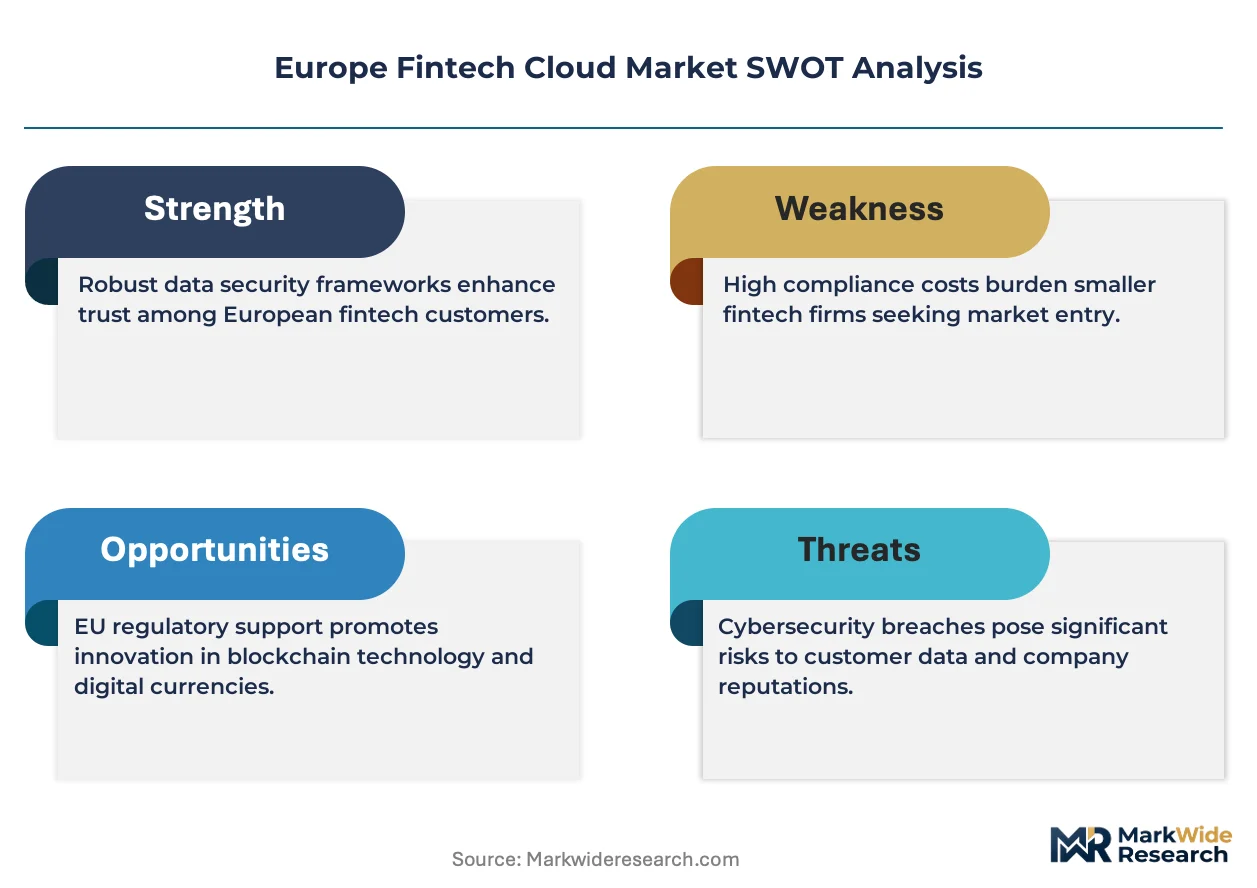
EU AI Act algorithmic auditing mandates gate qualified supply and premium-tier pricing access for fintech cloud providers serving French and German banking clients. Compliance certification costs propagate through subscription pricing, while uncertified competitors face exclusion from public-sector procurement channels.
Pricing Analysis
Subscription-based SaaS tiers with usage-scaled bands dominate procurement across European financial institutions. Pricing stratifies across sovereign-certified premium tiers, standard hyperscale offerings, and economy-grade shared infrastructure based on data residency guarantees and DORA audit depth. Cost compression in standard tiers is intensifying because hyperscale providers are absorbing certification overhead to defend market share. Tier-one banks show least price sensitivity; mid-size credit unions in Benelux markets negotiate hardest on per-seat licensing.
Supply Chain Analysis
Refurbished server hardware flows and certified component recycling programs extend asset lifecycles for sovereign cloud facilities in France and Germany. Compute infrastructure concentrates in Ireland, the Netherlands, and Germany due to favorable energy costs and submarine cable landing points. Supply chains draw from Taiwanese semiconductor foundries, South Korean memory suppliers, and Nordic renewable energy certificates. Single-source vulnerability in AI accelerator chips creates procurement risk for fraud detection workloads. Distribution runs through direct enterprise sales teams with embedded compliance consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe fintech cloud market compounds regulatory complexity into sustained demand for certified infrastructure. DORA operational resilience testing deadlines drive mandatory upgrade cycles across German and French banking infrastructure.
For Market Incumbents: Hedge against hyperscale price erosion by deepening sovereign-cloud certification portfolios beyond minimum compliance thresholds. Defend margin position through embedded compliance-as-a-service modules that lock in annual recurring revenue. Acquire specialist audit trail providers to internalize GDPR data lineage capabilities.
For New Entrants and Emerging Players: Telco edge partnerships offer the fastest channel to sub-10 millisecond latency deployments for real-time fraud detection in Spanish and Italian urban centers. Target Polish and Romanian banking sectors where cloud penetration gaps exceed Western benchmarks by 40-60 percentage points. Lead with API-first composable banking engines that compress implementation timelines versus monolithic replacements.
For Investors and Strategic Acquirers: Roll-up economics work for DORA-certified mid-size compliance specialists because regulatory fragmentation prevents hyperscale standardization. Platform consolidation across tier-two regional banks will accelerate as COBOL migration timelines compress. Watch BaFin and ACPR enforcement patterns for early signals of certification premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BaFin and ACPR mandates anchor premium pricing for EU data residency guarantees. |
| Composable Banking Platform Integration | API-first architectures from Mambu compress German regional bank deployment timelines. |
| Edge Computing Partnership | Telco 5G convergence in Barcelona and Frankfurt enables sub-10ms fraud detection latency. |
| Compliance-as-a-Service Module Launch | Subscription audit trails displace perpetual licensing among Benelux pension funds. |
| Eastern European Geographic Expansion | Polish and Romanian banking sectors show 40-60 point cloud penetration gaps versus Western benchmarks. |
Research Methodology
Multiple input streams — primary interviews with cloud procurement officers, regulatory compliance leads, and core banking transformation directors; secondary validation against EBA outsourcing guidelines, DORA implementation texts, and hyperscaler capex disclosures; plus customs records of server hardware imports — were reconciled through bottom-up and top-down triangulation. Conversations with tier-one bank CTOs, neobank infrastructure heads, and sovereign cloud sales directors supplied qualitative demand calibration. SEC filings from listed providers and EU regulatory impact assessments furnished supply-side constraints.
Data-stream reconciliation across service type, deployment model, end-user category, and national regulatory cluster dimensions generated volume and value outputs over the projection horizon. CAGRs emerged from segment-level growth rate blending with macroeconomic elasticity assumptions. Model inputs included neobank transaction volume trajectories, DORA compliance deadline phasing, and sovereign-cloud certification cost pass-through coefficients.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EBA guideline revisions and AI Act enforcement intensity. Forecasts reflect documented assumptions about regulatory implementation timelines and technology substitution rates. Practitioners should monitor BaFin incident reporting threshold adjustments and CNIL algorithmic audit frequency patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Financial App Market
FinTech
Latin America AI in Fintech Market
FinTech
Financial Consolidation Software Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Financial Technology Fintech Market
FinTech
France AI in Fintech Market
FinTech
AI Finance Market
FinTech
Lendtech Market
FinTech
Decentralized Finance Technology Market
FinTech
Singapore Fintech Market
FinTech
Fintech-As-A-Service Platform Market
FinTech
Fintech Lending Market
FinTech
Saudi Arabia Fintech Market
FinTech
Digital Banking Platform Market
FinTech
Wealthtech Solutions Market
FinTech
Autonomous Finance Market