
 Reinsurance Market | 2026-2036
Reinsurance Market Size, Share, and Industry Trends Forecast 2026-2036
Reinsurance Market Outlook
Specimen-grade catastrophe modeling is rotating reinsurance pricing toward risk-adequate technical rates after years of soft-market erosion. Munich Re leverages proprietary climate risk analytics to sustain underwriting discipline across peak perils. Swiss Re anchors global capacity for natural disaster coverage through its parametric and traditional treaty platforms. Lloyd's competes via its syndicated capital structure, which differentiates risk placement granularity for complex international programs.
Reinsurance is a risk-transfer mechanism where one insurer—the reinsurer—assumes portions of underwritten liabilities from a primary insurer in exchange for premium cessions, governed by attachment points, limits, and loss-sharing formulas. Its commercial purpose lies in stabilizing primary insurer balance sheets against capital-depleting events while enabling portfolio expansion beyond retention limits. Property reinsurance dominates absolute premium volume as climate-exposed primary carriers cede peak natural disaster accumulations, while specialty reinsurance captures the fastest expansion through cyber, terrorism, and pandemic tail risks. Treaty reinsurance structures command the deepest capacity pools, with proportional arrangements concentrating margin in long-tail casualty lines where investment income extends duration-matched returns.
Solvency II in Europe, the Bermuda Monetary Authority's group supervision framework, and state-level NAIC risk-based capital standards in the United States collectively shape reinsurance demand by dictating primary insurer capital relief thresholds and collateral requirements. These frameworks elevate demand for highly rated reinsurance counterparties that qualify for full reserve credit under regulatory accounting. Stakeholders must monitor how evolving climate stress-testing mandates across these jurisdictions reshape attachment point economics and cession strategies.
Market Dynamics
Climate volatility is compressing attachment point economics across property catastrophe lines, forcing primary carriers to restructure cession strategies around parametric triggers and alternative capital vehicles. Solvency II's evolving stress-testing mandates are simultaneously tightening reserve credit eligibility for reinsurance counterparties.
Growth Catalysts
- Regulatory capital relief:Solvency II's risk-based capital framework in Europe elevates demand for highly rated reinsurance that qualifies for full reserve credit under regulatory accounting.
- Climate-exposed accumulation management:Peak natural disaster concentrations in Florida and California are driving treaty coverage expansion across property lines.
- Cyber tail risk emergence:Silent cyber exposures in traditional casualty portfolios are accelerating standalone cyber reinsurance demand from primary carriers.
Market Restraints
- Alternative capital volatility:Catastrophe bond pricing spreads and collateralized reinsurance capacity fluctuate with ILS fund redemption cycles.
- Model risk concentration:Reliance on RMS and AIR catastrophe models creates systemic pricing correlation across the Bermuda and London markets.
- Long-tail reserving uncertainty:Asbestos and environmental liability runoff strains retrocessional capacity for legacy casualty portfolios.
Strategic Opportunities
- India's underpenetrated market:The Insurance Regulatory and Development Authority of India's reinsurance liberalization opens cession flows to foreign specialist carriers.
- Parametric convergence with IoT:Sensor-triggered indemnity structures are merging with traditional treaty platforms for agricultural and supply chain risks.
- EU Green Deal alignment:Climate transition risk carve-outs in commercial property treaties qualify for sustainable finance taxonomy benefits.
Industry Challenges
- Catastrophe modeler talent scarcity:Actuarial and atmospheric science expertise concentrates among a handful of specialist boutiques and vendor platforms.
- Legacy system integration friction:Treaty administration platforms from the 1990s impede real-time data exchange with algorithmic underwriting engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinsurance Market |
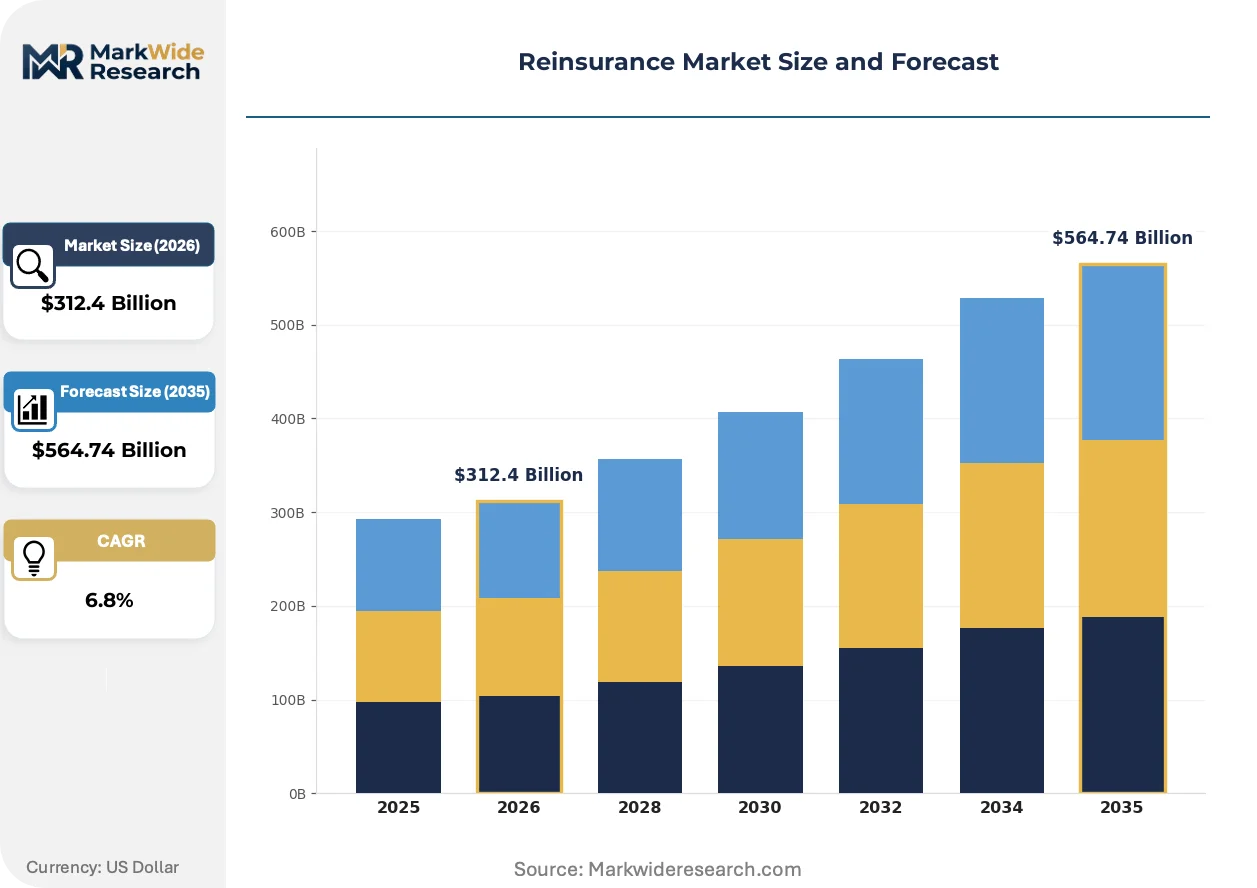
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Property Reinsurance, Casualty Reinsurance, Life Reinsurance, Specialty Reinsurance Offering: Facultative Reinsurance, Treaty Reinsurance, Proportional Reinsurance, Non-Proportional Reinsurance Client Type: Insurance Companies, Corporations, Governments, Mutual Associations Coverage Area: Natural Disasters, Liability Claims, Health Risks, Emerging Markets |
| Companies Covered | Munich Re, Swiss Re, Berkshire Hathaway, Lloyd’s, Reinsurance Group of America, Everest Re, Hannover Re, SCOR, RenaissanceRe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinsurance Market Strategic Shifts
Artificial intelligence is penetrating risk selection and pricing workflows across the reinsurance value chain, compressing cycle times from months to weeks. Three developments are reshaping competitive positioning.
Machine learning-based property risk scoring is displacing traditional surveyor-dependent underwriting for commercial real estate treaties. Primary carriers in the United States are adopting these platforms for mid-market portfolios. The shift is compressing quote turnaround from 45 days to 72 hours while reducing field inspection costs.
The Bermuda Monetary Authority's digital asset custody framework is enabling blockchain-native collateral posting for ILS structures. Tokenized catastrophe bond settlement is reducing counterparty friction in collateralized reinsurance. Bermuda-domiciled special purpose insurers are piloting smart contract triggers for parametric hurricane coverage.
Buyers are unbundling multi-year treaty arrangements in favor of annual renewable structures with embedded rate escalation caps. Primary carriers in Japan and Australia are leading this pivot to preserve capital flexibility. The shift compresses reinsurer visibility into future premium streams while elevating renewal negotiation frequency.
Reinsurance Market Segmentation
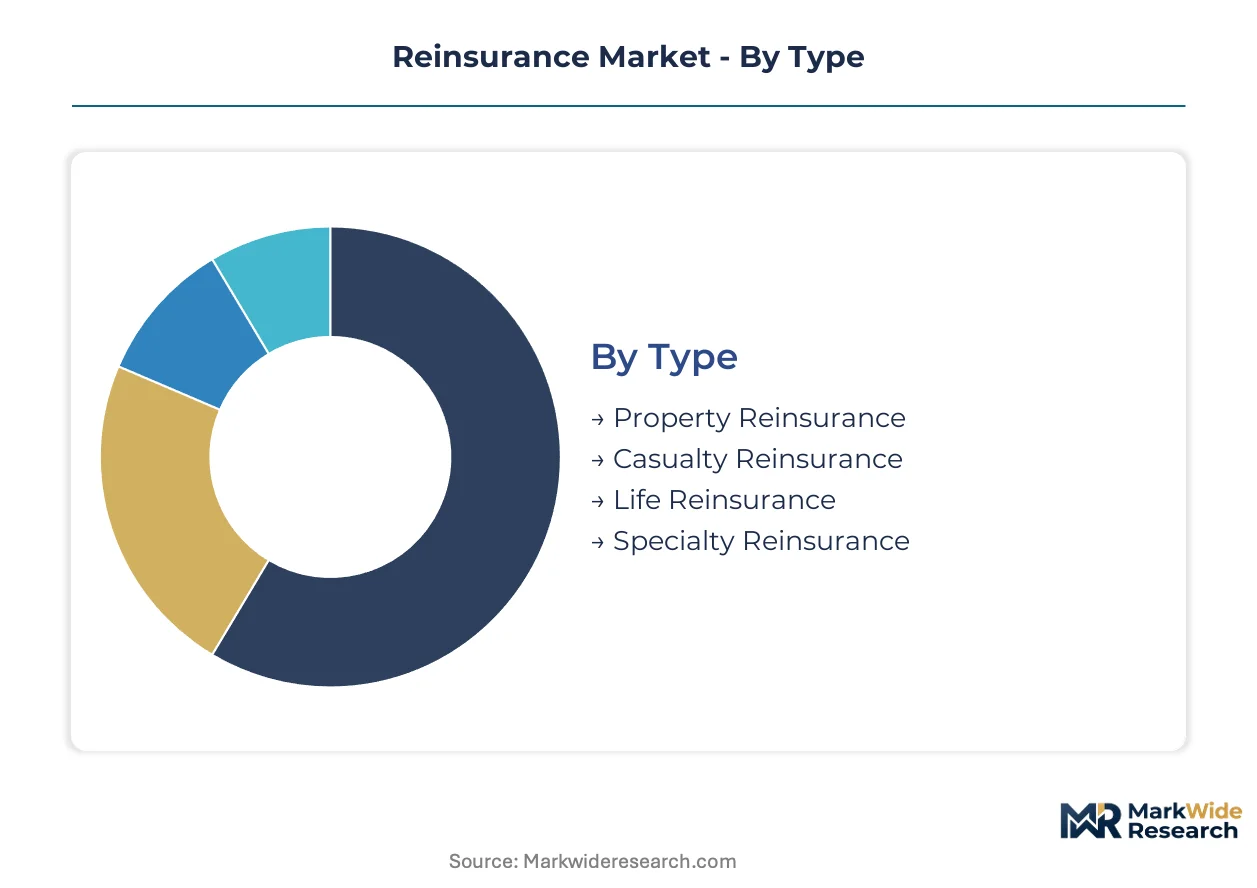
Reinsurance segmentation reflects how risk transfer instruments align with capital relief mandates and accumulation management needs. Treaty structures, client sophistication, and peril geography collectively determine pricing mechanics and counterparty selection across the value chain.
Type:
Property Reinsurance faces the most acute substitution pressure from alternative capital vehicles, as catastrophe bonds and collateralized reinsurance directly compete for peak peril capacity.
- Property Reinsurance:Covers physical damage from natural catastrophes, fire, and engineering perils through proportional and non-proportional treaty structures. Florida and California primary carriers cede peak hurricane and wildfire accumulations to Bermuda-domiciled capacity providers as Solvency II and NAIC risk-based capital standards tighten retention economics.
- Specialty Reinsurance:Encompasses cyber, terrorism, pandemic, and political risk tail exposures that fall outside standard treaty scopes. Lloyd's syndicates and Bermuda specialists are building dedicated cyber catastrophe pools as silent cyber liabilities surface in traditional casualty portfolios.
- Casualty Reinsurance:Addresses long-tail liability exposures including general liability, auto, and workers compensation through quota share and excess of loss arrangements.
- Life Reinsurance:Transfers mortality, longevity, and morbidity risks from primary life insurers through coinsurance and modified coinsurance structures.
Property Reinsurance anchors the volume base while Specialty Reinsurance gains share at the steepest rate.
Offering:
Cost tier differentiation separates bespoke placement labor from automated treaty administration, with proportional structures commanding premium pricing for investment income capture.
- Treaty Reinsurance:Provides automatic coverage for entire portfolios of risks under pre-negotiated terms, eliminating individual risk assessment. European primary carriers leverage treaty structures to secure Solvency II reserve credit through multi-year arrangements with AA-rated counterparties.
- Non-Proportional Reinsurance:Covers losses exceeding specified attachment points, with the reinsurer assuming no proportional premium or liability share. Japanese and Australian carriers are unbundling multi-year treaties for annual renewable structures with embedded rate escalation caps to preserve capital flexibility.
- Facultative Reinsurance:Offers case-by-case coverage for individual risks that fall outside treaty terms or exceed capacity limits.
- Proportional Reinsurance:Cedes a fixed percentage of premiums and liabilities, with the reinsurer participating directly in underwriting results and investment income.
Treaty Reinsurance dominates absolute premium flow while Non-Proportional Reinsurance climbs fastest as climate volatility compresses attachment point economics.
Client Type:
Volume concentration clusters with insurance companies seeking regulatory capital relief, though government demand is accelerating for sovereign catastrophe protection.
- Insurance Companies:Primary carriers ceding risks to optimize risk-based capital ratios and expand underwriting capacity beyond retention limits. German and Swiss insurers utilize reinsurance to manage Solvency II solvency capital requirement volatility.
- Governments:Sovereign entities purchasing parametric coverage for natural disaster fiscal shock absorption. Caribbean Catastrophe Risk Insurance Facility members and Southeast Asian sovereigns are expanding trigger-based pool participation.
- Corporations:Large enterprises accessing captive reinsurance structures or direct placement for uninsurable retained risks.
- Mutual Associations:Member-owned insurers pooling risks through reciprocal reinsurance arrangements.
Insurance Companies retain the dominant placement volume while Government demand expands most quickly through sovereign parametric platforms.
Coverage Area:
Geographic peril distribution shapes capacity allocation, with natural disaster concentration in coastal zones competing against emerging market expansion for finite reinsurer attention.
- Natural Disasters:Hurricane, earthquake, flood, and wildfire coverage absorbing the largest absolute reinsurance capacity. RMS and AIR catastrophe models drive pricing correlation across Bermuda and London market property catastrophe lines.
- Emerging Markets:Underpenetrated regions in India, Southeast Asia, and Africa where regulatory liberalization is opening cession flows. India's Insurance Regulatory and Development Authority reinsurance liberalization permits foreign specialist carriers to access domestic primary cessions.
- Liability Claims:Third-party bodily injury, property damage, and professional liability exposures with extended loss development horizons.
- Health Risks:Medical cost inflation, pandemic mortality, and long-term care liability transfers from health insurers and government payers.
Natural Disasters anchors capacity deployment while Emerging Markets attracts the steepest expansion trajectory through regulatory opening and penetration gap closure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The reinsurance trade flows net toward Bermuda, Switzerland, and Germany as capacity exporters, while the United States, Japan, and India represent the largest net importers of third-party reinsurance protection. Capital relief demand from Solvency II and NAIC regimes drives this directional imbalance.
United States
Florida and California primary carriers cede peak hurricane and wildfire accumulations to offshore capacity providers. NAIC risk-based capital standards tighten retention economics for state-regulated insurers. Bermuda-domiciled reinsurers maintain underwriting offices in Miami and New York to service treaty placements.
Bermuda
The Bermuda Monetary Authority's group supervision framework attracts specialty reinsurance capital seeking collateralized structures. Solvency II equivalence recognition permits European primary carriers to claim full reserve credit for Bermuda-domiciled counterparties. Hamilton and Pembroke host the highest concentration of catastrophe bond issuance infrastructure.
Germany
German insurers utilize reinsurance to manage Solvency II solvency capital requirement volatility across property and casualty portfolios. BaFin supervision maintains strict fit-and-proper standards for reinsurance counterparty eligibility. Munich anchors continental Europe's largest reinsurance buyer concentration.
Switzerland
Swiss primary carriers leverage FINMA's risk-based capital framework to optimize reinsurance cession strategies. Swiss Re and Zurich-based capacity providers supply global natural disaster coverage through parametric and traditional treaty platforms. The Swiss Solvency Test creates regulatory demand for highly rated reinsurance protection.
India
The Insurance Regulatory and Development Authority's reinsurance liberalization permits foreign specialist carriers to access domestic primary cessions. General insurers cede agricultural and motor third-party liabilities under mandatory cession requirements. Mumbai hosts the headquarters of GIC Re and international reinsurer liaison offices.
Reinsurance Market Competitive Environment
Concentration sits with diversified multi-line reinsurers and Bermuda-focused catastrophe specialists. The market structure divides between scale-driven global capacity providers and niche peril underwriters. Two archetypes dominate: integrated reinsurance groups with investment banking capabilities, and mono-line catastrophe underwriters with alternative capital access. Competitive moves center on portfolio diversification into cyber and parametric lines, plus strategic partnerships with insurance-linked securities fund managers.
Within the integrated tier, Munich Re and Swiss Re exemplify scale-driven capacity deployment across peak perils and long-tail casualty. Lloyd's occupies a position as a distributed capital marketplace through its syndicated structure. Among catastrophe specialists, RenaissanceRe represents the alternative capital-integrated model.
| Leading Market Players |
|---|
| Munich Re |
| Swiss Re |
| Berkshire Hathaway |
| Lloyd's |
| Reinsurance Group of America |
| Everest Re |
| Hannover Re |
| SCOR |
| RenaissanceRe |
| Others |
Value Chain & Pricing Dynamics
Multi-year treaty arrangements with embedded rate escalation caps lock in reinsurer capacity access while ceding primary carriers price visibility across renewal cycles. These structures concentrate margin in Bermuda and London market hubs where Solvency II equivalence and NAIC risk-based capital standards elevate counterparty eligibility premiums.
Pricing Analysis
Industrial OEM buyers anchor reinsurance pricing through proportional treaty structures that stratify across AA-rated, single-A, and collateralized tiers. Price differentiation hinges on counterparty credit quality and attachment point granularity, with catastrophe bond spreads compressing traditional property reinsurance layers. Pricing pressure stems from alternative capital inflows via ILS fund redemption volatility, while mid-market primary carriers exhibit acute price sensitivity versus national carriers with captive capacity.
Supply Chain Analysis
Port congestion at Lloyd's underwriting hubs and Bermuda's Hamilton-Pembroke corridor elevates placement friction for international treaty programs. Capacity concentrates in Bermuda, Switzerland, and Germany as net exporters, drawing from actuarial modeling talent pools and collateral infrastructure in the Cayman Islands and Ireland. Single-source vulnerability concentrates in RMS and AIR catastrophe model dependencies, while distribution runs through broker intermediaries in London and direct placement channels for large national carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reinsurance represents a service-attach opportunity where risk analytics subscriptions and parametric trigger administration expand faster than traditional premium cession volumes.
For Market Incumbents: Shield treaty margins by deepening proprietary climate risk model differentiation against commoditized vendor platforms. Invest in Solvency II equivalence maintenance for Bermuda and Swiss domiciles to preserve reserve credit eligibility. Consolidate retrocessional capacity through captive sidecar structures to offset ILS fund redemption cyclicality. For New Entrants and Emerging Players: Anchor in India's liberalized reinsurance market where IRDAI permits foreign specialist access to agricultural and motor third-party cessions. Target cyber catastrophe pools as silent cyber liabilities surface in traditional casualty portfolios. Pursue parametric convergence with IoT sensor networks for agricultural supply chain risks. For Investors and Strategic Acquirers: Algorithmic underwriting boutiques with machine learning-based property risk scoring capabilities command scarcity premiums as quote cycles compress from months to weeks. Long-term viability across the analysis window hinges on climate model talent concentration and alternative capital integration depth. Monitor catastrophe bond issuance spreads as an inflection indicator for traditional reinsurance pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Cyber Catastrophe Pool Formation | Lloyd's syndicates and Bermuda specialists address silent cyber exposure accumulation in casualty portfolios. |
| Parametric Trigger Platform Development | Smart contract-enabled hurricane coverage reduces settlement friction for Caribbean sovereign protection. |
| Alternative Capital Sidecar Launch | Collateralized structures from ILS fund managers expand peak peril capacity beyond traditional balance sheets. |
| Climate Risk Analytics Licensing | Proprietary model subscriptions generate recurring revenue from primary carrier underwriting workflows. |
| Multi-Year Treaty Unbundling | Annual renewable structures with rate escalation caps preserve primary carrier capital flexibility. |
Study Parameters
The analysis maps treaty reinsurance, facultative placement, and alternative capital segments, each validated through chief underwriting officers, catastrophe modelers, and broker placement executives. Primary interviews with Solvency II compliance officers and NAIC state regulators combined with secondary validation from Bermuda Monetary Authority filings, Lloyd's syndicate returns, and catastrophe bond issuance databases. Bottom-up treaty premium aggregation and top-down macroeconomic stress-testing provided cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by risk transfer instrument, counterparty credit tier, peril geography, and regulatory capital relief eligibility. CAGRs derived from historical cession rate analysis and forward-looking primary carrier retention economics, incorporating climate volatility stress parameters and ILS market capacity forecasts.
Material uncertainties — model risk concentration, regulatory equivalence revocation, and alternative capital redemption cycles — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Solvency II maintenance and NAIC risk-based capital continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Global Sports Insurance Market
Insurance
Umbrella Insurance Market
Insurance
US Extended Warranty Market
Insurance
Crime Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Global Vehicle Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Embedded Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Digital Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Auto Compulsory Insurance Market