
 Banking Wearable Devices Market | 2026-2036
Banking Wearable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Wearable Devices Market Insights
Unbundling of payment credentials from smartphone-locked wallets is decoupling banking access from handset dependency. Apple Inc. leverages its secure element architecture to anchor premium contactless payment experiences across watchOS devices. Samsung Electronics Co., Ltd. competes through Knox security layers that sustain enterprise-grade transaction integrity in corporate deployments. Xiaomi Corporation specializes in cost-optimized NFC modules that dominate mass-market payment band configurations in Asia.
Banking wearable devices integrate tokenized payment credentials, biometric sensors, and wireless communication protocols into body-worn hardware engineered for financial transaction authentication and account management. These systems employ EMV-compliant secure elements, capacitive fingerprint scanners, and Bluetooth Low Energy radios to execute contactless payments while transmitting encrypted financial alerts to the wearer. Smartwatches occupy the largest value pool due to their multifunctional utility and established consumer familiarity, while smart rings represent the fastest-growing configuration as miniaturized NFC antennas achieve reliable transaction range. Payment bands sustain meaningful volume in developing markets where dedicated single-function hardware outperforms premium smartwatch price points.
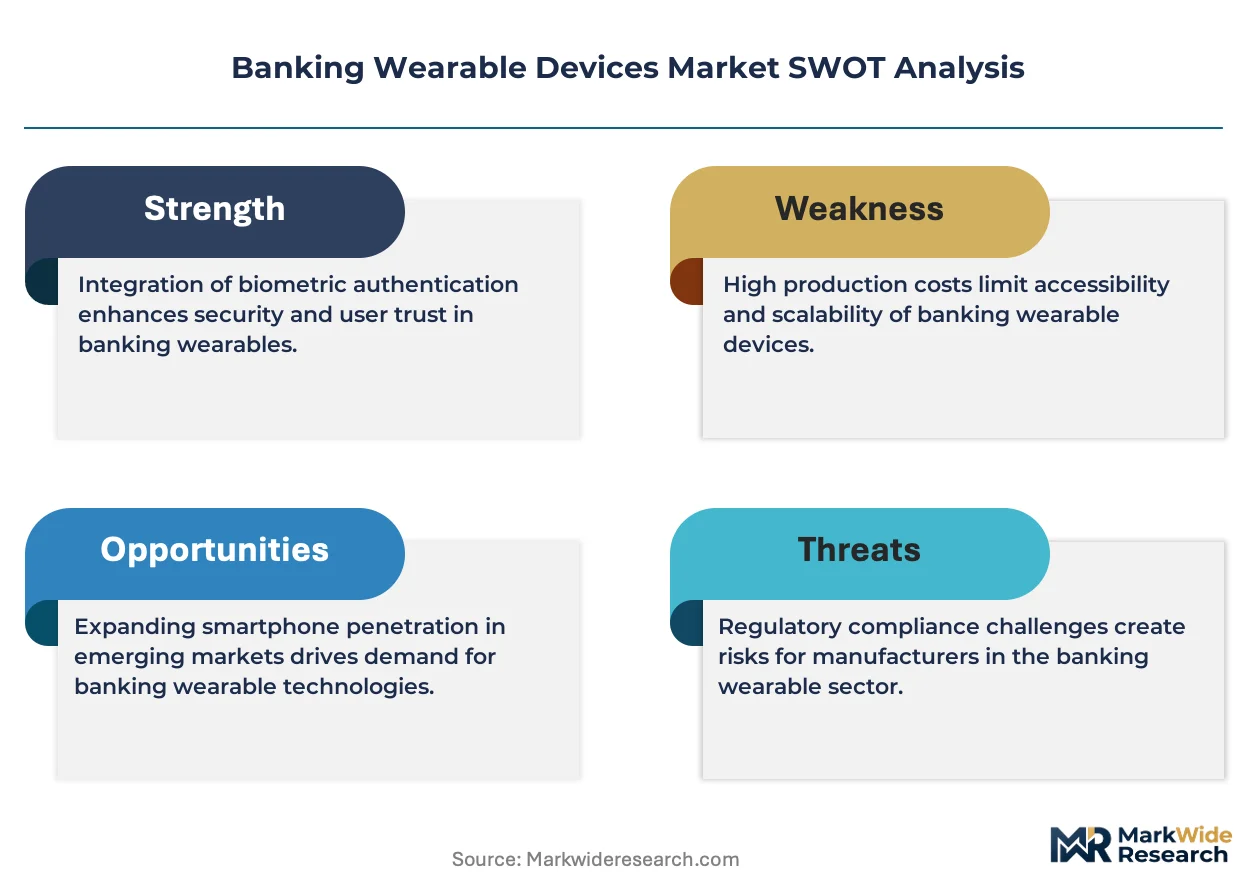
FCC certification requirements govern radio frequency emissions for wearable payment hardware sold in the United States, while PCI DSS compliance mandates constrain how device manufacturers architect token vaults and cryptographic key storage. The EU AI Act introduces algorithmic transparency obligations for fraud detection models embedded in wearable banking applications. Stakeholders must monitor evolving biometric data governance frameworks as regulators in multiple jurisdictions sharpen consent requirements for fingerprint and heart-rate pattern recognition used in authentication workflows.
Market Dynamics
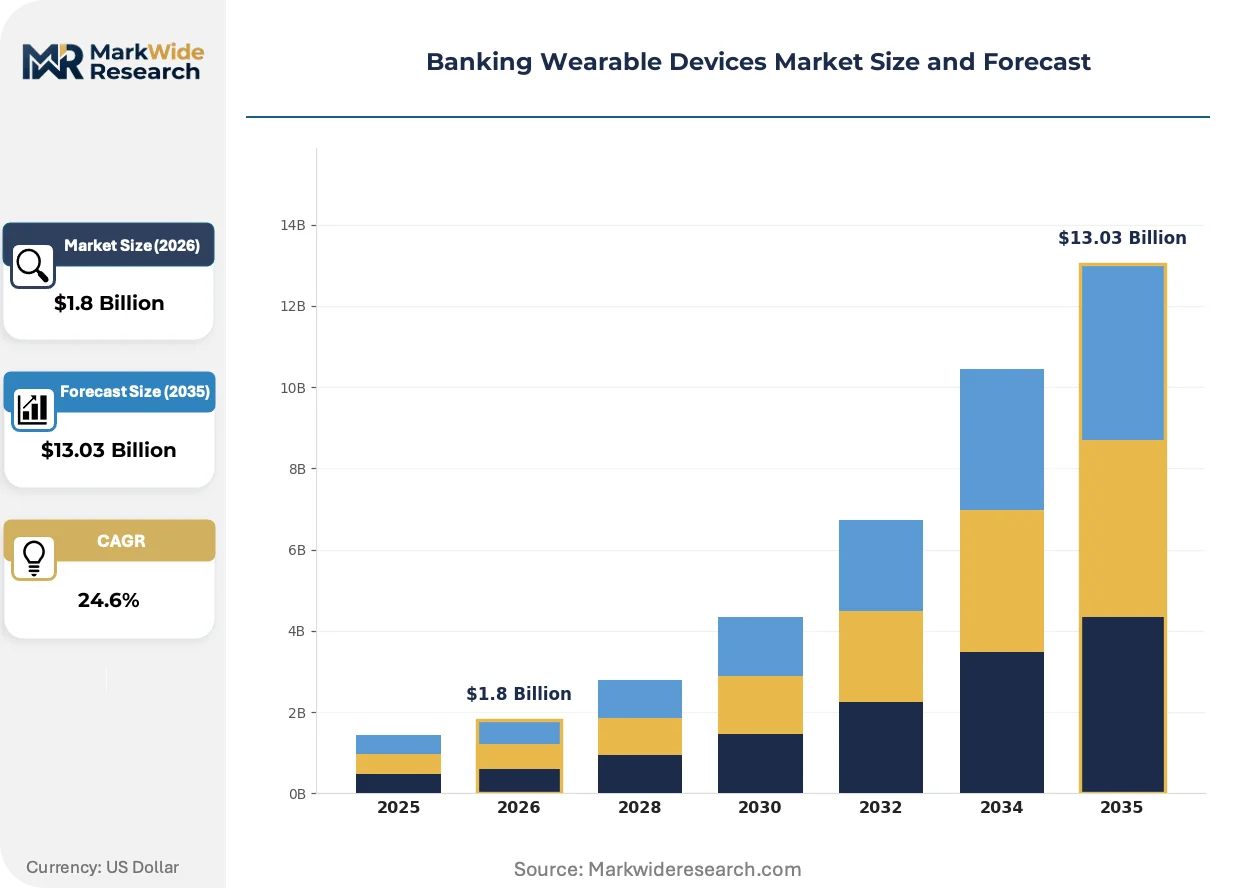
Tokenization protocols are decoupling payment credentials from smartphone hardware, enabling wrist-worn and finger-worn form factors to execute EMV-compliant transactions independently of handset tethering. This structural shift compresses authentication latency while expanding addressable user bases beyond premium smartphone owners.
Growth Catalysts
- EU AI Act compliance:Algorithmic transparency mandates for fraud detection models are accelerating hardware-embedded biometric verification adoption across European banking wearables.
- Capacitive fingerprint miniaturization:Sensor module cost curves below three dollars are unlocking mass-market payment band configurations in price-sensitive Asian markets.
- Retail banking customer migration:Contactless credential portability from smartphones to wearables is driving fastest-expanding end-user cohort demand in Germany and the United States.
Market Restraints
- Secure element supply concentration:Foundry capacity for EMV-certified hardware security modules concentrates among three East Asian semiconductor packaging houses.
- FCC certification timelines:Radio frequency emission testing for wearable payment hardware in the United States extends commercialization cycles by four to seven months.
- Smartphone wallet substitution:Apple Pay and Google Pay maintain entrenched user habits and merchant acceptance infrastructure that wearable-native systems must displace.
Strategic Opportunities
- India PLI scheme:Production-linked incentive structures for electronics manufacturing are attracting wearable payment hardware assembly capacity to Gujarat and Tamil Nadu industrial corridors.
- Enterprise corporate wellness convergence:Biometric health monitoring integrated with payroll-linked payment credentials is opening B2B deployment channels in United States manufacturing sectors.
- Smart ring form factor:Miniaturized NFC antenna reliability improvements are creating fastest-growing configuration category for jewelry-integrated banking access.
Industry Challenges
- PCI DSS cryptographic key architecture:Token vault design complexity extends engineering headcount requirements and certification consultancy spend for device manufacturers.
- Biometric data governance fragmentation:Divergent consent frameworks for heart-rate pattern recognition across United States state-level privacy laws and GDPR create compliance engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Wearable Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatches, Fitness Trackers, Smart Rings, Head-Mounted Displays, Payment Bands Functionality: Contactless Payments, Biometric Authentication, Account Notifications, Financial Alerts, Fraud Detection End User: Corporate Clients, Retail Customers, Small Business Owners, Freelancers, Financial Advisors Distribution Channel: Online Banking Platforms, Retail Banking Branches, Mobile Wallets, Authorized Resellers, Direct Sales |
| Companies Covered | Garmin Ltd., Xiaomi Corporation, Apple Inc., Huami Technology Co., Ltd., Fossil Group, Inc., Samsung Electronics Co., Ltd., Huawei Technologies Co., Ltd., Guangdong OPPO Mobile Telecommunications Corp., Ltd., Fitbit, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Wearable Devices Market Trends and Innovations
Hardware security architecture and regulatory biometric governance are converging to redefine competitive differentiation in wearable banking. Product development cycles now synchronize with certification regime evolution rather than consumer electronics refresh patterns.
Ultra-wideband positioning chips paired with secure elements are consolidating transaction authentication around spatial verification protocols. Retail banking deployers in Germany and the United States are integrating these modules for proximity-based fraud prevention. The technology is consolidating previously separate payment and access-control credential management into unified wearable firmware stacks.
GDPR Article 9 special category processing restrictions are tightening consent workflows for biometric authentication in European banking wearables. Device manufacturers must now implement granular opt-in architectures for fingerprint template storage. Premium smartwatch configurations targeting EU markets are responding with hardware-isolated biometric data enclaves that limit cloud transmission.
Banking customers are fragmenting procurement authority between retail and enterprise channels as corporate wellness programs subsidize wearable deployment. United States manufacturing and logistics sectors are displacing individual purchase decisions with fleet-managed payment credential distribution. This behavioral rotation concentrates volume among device vendors with enterprise device management certification and Knox-grade security layering.
Banking Wearable Devices Market Segmentation
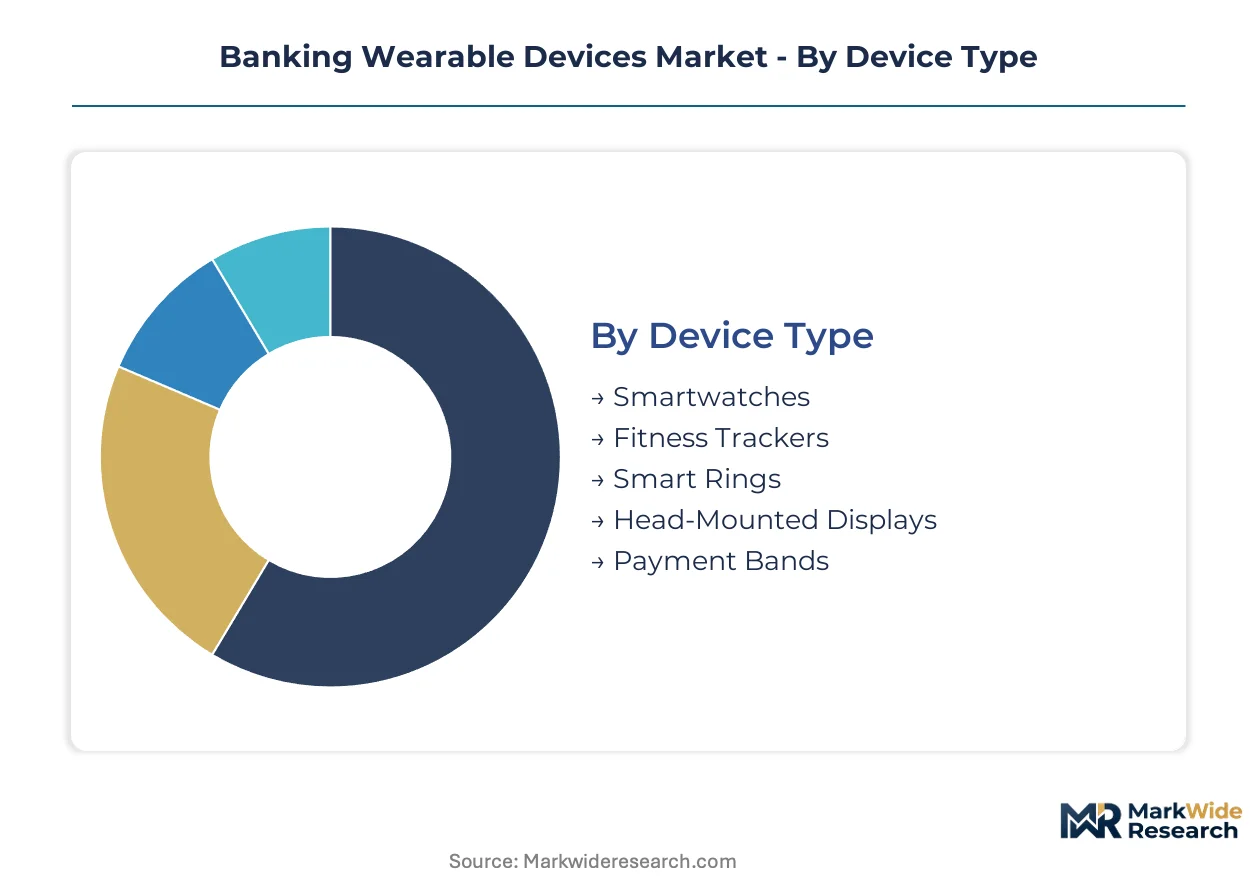
Banking wearable devices fragment across four structural dimensions that determine hardware specifications, certification pathways, and margin architecture. Device type governs secure element placement and antenna geometry. Functionality selection drives biometric sensor integration depth. End-user classification shapes enterprise device management requirements. Distribution channel determines token vault custody models.
Device Type:
Standardization dominates wrist-worn configurations while finger-worn and head-mounted variants require bespoke engineering for secure element miniaturization.
- Smartwatches:Multi-function wrist-worn devices integrate EMV-compliant secure elements, capacitive fingerprint sensors, and Bluetooth Low Energy radios for contactless payment execution. Demand concentrates in Germany and the United States where established smartwatch ecosystems intersect with mature digital banking infrastructure, driven by retail banking customer migration from smartphone-locked wallets.
- Smart Rings:Finger-worn form factors employ miniaturized NFC antennas and ceramic or titanium enclosures to achieve reliable transaction range in jewelry-integrated configurations. Demand concentrates among premium retail segments in China and Germany where aesthetic integration with personal accessories drives adoption, propelled by tokenization protocols that decouple credentials from handset tethering.
- Fitness Trackers:Health-monitoring wristbands with payment capabilities leverage existing heart-rate sensor infrastructure for biometric authentication overlays.
- Head-Mounted Displays:AR-enabled eyewear integrates secure elements for spatial payment verification in enterprise logistics environments.
- Payment Bands:Dedicated single-function NFC wristbands dominate price-sensitive Asian markets through cost-optimized module configurations.
Most installed capacity flows through Smartwatches. Expansion is steepest in Smart Rings.
Functionality:
Core payment execution commands premium pricing while layered authentication and alert services differentiate mid-tier offerings.
- Contactless Payments:EMV-compliant transaction execution via NFC tokenization represents the foundational capability enabling all other functionality layers. Deployment concentrates in United States and German retail banking channels where FCC and EU AI Act compliance frameworks mandate hardware-embedded credential security, driven by near-field communication tokenization standards.
- Biometric Authentication:Fingerprint, heart-rate pattern, and behavioral biometric verification layers reduce fraud incidence in high-value transactions. Adoption concentrates in European markets subject to GDPR Article 9 special category processing restrictions, propelled by algorithmic transparency mandates for fraud detection models.
- Account Notifications:Encrypted financial alert transmission via Bluetooth Low Energy enables real-time balance and transaction visibility.
- Financial Alerts:Threshold-based spending warnings and merchant category notifications support budget management workflows.
- Fraud Detection:On-device machine learning models analyze transaction velocity and geolocation patterns for anomaly flagging.
Contactless Payments anchors revenue contribution. Biometric Authentication is climbing the fastest as regulatory pressure intensifies.
End User:
Individual procurement authority fragments as corporate wellness programs displace personal purchase decisions in manufacturing and logistics sectors.
- Retail Customers:Individual consumers purchasing through banking channels or direct-to-consumer electronics retail represent the volume foundation. Demand concentrates in United States and China where smartphone wallet substitution pressure is highest, driven by contactless credential portability from handsets to wearables.
- Corporate Clients:Enterprise fleet deployments integrate payroll-linked payment credentials with biometric health monitoring for manufacturing workforce management. Adoption concentrates in United States industrial corridors where Knox-grade security layering and enterprise device management certification are mandatory, propelled by corporate wellness convergence with banking access.
- Small Business Owners:Sole proprietors seek consolidated personal-business expense separation through dedicated wearable credential sets.
- Freelancers:Gig economy workers prioritize instant payment receipt notification and rapid fund access mobility.
- Financial Advisors:Wealth management professionals require secure client account viewing and transaction authorization workflows.
Retail Customers maintain the largest installed base. Corporate Clients are gaining share fastest through fleet-managed procurement.
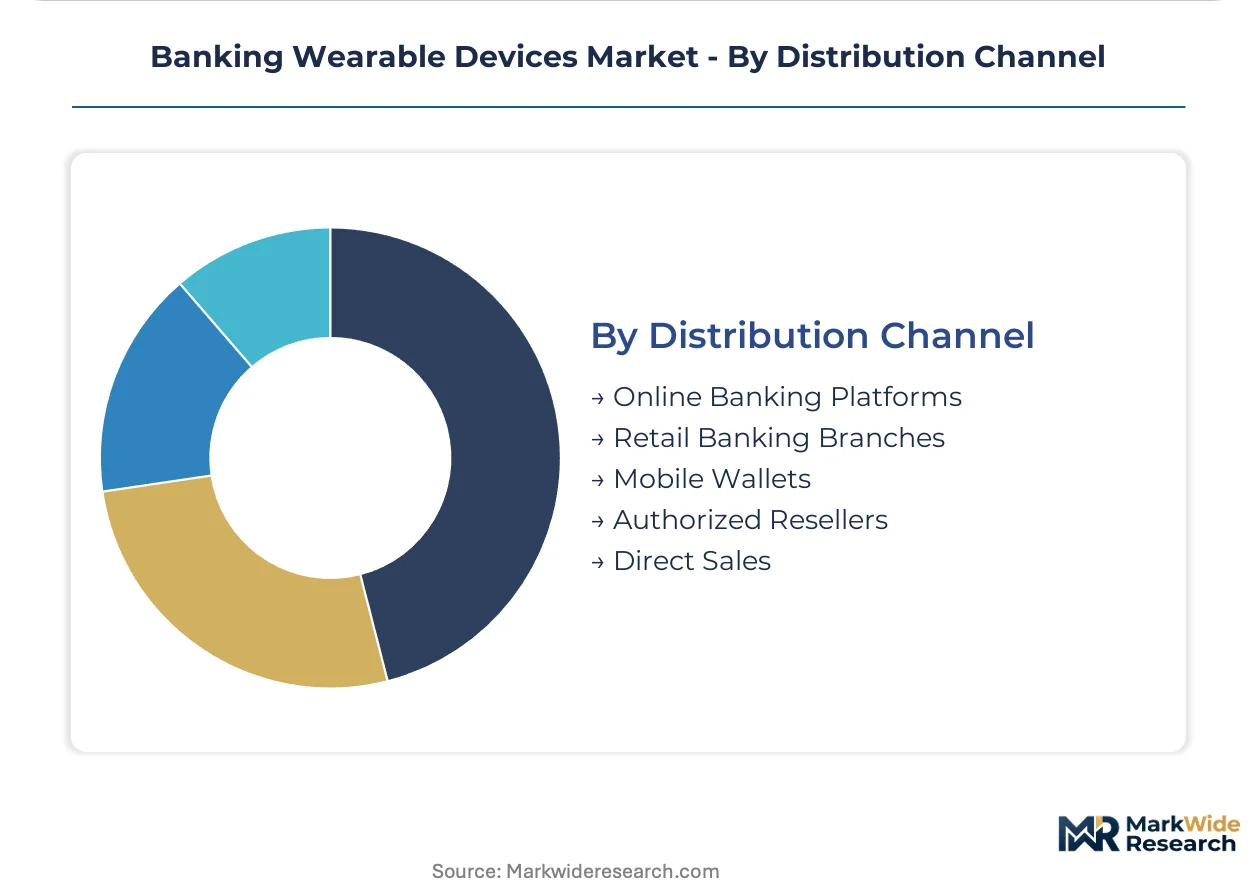
Distribution Channel:
Token vault custody models diverge between banking-controlled platforms and wallet-provider intermediated pathways.
- Online Banking Platforms:Direct-to-customer provisioning through mobile banking applications enables seamless credential tokenization and device pairing. Volume concentrates in Germany and United States where established digital banking infrastructure supports over-the-air secure element personalization, driven by retail banking customer preference for integrated financial service ecosystems.
- Mobile Wallets:Third-party wallet application integration extends distribution reach beyond traditional banking relationships. Penetration concentrates in China where Alipay and WeChat Pay infrastructure dominates, propelled by super-app ecosystem lock-in effects.
- Retail Banking Branches:Physical channel deployment supports demographic segments requiring assisted setup and biometric enrollment.
- Authorized Resellers:Electronics retail partnerships expand addressable markets through point-of-sale financing and trade-in programs.
- Direct Sales:Manufacturer-controlled channels preserve margin and enable rapid security patch distribution.
Online Banking Platforms process the highest credential volume. Mobile Wallets show the steepest expansion trajectory in Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The banking wearable devices industry traces its commercial roots to the United States and Germany, where early smartwatch payment integrations established the technical and regulatory templates now diffusing across major economies.
United States
Retail banking customers drive wrist-worn payment adoption as contactless credentials migrate from smartphones. FCC certification requirements govern radio frequency emissions for wearable hardware, extending commercialization cycles. Silicon Valley and Austin tech corridors host secure element architecture development for premium smartwatch ecosystems.
Germany
Established smartwatch ecosystems intersect with mature digital banking infrastructure to sustain demand concentration. EU AI Act algorithmic transparency mandates accelerate hardware-embedded biometric verification adoption. Bavarian industrial clusters engineer EMV-compliant secure elements for European market certification.
China
Mass-market payment band configurations dominate through cost-optimized NFC module production. MIIT and SAMR standards govern wireless communication protocols and data security for wearable financial hardware. Shenzhen and Dongguan manufacturing corridors concentrate miniaturized antenna assembly capacity.
India
Production-linked incentive structures attract wearable payment hardware assembly to Gujarat and Tamil Nadu industrial corridors. RBI guidelines on tokenized payment systems shape domestic certification requirements. Bangalore fintech clusters pilot payroll-linked biometric authentication for corporate workforce deployments.
Japan
Consumer electronics heritage supports premium smartwatch payment integration with transit and retail infrastructure. METI standards coordinate secure element interoperability across domestic banking networks. Tokyo-Osaka metropolitan corridors concentrate contactless merchant terminal density that wearable systems leverage.
Banking Wearable Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across secure element architecture and biometric sensor integration depth. The vendor base stratifies into three tiers: ecosystem-anchored technology giants, specialized wearable fabricators, and cost-optimized module assemblers. Strategic moves concentrate on enterprise device management certification acquisition and Knox-grade security layering for corporate fleet deployments. Geographic expansion into India PLI corridors and technology licensing for ultra-wideband positioning integration represent dominant competitive vectors.
Within the ecosystem-anchored tier, Apple Inc. and Samsung Electronics Co., Ltd. occupy positions defined by proprietary secure element architectures and vertical control over hardware-software integration. Xiaomi Corporation exemplifies the cost-optimized archetype through mass-market NFC module configurations. Garmin Ltd. represents specialized wearable fabricators with enterprise-facing device management capabilities. These three anchors collectively illustrate the competitive tension between premium authentication experiences and price-sensitive credential portability across diverging regional demand profiles.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Xiaomi Corporation |
| Apple Inc. |
| Huami Technology Co., Ltd. |
| Fossil Group, Inc. |
| Samsung Electronics Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| Guangdong OPPO Mobile Telecommunications Corp., Ltd. |
| Fitbit, Inc. |
| Others |
Pricing and Supply Chain Analysis
Retail banking customer procurement consolidation around fleet-managed corporate wellness programs is forcing module suppliers to absorb volume-scale discounts while maintaining Knox-grade security certification standards, compressing margins at the component tier and amplifying price differentiation between premium smartwatch and mass-market payment band configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with EMV certification grade and biometric sensor integration depth as primary price differentiation drivers. Cost compression in economy-tier payment bands is intensifying because Xiaomi Corporation's cost-optimized NFC modules anchor Asian mass-market pricing. Corporate clients demonstrate lowest price sensitivity due to enterprise device management certification requirements, while individual retail customers in developing markets exhibit highest sensitivity.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Dongguan manufacturing corridors are elevating labor costs for miniaturized antenna assembly, even as Gujarat and Tamil Nadu industrial corridors attract capacity through India's PLI scheme. Secure element fabrication draws from Taiwan and South Korea foundries, while ceramic enclosures and titanium substrates feed from Chinese metallurgical suppliers. Single-source vulnerability concentrates in EMV-certified hardware security module packaging houses. Distribution runs through direct-to-consumer online banking platforms and mobile wallet intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in banking wearables rests on capacitive fingerprint sensor cost curves dropping below three dollars and premium smart ring adoption shifting volume toward jewelry-integrated form factors with higher attachment rates.
For Market Incumbents: Acquire enterprise device management certification assets to defend corporate fleet deployment share against Knox-grade security layering competitors. Secure foundry capacity agreements for EMV-certified secure elements to mitigate single-source concentration risk in East Asian packaging houses. For New Entrants and Emerging Players: Enter via smart ring form factor miniaturization targeting premium retail segments in Germany and China where aesthetic integration commands pricing power. White-space opportunity concentrates in payroll-linked biometric authentication for United States manufacturing workforce management with corporate wellness convergence positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized wearable fabricators possessing enterprise-facing device management capabilities and ultra-wideband positioning chip integration roadmaps. Long-term viability favors vendors with backward integration into secure element architecture rather than module assemblers. Signal to watch: FCC certification timeline compression indicating regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-wideband Positioning Integration | Spatial verification protocols consolidate payment and access-control credentials into unified firmware stacks for German retail banking deployers. |
| Enterprise Device Management Certification | Knox-grade security layering opens B2B deployment channels in United States manufacturing and logistics sectors. |
| India PLI Corridor Manufacturing | Production-linked incentives attract assembly capacity to Gujarat and Tamil Nadu for cost-optimized payment band export. |
| GDPR Article 9 Compliance Architecture | Hardware-isolated biometric data enclaves limit cloud transmission for EU market premium smartwatch configurations. |
| Capacitive Fingerprint Miniaturization | Sensor module cost curves below three dollars unlock mass-market payment band configurations in price-sensitive Asian markets. |
Research Methodology
Bottom-up retail banking and corporate client modeling reconciled against top-down secure element and NFC module production tracking forms the analytical core. Primary interviews with wearable device engineering leads, digital banking product managers, enterprise procurement officers, and regulatory compliance consultants combined with secondary validation from SEC filings, FCC equipment authorization databases, EU AI Act implementation guidance, and RBI tokenization guidelines. Triangulation across stakeholder inputs and documentary sources anchors volume estimates.
Historical trendline analysis of smartwatch and payment band shipment patterns informs projection modeling across device type, functionality layer, end-user classification, and distribution channel dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market trajectory. Industry-specific forecast inputs include EMV certification pipeline tracking and corporate wellness program adoption curves in United States manufacturing sectors.
The model holds under stable regulatory certification timelines and continued NFC tokenization standardization; deviation in FCC approval delays or EU AI Act enforcement intensity would shift commercialization cycle assumptions. Forecasts reflect documented assumptions about biometric sensor cost curves and secure element foundry capacity expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
API Banking Market
Banking
Global Banking Systems Software Market
Banking
Credit Intermediation Market
Banking
North America Bank Kiosk Market
Banking
Asia-Pacific Islamic Finance Market
Banking
US Retail Banking Market
Banking
AI and Automation in Banking Market
Banking
Voice Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Bank Kiosk Market
Banking
Mobile Banking Market
Banking
Banking Wearable Market
Banking
Brazil Retail Banking Market
Banking
Middle East and Africa Neobanking Market
Banking
US Banking-As-A-Service Market