
 GCC Bancassurance Market | 2026-2036
GCC Bancassurance Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Bancassurance Market Intelligence
The EU Green Deal's extraterritorial disclosure requirements for financial services is repositioning how Gulf insurers report embedded carbon in investment-linked policies. Allianz SE leverages its European compliance infrastructure to anchor sustainability-linked product design across UAE and Saudi partnerships. HSBC Holdings plc dominates bancassurance shelf space in the UAE through its captive distribution network and integrated wealth advisory desks. AXA Group differentiates via digital-first policy administration platforms that reduce branch onboarding friction for mass-affluent segments.
Bancassurance denotes the distribution of insurance products through banking channels, where licensed insurers underwrite policies sold via bank branch networks, online portals, and relationship manager referrals, with commission structures typically embedding 15-40% of first-year premium into bank revenue pools. Life Insurance occupies the largest share of GCC bancassurance premium flows, driven by mandatory credit-life provisions tied to mortgage and personal lending. High Net Worth Individuals represent the fastest-growing customer segment as private banks bundle universal life with investment advisory and cross-border wealth structuring. Online Sales channels are accelerating fastest among distribution modalities, though Bank Branches still capture the majority of policy origination value due to face-to-face trust dynamics in Gulf markets.
SAMR in China and the EU AI Act create compliance templates that UAE Insurance Authority and Saudi Central Bank increasingly reference for algorithmic underwriting transparency in digital bancassurance platforms. The country's national insurance regulator in the UAE mandates bancassurance product filings with explicit fee disclosure, compressing opaque commission structures and favoring banks with integrated actuarial capabilities. Stakeholders must monitor whether Saudi Central Bank's open banking framework enables third-party insurance aggregators to disintermediate proprietary bank-insurer exclusivity arrangements before committing to long-term distribution partnerships.
Market Dynamics
Saudi Central Bank's open banking framework and the UAE Insurance Authority's fee disclosure mandates are compressing opaque commission structures while accelerating digital policy origination across Gulf bank branch networks.
Growth Catalysts
- Credit-life mandates:Saudi Arabia's mortgage lending surge embeds mandatory term life coverage into retail banking products, channeling premium flows through established branch relationships.
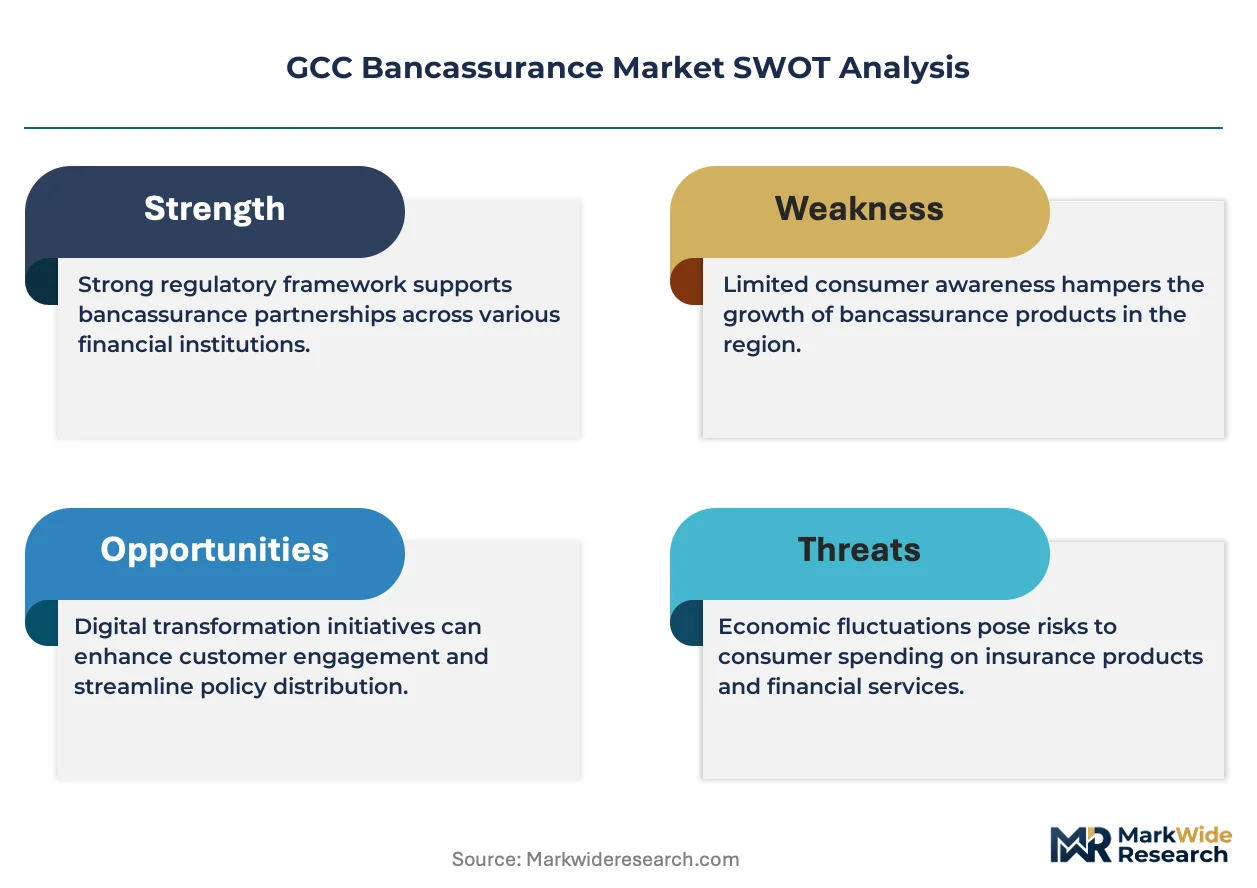
- EU AI Act templates:Algorithmic underwriting transparency requirements from European regulatory frameworks are being adapted by UAE and Saudi supervisors, legitimating automated risk assessment in digital bancassurance platforms.
- Private banking bundling:High Net Worth Individuals across Dubai and Abu Dhabi are driving demand for universal life products integrated with cross-border wealth structuring services.
Market Restraints
- Commission compression:UAE Insurance Authority product filings with explicit fee disclosure are eroding the 15-40% first-year premium pools that historically sustained bank profitability.
- Legacy system integration:Core banking platforms at established Gulf institutions require substantial reconfiguration to support real-time policy administration and digital onboarding workflows.
- Third-party aggregator threat:Saudi Central Bank's open banking framework may enable insurance aggregators to bypass proprietary bank-insurer exclusivity arrangements.
Strategic Opportunities
- Kuwait underpenetration:Bancassurance density remains below Gulf averages, presenting first-mover advantages for insurers establishing dedicated distribution partnerships with retail banking networks.
- Embedded carbon reporting:EU Green Deal extraterritorial disclosure requirements create demand for sustainability-linked investment policies among Gulf private banks serving European-connected clients.
- Mass-affluent digital migration:Online sales channels are capturing policy origination previously handled through branch referrals, rewarding platforms with integrated actuarial capabilities.
Industry Challenges
- Actuarial talent scarcity:Gulf insurance authorities require localized expertise to validate algorithmic underwriting models, yet regional supply of qualified professionals trails platform deployment timelines.
- Cross-border data governance:Wealth structuring for High Net Worth Individuals involves policy data transfers across multiple jurisdictions, complicating compliance with divergent privacy frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Bancassurance Market |
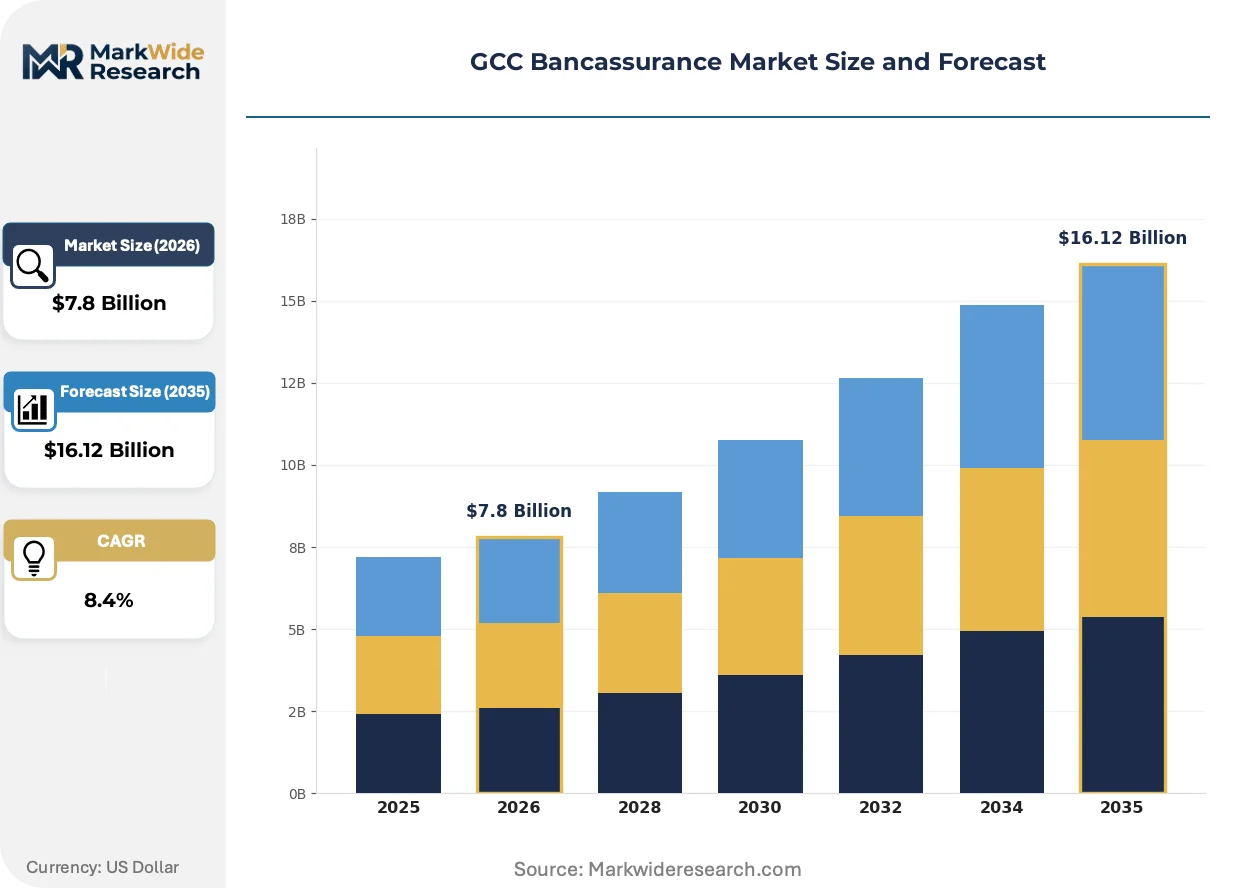
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Motor Insurance Distribution Channel: Online Sales, Bank Branches, Call Centers, Financial Advisors Customer Segment: Individual Customers, SMEs, Corporates, High Net Worth Individuals Service Type: Advisory Services, Claims Management, Policy Administration, Risk Assessment |
| Companies Covered | Citigroup Inc., Wells Fargo & Company, Allianz SE, Barclays plc, Banco Santander SA, AXA Group, MetLife Inc., ABN AMRO Bank N.V., HSBC Holdings plc, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Bancassurance Market Strategic Shifts & Innovations
Digital policy origination platforms are absorbing underwriting workflows previously executed through face-to-face branch interactions, while regulatory transparency mandates and sustainability-linked product design reshape competitive differentiation across Gulf banking partnerships.
Algorithmic underwriting engines are absorbing traditional risk assessment functions previously performed by human actuaries in branch settings. Mass-affluent segments across Dubai and Abu Dhabi are adopting these platforms at accelerating velocity as trust in automated decision-making solidifies. This absorption is compressing policy issuance timelines from weeks to hours while reducing onboarding friction for digitally native customer cohorts.
SAMR-aligned product standardization frameworks from China's regulatory architecture are influencing UAE Insurance Authority guidelines for digital bancassurance filings. Gulf supervisors are adapting these templates to mandate explicit fee disclosure and algorithmic transparency in automated underwriting systems. Retail banking distributors across the Emirates are responding by consolidating partnerships with insurers possessing integrated actuarial capabilities.
Relationship manager referrals are yielding to self-service digital portals for routine policy origination among younger demographic cohorts. Branch networks still capture high-value universal life sales requiring face-to-face trust dynamics, but online channels are displacing intermediaries for standardized credit-life and term products. This bifurcation is most visible in Saudi Arabia's retail banking corridors, where mortgage lending automation drives parallel demand for instantaneous coverage issuance.
GCC Bancassurance Market Segmentation
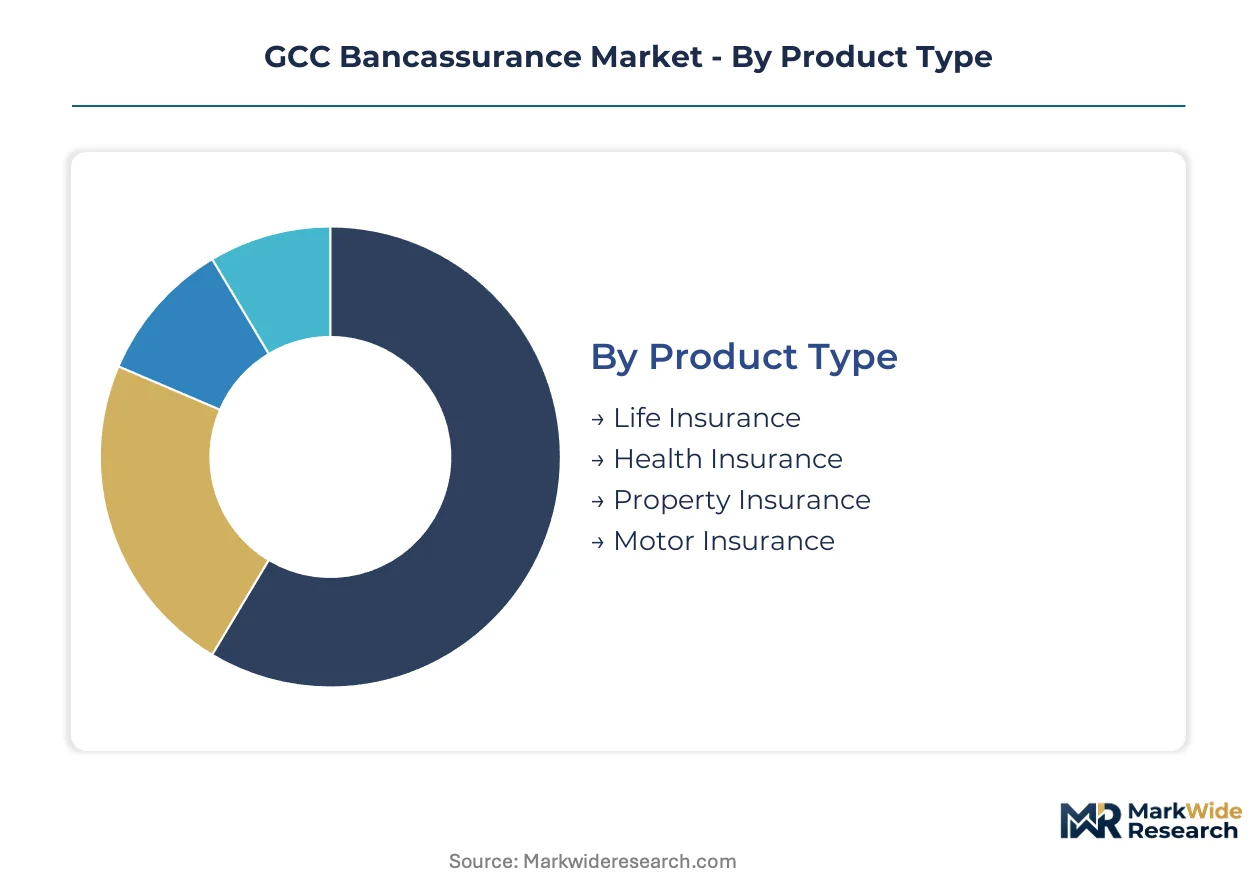
Segmentation in GCC bancassurance reveals how capital deployment, regulatory alignment, and customer trust dynamics vary across product structures and delivery mechanisms. Banks and insurers must match infrastructure investment to segment-specific origination complexity and compliance burden.
Product Type:
Capital intensity peaks in segments requiring embedded actuarial infrastructure and regulatory capital reserves.
- Life Insurance:Universal life and credit-life products demand captive actuarial teams and SAMR-aligned algorithmic underwriting platforms. Mandatory mortgage-linked term coverage in Saudi Arabia channels premium volume through retail banking networks, though EU AI Act transparency requirements elevate compliance spend for automated risk assessment engines.
- Health Insurance:Group medical policies for private-sector employers in Dubai and Abu Dhabi require integrated claims management systems and provider network contracting. DHA and DOH regulatory filings impose recurring compliance costs that favor insurers with established Gulf health authority relationships.
- Property Insurance:Home and contents coverage tied to mortgage origination flows through branch-based distribution with standardized underwriting.
- Motor Insurance:Vehicle coverage distributed via banking partnerships leverages telematics integration for premium pricing, with UAE Insurance Authority mandates on digital policy issuance driving platform investment.
Most installed capacity flows through Life Insurance. Expansion is steepest in Health Insurance.
Distribution Channel:
Customer acquisition economics diverge sharply between high-touch relationship models and self-service digital infrastructure.
- Bank Branches:Face-to-face origination captures universal life and complex wealth-structuring products where trust dynamics favor human advisors. UAE and Saudi branch networks retain premium shelf space through exclusive insurer partnerships, though 15-40% commission pools face compression under fee disclosure mandates.
- Online Sales:Digital portals for standardized credit-life and term products reduce onboarding friction for mass-affluent cohorts in Riyadh and Dubai. Algorithmic underwriting engines compress policy issuance timelines, with Saudi Central Bank open banking frameworks enabling aggregator competition.
- Call Centers:Voice-channel origination serves renewal and endorsement transactions with lower per-policy acquisition cost than branches.
- Financial Advisors:Independent advisory channels access high net worth segments outside proprietary bank networks, though regulatory licensing requirements limit scalable deployment.
Policy value concentrates in Bank Branches. Digital origination is climbing the fastest among modalities.
Customer Segment:
Regulatory treatment and product complexity create distinct profitability profiles across buyer categories.
- High Net Worth Individuals:Cross-border wealth structuring demands universal life products with investment-linked components and multi-jurisdictional compliance. Dubai private banks bundle advisory, insurance, and custody services, generating elevated fee income per relationship.
- Corporates:Group life and health coverage for private-sector employers in Abu Dhabi and Riyadh sustains recurring premium flows with standardized underwriting.
- Individual Customers:Retail banking clients across Saudi Arabia and the UAE represent expanding demand for mortgage-linked credit-life and simple term coverage.
- SMEs:Small business segments remain underpenetrated relative to corporate and individual categories, with distribution economics challenging at lower premium scale.
Revenue per relationship peaks with High Net Worth Individuals. Volume expansion is gaining share fastest among Individual Customers.
Service Type:
Technology substitution and regulatory automation reshape which service layers justify dedicated investment.
- Policy Administration:Core systems for issuance, endorsement, and renewal require real-time integration with banking cores and regulatory reporting infrastructure. UAE Insurance Authority digital filing mandates favor platforms with automated compliance workflows.
- Advisory Services:Human-delivered wealth and risk counseling retains premium positioning for complex universal life and cross-border structuring.
- Claims Management:Health and property claims processing demands provider network integration and fraud detection capabilities.
- Risk Assessment:Algorithmic underwriting engines absorb traditional actuarial functions, with SAMR-aligned transparency requirements elevating model governance investment.
Platform spend concentrates in Policy Administration. Automation penetration is expanding most quickly in Risk Assessment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bancassurance distribution first achieved scale in European banking networks during the 1980s before Gulf institutions adapted the model to Islamic finance frameworks. The GCC variant now channels life and health products through retail branch networks anchored in hydrocarbon-funded banking systems.
Saudi Arabia
Mortgage lending expansion and mandatory credit-life provisions drive premium volume through Riyadh-based retail networks. Saudi Central Bank's open banking framework enables third-party aggregator access to customer financial data. Jeddah and the Eastern Province host concentrated branch infrastructure where insurers compete for exclusive distribution partnerships.
United Arab Emirates
Private-sector employment growth in Dubai and Abu Dhabi sustains group life and health coverage uptake through bank-originated policies. UAE Insurance Authority mandates explicit fee disclosure in product filings, compressing traditional commission structures. Dubai International Financial Centre clusters wealth advisory operations bundling universal life with cross-border structuring services.
Kuwait
Bancassurance penetration trails Gulf averages, creating first-mover opportunities for insurers establishing dedicated retail banking partnerships. The country's national insurance regulator maintains conservative licensing requirements that slow foreign carrier market entry. Kuwait City concentrates domestic banking assets where local insurers retain distribution exclusivity.
Qatar
High net worth demographic density supports premium universal life products distributed through private banking channels. Qatar Central Bank's regulatory framework emphasizes consumer protection disclosures in bancassurance product marketing. Doha's financial district hosts captive insurance operations serving regional family office networks.
Bahrain
Regional insurance licensing hub status attracts carrier regional headquarters seeking Gulf market access. Central Bank of Bahrain's regulatory sandbox permits pilot digital bancassurance platforms with relaxed filing requirements. Manama's banking cluster serves as a testbed for algorithmic underwriting deployment before Saudi and UAE scaling.
GCC Bancassurance Market Key Industry Players
Premium-margin players sit above commodity-margin players across advisory integration and digital platform sophistication. The vendor base concentrates around banking groups with captive distribution networks and European insurers with compliance infrastructure transferable to Gulf regulatory frameworks. Three archetypes dominate: integrated universal banks with proprietary insurance partnerships, European carriers leveraging EU regulatory templates, and regional insurers with localized actuarial capabilities. Competitive moves center on exclusive distribution renegotiations and algorithmic underwriting platform deployment.
Among European-based carriers, Allianz SE and AXA Group exemplify compliance-forward positioning adapted to EU AI Act transparency requirements. HSBC Holdings plc anchors the integrated banking archetype through UAE and Saudi branch network dominance. These three entities represent distinct strategic postures: regulatory infrastructure leverage, digital platform specialization, and captive distribution scale.
| Leading Market Players |
|---|
| Citigroup Inc. |
| Wells Fargo & Company |
| Allianz SE |
| Barclays plc |
| Banco Santander SA |
| AXA Group |
| MetLife Inc. |
| ABN AMRO Bank N.V. |
| HSBC Holdings plc |
| Others |
Cost & Logistics Intelligence
Sovereign-backed banking networks across Saudi Arabia and the UAE anchor distribution capacity, compressing commission pools while concentrating pricing power with institutions possessing integrated actuarial platforms. This ownership pattern channels premium flows through exclusive partnerships that resist price-based competition from smaller regional carriers lacking captive branch infrastructure.
Pricing Analysis
Commission-based pricing structures embedded in first-year premium splits dominate bancassurance economics, with bank revenue pools historically capturing substantial portions before UAE Insurance Authority fee disclosure mandates. Price differentiation rests on algorithmic underwriting sophistication and regulatory compliance infrastructure rather than product features alone. Pricing pressure intensifies as digital aggregators exploit Saudi Central Bank open banking frameworks to bypass proprietary exclusivity arrangements. Individual retail banking customers exhibit highest price sensitivity for standardized credit-life products, while High Net Worth Individuals demonstrate lowest sensitivity due to bundled wealth advisory integration.
Supply Chain Analysis
SAMR-aligned certification requirements for algorithmic underwriting transparency are gating market access, favoring insurers with pre-built compliance architectures adaptable to UAE Insurance Authority and Saudi Central Bank mandates. Product development and policy administration concentrate in the UAE, Saudi Arabia, and Bahrain, with the latter serving as a regulatory sandbox for platform testing before Gulf-wide deployment. Raw material dependencies include actuarial talent pools, core banking system integration capacity, and regulatory filing expertise. Supply chain risk centers on single-source vulnerability in qualified actuarial professionals needed to validate automated risk assessment engines. Distribution runs through exclusive bank-insurer partnerships, though aggregator platforms threaten disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC bancassurance functions as a stable compounder anchored by mandatory credit-life provisions tied to mortgage lending expansion across Saudi Arabia and the UAE. Regulatory transparency mandates and digital platform investments sustain predictable premium flow trajectories.
For Market Incumbents: Deepen exclusive distribution partnerships with retail banking networks in Saudi Arabia's Eastern Province and UAE's northern emirates before open banking frameworks enable aggregator competition. Invest in SAMR-aligned algorithmic underwriting certification to defend against commission compression from fee disclosure mandates. Prioritize vertical integration of actuarial capabilities to maintain pricing power as regulatory transparency erodes opaque revenue pools. For New Entrants and Emerging Players: The price-point gap between premium universal life products and economy-tier credit-life coverage creates entry space for digitally native platforms targeting mass-affluent segments in Riyadh and Dubai. Kuwait's underpenetrated banking networks offer the most penetrable geography for first-mover distribution partnerships. Lead with self-service digital onboarding that compresses policy issuance timelines relative to legacy branch-based competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional insurers lacking integrated digital policy administration platforms but possessing established Gulf regulatory relationships. Long-term viability across a multi-year horizon favors carriers with backward integration into actuarial talent development and algorithmic model governance. Monitor Saudi Central Bank open banking implementation velocity as the critical inflection signal for proprietary distribution exclusivity durability.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Underwriting Platform Deployment | SAMR-aligned transparency requirements elevate compliance barriers for automated risk assessment engines across UAE and Saudi partnerships. |
| Exclusive Distribution Partnership Renegotiation | Bank branch networks in Dubai and Riyadh command premium shelf space as open banking frameworks threaten proprietary insurer arrangements. |
| Actuarial Talent Development Program | Localized expertise scarcity constrains platform deployment timelines, favoring carriers with captive training pipelines. |
| Digital Policy Origination Migration | Self-service portals displace relationship manager referrals for standardized products among mass-affluent cohorts in Saudi retail corridors. |
| Sustainability-Linked Product Design | EU Green Deal extraterritorial disclosure requirements create demand for embedded carbon reporting in investment-linked policies. |
Research Approach
Direct dialogue with insurance product heads, regulatory affairs officers at UAE Insurance Authority and Saudi Central Bank, retail banking distribution executives, and actuarial platform engineers grounded qualitative findings. Secondary validation drew from SAMR algorithmic transparency guidelines, EU AI Act implementation documentation, DHA and DOH health insurance filings, and SEC disclosures from listed European carriers with Gulf operations. Bottom-up policy volume estimates triangulated against top-down banking sector lending data.
Segmented outputs across product type, distribution channel, customer segment, and service type dimensions populated the analytical framework. CAGRs derived from lending growth trajectories, regulatory implementation schedules, and digital adoption curves specific to bancassurance distribution. Algorithmic underwriting penetration rates and open banking framework adoption timelines served as key forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path for algorithmic underwriting platforms; alternative pathways for human-in-the-loop risk assessment would alter the outlook for branch-based origination economics. Forecasts reflect assumptions regarding regulatory implementation velocity and banking sector consolidation patterns. A model refresh is warranted upon material change in Saudi Central Bank open banking aggregator licensing thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Financial Guarantee Market
Insurance
Cancer Insurance Market
Insurance
Intellectual Property Liability Insurance Market
Insurance
Critical Illness Insurance Market
Insurance
Norway Property and Casualty Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
Europe Online Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
France Car Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Aviation Insurance Market
Insurance
Canada Home Insurance Market