
 Canada Health and Medical Insurance Market | 2026-2036
Canada Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Health and Medical Insurance Market Outlook
Health Canada's Patented Medicine Prices Review Board reforms is shifting how insurers design prescription drug benefits. Manulife Financial Corporation leverages its digital health platform to streamline claims processing for employer groups. Sun Life Financial Inc. dominates the small business segment with bundled wellness and disability products. Green Shield Canada specializes in non-profit and charitable sector coverage, anchoring a niche with distinct procurement cycles.
Canada health and medical insurance constitutes privately underwritten risk-pooling instruments that supplement provincial single-payer systems, covering services excluded from public plans such as prescription pharmaceuticals, dental care, vision services, and private hospital accommodations. These contracts operate through premium-based funding mechanisms with defined benefit schedules, experience-rated renewals, and managed care protocols that control utilization. Group policies command the largest premium volume due to mandatory participation structures in corporate settings, while individual plans carry higher per-member acquisition costs and medical underwriting intensity. Critical illness coverage represents the fastest-expanding policy type as consumers seek lump-sum protection against cancer, stroke, and cardiac events outside reimbursement-based models.
Health Canada, the Office of the Superintendent of Financial Institutions, and provincial insurance regulators collectively govern solvency standards, policy form approvals, and consumer protection frameworks that dictate product availability and pricing transparency. The Canadian Life and Health Insurance Association's self-regulatory codes further constrain claims practices and disclosure requirements, creating compliance costs that favor scaled carriers. Stakeholders must monitor provincial pharmacare expansion timelines and their erosion of private drug coverage addressable markets.
Market Dynamics
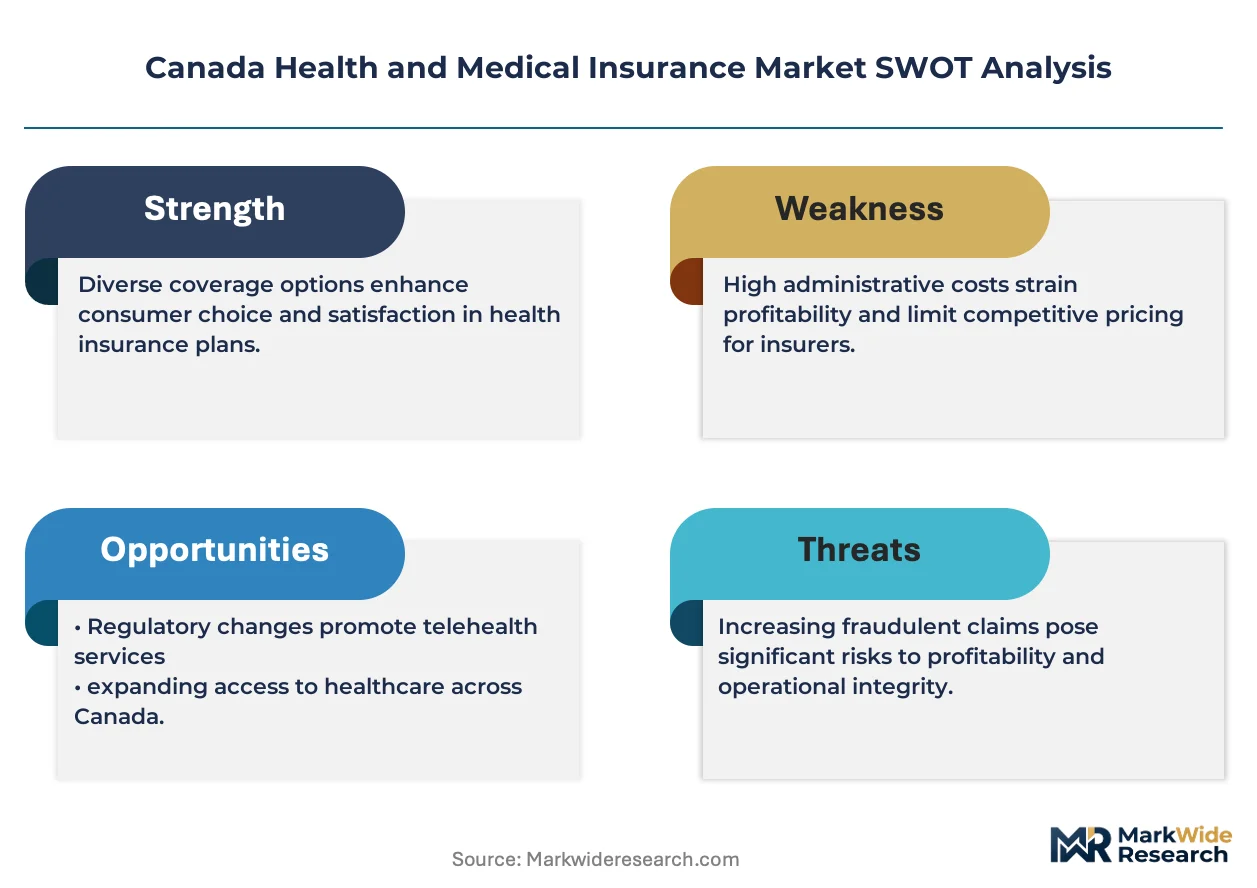
Health Canada's Patented Medicine Prices Review Board reforms are compressing drug reimbursement margins and forcing insurers to redesign benefit formularies around therapeutic value tiers rather than brand premiums.
Growth Catalysts
- Provincial Pharmacare Integration:Ontario and British Columbia are expanding public drug coverage for seniors, creating demand for private supplemental wrap-around policies that fill reimbursement gaps.
- Corporate Talent Competition:Technology sector employers in Toronto and Vancouver are bundling extended health benefits with mental health services to attract skilled workers in tight labor markets.
- Digital Claims Platforms:Real-time adjudication systems are reducing administrative friction for group plan administrators and accelerating member reimbursement cycles.
Market Restraints
- Single-Payer Crowding:Provincial health plans in Quebec and Alberta cover an expanding list of pharmaceuticals, eroding the addressable market for private drug insurance.
- Regulatory Fragmentation:Thirteen provincial and territorial insurance regulators maintain divergent policy form approval timelines, multiplying compliance overhead for national carriers.
- Biologic Cost Concentration:Specialty pharmaceutical spending now dominates large group claims experience, making premium predictability difficult for underwriters.
Strategic Opportunities
- Atlantic Canada Underpenetration:Nova Scotia and New Brunswick show lower private insurance density than Ontario, presenting white space for individual critical illness product expansion.
- Paramedical Service Bundling:Physiotherapy, chiropractic, and massage coverage are emerging as differentiators in small group markets where employers seek wellness-oriented benefits.
- Health Canada Digital Health Guidance:New frameworks for telehealth reimbursement are enabling insurers to integrate virtual care delivery into standard benefit schedules.
Industry Challenges
- Actuarial Talent Scarcity:Specialized health insurance pricing expertise is concentrating among senior professionals nearing retirement, constraining product development velocity.
- Legacy System Integration:Provincial health card data standards vary across jurisdictions, complicating real-time eligibility verification for supplemental insurers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Health and Medical Insurance Market |
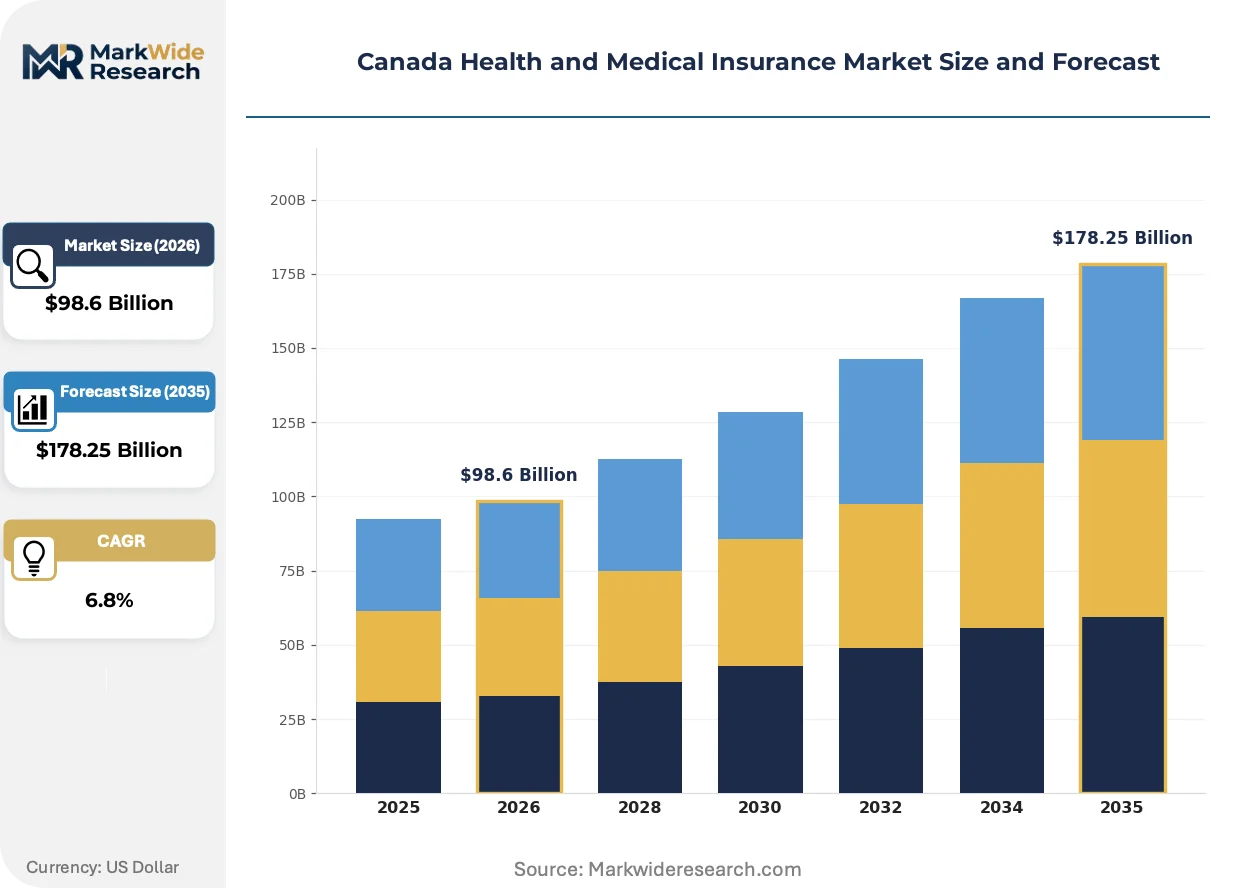
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family, Group, Critical Illness Coverage Scope: Hospitalization, Outpatient, Prescription Drugs, Preventive Care Customer Type: Private Individuals, Small Businesses, Corporations, Non-Profit Organizations Payment Model: Fee-for-Service, Managed Care, Capitation, Indemnity |
| Companies Covered | Desjardins Group, Green Shield Canada, Manulife Financial Corporation, Empire Life, Beneva, Sun Life Financial Inc., Industrial Alliance (iA Financial Group), Equitable Life Insurance Company of Canada, Canada Life Assurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Health and Medical Insurance Market Strategic Shifts
Artificial intelligence and connected health infrastructure are redefining how Canadian insurers assess risk, process claims, and engage policyholders across group and individual segments.
Telemedicine platforms are electrifying first-line care access by connecting plan members with physicians through mobile applications. Large employer groups in Calgary and Montreal are adopting these services as standard benefits. The technology is compressing traditional primary care utilization patterns and redirecting claims volume away from in-person consultations.
Health Canada's new guidance on real-world evidence for drug reimbursement decisions is tightening formulary management standards. Insurers must now demonstrate clinical outcomes for high-cost therapies before securing preferred tier placement. Group benefit administrators in Ontario are responding by contracting with pharmacy benefit managers that specialize in outcomes-based contracting.
Direct-to-consumer distribution channels are displacing traditional advisor-mediated sales for individual critical illness products. Digital comparison platforms now dominate customer acquisition in urban centers, replacing face-to-face underwriting interviews with algorithmic risk scoring. British Columbia shows the highest adoption of these frictionless purchase pathways among younger demographics.
Canada Health and Medical Insurance Market Segmentation
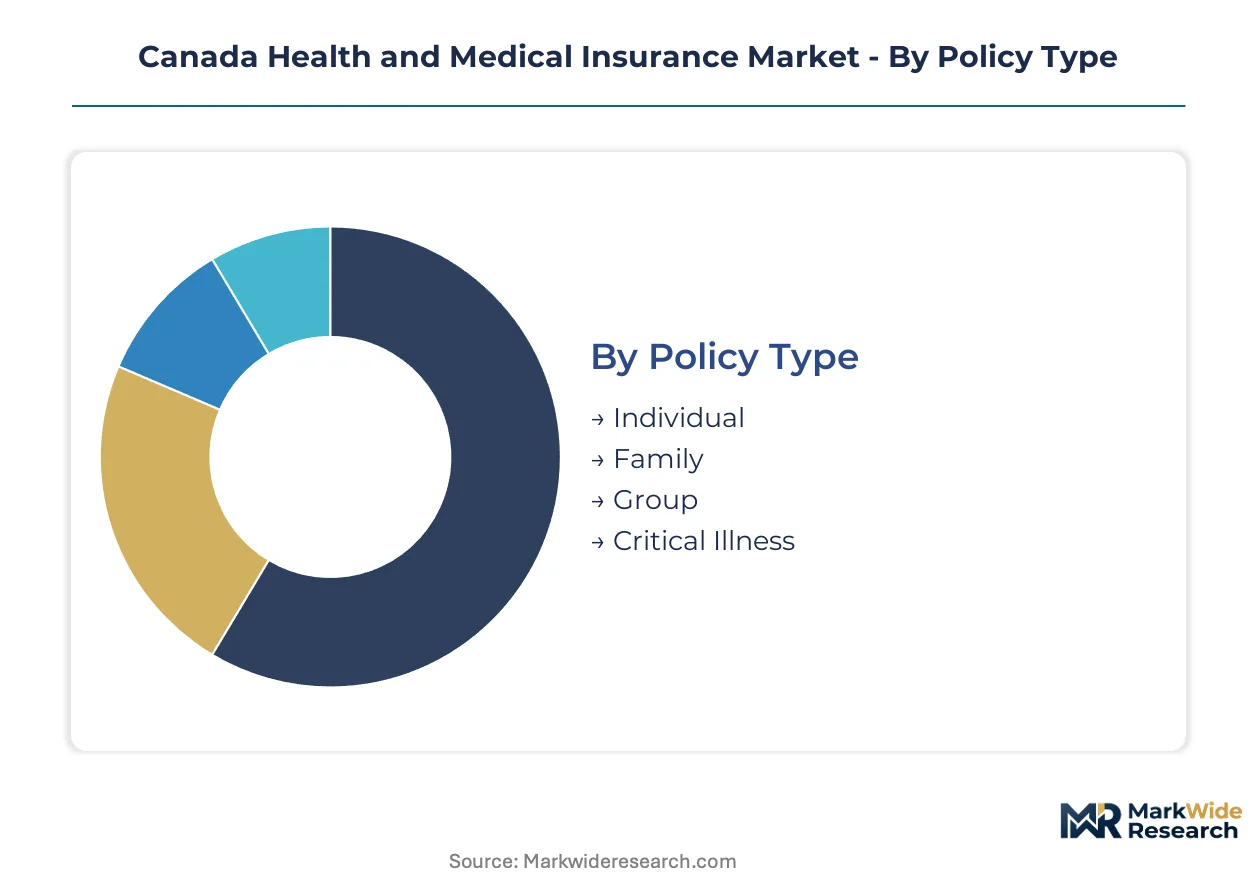
Segmentation in the Canadian health insurance market determines how provincial single-payer gaps translate into addressable premium pools. Insurers architect products around employer size, risk tolerance, and the specific services excluded from public coverage in each province.
Policy Type:
Standalone individual policies operate outside employer sponsorship, while embedded group coverage dominates commercial premium flows through mandatory workplace participation.
- Individual:Underwritten policies sold directly to consumers through digital platforms or advisors. Demand concentrates in Ontario and British Columbia among self-employed professionals and gig economy workers who lack employer-sponsored access.
- Family:Multi-member contracts extending coverage to dependents under single premium structures. Small business owners in Calgary and Ottawa purchase these to supplement provincial gaps for spouses and children.
- Group:Employer-sponsored plans with mandatory or opt-out participation. Technology sector employers in Toronto and Vancouver bundle these with mental health riders to compete for talent.
- Critical Illness:Lump-sum policies paying upon diagnosis of specified conditions rather than reimbursing treatment costs. Atlantic Canada shows underpenetration relative to Ontario, presenting expansion opportunity for simplified-issue products.
Group coverage leads volumes today; critical illness is gaining share fastest among younger demographics seeking financial protection outside reimbursement models.
Coverage Scope:
Cost-tier stratification separates basic hospital supplements from comprehensive outpatient and pharmaceutical riders that command premium multiples.
- Hospitalization:Semi-private and private room accommodations excluded from provincial standard ward coverage. Corporate plans in Montreal and Vancouver uniformly include this as a baseline benefit.
- Outpatient:Specialist consultations, diagnostic imaging, and day procedures outside hospital admission. British Columbia's limited public outpatient drug coverage drives private wrap-around demand here.
- Prescription Drugs:Pharmaceutical reimbursement for medications excluded from provincial formularies or subject to deductibles. Health Canada's Patented Medicine Prices Review Board reforms are compressing margins and forcing therapeutic-value tier designs.
- Preventive Care:Annual physicals, vaccinations, and screening services. Wellness-oriented employers in Toronto's financial district are expanding these benefits to reduce long-term claims experience.
Prescription drug coverage anchors premium economics today; preventive care is expanding most quickly as employers seek utilization reduction.
Customer Type:
Volume concentration sits with large corporate accounts, while margin profiles favor small business segments with less pricing power and higher retention.
- Private Individuals:Direct purchasers of individual and family policies through broker networks or digital channels. Alberta's energy sector layoffs have shifted some former group members into this segment.
- Small Businesses:Firms with under 50 employees purchasing pooled group coverage through association plans or direct carrier relationships. Sun Life dominates this segment with bundled wellness and disability products.
- Corporations:Large employers with self-insured or fully-insured arrangements and dedicated benefits administration. Technology and professional services firms in Vancouver and Toronto drive innovation in mental health and paramedical bundling.
- Non-Profit Organizations:Charitable and social service employers with distinct procurement cycles and budget constraints. Green Shield Canada specializes in this niche with tailored funding mechanisms.
Corporations generate the largest premium volumes; small businesses show the steepest expansion trajectory as provincial employment shifts toward services.
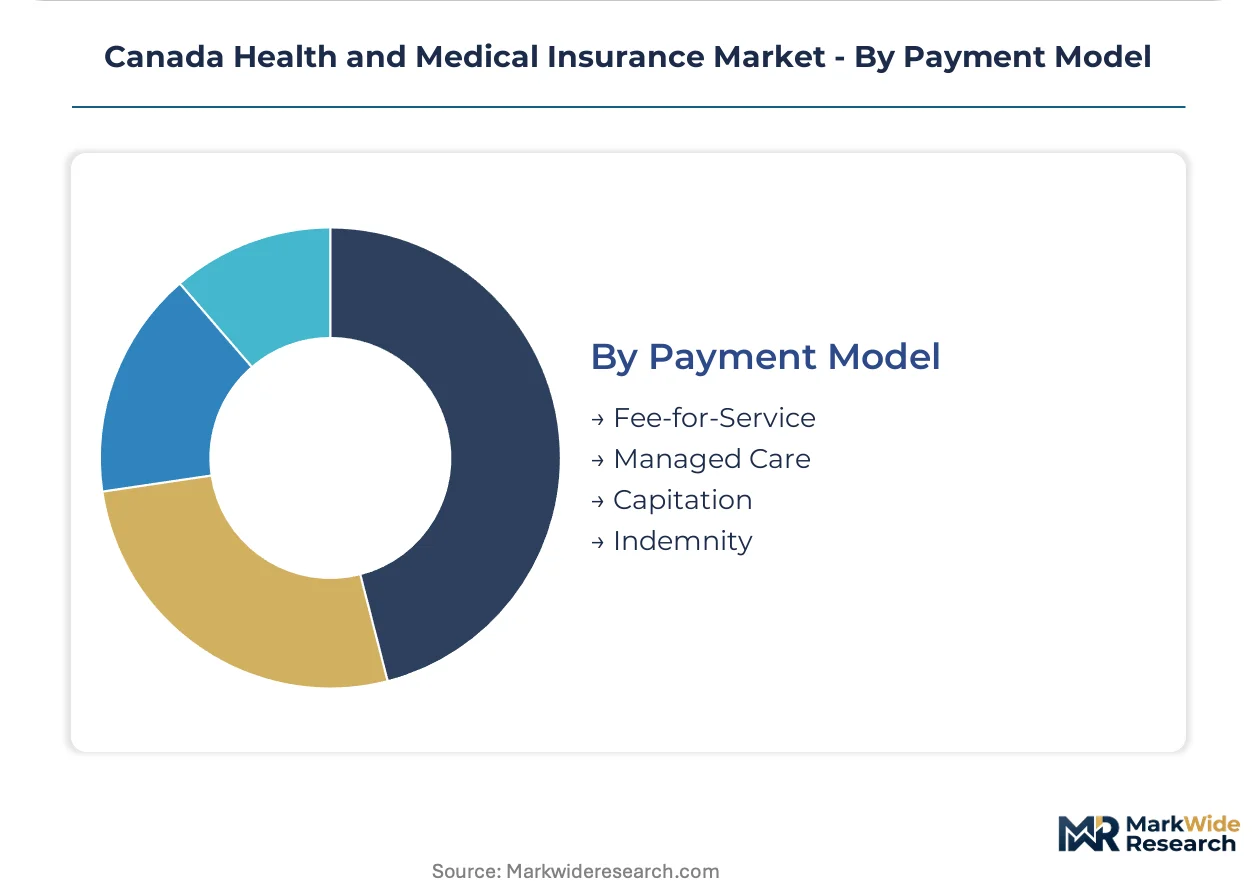
Payment Model:
Maturity gradients separate legacy indemnity structures from managed care protocols that Health Canada's digital health guidance is now enabling.
- Fee-for-Service:Traditional reimbursement of providers per procedure or visit rendered. Quebec maintains higher penetration of this model due to physician billing system structures.
- Managed Care:Utilization review, prior authorization, and network restrictions controlling cost exposure. Ontario group administrators are contracting with pharmacy benefit managers for outcomes-based contracting under this model.
- Capitation:Fixed per-member-per-month payments to provider networks assuming full care responsibility. Limited penetration in Canada relative to US markets due to provincial primary care enrollment models.
- Indemnity:Fixed cash payments to policyholders regardless of actual treatment costs. Critical illness products exclusively use this structure, enabling member discretion in fund deployment.
Managed care leads adoption among large groups; indemnity structures are climbing fastest within critical illness and hospital cash products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology sector employment clusters in Toronto and Vancouver anchor private insurance demand, while aging demographics across Ontario and British Columbia drive supplemental coverage uptake. Provincial pharmacare integration timelines create divergent market conditions across Canadian jurisdictions.
Ontario
Corporate talent competition in Toronto's financial district and Waterloo technology corridor expands employer-sponsored group coverage. Health Canada's Patented Medicine Prices Review Board reforms reshape prescription drug benefit designs for large employers. Manulife Financial Corporation leverages digital health platforms to streamline claims processing for enterprise clients concentrated in the Greater Toronto Area.
British Columbia
Vancouver's technology sector employers bundle extended health benefits with mental health services to attract skilled workers. Limited public outpatient drug coverage creates demand for private wrap-around policies. Sun Life Financial Inc. dominates small business segments with bundled wellness and disability products targeting professional services firms.
Quebec
Single-payer pharmaceutical coverage expansion erodes addressable markets for private drug insurance. Physician billing system structures maintain higher fee-for-service penetration than other provinces. Beneva and Desjardins Group anchor cooperative insurance models with distinct member-owned governance structures.
Alberta
Energy sector employment volatility shifts former group members into individual policy segments. Calgary employers adopt telemedicine platforms as standard benefits to compress primary care utilization. Industrial Alliance serves mid-market corporate accounts through flexible funding arrangements.
Atlantic Canada
Nova Scotia and New Brunswick show lower private insurance density than central provinces, presenting expansion opportunity for simplified-issue critical illness products. Non-profit and charitable sector employers concentrate procurement cycles through specialized carriers. Green Shield Canada anchors niche coverage with tailored funding mechanisms for social service organizations.
Canada Health and Medical Insurance Market Competitive Environment
Capital-heavy insurers with proprietary distribution networks compete with asset-light administrators outsourcing underwriting capacity. The market structures around three tiers: national diversified carriers with full product suites, regional specialists serving niche employment sectors, and mutual cooperatives with member-owned governance. Consolidation pressures favor scaled players with compliance resources to navigate thirteen provincial regulatory regimes. Strategic moves concentrate on digital platform investments and pharmacy benefit manager partnerships.
Within the national diversified tier, Manulife Financial Corporation, Sun Life Financial Inc., and Canada Life Assurance Company exemplify integrated carriers spanning group, individual, and wealth management operations. These firms occupy positions defined by scale-driven cost advantages and enterprise technology infrastructure. Green Shield Canada anchors the non-profit specialist archetype with distinct procurement relationships in charitable sectors. Desjardins Group represents cooperative governance models with Quebec-centric membership bases. Industrial Alliance and Empire Life sit within mid-market commercial segments with flexible product architectures.
| Leading Market Players |
|---|
| Desjardins Group |
| Green Shield Canada |
| Manulife Financial Corporation |
| Empire Life |
| Beneva |
| Sun Life Financial Inc. |
| Industrial Alliance (iA Financial Group) |
| Equitable Life Insurance Company of Canada |
| Canada Life Assurance Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap insurers with regional broker networks anchor pricing discipline through selective underwriting capacity and captive distribution control, compressing margin pressure from direct-to-consumer digital entrants while maintaining premium integrity in employer-sponsored segments.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes employer-sponsored group plans from individual critical illness policies. Premium-mid-economy pricing differentiation separates comprehensive drug-dental-vision packages from hospital-only supplements. Cost compression in individual segments is intensifying because algorithmic underwriting reduces acquisition friction. Small business purchasers show highest price sensitivity, while technology sector corporations prioritize benefit breadth over premium minimization.
Supply Chain Analysis
Direct-to-employer channels handle enterprise group demand, while advisor-mediated distribution serves individual policyholders. Claims administration draws from domestic technology vendors and offshore business process outsourcing in India and the Philippines. Pharmacy benefit management hinges on therapeutic value tiering and real-time adjudication platforms. Single-source vulnerability concentrates in legacy core system vendors serving multiple national carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Provincial pharmacare integration timelines create geographic-arbitrage opportunities, with Ontario and British Columbia's slower public expansion preserving larger private addressable markets than Quebec's accelerated single-payer pharmaceutical coverage.
For Market Incumbents: Hedge against single-payer crowding by deepening paramedical service bundling and mental health riders that provincial plans exclude. Vertical integration into pharmacy benefit management secures formulary control as Health Canada's Patented Medicine Prices Review Board reforms compress drug reimbursement margins.
For New Entrants and Emerging Players: Digital comparison platforms offer lowest-friction customer acquisition among younger demographics in British Columbia and Ontario. Atlantic Canada's underpenetrated critical illness market presents expansion opportunity through simplified-issue products targeting self-employed professionals lacking employer-sponsored access.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with concentrated broker relationships and legacy system dependencies. Long-term viability over the projection horizon favors carriers with proprietary digital health infrastructure and pharmacy benefit manager partnerships. Monitor Health Canada digital health guidance implementation as inflection indicator for telehealth reimbursement expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Benefit Manager Partnership | Secures formulary tier placement and outcomes-based contracting leverage for Ontario group administrators. |
| Telehealth Platform Integration | Enables virtual care reimbursement under Health Canada's new digital health guidance frameworks. |
| Paramedical Service Bundling | Differentiates small group offerings where Sun Life currently dominates with wellness-disability combinations. |
| Critical Illness Product Simplification | Captures Atlantic Canada expansion opportunity through algorithmic underwriting replacing face-to-face interviews. |
| Provincial Regulatory Compliance Investment | Reduces overhead multiplication from thirteen divergent insurance regulator approval timelines. |
Study Parameters
Bottom-up employer group modeling reconciled against top-down premium volume tracking forms the analytical core. Primary interviews with benefits administrators, insurance broker principals, pharmacy benefit managers, and provincial regulator officials combined with secondary validation from OSFI solvency filings, CLHIA industry reports, and Health Canada drug pricing databases. Triangulation across these sources ensures coverage scope accuracy and premium flow attribution.
Input-output matrices map policy type, coverage scope, customer segment, and payment model dimensions across the projection horizon. CAGRs derive from experience-rated renewal patterns and demographic-adjusted uptake modeling. Forecast inputs incorporate provincial pharmacare expansion timelines, technology sector employment density shifts, and digital platform adoption curves.
Revisions become necessary when provincial drug coverage expansions accelerate beyond modeled timelines or when Health Canada regulatory guidance shifts reimbursement frameworks materially. Forecasts reflect assumptions about single-payer erosion rates and employer-sponsored participation stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Cyber Liability Insurance Market
Insurance
Disability Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Term Insurance Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Bancassurance Market
Insurance
Travel Insurance Market
Insurance
Takaful Market
Insurance
India Property & Casualty Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Agriculture Insurance Market