
 United States Dental Insurance Market | 2026-2036
United States Dental Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
United States Dental Insurance Market Analytics
Broker and agent distribution channels are reshaping how dental insurance reaches consumers in the United States. Delta Dental leverages its state-level license network to sustain dominant market presence across employer-sponsored segments. Guardian Direct competes through direct-to-consumer digital platforms that bypass traditional intermediaries. Anthem Blue Cross Blue Shield anchors its position via integrated medical-dental bundles sold through large employer channels.
Dental insurance constitutes a specialized health coverage product designed to offset costs of preventive care, restorative procedures, and orthodontic treatment through risk-pooled premium structures. Policies typically specify annual maximum benefits, waiting periods for major services, and coinsurance ratios calibrated by procedure category. Employer-sponsored group plans command the largest premium pool, while individual direct-purchase coverage represents the fastest-growing enrollment channel as gig-economy workers seek portable benefits. Orthodontic coverage attracts disproportionate margin concentration due to higher premium pricing and selective enrollment patterns among families with adolescent dependents.
The Affordable Care Act, state insurance commissioners, and ERISA fiduciary standards collectively govern product design, rate review, and employer plan administration across the United States. ACA pediatric dental essential health benefit requirements shape minimum coverage floors, while state regulators control premium rate approvals and network adequacy standards. Stakeholders must monitor state-level Medicaid expansion dynamics and Medicare Advantage dental carve-in trends that redraw competitive boundaries between public and private coverage architectures.
Market Dynamics
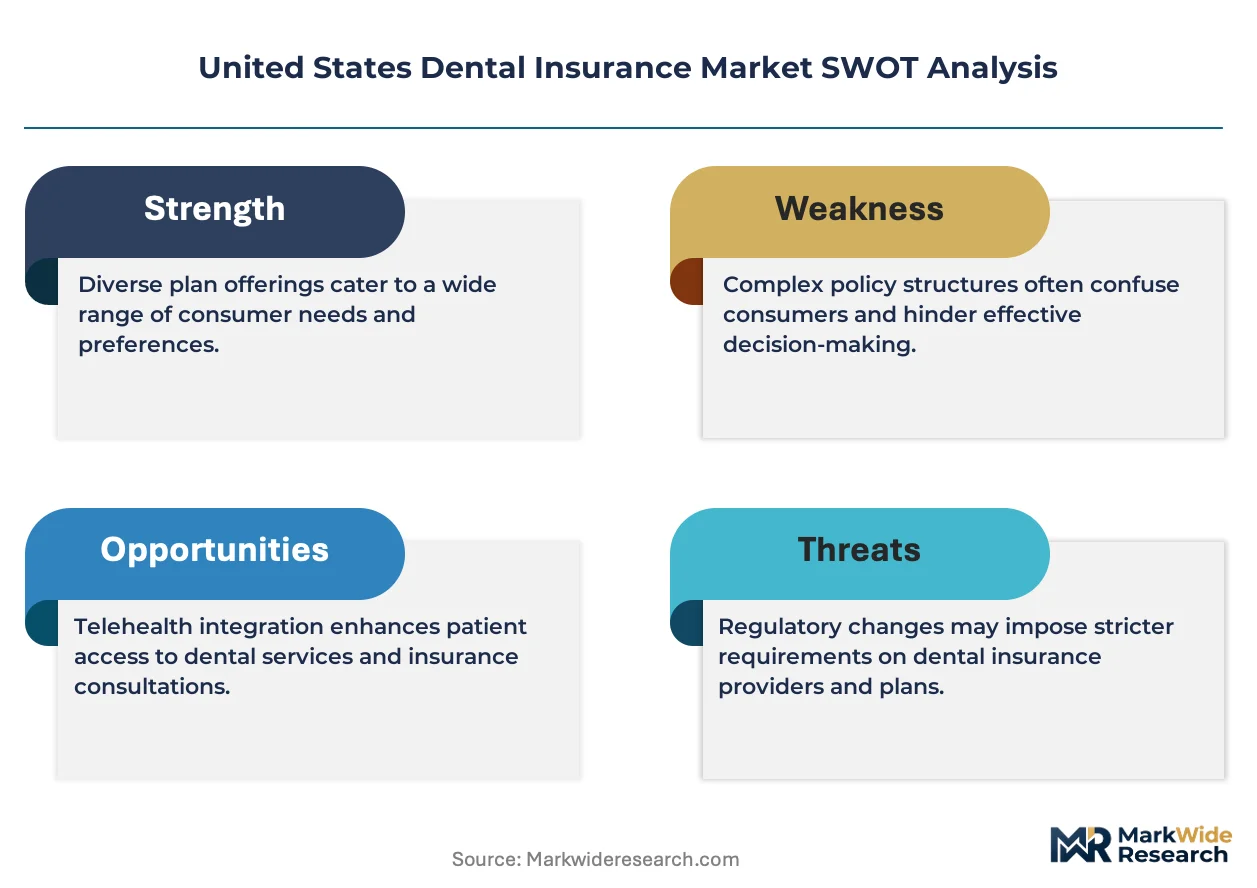
The Affordable Care Act's pediatric dental essential health benefit mandate is compressing product design cycles while employer-sponsored group plans absorb working-age adults into risk pools faster than individual channels can scale.
Growth Catalysts
- ACA Pediatric Mandate:The essential health benefit requirement for dental coverage up to age 19 establishes coverage floors that standardize minimum benefits across state markets, expanding the addressable population for carriers.
- Gig-Economy Workforce Expansion:Platform workers without traditional employer access are driving direct-to-consumer enrollment growth as portable benefits gain priority among independent contractors.
- Orthodontic Procedure Demand:Adolescent-dependent families are selecting plans with higher premium pricing for orthodontic riders, concentrating margin in family-tier products.
Market Restraints
- State Rate Review Friction:Insurance commissioners in high-demand states impose prolonged premium approval timelines that delay product launches and compress pricing flexibility.
- Network Adequacy Requirements:State-level standards for provider-to-enrollee ratios force carriers to maintain expensive broad networks in rural geographies with sparse dental infrastructure.
- Annual Maximum Benefit Caps:Policy structures limiting yearly payouts on major restorative procedures create coverage gaps that push substantial cost burden back to enrollees.
Strategic Opportunities
- Medicare Advantage Carve-In Expansion:The integration of dental benefits into MA plans creates a new enrollment channel as seniors age out of employer coverage without standalone dental options.
- Medicaid Expansion Dynamics:State-level decisions on adult dental benefit inclusion in Medicaid programs are redrawing competitive boundaries between public and private coverage architectures.
- Telehealth Diagnostic Integration:Remote oral health screening technologies are converging with traditional insurance workflows to enable preventive care cost reduction and earlier intervention.
Industry Challenges
- Actuarial Talent Scarcity:Specialized pricing expertise for dental-specific morbidity patterns remains concentrated among legacy carriers, constraining new market entrants.
- Legacy System Integration:Core administrative platforms require substantial capital expenditure to accommodate real-time eligibility verification and digital claims processing demanded by employer clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Dental Insurance Market |
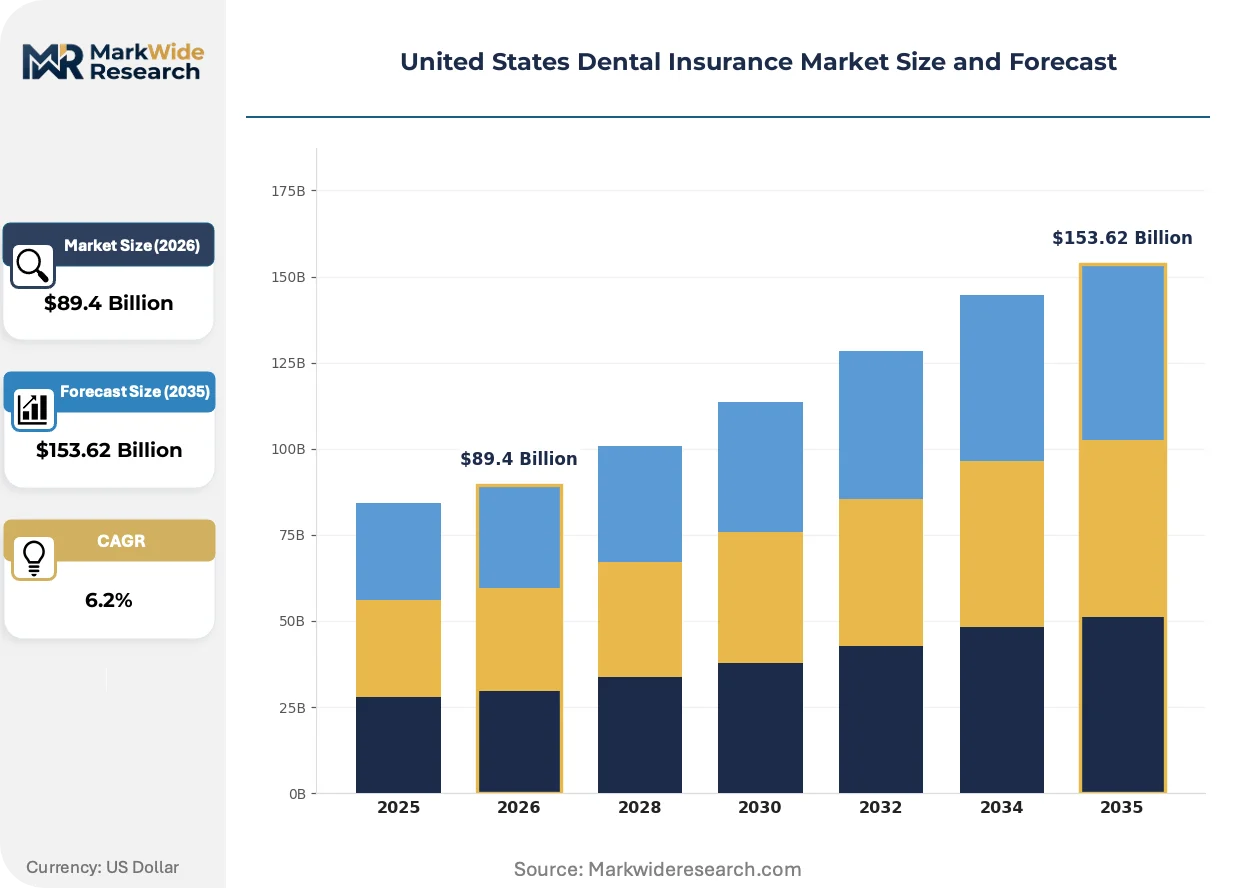
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $153.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Preventive, Basic, Major, Orthodontic Plan Structure: Individual, Family, Group, Employer-Sponsored Benefit Level: High, Medium, Low, Catastrophic Distribution Channel: Online, Agent, Direct, Brokers |
| Companies Covered | Guardian Direct, Anthem Blue Cross Blue Shield, Delta Dental, Spirit Dental, Denali Dental, DentaQuest, Ameritas, Physicians Mutual, MetLife, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Dental Insurance Market Evolving Landscape
Digital distribution infrastructure is restructuring how dental insurance reaches enrollees, with platform-based enrollment displacing traditional broker intermediaries in the individual market segment.
Teledentistry platforms are virtualizing the initial patient-carrier interaction, replacing in-person screening requirements with asynchronous photo-based assessments. Individual direct-purchase enrollees are adopting these tools at accelerating rates, particularly in states with limited rural provider density. This virtualization is compressing the time between quote and policy activation while reducing carrier acquisition costs.
The ACA's essential health benefit framework continues to reshape minimum coverage standards, with state insurance commissioners interpreting pediatric dental mandates through varying regulatory lenses. Employer-sponsored plans face heightened compliance scrutiny as HHS audits verify that dependent coverage meets federal minimums. Large-group administrators in California and Texas are responding by unbundling pediatric riders to isolate regulatory exposure.
Broker channel displacement is accelerating as gig-economy workers seek enrollment pathways without intermediary commissions. Direct-to-consumer platforms are capturing these buyers through simplified digital underwriting that eliminates paper-based health questionnaires. This behavioral shift concentrates in Florida and other states with high independent contractor populations, where traditional group eligibility verification no longer applies.
United States Dental Insurance Market Segmentation
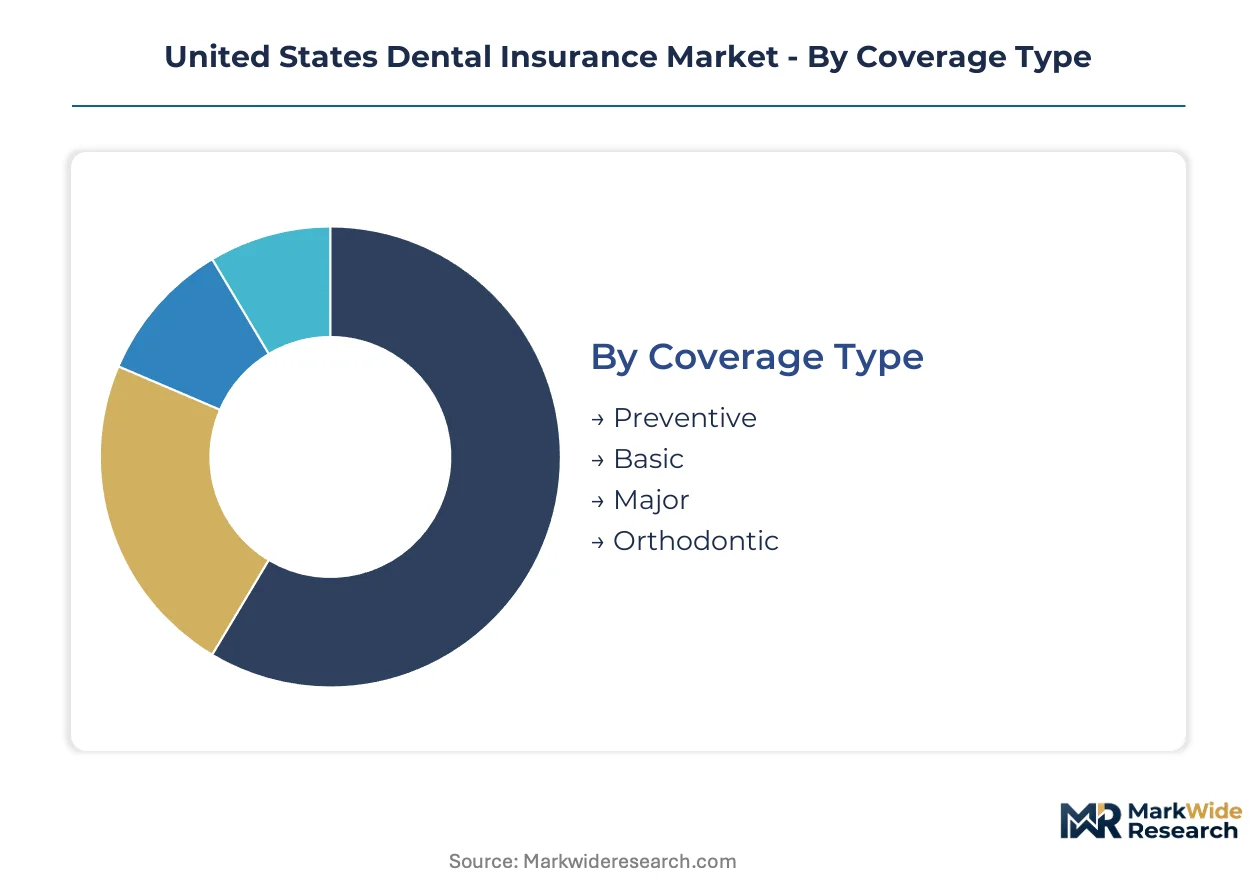
Dental insurance segmentation reveals how carriers calibrate risk pools, pricing tiers, and distribution reach across divergent customer needs. Each dimension—coverage depth, plan structure, benefit generosity, and sales channel—creates distinct competitive battlegrounds with specialized margin profiles and regulatory exposures.
Coverage Type:
Cost tier differentiation shapes carrier profitability and member retention across the four standard coverage categories.
- Preventive:Routine cleanings, exams, and X-rays form the foundation tier with near-universal enrollment and minimal member cost-sharing. Employer-sponsored plans in California and Texas absorb this coverage as a baseline expectation, though ACA pediatric mandates now standardize these benefits across individual markets.
- Orthodontic:Braces, aligners, and related appliances command premium pricing and selective enrollment concentrated among families with adolescent dependents. Florida's large household formations sustain disproportionate demand for this rider, generating carrier margin concentration despite longer utilization tails.
- Basic:Fillings and simple extractions occupy the middle utilization band with moderate coinsurance structures.
- Major:Crowns, bridges, and dentures trigger annual maximum benefit caps that push substantial cost burden to enrollees.
Preventive coverage commands the established base. The steepest expansion runs through Orthodontic riders as adolescent-dependent families prioritize comprehensive family-tier products.
Plan Structure:
Customer type determines risk pool composition, administrative complexity, and portability characteristics across enrollment modalities.
- Employer-Sponsored:Large-group plans aggregate working-age adults into stable risk pools with streamlined underwriting and lower per-member acquisition costs. Texas and California employer bases sustain the deepest premium pools, though gig-economy displacement is fragmenting traditional eligibility verification.
- Individual:Direct-purchase coverage serves independent contractors and early retirees outside group eligibility, requiring simplified digital underwriting and portable benefit designs. Florida's high independent contractor density accelerates enrollment through direct-to-consumer platforms that bypass broker commissions.
- Family:Multi-dependent tiers bundle adult and pediatric coverage with orthodontic riders that concentrate margin.
- Group:Small-employer plans face adverse selection pressures and higher administrative load per member.
Employer-Sponsored structures anchor premium volume. The sharpest enrollment gains are appearing in Individual channels as platform workers seek benefits decoupled from traditional employment.
Benefit Level:
Generosity gradients segment buyers by price sensitivity, risk tolerance, and expected utilization intensity.
- High:Generous annual maximums, low coinsurance, and minimal waiting periods attract utilization-heavy enrollees willing to pay premium rates. Large-group administrators in California deploy these tiers to compete for talent in tight labor markets.
- Catastrophic:Minimal premiums with high deductibles and restricted provider networks serve price-sensitive buyers seeking emergency protection only. Rural geographies with sparse dental infrastructure see concentrated uptake where network adequacy requirements already constrain carrier flexibility.
- Medium:Balanced cost-sharing structures dominate employer-sponsored selections.
- Low:Stripped-down benefits with tight annual caps appeal to budget-constrained individual purchasers.
Medium benefit levels capture the broadest enrollment. Catastrophic designs are climbing fastest among gig-economy entrants prioritizing minimal premium outlay over comprehensive protection.
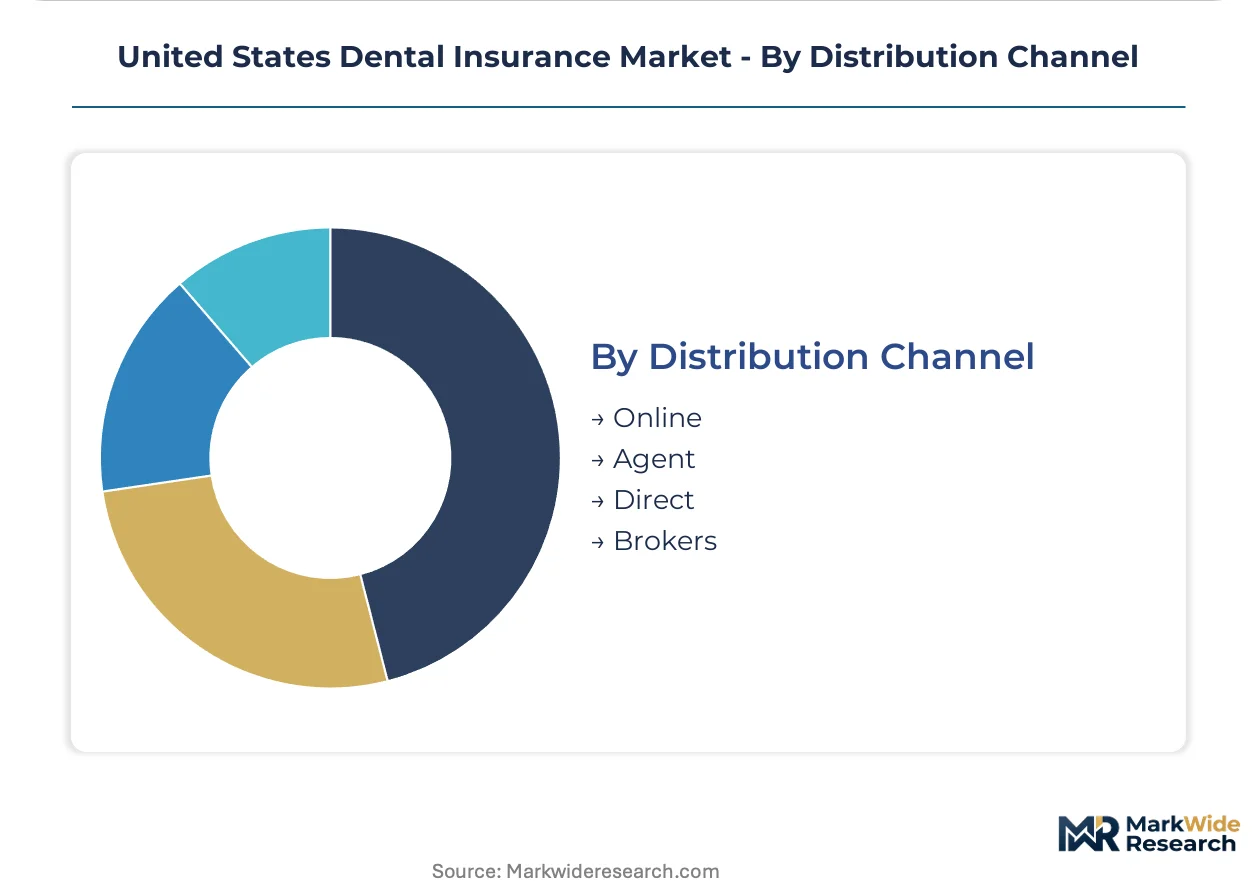
Distribution Channel:
Sales pathway selection reflects buyer demographics, regulatory exposure, and carrier cost-to-acquire economics.
- Online:Platform-based enrollment displaces traditional intermediaries through real-time quoting and automated underwriting. Direct-to-consumer specialists leverage these channels in Florida and other high-contractor-density states where group eligibility verification no longer applies.
- Brokers:Intermediary networks sustain dominant share in employer-sponsored segments where plan customization and compliance navigation justify commission structures. Delta Dental's state-level license network exemplifies this channel's persistence.
- Agent:Captive and independent agents concentrate in rural markets requiring localized relationship selling.
- Direct:Carrier-owned sales forces target large-group accounts with complex benefit administration needs.
Broker networks retain the deepest employer-sponsored penetration. Online platforms are gaining share fastest among individual purchasers seeking commission-free enrollment pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in California and Texas employer markets, while Florida's individual channel growth runs at steeper enrollment velocity despite thinner margins per member.
California
Large-group administrators in California deploy high-benefit tiers to compete for talent in tight labor markets. HHS audits verify that dependent coverage meets federal ACA pediatric minimums. The Los Angeles-San Francisco corridor sustains the deepest employer-sponsored premium pools.
Texas
Texas employer bases absorb working-age adults into stable risk pools with streamlined underwriting. State insurance commissioners impose network adequacy standards that force broad provider networks. Dallas-Fort Worth and Houston metropolitan clusters anchor carrier distribution infrastructure.
Florida
Florida's high independent contractor density accelerates direct-to-consumer enrollment through commission-free digital platforms. ACA pediatric dental essential health benefit mandates standardize minimum coverage floors across individual markets. Miami and Tampa Bay metro areas concentrate gig-economy platform worker demand.
Northeast Corridor
Legacy carrier concentration in the Northeast creates pricing discipline through actuarial talent scarcity. ERISA fiduciary standards govern employer plan administration with heightened compliance scrutiny. Greater Boston and New York Metro sustain specialized orthodontic rider demand among affluent households.
Midwest
Manufacturing employer bases in the Midwest maintain traditional group-sponsored structures with lower administrative load per member. State Medicaid expansion decisions redraw competitive boundaries between public and private coverage. Chicago and Detroit industrial corridors sustain stable enrollment despite slower premium growth.
United States Dental Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower risk pools. The United States dental insurance market structures around three tiers: dominant state-licensed networks, direct-to-consumer digital platforms, and integrated medical-dental bundles. Strategic archetypes include employer-channel incumbents leveraging license density, individual-market disruptors bypassing broker commissions, and health system affiliates cross-selling medical membership. Competitive moves concentrate on Medicare Advantage carve-in expansion and telehealth diagnostic integration.
Among the dominant network tier, Delta Dental exemplifies state-level license leverage across employer-sponsored segments. Guardian Direct occupies the direct-to-consumer vector with digital-first enrollment pathways. Anthem Blue Cross Blue Shield anchors integrated medical-dental positioning through large employer channels. These three represent the primary competitive archetypes reshaping distribution economics.
| Leading Market Players |
|---|
| Guardian Direct |
| Anthem Blue Cross Blue Shield |
| Delta Dental |
| Spirit Dental |
| Denali Dental |
| DentaQuest |
| Ameritas |
| Physicians Mutual |
| MetLife |
| Others |
Value Network & Pricing Analysis
State rate review friction determines both tiered pricing spreads and supply chain configuration in dental insurance. Prolonged premium approval timelines in high-demand states compress pricing flexibility while forcing carriers to maintain expensive broad networks in rural geographies with sparse dental infrastructure.
Pricing Analysis
The customization-premium spread separates employer-sponsored group plans from individual direct-purchase coverage. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by annual maximum benefit caps and orthodontic rider inclusion. Cost compression in catastrophic tiers intensifies as gig-economy workers prioritize minimal premium outlay over comprehensive protection. Individual purchasers exhibit highest price sensitivity, while large-group administrators in tight labor markets absorb premium increases with minimal elasticity.
Supply Chain Analysis
Export-control regime angles are less relevant here; instead, network adequacy requirements function as regulatory chokepoints limiting provider flow. Supply concentrates in California, Texas, and Florida where large employer bases and aging populations sustain premium growth. Carrier networks draw from independent dental practices, dental service organizations, and health system-affiliated clinics. Single-source vulnerability emerges in rural geographies where sparse dental infrastructure forces expensive broad network maintenance. Distribution runs through broker intermediaries in employer segments and direct-to-consumer platforms in individual markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized actuarial talent for dental-specific morbidity patterns remains concentrated among legacy carriers, constraining new entrants and creating acquisition premiums for scarce pricing expertise.
For Market Incumbents: Harden network adequacy positions in rural geographies where state-level provider-to-enrollee ratios create defensive moats. Invest in legacy system modernization to accommodate real-time eligibility verification demanded by employer clients. Consolidate actuarial talent pools through targeted acquisition of specialized pricing teams as emerging digital-first carriers attempt to bypass traditional underwriting infrastructure. For New Entrants and Emerging Players: Build out direct-to-consumer digital platforms targeting Florida and other high independent contractor density states where group eligibility verification no longer applies. Capture Medicare Advantage carve-in expansion as seniors age out of employer coverage without standalone dental options. Prioritize teledentistry integration as the primary go-to-market differentiator against broker-dependent incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with captive distribution infrastructure over component specialists with narrower risk pools. Long-term viability hinges on telehealth diagnostic integration capabilities and state-level license density. Target acquisition archetypes include direct-to-consumer digital platforms with proven unit economics and Medicare Advantage carve-in capabilities. Watch Medicaid expansion dynamics as the inflection signal that redraws competitive boundaries between public and private coverage architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Diagnostic Integration | Remote oral health screening converges with insurance workflows to enable preventive care cost reduction. |
| Medicare Advantage Carve-In Expansion | Integration of dental benefits into MA plans creates new enrollment channel for aging populations. |
| Direct-to-Consumer Platform Launch | Commission-free digital enrollment captures gig-economy workers outside traditional group eligibility. |
| Legacy System Modernization | Real-time eligibility verification and digital claims processing meet employer client demands. |
| State License Network Consolidation | License density across employer-sponsored segments sustains dominant market presence against disruptors. |
Research Methodology
Operator-level perspectives from carrier actuarial directors, state insurance commissioner staff, employer benefits administrators, and dental service organization executives anchored the qualitative base. Primary interviews combined with secondary validation from NAIC rate filing databases, CMS Medicare Advantage enrollment reports, HHS essential health benefit audit documentation, and employer plan sponsor SEC disclosures. Bottom-up enrollment data triangulated against top-down premium pool estimates across the analysis window.
Scenario-bracketing framed the analytical approach with sensitivity testing around Medicaid expansion trajectories and Medicare Advantage dental carve-in penetration. Segmentation dimensions modeled include coverage type, plan structure, benefit generosity tier, and distribution channel complexity. CAGRs derived from enrollment velocity trends, premium pricing power indices, and actuarial loss ratio projections. Industry-specific forecast inputs incorporated state-level network adequacy standard variations and pediatric dental essential health benefit compliance cost differentials.
Sensitivities concentrate around state Medicaid expansion decisions and Medicare Advantage dental benefit integration pace. Forecasts reflect assumptions on regulatory stability and employer-sponsored plan persistence rates. Material shifts in ACA essential health benefit interpretations or ERISA fiduciary standard enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Marine Freight Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Commercial Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
Digital Monetary Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Earthquake Insurance Market
Insurance
France Property and Casualty Insurance Market
Insurance
Europe EV Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Estonia Property and Casualty Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Umbrella Insurance Market
Insurance
Engineering Insurance Market
Insurance
Workers Compensation Insurance Market