
 Car Insurance Market | 2026-2036
Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Car Insurance Market Analysis
EU Green Deal vehicle-emission benchmarks are restructuring auto insurance risk pools as insurers factor carbon-adjusted repair costs and EV battery replacement values into underwriting models. State Farm leverages its captive agency network to sustain dominant market presence across rural and suburban territories. Progressive anchors its competitive position through direct-to-consumer digital channels that reduce acquisition costs. Allstate differentiates via telematics-driven usage-based programs that reward low-mileage drivers with dynamic premium adjustments.
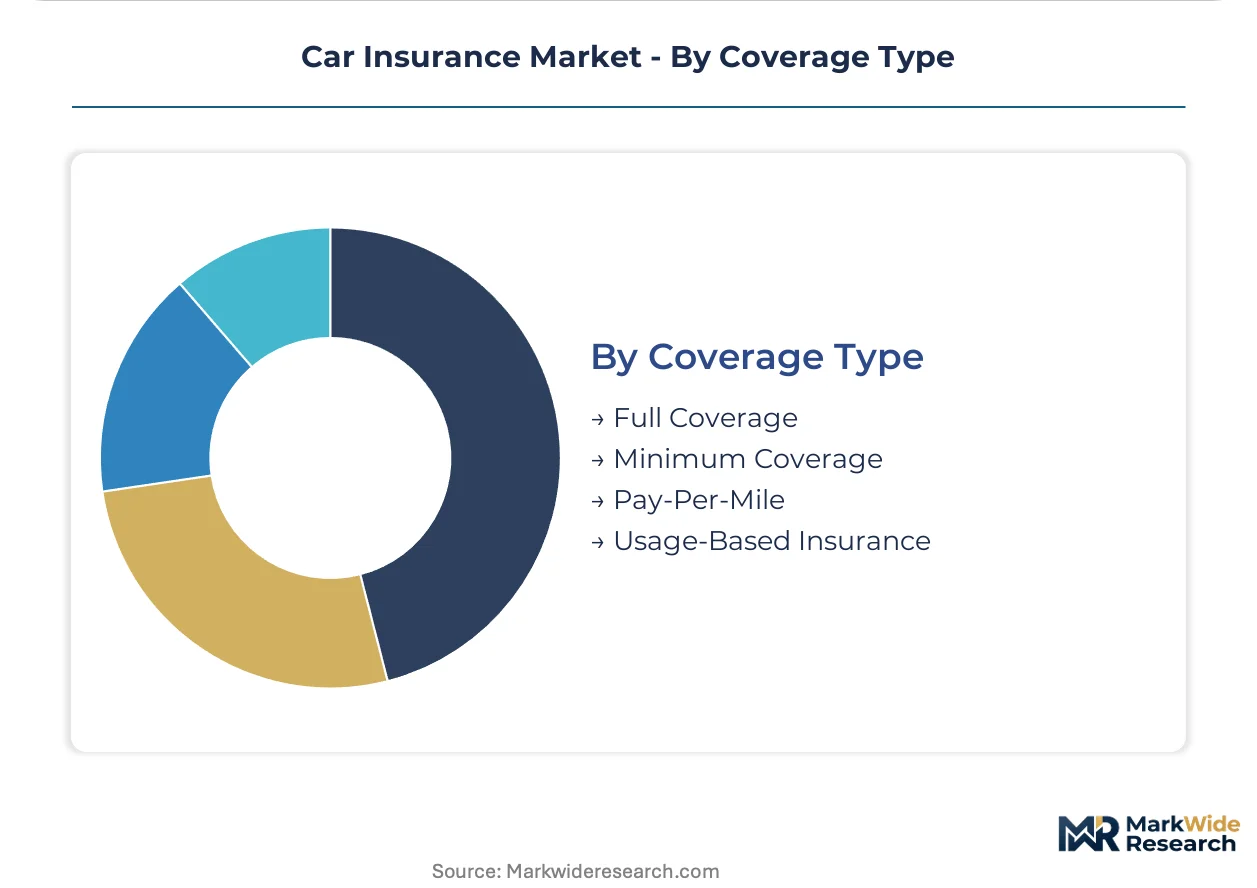
Car insurance constitutes a risk-transfer contract indemnifying vehicle owners against financial loss from collision, theft, liability, or bodily injury, with premiums calibrated through actuarial analysis of driving history, vehicle attributes, geographic exposure, and credit-based insurance scores. The product type dimension spans liability coverage, collision coverage, comprehensive coverage, and personal injury protection, with liability coverage occupying the largest premium share due to mandatory minimum requirements in most jurisdictions. Usage-based insurance within the coverage type category represents the fastest-growing structural segment as connected-car data streams enable real-time risk pricing and behavioral feedback loops.
Federal and state regulators shape market architecture through the National Association of Insurance Commissioners model laws, state-level mandatory coverage statutes, and the Consumer Financial Protection Bureau oversight of premium financing practices. The National Highway Traffic Safety Administration crash-test protocols indirectly influence repair-cost assumptions embedded in collision coverage pricing. Stakeholders must monitor the interplay between autonomous-vehicle liability frameworks and traditional fault-based underwriting models as driving automation shifts risk allocation from individual operators to manufacturers and software providers.
Market Dynamics
Telematics-enabled usage-based insurance is absorbing traditional actuarial models as real-time driving data displaces static risk proxies, compressing pricing cycles from annual to dynamic intervals.
Growth Catalysts
- Ride-sharing commercial mandates:Platform drivers in the United States face state-level coverage requirements that expand addressable premium pools beyond personal auto policies.
- EU Green Deal integration:Carbon-adjusted repair cost frameworks are embedding environmental liability into underwriting models, creating new coverage categories for EV battery replacement.
- Connected-vehicle data streams:OEM-installed telematics hardware is enabling behavioral feedback loops that reduce loss ratios for early-adopting carriers.
Market Restraints
- Semiconductor supply concentration:Taiwan-dominant chip fabrication creates repair cost volatility as ADAS-equipped vehicles require specialized component sourcing.
- Lithium-ion battery replacement economics:EV powertrain damage claims absorb disproportionate reserves due to limited secondary market availability and technician certification gaps.
- State-level regulatory fragmentation:Non-uniform mandatory minimum statutes across fifty US jurisdictions inflate compliance overhead for national carriers.
Strategic Opportunities
- Autonomous-vehicle liability frameworks:Shifting fault allocation from operators to manufacturers creates product liability adjacency opportunities for traditional auto underwriters.
- Embedded insurance distribution:Point-of-sale integration with automotive OEMs and digital retail platforms captures policyholders at vehicle transaction moments.
- India's expanding vehicle fleet:Regulatory push for mandatory third-party coverage in underpenetrated urban markets opens greenfield premium growth corridors.
Industry Challenges
- Telematics data scientist scarcity:Actuarial departments lack sufficient talent to operationalize real-time pricing algorithms at scale.
- Legacy policy administration system integration:Core platform modernization demands compete with innovation budgets, delaying dynamic rating engine deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Insurance Market |
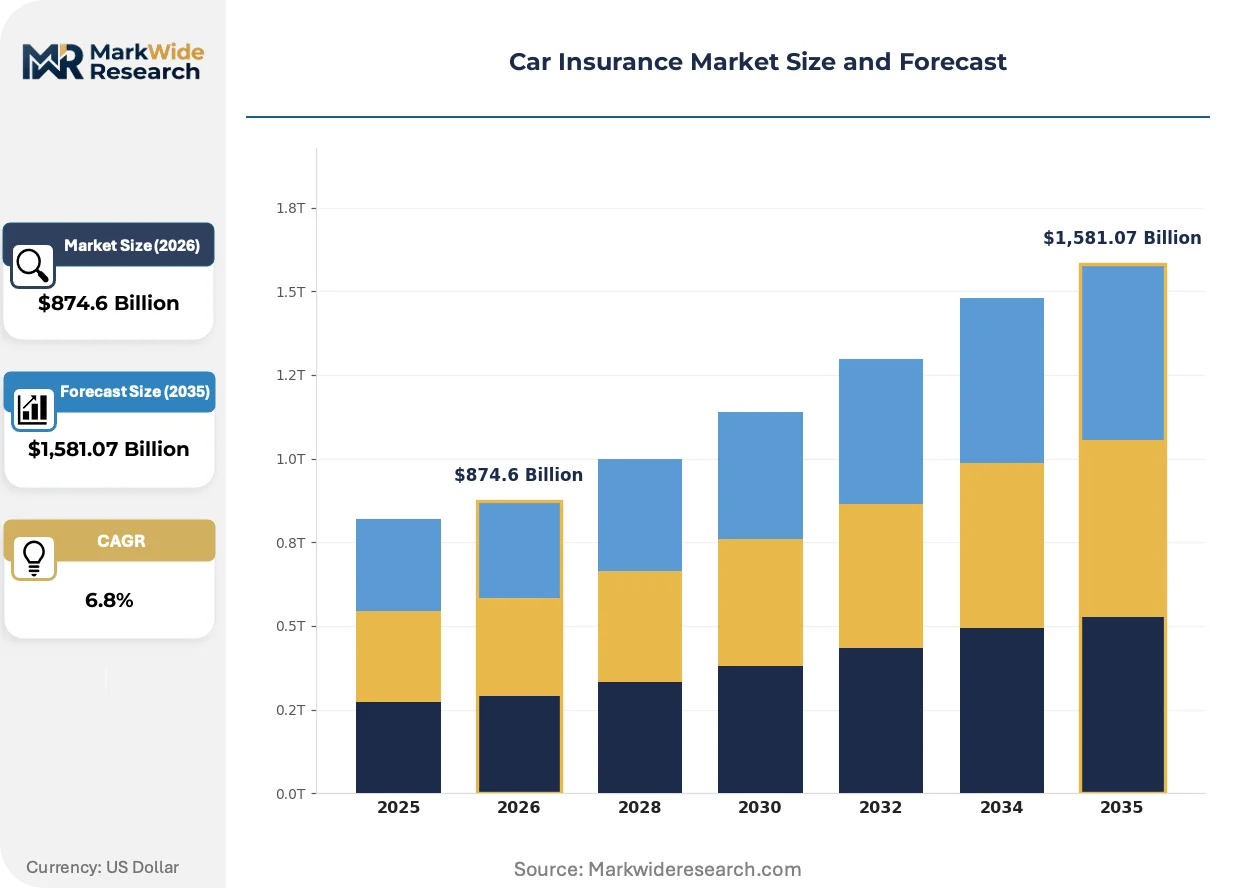
| Market Size in 2026 | $874.6 Billion |
| Market Size in 2035 | $1,581.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liability Coverage, Collision Coverage, Comprehensive Coverage, Personal Injury Protection End User: Individual Policyholders, Fleet Owners, Commercial Drivers, Ride-Sharing Services Distribution Channel: Online Brokers, Direct Agents, Insurance Agencies, Comparison Websites Coverage Type: Full Coverage, Minimum Coverage, Pay-Per-Mile, Usage-Based Insurance |
| Companies Covered | State Farm, Progressive, Geico, Allstate, USAA, Liberty Mutual, Farmers, Travelers, Nationwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Insurance Market Emerging Trajectories
Data-driven risk assessment protocols are displacing static demographic proxies across the value chain, compressing the interval between behavior capture and premium adjustment from annual cycles to continuous recalibration.
Artificial intelligence is absorbing claims processing workflows as computer vision systems automate damage assessment from smartphone-submitted imagery. Mid-market carriers in Germany and the United States are deploying these tools to compress cycle times from days to hours. The structural consequence is workforce displacement in traditional adjuster functions and margin compression for carriers slow to automate.
The EU AI Act's risk-based classification framework is mandating algorithmic transparency for automated underwriting decisions affecting consumer access to coverage. European carriers must now maintain explainability documentation for telematics-derived pricing models. Personal lines segments in France and the Netherlands face the steepest compliance curves as regulators scrutinize proxy discrimination in behavioral scoring.
Subscription-based mobility coverage is displacing traditional annual policies as fleet-operating corporations and multi-vehicle households demand usage-calibrated protection. German automotive OEMs and US-based fleet management platforms are piloting embedded per-mile products that unbundle insurance from vehicle ownership. This pattern concentrates in urban corridors where vehicle utilization rates vary significantly across monthly intervals.
Car Insurance Market Segmentation
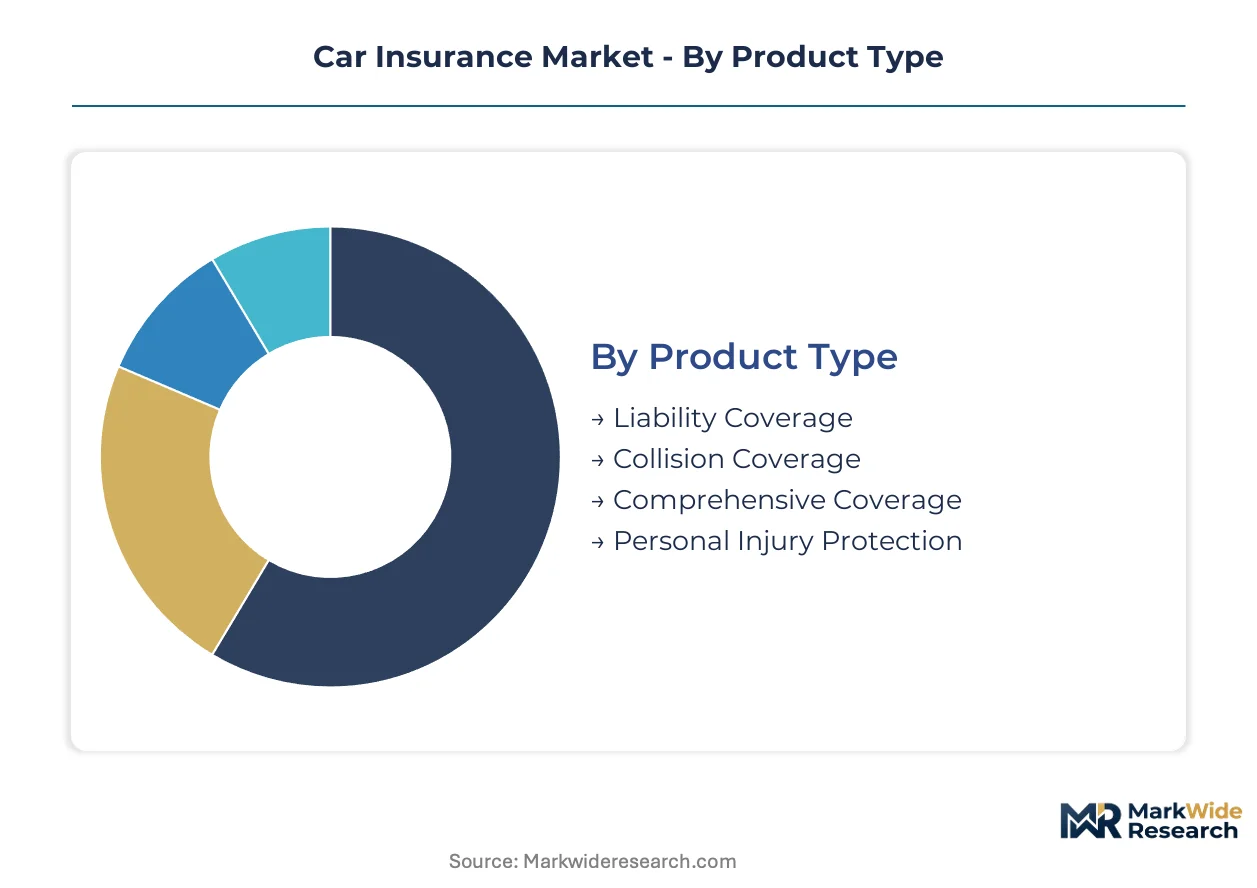
Car insurance segmentation reveals how risk transfer mechanisms adapt to divergent liability exposures, vehicle utilization patterns, and distribution economics. Each dimension carries distinct regulatory overlays and data requirements that reshape carrier operating models.
Product Type:
State-level mandatory minimum statutes and NHTSA safety protocols create tiered certification burdens across coverage categories, with liability products facing the most uniform compliance requirements.
- Liability Coverage:Mandated financial responsibility frameworks in most US jurisdictions require bodily injury and property damage protection. Demand concentrates among cost-sensitive individual policyholders in states with elevated minimum thresholds. NHTSA crash-test protocols indirectly influence loss cost assumptions embedded in pricing.
- Collision Coverage:Physical damage protection for at-fault accidents carries higher actuarial complexity due to semiconductor-dependent repair costs. Fleet owners in the United States absorb disproportionate premium volume as commercial utilization accelerates wear-related claims.
- Comprehensive Coverage:Non-collision perils including theft, vandalism, and weather damage. EU Green Deal carbon-adjusted repair frameworks are embedding environmental liability into underwriting models for this segment.
- Personal Injury Protection:No-fault medical expense coverage required in specific US states. Regulatory fragmentation creates compliance overhead for national carriers operating across mandatory and optional jurisdictions.
Leading the category by volume: Liability Coverage. Growing fastest: Collision Coverage as ADAS-equipped vehicle repair costs escalate.
End User:
Risk profiles diverge sharply across user types, with commercial utilization patterns demanding specialized telematics integration and loss control protocols.
- Individual Policyholders:Standard personal auto coverage for private vehicle owners. United States households sustain baseline premium volume through state-mandatory purchase requirements.
- Fleet Owners:Multi-vehicle commercial operations require centralized policy administration and driver monitoring systems. Germany and the United States pilot embedded per-mile products that unbundle insurance from ownership.
- Commercial Drivers:Professional operators face elevated liability exposure and hours-of-service regulatory scrutiny. Federal Motor Carrier Safety Administration compliance overlays shape coverage structure.
- Ride-Sharing Services:Platform drivers require specialized commercial coverage for period-based liability exposure. State-level coverage mandates in the United States expand addressable premium pools beyond personal auto policies.
Individual Policyholders anchor premium volume. Ride-Sharing Services expand most quickly as platform penetration deepens.
Distribution Channel:
Acquisition cost structures and customer lifetime value economics vary dramatically across channel architecture, with digital intermediaries compressing traditional agency economics.
- Online Brokers:Digital aggregation platforms enabling multi-carrier quote comparison. Progressive anchors competitive position through direct-to-consumer channels that reduce acquisition costs.
- Direct Agents:Captive or exclusive representative networks. State Farm leverages this structure to sustain dominant presence across rural and suburban United States territories.
- Insurance Agencies:Independent intermediaries representing multiple carriers. Legacy policy administration system integration demands compete with innovation budgets at these firms.
- Comparison Websites:Price-focused aggregators with minimal advisory function. European carriers face EU AI Act algorithmic transparency requirements for automated quoting decisions.
Insurance Agencies retain largest policy count. Online Brokers gain share fastest as smartphone-native consumers mature.
Coverage Type:
Data intensity and pricing granularity separate traditional annual contracts from emerging usage-calibrated alternatives, with telematics infrastructure determining competitive viability.
- Full Coverage:Combined liability, collision, and comprehensive protection. Standard for financed vehicles and risk-averse United States policyholders.
- Minimum Coverage:State-mandated liability limits only. Price-sensitive segments in jurisdictions with low mandatory thresholds.
- Pay-Per-Mile:Distance-calibrated premiums for low-utilization vehicles. German automotive OEMs pilot embedded products targeting urban corridors with variable monthly usage.
- Usage-Based Insurance:Real-time behavioral pricing through connected-vehicle data streams. Allstate differentiates via telematics-driven programs rewarding low-mileage drivers with dynamic premium adjustments.
Full Coverage dominates premium volume. Usage-Based Insurance climbs fastest as OEM-installed telematics hardware proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive insurance corridor anchors North American actuarial innovation as connected-vehicle data streams reshape underwriting protocols. Premium volume concentrates where state mandates intersect with dense vehicle fleets and technology adoption clusters.
United States
State-level mandatory coverage statutes and NHTSA safety protocols sustain the world's largest addressable premium pool. The National Association of Insurance Commissioners coordinates model laws across fifty jurisdictions while the Consumer Financial Protection Bureau oversees premium financing. Silicon Valley telematics startups and Hartford's insurance legacy cluster compete to operationalize real-time behavioral pricing.
Germany
KBA vehicle certification requirements and EU Green Deal carbon-adjusted repair frameworks are restructuring comprehensive coverage underwriting. The country's automotive OEMs pilot embedded per-mile products through Munich and Stuttgart technology corridors. Allianz and Munich Re anchor reinsurance capacity for telematics-enabled usage-based programs.
China
MIIT connected-vehicle standards and SAMR insurance sector oversight accelerate data-driven risk assessment adoption. Shanghai and Beijing insurance clusters process claims through AI-powered computer vision systems. The country's dual carbon goals are embedding EV battery replacement values into emerging comprehensive coverage categories.
United Kingdom
FCA conduct rules and the Financial Ombudsman Service dispute resolution framework shape personal lines distribution. London's Lloyd's market provides specialty commercial auto capacity for fleet operators and ride-sharing platforms. Manchester and Birmingham digital brokers compress acquisition costs through direct-to-consumer channels.
India
IRDAI mandatory third-party coverage push and RBI premium financing oversight expand underpenetrated urban markets. Mumbai and Delhi-NCR insurance clusters deploy smartphone-based claims submission tools. The country's expanding vehicle fleet opens greenfield growth corridors as regulatory enforcement tightens across state transport departments.
Car Insurance Market Vendor Landscape
The competitive structure tilts toward captive agency networks and direct-to-consumer digital channels as distribution economics fragment market share. Three archetypes dominate: rural-suburban agency-heavy incumbents, digital-native direct writers, and telematics-integrated usage-based specialists. Consolidation pressures intensify as legacy policy administration modernization demands compete with innovation budgets. Strategic moves concentrate on embedded insurance partnerships with automotive OEMs and point-of-sale platform integration.
Among US-based national carriers, State Farm, Progressive, and Allstate anchor distinct competitive positions. State Farm exemplifies the captive agency archetype through exclusive representative networks penetrating rural and suburban territories. Progressive occupies the digital direct-to-consumer vector with reduced acquisition cost structures. Allstate represents telematics-driven differentiation through behavioral feedback programs and dynamic premium adjustments.
| Leading Market Players |
|---|
| State Farm |
| Progressive |
| Geico |
| Allstate |
| USAA |
| Liberty Mutual |
| Farmers |
| Travelers |
| Nationwide |
| Others |
Supply Flow & Price Mechanics
Automotive repair cost indices and semiconductor spot-price volatility cascade through actuarial models into tiered premium structures, compressing margins for carriers slow to operationalize real-time rating engines while rewarding early telematics adopters with loss-ratio advantages.
Pricing Analysis
Usage-calibrated premium anchors displace static annual contracts as OEM-installed telematics hardware enables behavioral feedback loops. Three-tier pricing structure across premium, standard, and economy levels separates telematics-integrated policies from traditional demographic-rated coverage from state-minimum liability products. Cost compression in comprehensive coverage is intensifying because lithium-ion battery replacement claims absorb disproportionate reserves. Price-sensitive individual policyholders in low-mandate US states gravitate toward minimum liability tiers, while fleet operators absorb premium-mid-economy pricing differentiation with less elasticity.
Supply Chain Analysis
Salvage vehicle auctions and certified pre-owned remarketing channels feed secondary parts markets that stabilize collision coverage loss costs. Taiwan, South Korea, and Germany concentrate semiconductor and ADAS component fabrication that repair networks draw from for sensor-equipped vehicle claims. Raw material dependencies center on lithium carbonate, rare earth magnets, and high-strength steel alloys. Single-source vulnerability in Taiwan-dominant chip fabrication creates repair cost volatility when geopolitical friction disrupts component flows. Distribution runs through captive agency networks, direct-to-consumer digital platforms, and embedded OEM point-of-sale partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carriers face a vertical-integration race into telematics data infrastructure and claims automation capabilities, with first-mover advantages accruing to those capturing connected-vehicle streams before OEMs gate access.
For Market Incumbents: Lock in exclusive telematics data partnerships with automotive OEMs before platform intermediaries commoditize behavioral scoring. Consolidate legacy policy administration systems through cloud-native replacements that compress rating-engine deployment cycles. State-level regulatory fragmentation threatens compliance overhead for national carriers operating across fifty US jurisdictions. For New Entrants and Emerging Players: The gap between premium telematics-integrated policies and economy-tier minimum coverage creates white-space for per-mile products targeting urban multi-vehicle households with variable monthly utilization. India's underpenetrated mandatory third-party markets and Germany's embedded per-mile pilot corridors offer the most penetrable geographies. Go-to-market execution should prioritize smartphone-native digital distribution that bypasses captive agency infrastructure. For Investors and Strategic Acquirers: The window for entry favors telematics-enabled usage-based specialists with operationalized real-time pricing algorithms and OEM data partnerships. Long-term viability hinges on carriers proving loss-ratio compression against traditional actuarial models. Watch for autonomous-vehicle liability framework rulings that shift fault allocation from operators to manufacturers as the inflection signal triggering product liability adjacency plays.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership | Exclusive OEM agreements lock in behavioral data streams before platform commoditization. |
| Legacy System Modernization | Cloud-native policy administration compresses dynamic rating engine deployment timelines. |
| Embedded Insurance Integration | Point-of-sale capture at vehicle transaction moments reduces customer acquisition costs. |
| AI Claims Automation | Computer vision damage assessment from smartphone imagery compresses cycle times. |
| Autonomous Liability Framework Positioning | Early product liability adjacency prepares carriers for fault allocation shifts to manufacturers. |
Methodological Framework
SEC 10-K filings, NAIC statutory financial statements, and NHTSA crash-test databases formed the secondary backbone, supplemented by primary interviews with auto insurance actuarial directors, telematics platform engineers, state insurance commissioners, and collision repair shop operators. Bottom-up triangulation across premium volume data and top-down validation through regulatory filing aggregation anchored market sizing.
Bottom-up modeling segmented the market across coverage type, distribution channel, end-user archetype, and vehicle propulsion architecture over the projection horizon. CAGRs derived from historical premium growth trajectories adjusted for telematics penetration curves and EV fleet replacement rates. Forecast inputs incorporated state-level mandatory coverage statute changes and EU Green Deal carbon-adjusted repair cost frameworks.
Inputs from carrier statutory filings and OEM telematics disclosures were available through the study window; gaps in real-time driving behavior datasets introduce uncertainty bands around usage-based insurance adoption curves. Forecasts reflect assumptions regarding regulatory enforcement consistency and semiconductor supply normalization. Material deviation in autonomous-vehicle liability rulings or Taiwan chip fabrication capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Property and Casualty Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Crop Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
France Liability Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Bancassurance Market
Insurance
Auto Extended Warranty Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
UK Travel Insurance Market
Insurance
Crime Insurance Market
Insurance
Jewelry Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
China Property and Casualty Insurance Market