
 Spain Group Health Insurance Market | 2026-2036
Spain Group Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Group Health Insurance Market Insights
Digital health management platforms are consolidating how group health insurance is sold in Spain, embedding telemedicine access and real-time claims tracking into standard corporate contracts. Adeslas leverages its integrated hospital network to sustain competitive positioning in employer-sponsored plans. AXA anchors its Spanish group portfolio through international portability features that serve expatriate-heavy industries. Mapfre differentiates via specialized risk-assessment tools for medium enterprises seeking tailored premium structures.
Spain group health insurance constitutes employer-sponsored medical coverage pooling risk across employee cohorts, typically structured with annual renewable terms, guaranteed issue provisions, and negotiated provider networks serving predetermined geographic catchments. The primary commercial purpose centers on workforce retention, tax-advantaged compensation packaging, and collective bargaining compliance within Spain's dual public-private healthcare architecture. Comprehensive policy types command dominant placement among large corporations seeking full inpatient-outpatient-dental integration, while basic plans attract cost-constrained small businesses navigating Spain's statutory minimum coverage thresholds. Medium enterprises represent the fastest-expanding customer type segment as automated enrollment platforms reduce administrative barriers previously favoring large-group procurement scale.
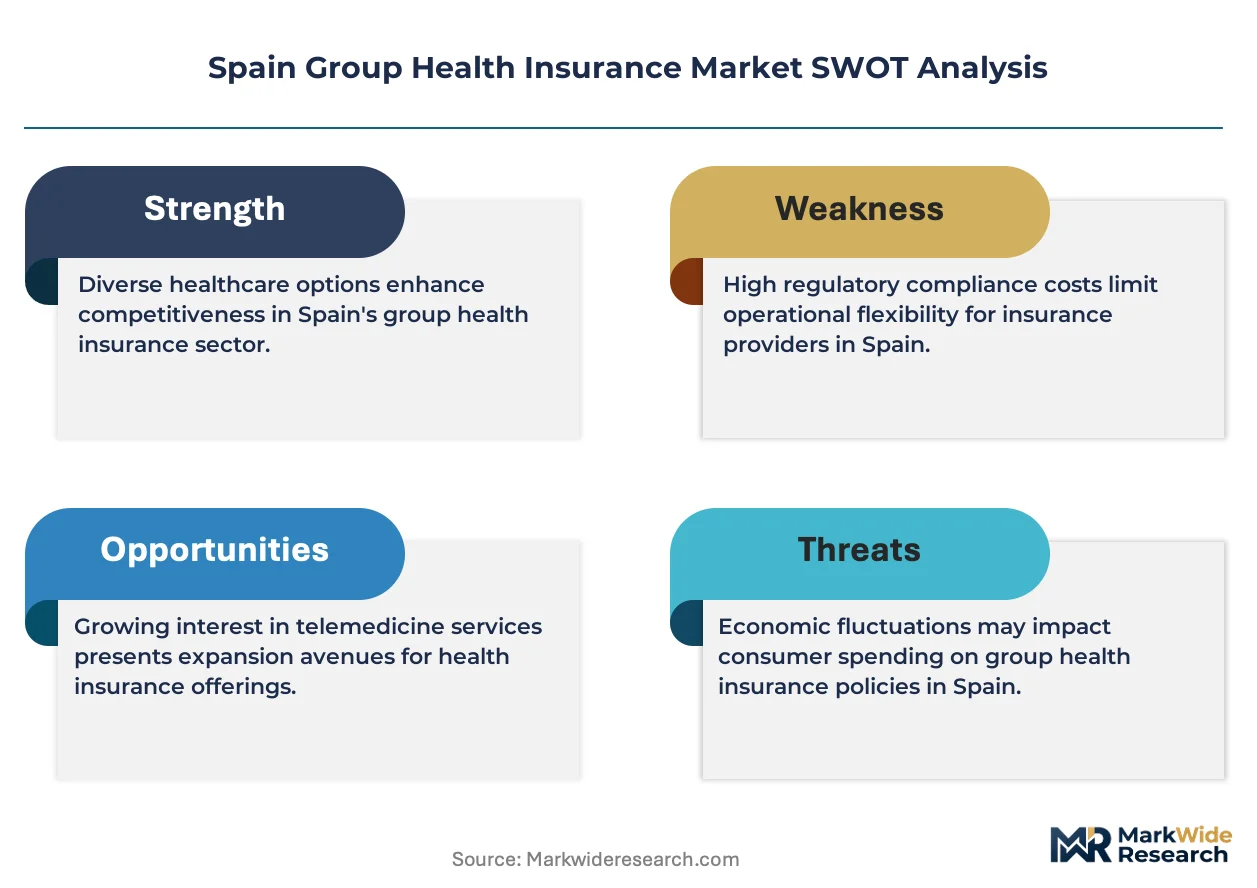
Spain's General Directorate of Insurance and Pension Funds (DGSFP) enforces solvency ratios and policy transparency requirements that shape product design and distribution compliance for all group health underwriters operating domestically. The National Securities Market Commission coordinates with DGSFP on bancassurance channel oversight, constraining how banks bundle health products with commercial lending instruments. Stakeholders must monitor evolving copayment and deductible regulation as policymakers weigh cost-containment measures against employer premium escalation pressures.
Market Dynamics
Digital health management platforms are compressing distribution layers in Spain's group health insurance sector, embedding telemedicine and real-time claims processing directly into employer contracts and bypassing traditional broker intermediaries.
Growth Catalysts
- DGSFP Solvency Mandates:Spain's General Directorate of Insurance and Pension Funds enforces capital adequacy requirements that elevate product quality standards and reduce insurer failure risk, strengthening employer confidence in long-term coverage commitments.
- Technology Sector Talent Competition:Madrid's multinational headquarters clusters are expanding group coverage enrollment as a retention instrument, treating comprehensive health benefits as non-negotiable compensation components.
- Automated Enrollment Platforms:Cloud-based administration tools are dismantling procurement barriers that previously favored large-group scale, opening medium enterprise segments to competitive bidding.
Market Restraints
- Copayment Regulatory Uncertainty:Spanish policymakers are weighing cost-containment measures against premium escalation pressures, creating compliance planning friction for underwriters designing multi-year contracts.
- Hospital Network Concentration:Integrated provider systems in Madrid and Barcelona limit negotiating leverage for insurers seeking competitive rate structures outside these metropolitan catchments.
- Public Healthcare Substitution:Spain's robust national health system offers zero-premium baseline coverage, constraining willingness-to-pay among cost-sensitive small employers.
Strategic Opportunities
- Barcelona Corporate Expansion:Catalonia's growing technology and pharmaceutical clusters represent underpenetrated demand relative to Madrid's saturated corporate corridor.
- International Portability Integration:Cross-border coverage features for expatriate-heavy industries align with Spain's position as a European headquarters location for multinational firms.
- Bancassurance Channel Evolution:The National Securities Market Commission's coordination with DGSFP on bundled product oversight is creating compliant pathways for bank-distributed group health offerings.
Industry Challenges
- Actuarial Talent Scarcity:Specialized underwriting expertise for medium enterprise risk assessment remains concentrated among legacy insurers, constraining new market entrants.
- Legacy System Integration:Real-time claims processing requirements demand API connectivity with employer HR platforms, forcing costly core system overhauls for established providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Group Health Insurance Market |
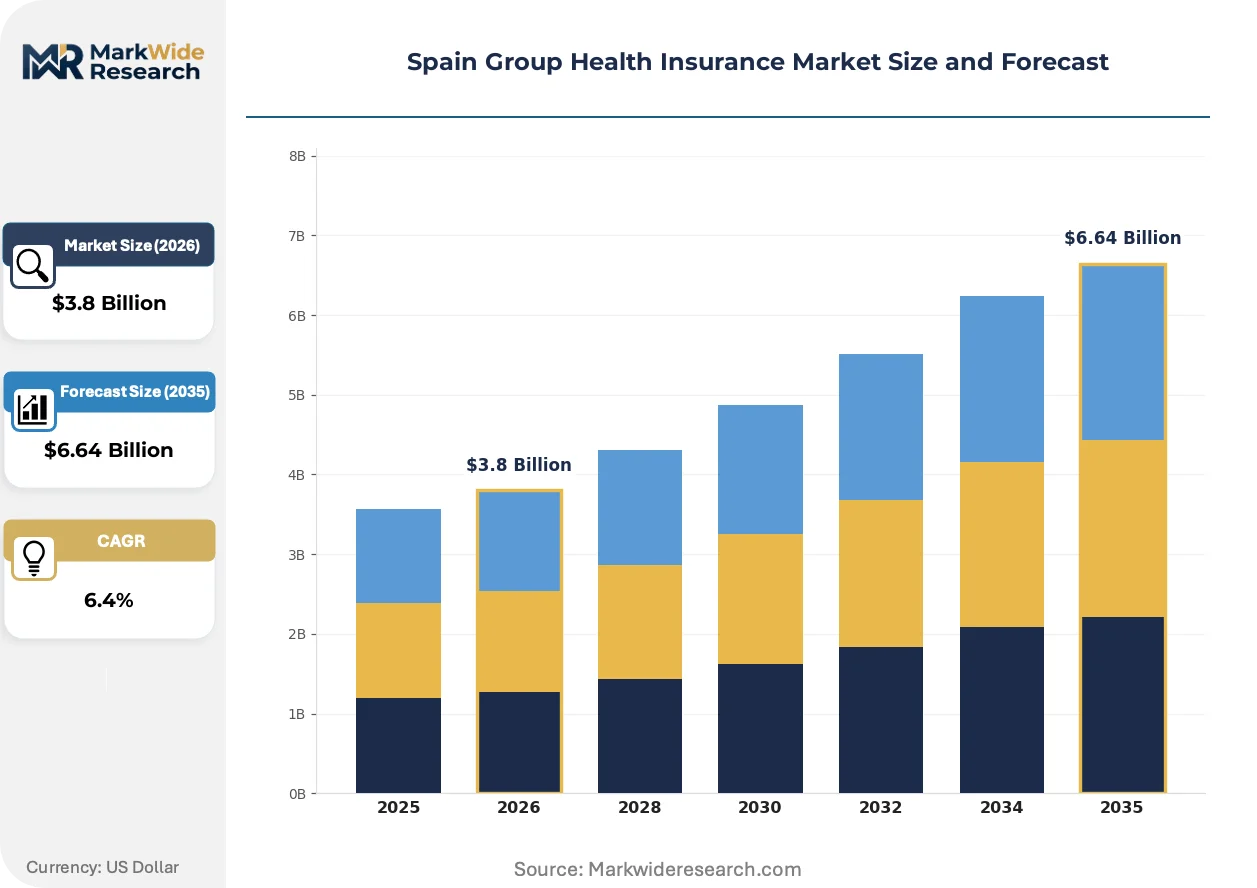
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Basic, Executive, Essential Customer Type: Small Businesses, Medium Enterprises, Large Corporations, Nonprofits Plan Coverage: Inpatient, Outpatient, Dental, Maternity Payment Structure: Premium-Based, Copayment, Deductible, Coinsurance |
| Companies Covered | Asisa, AXA, Adeslas, Mutua Madrileña, Allianz, Sanitas, Mapfre, Santalucía, DKV Seguros, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Group Health Insurance Market Trends and Innovations
Telemedicine infrastructure and predictive analytics are restructuring how Spanish employers procure and administer group health benefits, shifting value from policy documents to embedded health management services.
Digital health management platforms is consolidating control over the policy lifecycle by embedding virtual primary care, mental health counseling, and chronic disease monitoring into standard corporate contracts. Large multinational headquarters in Madrid are adopting these integrated offerings within single renewal cycles. This consolidation is compressing commissions for traditional insurance brokers who previously mediated employer-insurer relationships.
DGSFP transparency requirements are mandating standardized benefit disclosures and claims denial justification protocols that elevate administrative burdens for underwriters. Product design teams must now embed compliance documentation into policy management systems from inception. Medium enterprises with limited HR infrastructure are responding by favoring insurers offering pre-configured compliant plan templates.
Employer procurement committees are compressing renewal evaluation cycles from annual to continuous monitoring, treating group health as a dynamic operational expense rather than a fixed annual contract. Digital brokerage platforms with instant quote comparison tools are displacing relationship-based broker retention in Barcelona and Valencia. This pattern is most visible among technology sector employers with young, mobile workforces demanding immediate plan modifications.
Spain Group Health Insurance Market Segmentation
Employer procurement cycles in Spain's group health insurance sector are compressing from annual renewals to continuous evaluation, forcing insurers to align product tiers with distinct workforce risk profiles and administrative capabilities. Segmentation discipline determines whether underwriters capture Madrid's multinational headquarters or surrender share to automated enrollment platforms.
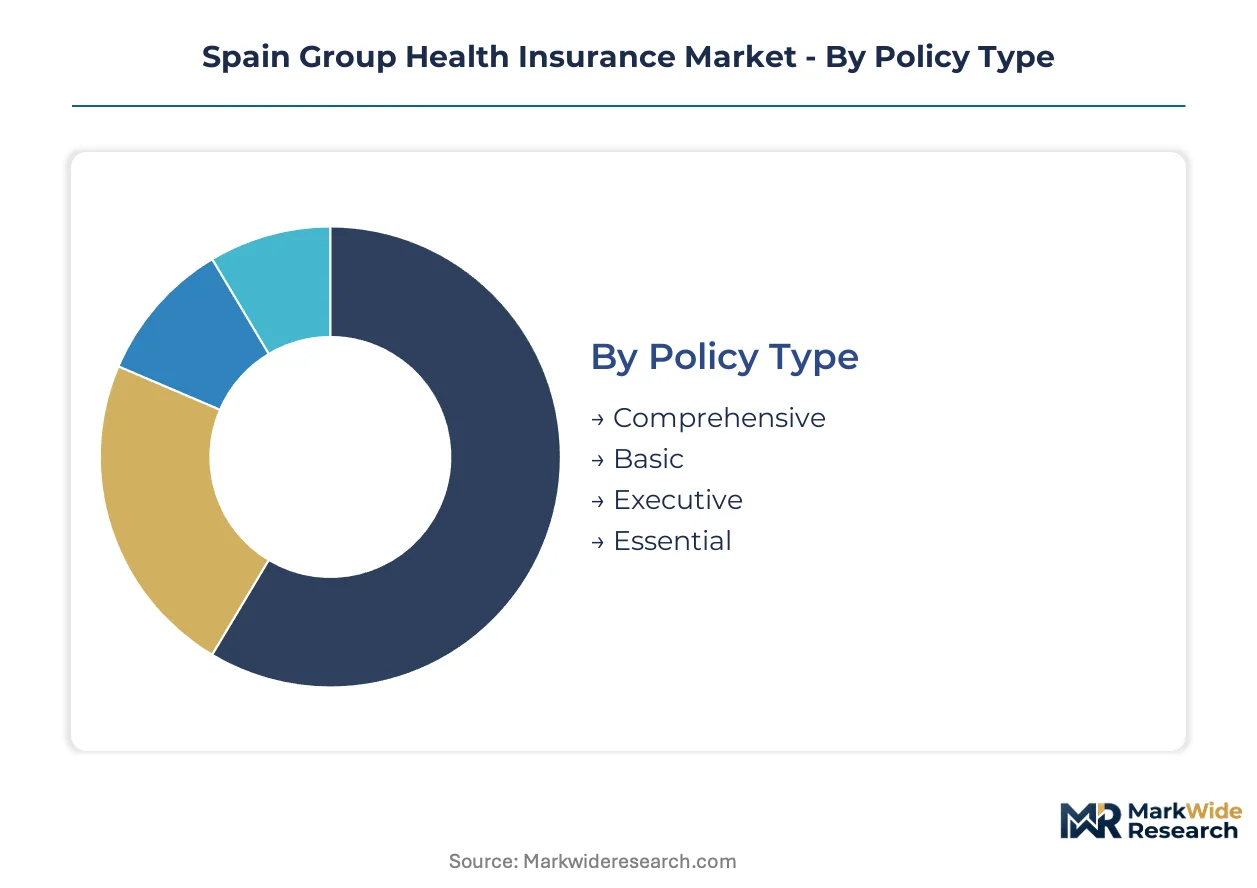
Policy Type:
Upgrade momentum from basic to comprehensive coverage is accelerating as technology sector employers treat health benefits as non-negotiable retention instruments.
- Comprehensive:Full inpatient-outpatient-dental integration with guaranteed issue provisions and negotiated hospital network access. Madrid's financial services clusters sustain dominant placement volumes as multinational headquarters demand seamless coverage for expatriate-heavy workforces.
- Basic:Statutory minimum coverage thresholds with limited provider networks and higher out-of-pocket exposure. Cost-constrained small businesses in Valencia and Seville navigate Spain's dual public-private architecture by layering modest private coverage atop the national health system.
- Executive:Premium-tier offerings with dedicated concierge services and international portability features.
- Essential:Stripped-down catastrophic coverage designed for compliance with collective bargaining minimums.
Volume placements concentrate in Comprehensive; the faster expansion belongs to Executive as Barcelona's pharmaceutical clusters professionalize benefits.
Customer Type:
Cost tier stratification separates automated enrollment platforms serving medium enterprises from relationship-based brokers retaining large-group accounts.
- Medium Enterprises:Cloud-based administration tools have dismantled procurement barriers that previously favored large-group scale, opening competitive bidding for 50-500 employee cohorts. Catalonia's technology subclusters represent underpenetrated demand relative to Madrid's saturated corridor.
- Large Corporations:Multinational headquarters command full inpatient-outpatient-dental integration with international portability and dedicated account management.
- Small Businesses:Limited HR infrastructure favors pre-configured compliant plan templates from insurers with simplified enrollment.
- Nonprofits:Budget-constrained organizations balancing mission alignment with statutory coverage obligations.
Revenue concentration sits with Large Corporations; medium enterprises are climbing the fastest as digital distribution removes friction.
Plan Coverage:
Application-specific bundling is restructuring standard contracts as employers embed telemedicine and mental health into core offerings.
- Inpatient:Hospitalization and surgical coverage with pre-negotiated rates at integrated provider systems. Madrid and Barcelona network concentration limits insurer negotiating leverage outside these metropolitan catchments.
- Outpatient:Primary care, specialist consultations, and diagnostic services with virtual access becoming standard.
- Dental:Preventive and restorative coverage often bundled as a retention differentiator in technology sector contracts.
- Maternity:Prenatal, delivery, and postnatal benefits reflecting Spain's demographic priorities and collective bargaining patterns.
Procurement frequency is highest for Inpatient; Dental is gaining share fastest as employers seek differentiation without premium escalation.
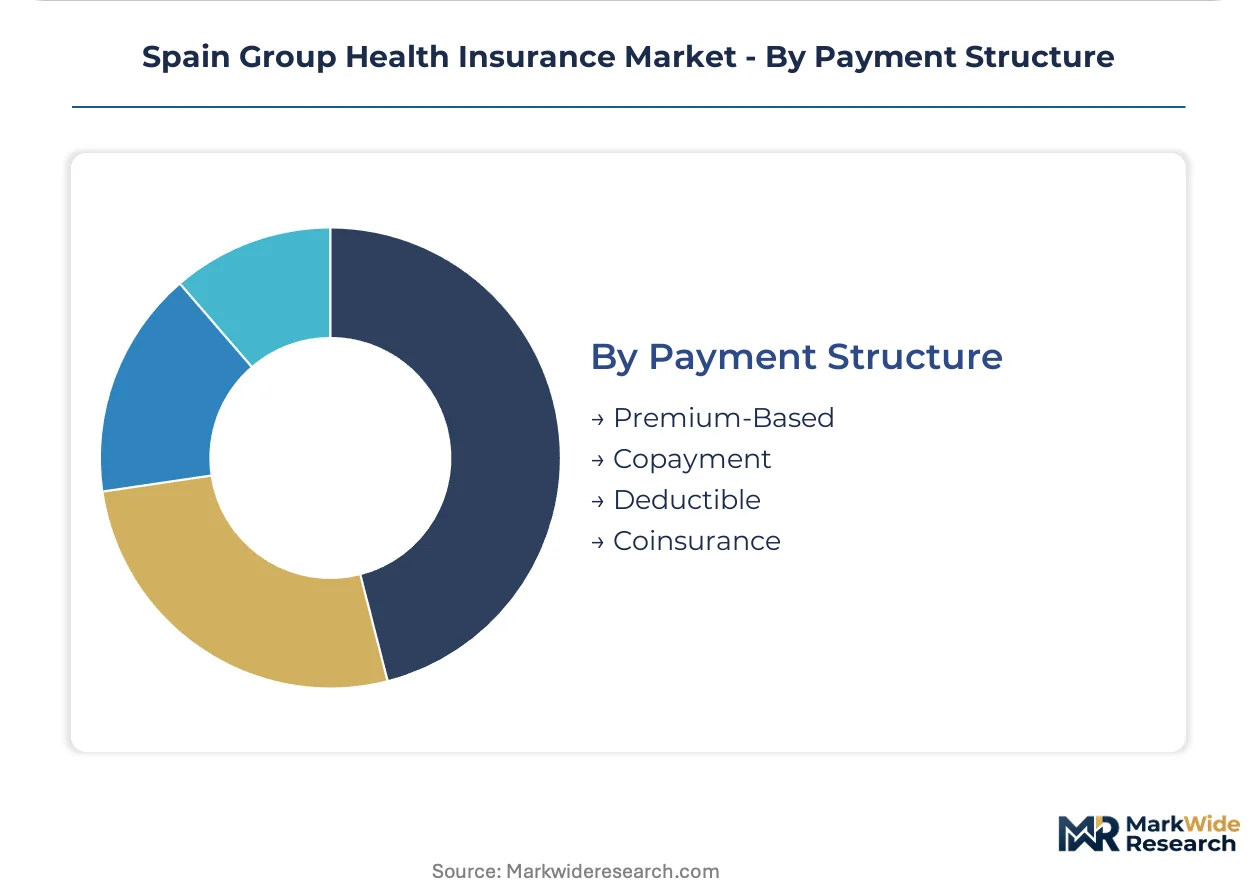
Payment Structure:
Margin architecture varies sharply across risk-sharing mechanisms, with DGSFP transparency mandates complicating multi-year contract design.
- Premium-Based:Fixed employer contributions with predictable budgeting and no employee point-of-service charges. Large corporations in Madrid's corporate corridor favor this structure for administrative simplicity and workforce satisfaction.
- Copayment:Per-visit or per-service charges creating utilization disincentives. Spanish policymakers are weighing cost-containment measures against employer premium escalation pressures, generating compliance planning friction.
- Deductible:Annual spending thresholds before coverage activation, rare in Spain's group market but emerging in cost-containment experiments.
- Coinsurance:Percentage cost-sharing arrangements splitting expenses between insurer and enrollee.
Contract prevalence favors Premium-Based; Copayment structures are expanding most quickly as policymakers pressure cost containment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's group health insurance production concentrates in Madrid and Barcelona, where insurer headquarters and hospital networks cluster, while consumption spreads across autonomous communities with varying employer density and public healthcare substitution rates.
Madrid
Financial services and multinational headquarters drive comprehensive policy uptake across the corporate corridor. Spain's General Directorate of Insurance and Pension Funds enforces solvency ratios that elevate product standards for underwriters headquartered in the capital. The Madrid metropolitan area sustains the densest concentration of large-group contracts serving expatriate-heavy industries.
Catalonia
Barcelona's technology and pharmaceutical subclusters represent underpenetrated demand relative to Madrid's saturated market. Regional health authorities coordinate with national regulators on copayment structure approvals affecting employer premium calculations. The Barcelona corporate expansion corridor is attracting automated enrollment platforms targeting medium enterprises with 50-500 employee cohorts.
Basque Country
Industrial manufacturing employers in Bilbao and San Sebastián navigate collective bargaining agreements that mandate minimum coverage thresholds. Spain's National Securities Market Commission coordinates with regional banking supervisors on bancassurance distribution compliance. The Basque industrial belt maintains steady basic plan enrollment layered atop the regional public health system.
Andalusia
Tourism and agriculture sector employers in Seville and Málaga exhibit cost-sensitive procurement favoring statutory minimum coverage. Regional economic development programs incentivize small business health benefit adoption through tax-advantaged compensation structures. The Costa del Sol corridor shows emerging demand from international remote workers seeking portable coverage.
Valencia
Mid-sized professional services firms in the Levante region favor pre-configured compliant plan templates reducing HR administrative burdens. Valencia's growing logistics and distribution clusters are expanding group coverage as workforce retention instruments. The metropolitan area sits between Madrid and Barcelona network concentrations, limiting insurer negotiating leverage.
Spain Group Health Insurance Market Competitive Landscape
Top-tier vendors anchor the premium comprehensive segment, while regional specialists and automated platforms compete for medium enterprise accounts. The market structure reflects moderate consolidation around integrated hospital networks and international portability capabilities. Three archetypes dominate: legacy insurers with captive provider infrastructure, multinational carriers with cross-border coverage features, and digital-first platforms dismantling traditional broker intermediation. Competitive moves center on API integration with employer HR systems and geographic expansion into underpenetrated autonomous communities.
Among Spain-based integrated providers, Adeslas and Sanitas exemplify the network-captive archetype leveraging hospital infrastructure for competitive positioning. AXA represents the multinational portability tier serving expatriate-heavy industries from Madrid headquarters. Mapfre occupies the specialized risk-assessment position for medium enterprises seeking tailored premium structures. Each anchors distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Asisa |
| AXA |
| Adeslas |
| Mutua Madrileña |
| Allianz |
| Sanitas |
| Mapfre |
| Santalucía |
| DKV Seguros |
| Others |
Pricing and Supply Chain Analysis
Multinational headquarters clusters in Madrid's corporate corridor anchor premium pricing power for comprehensive group health plans, compressing margins for insurers competing outside integrated hospital network catchments. DGSFP solvency mandates elevate capital reserve requirements that feed through to premium structures, while automated enrollment platforms dismantle traditional broker commissions in medium enterprise segments.
Pricing Analysis
Margin tightening in basic coverage tiers reflects public healthcare substitution pressure as cost-sensitive small employers layer minimal private benefits atop Spain's national health system. Premium-based fixed contributions dominate Madrid's large-group contracts, with price differentiation hinging on hospital network breadth and international portability features. Cost-down pressure accelerates in Barcelona's emerging technology clusters as digital brokerage platforms enable instant quote comparison. Small businesses in Valencia and Seville exhibit highest price sensitivity, while expatriate-heavy multinationals in Madrid show lowest sensitivity to premium escalation.
Supply Chain Analysis
Freight and logistics costs for medical equipment and pharmaceutical inputs exert secondary pressure on insurer-negotiated hospital rates, particularly for imported diagnostic technologies. Supply concentration centers on Germany, Switzerland, and the United States for advanced medical devices, while pharmaceutical APIs draw increasingly from India and China. Single-source vulnerability in specialized oncology drug supply chains creates rate negotiation friction for comprehensive plan underwriters. Distribution runs through integrated hospital networks in Madrid and Barcelona, with regional insurers maintaining captive provider infrastructure to defend margin positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's group health insurance sector is consolidating around vertical integration into hospital network infrastructure, with underwriters racing to secure captive provider capacity before automated platforms commoditize distribution in medium enterprise segments.
For Market Incumbents: To counter digital brokerage platform displacement in the 50-500 employee segment, legacy insurers should accelerate API integration with employer HR systems and deepen hospital network exclusivity in Barcelona's underpenetrated technology corridor. Defensive consolidation moves include acquiring automated enrollment platforms to neutralize channel threat and securing long-term rate agreements with Madrid's integrated provider systems before competitor capacity expansion.
For New Entrants and Emerging Players: Medium enterprises in Catalonia's pharmaceutical subclusters represent the most penetrable buyer archetype, with limited incumbent relationship density and growing demand for tailored premium structures. White-space targets include Barcelona's 50-200 employee technology firms and Valencia's logistics clusters seeking pre-configured compliant plan templates. A direct digital go-to-market angle bypassing traditional broker intermediation offers lowest customer acquisition friction.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated regional specialists with captive hospital infrastructure over pure distribution plays. Long-term viability hinges on network exclusivity durability rather than technology platform differentiation. Acquisition target archetypes include medium-enterprise-focused automated enrollment platforms and Barcelona-area provider networks. The signal to watch is DGSFP regulatory clarity on copayment structures, which would reset contract design economics across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital Network Integration | Captive provider infrastructure in Madrid and Barcelona secures rate negotiation leverage against competing underwriters. |
| Automated Enrollment Platform Launch | Cloud-based administration tools dismantle procurement barriers previously favoring large-group scale economies. |
| API Connectivity Investment | Real-time claims processing integration with employer HR systems meets continuous evaluation procurement patterns. |
| International Portability Expansion | Cross-border coverage features align with Spain's position as European headquarters location for multinational firms. |
| Telemedicine Infrastructure Buildout | Virtual primary care embedding distinguishes comprehensive plans in technology sector talent competition. |
Research Methodology
Document review covered DGSFP regulatory filings, National Securities Market Commission bancassurance oversight records, and insurer solvency disclosures, complemented by interviews with group health underwriting directors, employer benefits managers at Madrid multinational headquarters, automated enrollment platform product leads, and hospital network contracting officers. Secondary validation drew from Spanish insurance association statistical bulletins, autonomous community health authority procurement databases, and European insurance supervisor comparative reports. Bottom-up policy placement data triangulated against top-down premium revenue estimates across the analysis window.
Model outputs span policy type, customer type, plan coverage, and payment structure dimensions, with additional segmentation by autonomous community regulatory cluster and technology sector concentration. CAGRs derive from insurer premium growth trajectories, employer expansion patterns, and regulatory cost-pass-through assumptions. Forecast inputs include DGSFP solvency ratio evolution, telemedicine adoption curves in corporate contracts, and medium enterprise digital procurement penetration rates.
Revisions become necessary when DGSFP mandates materialize on copayment structures, public healthcare substitution rates shift in cost-sensitive segments, or hospital network consolidation alters regional rate negotiation dynamics. Forecasts reflect documented assumptions on employer retention benefit prioritization and regulatory transparency compliance costs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United Kingdom Parametric Insurance Market
Insurance
China Online Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Cancer Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
China Parametric Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
Insurance Brokerage Market
Insurance
Business Income Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Property and Casualty Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Art Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
General Insurance Market