
 China Property and Casualty Insurance Market | 2026-2036
China Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
China Property and Casualty Insurance Market Outlook
Embedded risk analytics services are reshaping how insurers capture value beyond premium collection. PICC Property & Casualty Co., Ltd. leverages its rural network density to dominate agricultural and vehicle coverage across county-level markets. Ping An Property & Casualty Insurance anchors its competitive position through proprietary AI-driven claims assessment platforms that compress loss-adjustment cycles. ZhongAn Online P&C Insurance specializes in parametric and usage-based products distributed through embedded e-commerce channels.
Property and casualty insurance constitutes a contractual risk-transfer mechanism where insurers indemnify policyholders against specified perils including physical damage, liability exposure, and business interruption, with pricing calibrated through actuarial modeling of frequency and severity distributions. The primary commercial purpose centers on enterprise solvency protection and regulatory capital relief through off-balance-sheet risk financing. Liability coverage leads premium generation among corporates facing heightened product-recall and environmental litigation exposures, while online distribution channels capture the fastest growth as mobile-native SMEs bypass traditional agent networks. Bundled policy structures concentrate margin pools by cross-subsidizing low-frequency property lines with high-retention liability attachments.
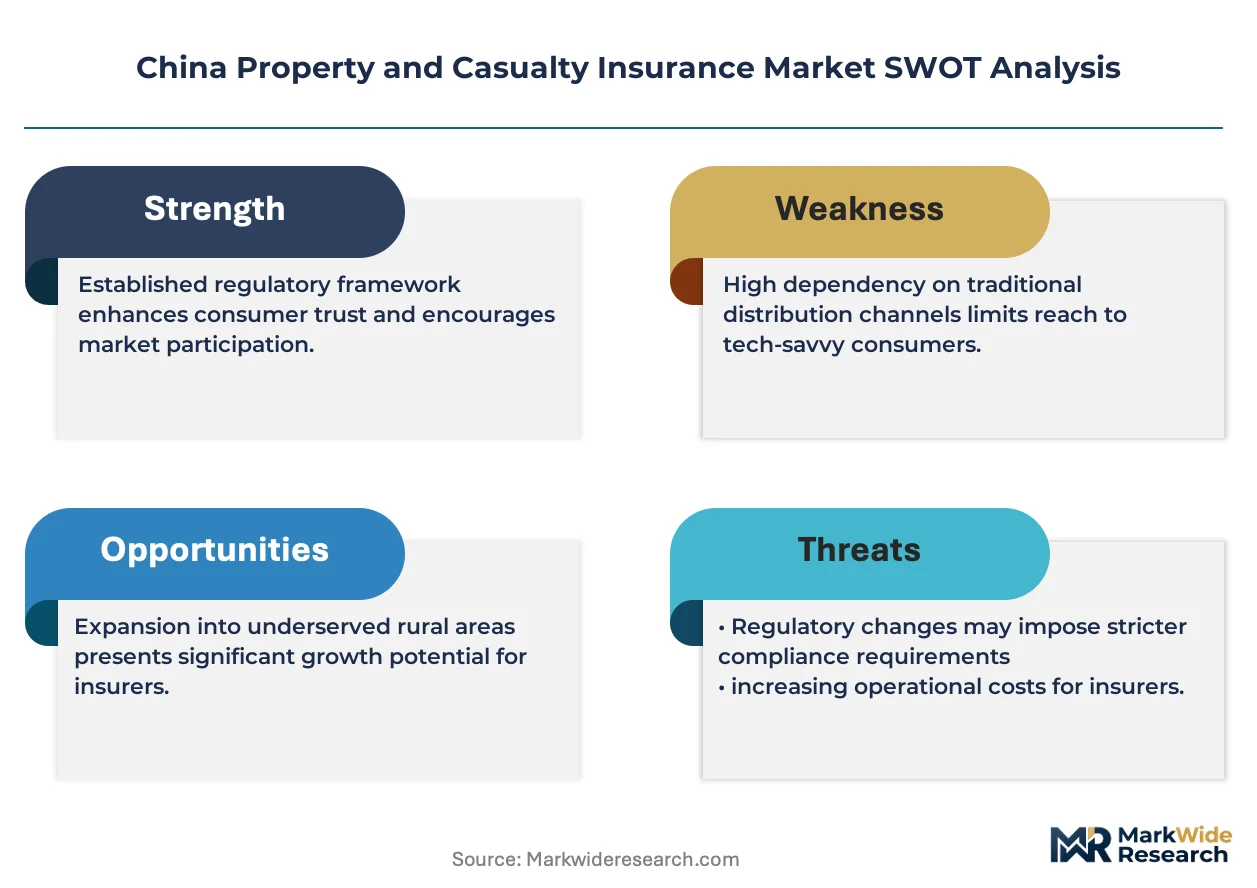
SAMR enforces solvency ratio thresholds and product filing requirements that constrain capital deployment flexibility for domestic underwriters. NMPA data standards intersect with MIIT cybersecurity rules to mandate encrypted health and telematics data handling in connected auto and medical liability products. Local banking and insurance regulators in Shanghai and Shenzhen pilot sandbox frameworks for parametric catastrophe bonds. Stakeholders must monitor how dual carbon goals reshape industrial property risk profiles and force recalibration of engineering inspection protocols.
Market Dynamics
Dual carbon goals from Beijing are forcing recalibration of industrial property risk profiles across heavy manufacturing clusters, compelling insurers to rewrite engineering inspection protocols and premium models for carbon-intensive assets.
Growth Catalysts
- Yangtze River Delta industrial density:Manufacturing concentration around Shanghai and Jiangsu province generates concentrated demand for commercial property and liability coverage as enterprises formalize risk transfer mechanisms.
- SAMR solvency modernization:The regulator's updated capital adequacy frameworks are pushing domestic underwriters toward sophisticated risk modeling, raising barriers that favor scaled players with advanced actuarial capabilities.
- Connected auto telematics:MIIT-mandated data standards for vehicle connectivity are enabling usage-based auto insurance products that align premium calibration with actual driving behavior rather than demographic proxies.
Market Restraints
- Catastrophe loss volatility:Flood and typhoon exposure in coastal provinces creates capital-intensive reserving requirements that constrain underwriting capacity for property lines.
- Agent network fixed costs:Rural distribution infrastructure demands sustained maintenance expenditure that dilutes margins on low-premium agricultural and micro-commercial policies.
- Legacy core system architecture:Mainframe-dependent policy administration platforms at established insurers impede real-time data integration with IoT-enabled risk monitoring devices.
Strategic Opportunities
- Parametric catastrophe bonds:Shanghai and Shenzhen regulatory sandboxes are piloting alternative risk transfer instruments that could unlock institutional capital for natural peril coverage.
- SME digital distribution bypass:Mobile-native small enterprises are abandoning traditional agent channels, creating whitespace for embedded insurance partnerships with e-commerce and fintech platforms.
- NMPA-aligned health data products:Medical liability and connected health offerings can leverage standardized pharmaceutical data governance to accelerate product development cycles.
Industry Challenges
- Actuarial talent scarcity:Shortage of professionals combining traditional pricing expertise with machine learning implementation is slowing AI-driven claims platform deployment.
- Cross-regional license harmonization:Provincial banking and insurance regulators maintain divergent product filing timelines that fragment national product rollouts.
- Telematics data integration:MIIT cybersecurity rules mandate encrypted handling that complicates real-time ingestion of vehicle sensor streams into pricing engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Property and Casualty Insurance Market |
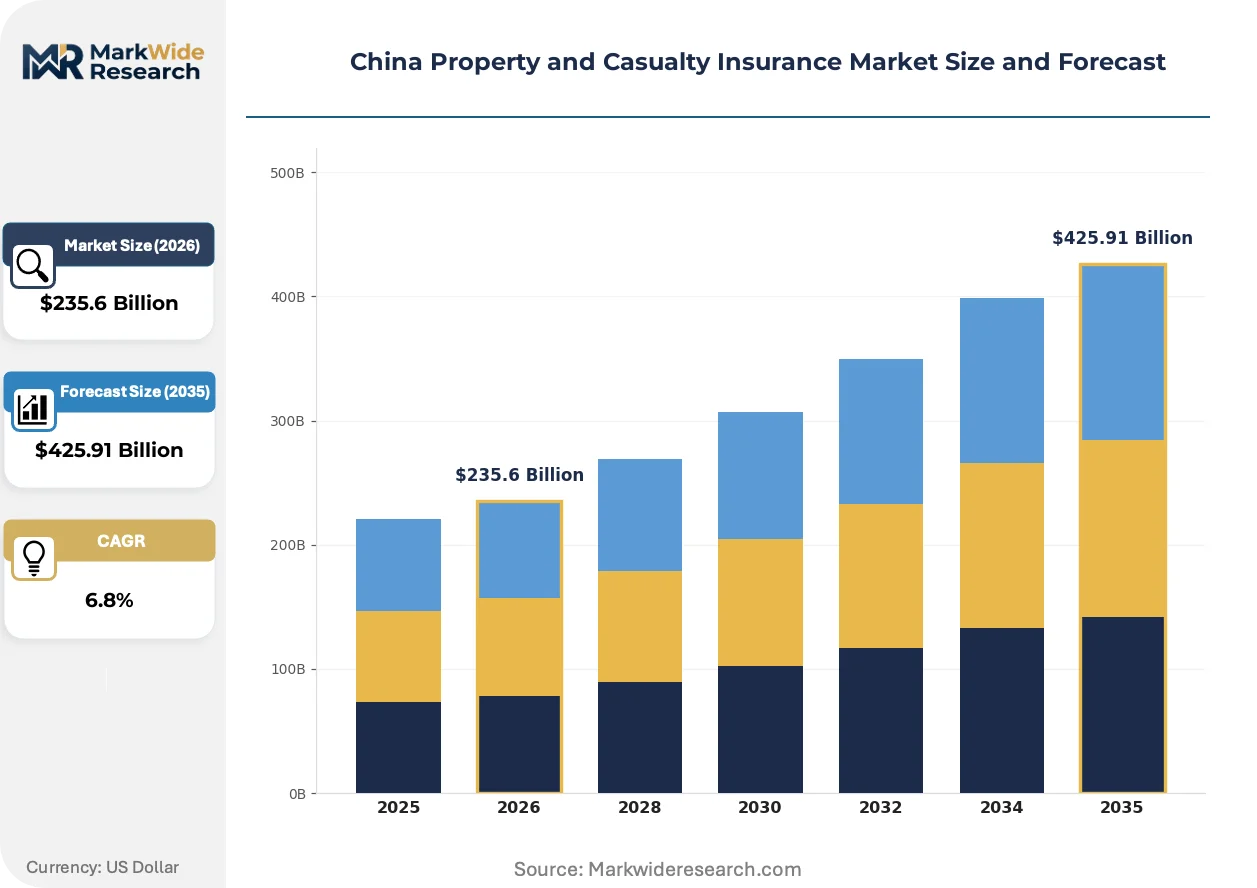
| Market Size in 2026 | $235.6 Billion |
| Market Size in 2035 | $425.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Property Damage, Personal Injury, Workers' Compensation Distribution Channel: Online, Brokers, Agents, Direct Sales End User: Individuals, SMEs, Corporates, Government Entities Policy Type: Standard, Custom, Bundled, Microinsurance |
| Companies Covered | China Continent Property & Casualty Insurance, Sunshine Insurance Group, PICC Property & Casualty Co., Ltd., ZhongAn Online P&C Insurance, China Taiping Insurance Group, Ping An Property & Casualty Insurance, China Life Property & Casualty Insurance Co., Huatai Property & Casualty Insurance, China Pacific Property Insurance Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Property and Casualty Insurance Market Strategic Shifts
Embedded risk analytics services are capturing value beyond premium collection, compressing loss-adjustment cycles and enabling proactive risk prevention. Three forces are reshaping competitive positioning.
AI-driven claims assessment is hybridizing traditional loss adjustment with computer vision and natural language processing. Property and casualty insurers are deploying these platforms to compress cycle times from weeks to days. The technology is hybridizing underwriting workflows by automating damage estimation while preserving human oversight for complex liability determinations.
SAMR consumer protection rules are tightening disclosure requirements for policy terms and claims settlement procedures. Insurers must now provide standardized plain-language summaries that reduce information asymmetry between underwriters and policyholders. Commercial lines in manufacturing-heavy provinces face the most intensive compliance scrutiny as regulators target enterprise buyers with limited bargaining power.
Mobile-native SMEs are abandoning traditional agent networks for direct digital purchasing through insurer apps and embedded third-party channels. This channel disintermediation is collapsing commission structures that historically subsidized rural distribution infrastructure. The shift is most visible in Jiangsu and Zhejiang province manufacturing corridors where younger enterprise owners demand instant quote-to-bind experiences.
China Property and Casualty Insurance Market Segmentation
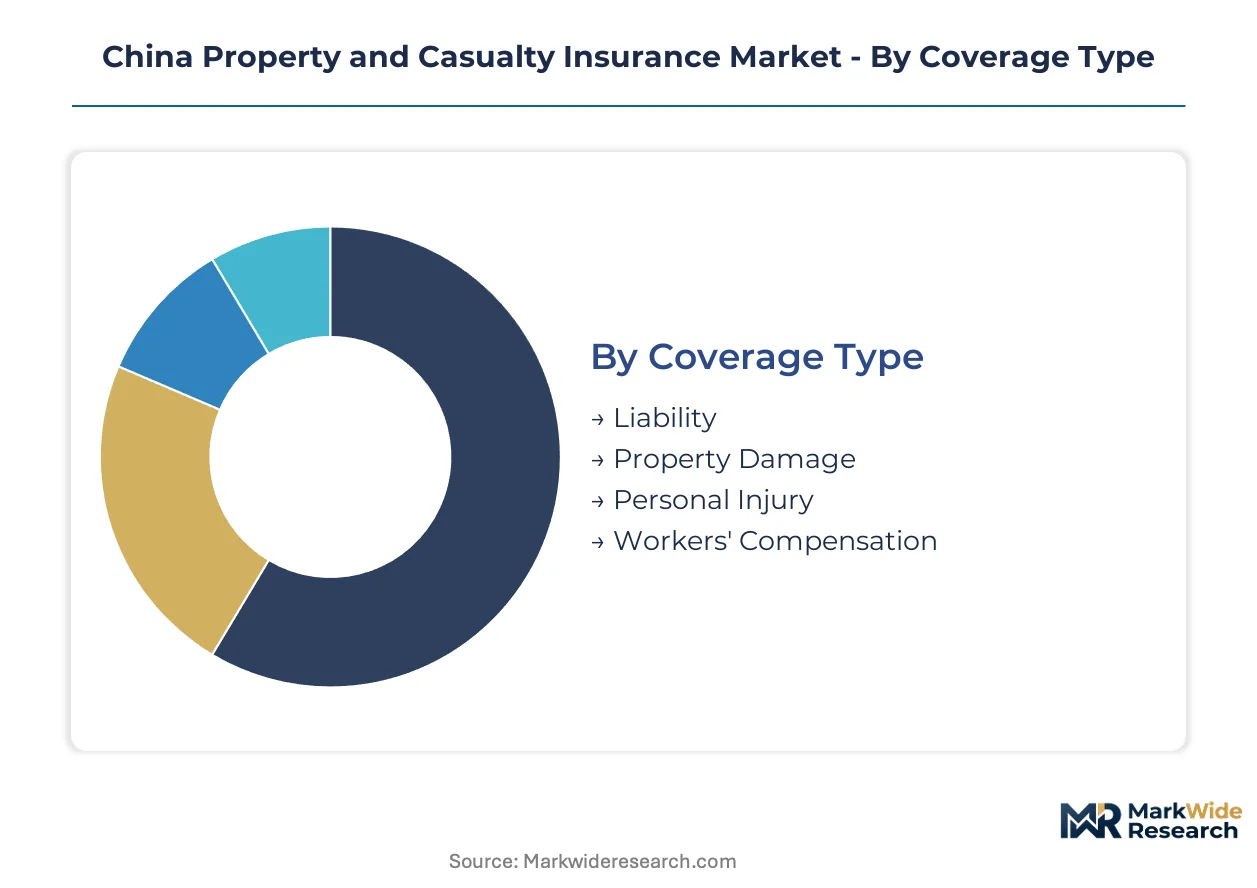
Segmentation reveals how P&C insurers allocate capital across divergent risk profiles and distribution economics. Coverage type and channel structure determine margin pools, while end-user scale dictates pricing sophistication and service intensity.
Coverage Type:
Liability through workers' compensation spans a use-case spectrum from enterprise solvency protection to individual income replacement, with each line demanding distinct actuarial reserves and regulatory capital treatment.
- Liability:Indemnifies third-party bodily injury and property damage claims arising from insured operations. Manufacturing concentration in Jiangsu and Zhejiang provinces drives commercial general liability demand as enterprises face heightened product-recall and environmental litigation exposures.
- Property Damage:Covers physical asset destruction from perils including fire, flood, and industrial accidents. Coastal manufacturing facilities in Shanghai municipality generate concentrated demand for all-risk commercial property policies as typhoon frequency intensifies.
- Personal Injury:Provides medical expense and lost income coverage for non-occupational accidents. County-level markets leverage PICC's rural network density for motor accident personal injury protection.
- Workers' Compensation:Mandated employer liability for occupational injury and disease claims. Heavy manufacturing clusters around the Yangtze River Delta sustain premium volume as SAMR enforces stricter workplace safety compliance.
Established volume favors property damage; emerging adoption favors liability as litigation exposure expands.
Distribution Channel:
Channel economics range from high-touch agent relationships to zero-marginal-cost digital binding, with cost tier determining reach and retention trade-offs.
- Online:Digital platforms enable instant quote-to-bind for standardized products. Mobile-native SMEs in Zhejiang province bypass traditional intermediaries for embedded e-commerce insurance partnerships.
- Brokers:Independent intermediaries negotiate complex commercial placements for mid-market enterprises. Manufacturing buyers in Jiangsu province rely on broker expertise for multi-line bundled structures.
- Agents:Captive and independent representatives maintain local relationships for claims advocacy. Rural agricultural coverage depends on county-level agent presence despite fixed cost dilution.
- Direct Sales:Insurer-employed forces target large corporate accounts with bespoke risk engineering. State-owned enterprises in Shanghai municipality procure direct for property and engineering lines.
Agent networks retain premium volume; online channels are climbing the fastest as mobile penetration deepens.
End User:
Customer type stratifies by premium scale, risk complexity, and purchasing sophistication across individual to sovereign buyers.
- Individuals:Personal auto and homeowners policies dominate retail premium pools. First-tier city households drive demand for high-limit personal umbrella coverage.
- SMEs:Small manufacturing and service enterprises require standardized commercial packages. Zhejiang province private enterprises favor micro-commercial policies through digital channels.
- Corporates:Large industrial and commercial entities negotiate tailored risk transfer programs. Multinational manufacturing facilities in Jiangsu province procure master policies with international extensions.
- Government Entities:Public infrastructure and social insurance programs create captive demand. Municipal governments in Shanghai pilot parametric catastrophe coverage for public assets.
Corporate accounts concentrate premium value; SME digital adoption is gaining share fastest.
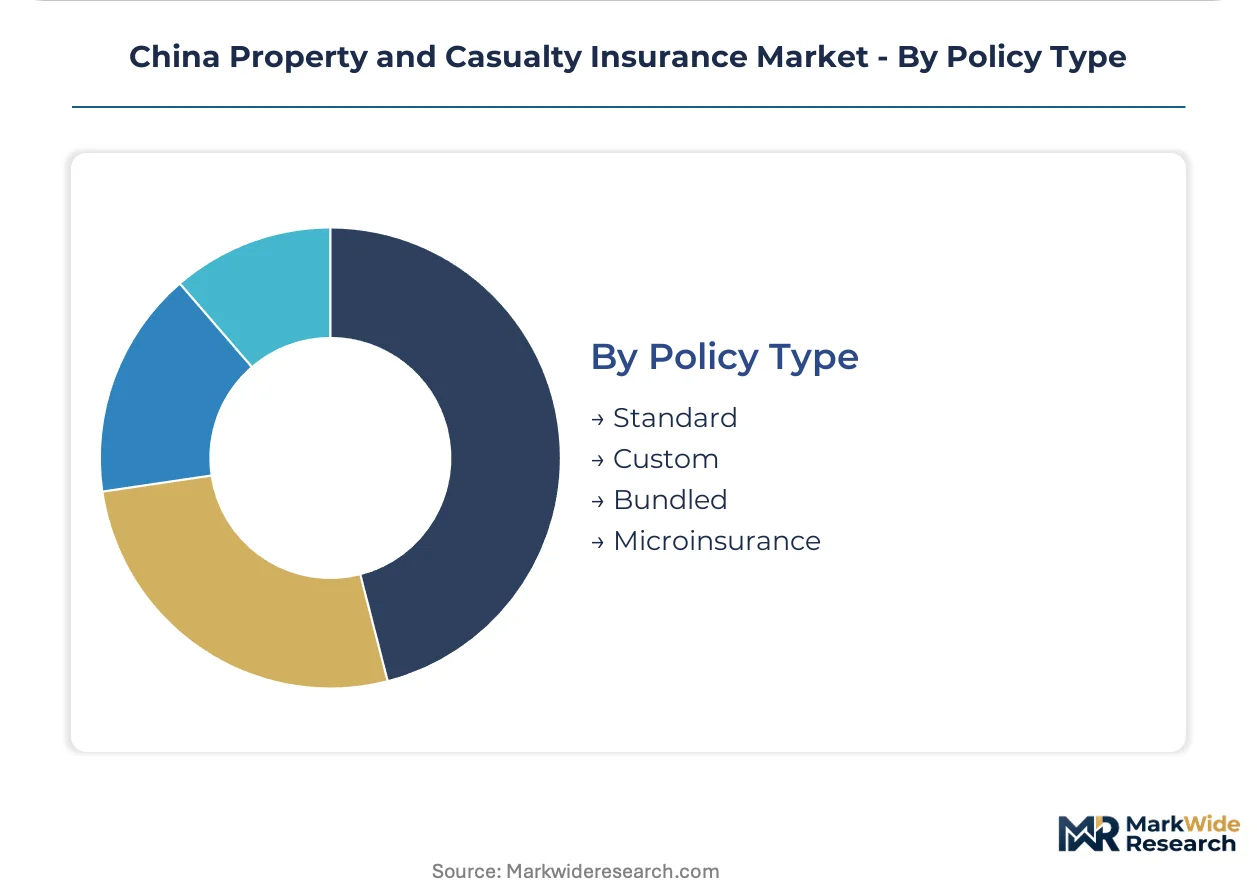
Policy Type:
Product architecture spans commoditized standard forms to engineered bespoke structures, with margin profile inversely related to customization depth.
- Standard:Pre-filed policy forms with limited coverage modifications for homogeneous risks. Personal auto and homeowners lines dominate standard product premium generation.
- Custom:Tailored endorsements and manuscript wording for unique exposure profiles. Large industrial risks in Jiangsu province require customized property and business interruption structures.
- Bundled:Multi-line packages combining property, liability, and specialty coverages. Manufacturing enterprises in Zhejiang province consolidate coverage for premium efficiency and reduced gap risk.
- Microinsurance:Simplified low-limit products for price-sensitive and underpenetrated segments. Rural agricultural policies and gig economy personal accident coverage expand through mobile distribution.
Bundled structures capture margin concentration; microinsurance shows steepest expansion trajectory through embedded distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity concentrates in western provinces where agricultural coverage dominates, while coastal manufacturing clusters absorb premium pricing for complex commercial placements. Yangtze River Delta buyers prioritize claims service quality over premium minimization. Policy penetration gaps widen between first-tier cities and county-level markets.
Yangtze River Delta
Shanghai and Jiangsu province manufacturing density generates concentrated demand for commercial property and liability coverage. SAMR enforces stricter solvency reporting for insurers operating across this cluster. Multinational manufacturing facilities in Suzhou and Wuxi procure bundled multi-line policies with international extensions.
Pearl River Delta
Guangdong province electronics and export manufacturing sustains premium volume for product liability and cargo insurance. MIIT cybersecurity rules mandate encrypted telematics data handling for connected auto products. Shenzhen-based fintech platforms embed microinsurance into e-commerce transactions for SME exporters.
Beijing-Tianjin-Hebei
State-owned enterprise concentration drives direct sales procurement for large property and engineering risks. Dual carbon goals from Beijing force recalibration of industrial property underwriting for steel and chemical assets. Tianjin port logistics operations generate marine cargo and warehouse liability demand.
Sichuan-Chongqing
Western China infrastructure investment creates demand for construction all-risk and surety coverage. Provincial regulators pilot relaxed product filing timelines for catastrophe bonds covering earthquake exposure. Chongqing automotive manufacturing clusters sustain workers' compensation and product liability premium pools.
Shandong Peninsula
Heavy industry and petrochemical concentration generates specialized engineering and environmental liability demand. NMPA-aligned data standards accelerate medical liability product development for hospital networks. Qingdao port operations sustain marine and logistics insurance placement volume.
China Property and Casualty Insurance Market Competitive Environment
Capability concentration sits with state-backed incumbents possessing rural network density; scale advantage sits with technology-integrated platforms targeting digital distribution. The market structures around three tiers: comprehensive national carriers, specialized online underwriters, and regional niche players. Strategic moves center on AI-driven claims automation partnerships and parametric catastrophe bond issuance through regulatory sandboxes.
Within the state-backed tier, PICC Property & Casualty Co., Ltd. and China Pacific Property Insurance Co., Ltd. occupy positions defined by branch network depth and agricultural coverage dominance. Ping An Property & Casualty Insurance anchors the technology-integrated segment through proprietary AI platforms. ZhongAn Online P&C Insurance exemplifies the specialized digital archetype with embedded e-commerce distribution.
| Leading Market Players |
|---|
| China Continent Property & Casualty Insurance |
| Sunshine Insurance Group |
| PICC Property & Casualty Co., Ltd. |
| ZhongAn Online P&C Insurance |
| China Taiping Insurance Group |
| Ping An Property & Casualty Insurance |
| China Life Property & Casualty Insurance Co. |
| Huatai Property & Casualty Insurance |
| China Pacific Property Insurance Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Actuarial talent concentration in Beijing and Shanghai directly determines where margin pools accumulate across pricing sophistication tiers, with insurers in these clusters commanding premium calibration fees that rural-network competitors cannot replicate.
Pricing Analysis
Claims service revenue tiers drive lifetime value differentiation across the market. Three-tier pricing structure across premium, standard, and economy levels stratifies based on AI-enabled claims speed and dedicated loss-adjustor assignment. Pricing pressure stems from mobile-native SME demand for instant quote-to-bind experiences that compress commission structures. Corporate buyers in Jiangsu province exhibit lowest price sensitivity, prioritizing claims service quality over premium minimization.
Supply Chain Analysis
Supplier-financing through extended payment terms from reinsurance partners sustains capital deployment flexibility for domestic underwriters. Risk capital draws from London, Bermuda, and Singapore markets as primary retrocession sources. Catastrophe modeling software and telematics data feeds constitute critical input dependencies. Single-source vulnerability concentrates in proprietary AI claims platforms. Distribution runs through county-level agent networks, direct corporate sales forces, and embedded digital partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's P&C insurance market is experiencing high-growth disruption as MIIT-mandated telematics data standards unlock usage-based product architectures that rewrite premium calibration economics.
For Market Incumbents: Harden proprietary AI claims platforms against insurtech disruption by accelerating computer vision deployment for damage estimation. Deepen vertical integration into telematics data streams through direct vehicle manufacturer partnerships. Lock in county-level agent exclusivity arrangements before digital channels erode rural distribution economics. For New Entrants and Emerging Players: Establish a beachhead in parametric catastrophe coverage through Shanghai and Shenzhen regulatory sandboxes. Target underpenetrated SME exporters in Zhejiang province manufacturing corridors with embedded e-commerce insurance partnerships. Deploy instant quote-to-bind mobile interfaces that bypass legacy agent infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward technology-integrated platforms possessing proprietary risk data assets and regulatory sandbox access. Long-term viability centers on insurers bridging AI-driven claims automation with compliant data governance. Monitor SAMR solvency modernization timelines as the signal for capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Claims Platform Deployment | Compresses loss-adjustment cycles from weeks to days while preserving SAMR-mandated human oversight for complex liability determinations. |
| Parametric Catastrophe Bond Issuance | Unlocks institutional capital through Shanghai and Shenzhen regulatory sandboxes for natural peril coverage expansion. |
| Telematics Data Partnership | Secures encrypted vehicle sensor streams compliant with MIIT cybersecurity rules for usage-based auto insurance calibration. |
| Rural Network Consolidation | Captures agricultural premium pools through county-level agent density that digital-native competitors cannot replicate. |
| Embedded Distribution Integration | Partners with fintech and e-commerce platforms to reach mobile-native SMEs abandoning traditional intermediary channels. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with underwriting executives, actuarial directors, claims operations heads, and regulatory affairs specialists at domestic insurers and reinsurance partners. Secondary validation drew from SAMR solvency disclosure filings, NMPA product registration databases, MIIT telematics standards documentation, and provincial banking and insurance regulatory bulletins. Bottom-up policy volume estimates were triangulated against top-down premium pool calculations across the analysis window.
Calibration anchored on segment-level growth trajectory modeling across coverage type, distribution channel, end-user scale, and policy architecture dimensions. CAGRs were derived from actuarial frequency-severity projections and regulatory capital requirement evolutions. Telematics penetration curves and catastrophe loss volatility assumptions fed into scenario-weighted forecast outputs throughout the projection horizon.
Sensitivities concentrate around SAMR solvency ratio adjustments, dual carbon goal implementation timelines, and telematics data standard enforcement intensity. Forecasts reflect documented assumptions regarding regulatory sandbox expansion and AI claims platform adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe EV Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Insurance Claims Services Market
Insurance
US Homeowner's Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Jewelry Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
UK Travel Insurance Market
Insurance
Solar Panel Warranty Insurance Market
Insurance
IoT Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
Liability Insurance Market