
 Europe Entertainment Insurance Market | 2026-2036
Europe Entertainment Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Entertainment Insurance Market Analytics
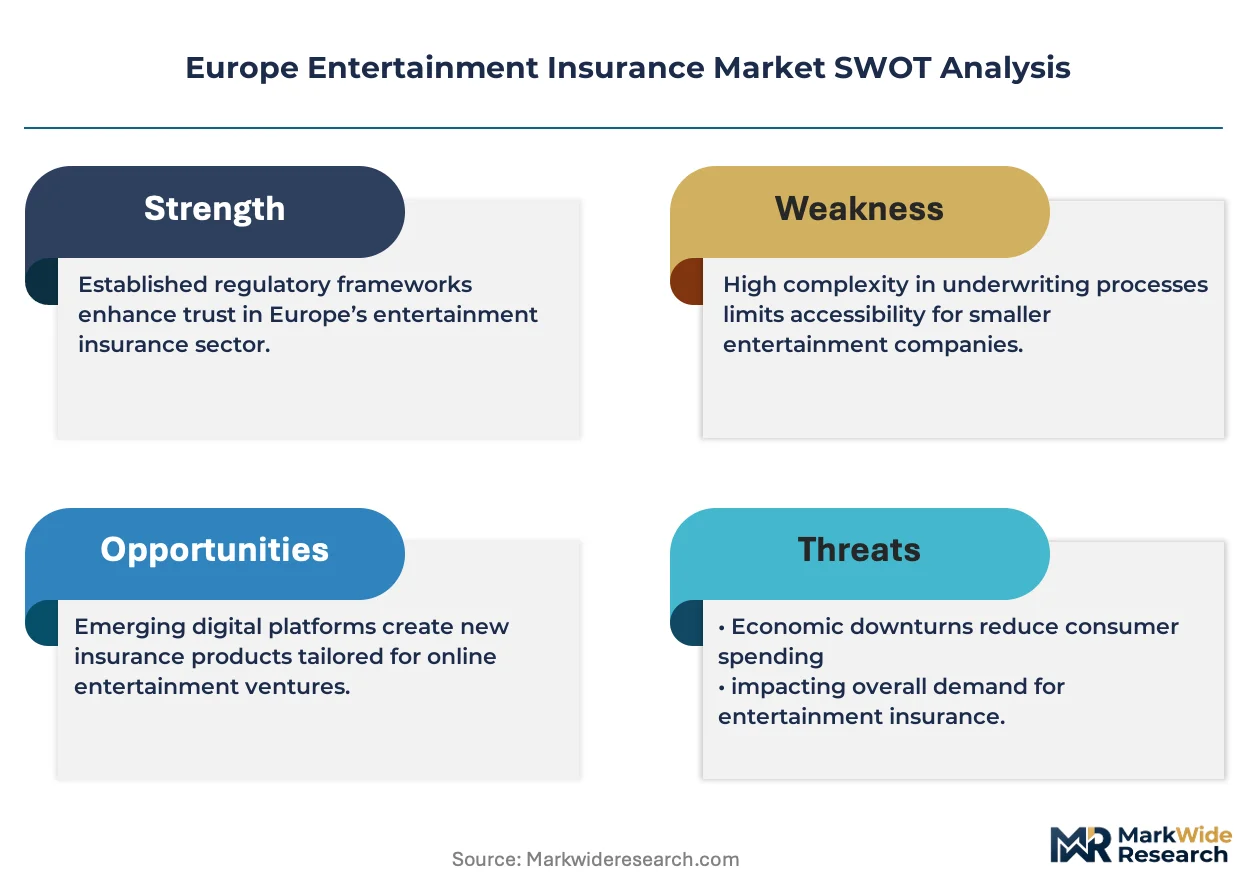
Buyer concentration among streaming platforms and major studios is restructuring how underwriters price entertainment risk across Europe. Allianz leverages its pan-European broker network to capture large-scale film production accounts. Chubb sustains competitive position through specialized media liability expertise and dedicated entertainment underwriting teams. Hiscox differentiates via flexible short-term policies tailored to independent producers and festival circuits.
Europe Entertainment Insurance encompasses risk transfer instruments designed to indemnify financial losses arising from production delays, equipment damage, event cancellation, and third-party media liability within the creative industries. Policies typically specify per-occurrence limits, aggregate caps, and deductible structures calibrated to project budgets and shooting schedules. Film Coverage dominates premium volume as episodic television and theatrical releases carry the highest per-project exposure concentrations. Event Cancellation is gaining structural importance as climate-related disruption frequency rises across outdoor festival seasons. Equipment Protection occupies a mature margin pool where commoditization pressures limit pricing power.
EMA frameworks influence pharmaceutical-adjacent productions requiring clinical accuracy representations, while GDPR shapes media liability coverage for personal data exposure in documentary and reality formats. The EU AI Act introduces emerging risk categories for synthetic media and generative content that underwriters must now evaluate. Stakeholders should monitor how national implementations of the EU Green Deal modify location-based risk assessments and force majeure definitions.
Market Dynamics
Streaming platforms are consolidating production procurement across Europe, forcing underwriters to redesign risk pricing models around multi-territory slate coverage rather than single-project policies.
Growth Catalysts
- EU Green Deal carbon-neutral mandates:Studios must adopt sustainable filming protocols, creating demand for specialized environmental liability riders and carbon offset verification coverage.
- Co-production treaty expansion:Bilateral agreements between Germany, France, and Spain multiply cross-border productions requiring unified multi-jurisdiction insurance frameworks.
- Generative AI content tools:Synthetic media production is accelerating, necessitating novel intellectual property and defamation risk products for automated content pipelines.
Market Restraints
- Reinsurance capacity contraction:Lloyd's syndicates have tightened entertainment sector appetite following pandemic-era event cancellation losses, constraining primary market capacity.
- Climate volatility in Southern Europe:Wildfire and flood frequency across Italy and Greece has rendered outdoor festival coverage unprofitable for standard market players.
- GDPR litigation exposure:Documentary and reality formats face elevated media liability costs from personal data breach claims in biometric and surveillance footage.
Strategic Opportunities
- Central and Eastern Europe production growth:Hungary, Poland, and Czech Republic offer underdeveloped entertainment insurance markets with expanding studio infrastructure and competitive location incentives.
- EU AI Act compliance products:Risk transfer instruments covering algorithmic transparency failures and synthetic media misrepresentation present first-mover advantage for specialized carriers.
- Parametric weather coverage:Index-based rainfall and temperature triggers can replace traditional cancellation policies for outdoor events facing climate uncertainty.
Industry Challenges
- Underwriter talent scarcity:Entertainment risk assessment requires hybrid skills combining production logistics knowledge with actuarial modeling, a profile rare in European labor markets.
- Legacy policy administration systems:Incumbent carriers operate on infrastructure incapable of processing real-time production schedule changes or automated claims triggers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Entertainment Insurance Market |
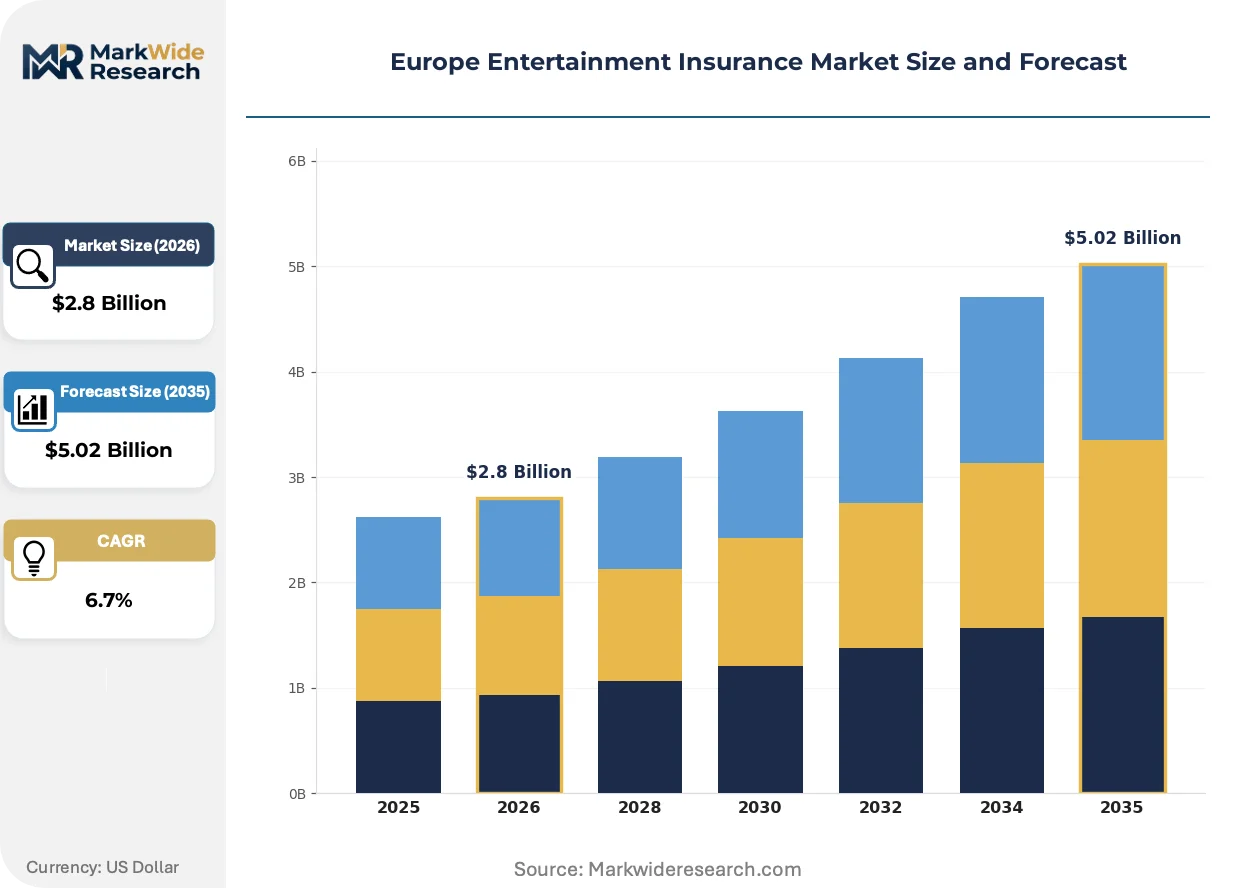
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Coverage, Event Cancellation, Media Liability, Equipment Protection End User: Film Producers, Event Organizers, Television Networks, Music Artists Policy Type: Short-Term, Long-Term, Comprehensive, Specialized Distribution Channel: Brokers, Direct Sales, Online Platforms, Industry Associations |
| Companies Covered | Allianz, Chubb, Hiscox, AXA, Lloyd's of London, Zurich Insurance Group, Assicurazioni Generali, AIG, HDI, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Entertainment Insurance Market Evolving Landscape
Digital production workflows and synthetic content generation are fragmenting traditional risk categories, compelling insurers to develop modular coverage architectures that reconfigure mid-production.
Parametric insurance structures are overtaking conventional indemnity models for event cancellation and weather disruption coverage. Festival organizers in the Netherlands and Belgium now prefer index-based payouts tied to rainfall thresholds rather than lengthy claims investigations. This compression of settlement cycles is reducing working capital requirements for promoters and shifting underwriter focus toward data sourcing rather than loss adjustment.
GDPR enforcement actions by CNIL in France and ICO in the United Kingdom are reshaping media liability coverage requirements for documentary productions handling biometric data. Insurers must now price explicit sub-limits for regulatory fines and mandatory breach notifications. Productions involving facial recognition or surveillance footage in Germany face mandatory privacy impact assessments that extend binding authority timelines.
Platform procurement teams are consolidating vendor relationships across continental production slates, replacing project-by-project insurance placement with annual master policies covering multiple territories. Netflix and Amazon Studios operations in Spain and Italy now demand pan-European coverage with consistent terms across jurisdictions. This concentration of buying power is compressing broker commissions and forcing carriers to standardize policy wordings previously customized by country.
Europe Entertainment Insurance Market Segmentation
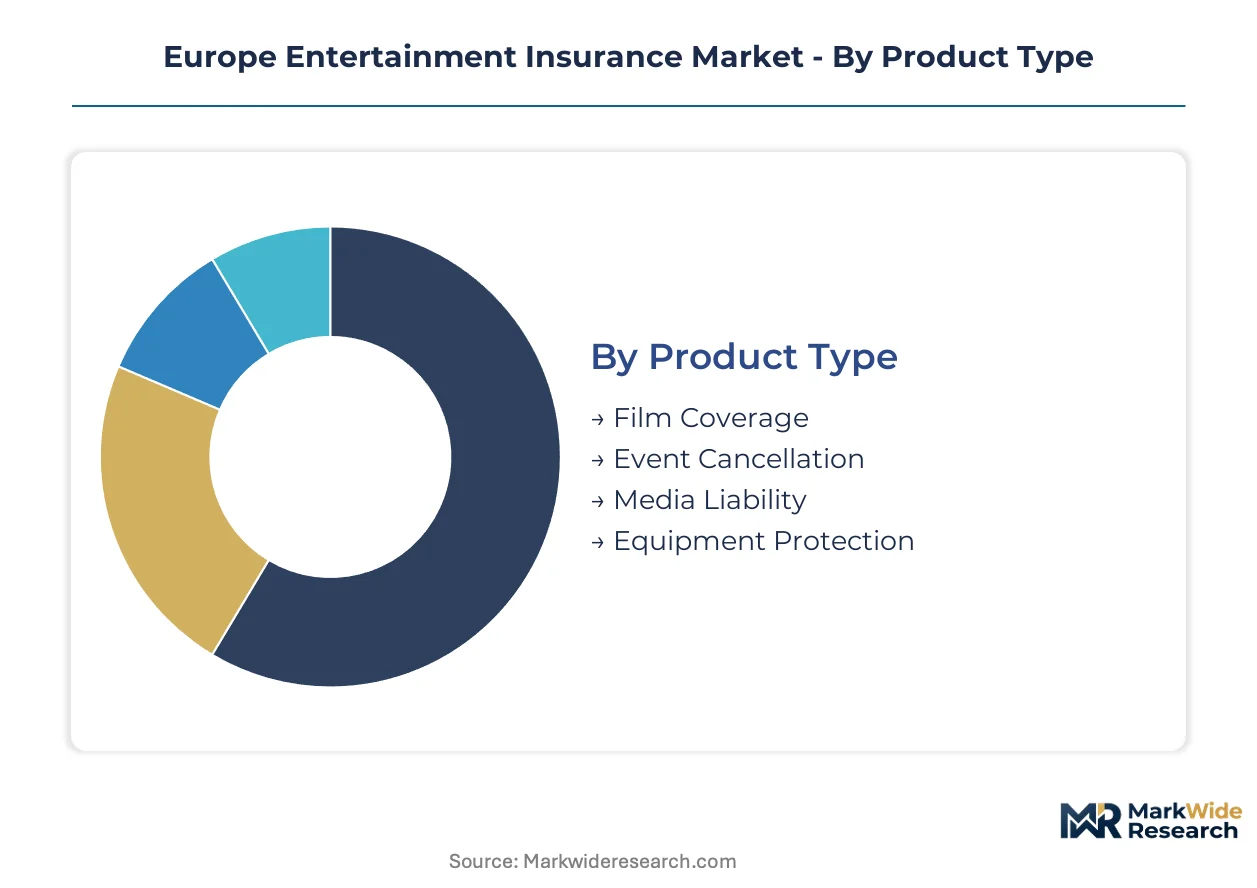
European entertainment insurance segmentation reflects how production workflows, liability exposures, and procurement channels are evolving under pressure from streaming platform consolidation and EU regulatory frameworks. Understanding these divisions enables carriers to calibrate pricing models and coverage architectures to specific risk concentrations.
Product Type:
Production technology upgrades and shifting liability exposures are driving policyholders to replace legacy single-peril coverage with modular, multi-risk products that adapt to digital workflows and synthetic content generation.
- Film Coverage:Policies indemnify production delays, cast non-appearance, and completion risks for theatrical and episodic projects. Demand concentrates in Germany and France where co-production treaties generate complex multi-territory shoots requiring unified coverage frameworks.
- Event Cancellation:Coverage transfers financial losses from weather disruption, venue unavailability, or artist withdrawal for festivals and live performances. Climate volatility across Southern Europe has pushed organizers in the Netherlands and Belgium toward parametric structures with index-based rainfall triggers.
- Media Liability:Protection against defamation, privacy invasion, and intellectual property claims arising from broadcast and streaming content. GDPR enforcement by CNIL and ICO elevates sub-limits for regulatory fines in documentary formats handling biometric data.
- Equipment Protection:Physical damage coverage for cameras, lighting, and grip equipment on location or in transit. Premiums face commoditization pressure as rental house consolidation reduces bespoke underwriting opportunities.
Film Coverage sits at the top of the volume ranking, with Event Cancellation climbing the fastest as climate-related disruption frequency reshapes outdoor festival risk transfer needs.
End User:
Customer procurement sophistication varies sharply across the cost spectrum, from streaming platforms demanding pan-European master policies to independent creators purchasing short-term coverage through digital channels.
- Film Producers:Production companies financing theatrical releases and streaming originals. Major studios in Spain and Italy now negotiate annual multi-territory programs with consistent terms across jurisdictions, compressing broker commissions.
- Event Organizers:Festival promoters and venue operators managing outdoor and indoor live entertainment. Parametric weather products are gaining preference over traditional indemnity models for rainfall and temperature disruption.
- Television Networks:Broadcasters and cable operators producing news, sports, and scripted content. GDPR compliance costs for biometric footage in reality formats are elevating media liability spend.
- Music Artists:Touring performers and their management securing cancellation and non-appearance coverage. Short-term policy demand spikes during summer festival seasons across Central and Eastern Europe.
Film Producers generate the deepest premium pools, while Event Organizers are expanding most quickly as festival infrastructure multiplies across Hungary, Poland, and Czech Republic.
Policy Type:
Duration and scope selection tracks production cycle length and risk complexity, with short-term products serving independent creators and comprehensive programs capturing platform-scale accounts.
- Short-Term:Single-project coverage spanning weeks to months for independent films and festival circuits. Hiscox and specialized carriers compete on flexible binding authority and rapid turnaround for location-specific shoots.
- Long-Term:Annual programs covering multiple productions or touring schedules. Netflix and Amazon Studios operations demand these structures with automatic territory extensions.
- Comprehensive:Bundled protection combining property, liability, and cancellation perils. Co-production treaty expansion requires these frameworks to harmonize coverage across German, French, and Spanish jurisdictions.
- Specialized:Narrowly scoped products for carbon offset verification, AI-generated content liability, or drone cinematography. EU AI Act implementation is creating first-mover opportunities for algorithmic transparency failure coverage.
Comprehensive policies command the largest premium volumes, with Specialized products gaining share fastest as synthetic media and green production protocols generate novel risk categories.
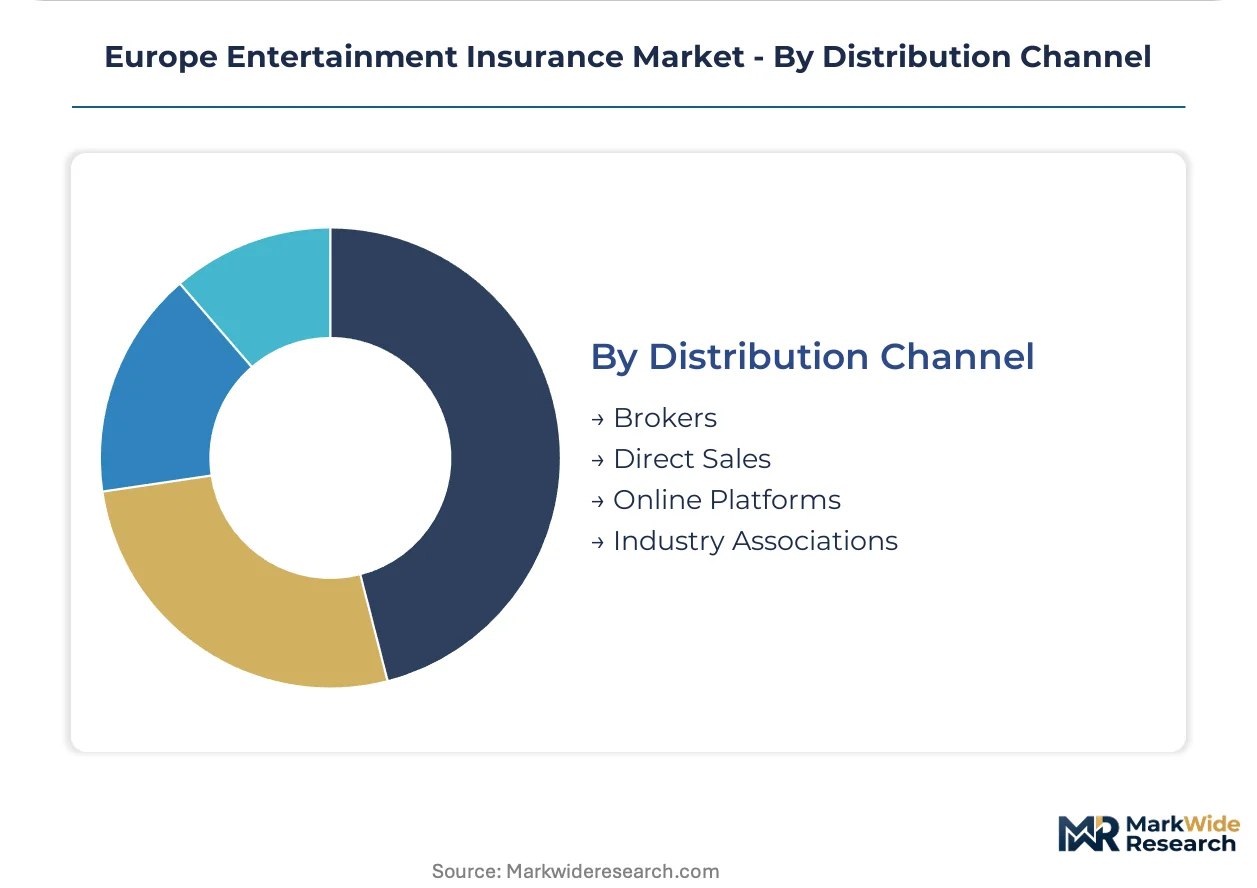
Distribution Channel:
Channel selection reflects account size, geographic scope, and buyer sophistication, with broker networks retaining dominance in large-scale production placement while digital platforms capture independent market share.
- Brokers:Intermediaries placing complex multi-territory coverage for studios and platforms. Allianz leverages its pan-European broker network to capture large-scale film production accounts.
- Direct Sales:Carrier-producer relationships bypassing intermediaries for major streaming clients. Platform procurement consolidation is compressing commission structures and standardizing policy wordings.
- Online Platforms:Digital portals enabling rapid quote-to-bind for short-term independent coverage. Legacy policy administration systems constrain real-time processing capabilities for schedule changes.
- Industry Associations:Group purchasing schemes through producer guilds and festival organizations. These channels aggregate small-account volume but limit customization for specialized risk profiles.
Brokers retain the dominant volume position, though Online Platforms are climbing fastest as independent producers seek frictionless coverage for fragmented project slates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled entertainment underwriters cluster in London, Paris, and Munich, anchoring the continent's risk assessment capacity for complex film and live event coverage.
Germany
Co-production treaties with France and Spain drive multi-territory production demand, requiring unified insurance frameworks across jurisdictions. The EU Green Deal carbon-neutral mandates reshape location risk assessments for studio shoots. Berlin and Munich host dense concentrations of underwriters specializing in completion guarantees and cast non-appearance coverage.
France
CNIL enforcement actions elevate media liability costs for documentary productions handling biometric data. The EU AI Act introduces compliance requirements for synthetic media that underwriters must price into emerging risk products. Paris anchors the largest entertainment underwriting cluster in continental Europe, with Île-de-France studios generating substantial premium volume.
United Kingdom
ICO regulatory pressure on personal data exposure in reality formats drives sub-limit restructuring for media liability policies. Lloyd's syndicates have tightened entertainment sector appetite following pandemic-era event cancellation losses. London remains the dominant placement hub for complex international productions, though capacity constraints persist.
Spain
Netflix and Amazon Studios procurement consolidation demands pan-European master policies with consistent terms across multiple territories. Climate volatility has rendered outdoor festival coverage unprofitable for standard market players in Mediterranean regions. Madrid and Barcelona production centers attract streaming platform investment, expanding demand for annual multi-territory programs.
Netherlands
Festival organizers prefer parametric weather coverage with index-based rainfall triggers over traditional indemnity models. The compression of settlement cycles reduces working capital requirements for promoters and shifts underwriter focus toward data sourcing. Amsterdam and Rotterdam host emerging insurtech platforms targeting frictionless short-term coverage for independent producers.
Europe Entertainment Insurance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Pan-European carriers leverage broker networks for large-scale studio accounts, while niche underwriters capture independent producers through flexible binding authority. Three archetypes dominate: diversified financial groups with entertainment divisions, Lloyd's syndicates specializing in media liability, and boutique carriers serving festival circuits and short-term productions. Competitive moves center on geographic expansion into Central and Eastern Europe and portfolio diversification into AI-generated content liability products.
Among diversified European carriers, Allianz exemplifies the pan-European network archetype, while Chubb occupies a position emphasizing specialized media liability expertise. Hiscox represents the boutique specialist tier focused on flexible short-term policies. These three anchors illustrate how scale, specialization, and agility segment competitive positioning across streaming platform procurement and independent producer channels.
| Leading Market Players |
|---|
| Allianz |
| Chubb |
| Hiscox |
| AXA |
| Lloyd's of London |
| Zurich Insurance Group |
| Assicurazioni Generali |
| AIG |
| HDI |
| Others |
Value Network & Pricing Analysis
Streaming platform procurement consolidation across Germany, France, and Spain demands unified multi-territory coverage with consistent terms, forcing carriers to standardize policy wordings and compress broker commissions while repositioning underwriting talent toward pan-European account management.
Pricing Analysis
Capacity additions in Central and Eastern Europe are reshaping price floors for production coverage as Hungary, Poland, and Czech Republic expand studio infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates streaming platform master policies from independent producer short-term coverage and festival circuit parametric products. Cost compression in standard market tiers is intensifying because Lloyd's syndicates have tightened entertainment sector appetite following pandemic-era losses. Film producers exhibit the highest price sensitivity due to budget-constrained completion guarantee requirements, while streaming platforms prioritize coverage consistency over premium minimization.
Supply Chain Analysis
EU Green Deal domestic-content mandates for carbon-neutral filming protocols are reshaping sourcing of location services, equipment rental houses, and post-production facilities toward verified sustainable vendors. Underwriting capacity concentrates in the United Kingdom, Germany, and France, with risk assessment expertise drawing from London Lloyd's syndicates, Munich completion guarantee specialists, and Paris media liability clusters. Supply chain vulnerability rests on single-source dependency for parametric weather data providers serving Netherlands and Belgium festival markets. Distribution runs through pan-European broker networks for studio accounts, direct carrier relationships for streaming platforms, and digital portals for independent producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Western European saturated markets and Central European expanding production infrastructure offers cost advantages in underwriting talent acquisition and regulatory compliance burden.
For Market Incumbents: Deepen vertical integration into parametric data sourcing capabilities to capture festival organizer demand in climate-vulnerable Southern Europe. Incumbent carriers face displacement risk from insurtech platforms offering real-time policy adjustments; defend through captive supply of proprietary production risk databases and automated claims triggers. For New Entrants and Emerging Players: Enter via specialized AI-generated content liability products addressing EU AI Act compliance requirements in France and Germany synthetic media productions. Central and Eastern European production growth represents the most penetrable geography, with Hungary studio infrastructure outpacing local underwriting capacity. Target digital-first distribution for independent producers seeking frictionless short-term coverage. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique carriers possessing flexible binding authority and festival circuit relationships that diversified conglomerates cannot replicate. Five-to-ten year viability favors specialists with modular coverage architectures adaptable to synthetic content workflows. Watch for inflection signals in national implementations of EU Green Deal carbon offset verification mandates that would elevate environmental liability rider demand.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Weather Product Development | Index-based rainfall triggers replace traditional cancellation policies for Netherlands and Belgium festival organizers facing climate volatility. |
| AI Act Compliance Coverage Launch | Algorithmic transparency failure products capture first-mover advantage in France and Germany synthetic media production markets. |
| Central European Geographic Expansion | Hungary, Poland, and Czech Republic studio infrastructure growth outpaces local underwriting capacity, creating white-space opportunity. |
| Carbon Offset Verification Rider Integration | EU Green Deal mandates elevate environmental liability coverage as mandatory component of studio location risk assessment. |
| Digital Platform Partnership | Real-time quote-to-bind capabilities address independent producer demand for schedule-flexible short-term production coverage. |
Research Methodology
Multiple input streams — primary interviews with underwriting directors, production risk managers, and streaming platform procurement leads; secondary validation through Lloyd's market filings, EIOPA regulatory disclosures, and European Audiovisual Observatory production data; plus customs records on equipment import flows — were reconciled through bottom-up and top-down triangulation.
Historical premium volume trajectories were cross-referenced against panel input from entertainment insurance specialists to construct analytical frameworks across product type, end user, policy duration, and distribution channel dimensions. CAGRs were derived from regression analysis of production slate expansion and regulatory cost imposition trends. Forecast inputs incorporated streaming platform content budget disclosures and EU AI Act implementation timelines.
Inputs from Lloyd's syndicate capacity reports and national insurance regulator filings were available through the study window; gaps in real-time production schedule change data introduce uncertainty bands around short-term policy demand projections. Forecasts reflect assumptions on regulatory enforcement intensity and climate disruption frequency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
UK Commercial Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Family Floater Health Insurance Market
Insurance
Trade Credit Insurance Market
Insurance
Embedded Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Canada House Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
United States Bancassurance Market
Insurance
Internet of Things Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
North America Family Floater Health Insurance Market